
 Forage Inoculants Market | 2026-2036
Forage Inoculants Market Size, Share, and Industry Trends Forecast 2026-2036
Forage Inoculants Market Analysis
The EU Green Deal is recalibrating procurement criteria across European dairy cooperatives, redirecting volume toward microbial silage additives that demonstrably cut enteric methane and improve feed conversion ratios. Cargill leverages its integrated animal nutrition platform to bundle inoculants with forage testing services across North American dairy belts. Lallemand sustains technology leadership through proprietary strain banks focused on Lactobacillus buchneri for aerobic stability. Chr. Hansen specializes in high-concentration freeze-dried formulations that extend shelf life without cold-chain dependency.
Forage inoculants are live microbial preparations, typically containing lactic acid bacteria at concentrations exceeding 100,000 colony-forming units per gram, applied to freshly cut forage to direct fermentation pH below 4.5 and inhibit spoilage organisms. Their primary purpose is to preserve nutritional value in silage and hay systems while reducing reliance on synthetic acids. Liquid formulations dominate volume due to ease of tank-mixing and uniform application across large-scale silage operations, though granular and powder forms are gaining traction in smaller livestock farms with limited mechanization. Multi-strain and custom blend formulations command premium positioning by addressing crop-specific fermentation challenges and variable dry matter conditions.
Regulatory frameworks including the EPA's biopesticide registration requirements, the EU's Feed Additives Regulation under EFSA oversight, and Brazil's MAPA registry for biological products collectively shape market access timelines and efficacy validation standards. These bodies mandate strain-level identification, stability testing, and residue documentation that filter out unsubstantiated claims and consolidate share among credentialed suppliers. Stakeholders must monitor evolving strain patent landscapes and regional organic certification rules to anticipate which formulation categories will retain pricing power versus commoditize.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is recalibrating procurement criteria across European dairy cooperatives, redirecting volume toward microbial silage additives that demonstrably cut enteric methane and improve feed conversion ratios.
Growth Catalysts
- EU Green Deal mandates:The Farm to Fork strategy tightens sustainability benchmarks for livestock feed additives, pushing demand toward certified biological solutions that reduce synthetic acid dependence.
- Dairy farm consolidation:Large-scale commercial operations in Brazil and Argentina are converting from chemical preservatives to microbial inoculant systems to improve silage fermentation efficiency.
- Strain optimization:Advances in Lactobacillus buchneri cultivation are delivering superior aerobic stability in high-moisture forage, cutting dry matter losses below traditional benchmarks.
Market Restraints
- Strain patent thickets:Proprietary Lactobacillus and Pediococcus strain banks controlled by established suppliers create licensing friction for new entrants seeking comparable efficacy claims.
- Cold-chain dependency:High-concentration freeze-dried formulations require controlled storage infrastructure that remains uneven across rural feed distribution networks in Argentina and Paraguay.
- Synthetic acid substitution:Propionic acid and formic acid preservatives retain cost advantages in commodity grain silage segments where fermentation control demands are less stringent.
Strategic Opportunities
- Organic certification expansion:EU organic livestock standards under EFSA oversight are mandating biological preservation methods, opening premium positioning for certified inoculant suppliers.
- Custom blend services:Crop-specific multi-strain formulations addressing variable dry matter conditions in alfalfa versus corn silage command pricing premiums from precision dairy operations.
- Liquid-to-granular pivot:Smaller livestock farms with limited mechanization are adopting powder and granular forms, creating channel diversification beyond tank-mixing infrastructure.
Industry Challenges
- EFSA registration timelines:Strain-level identification, stability testing, and residue documentation requirements under EU Feed Additives Regulation extend market access cycles beyond product development schedules.
- Application uniformity:Achieving consistent colony-forming unit distribution across irregular forage windrows demands precision applicator calibration that exceeds operator training levels on mid-scale farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forage Inoculants Market |
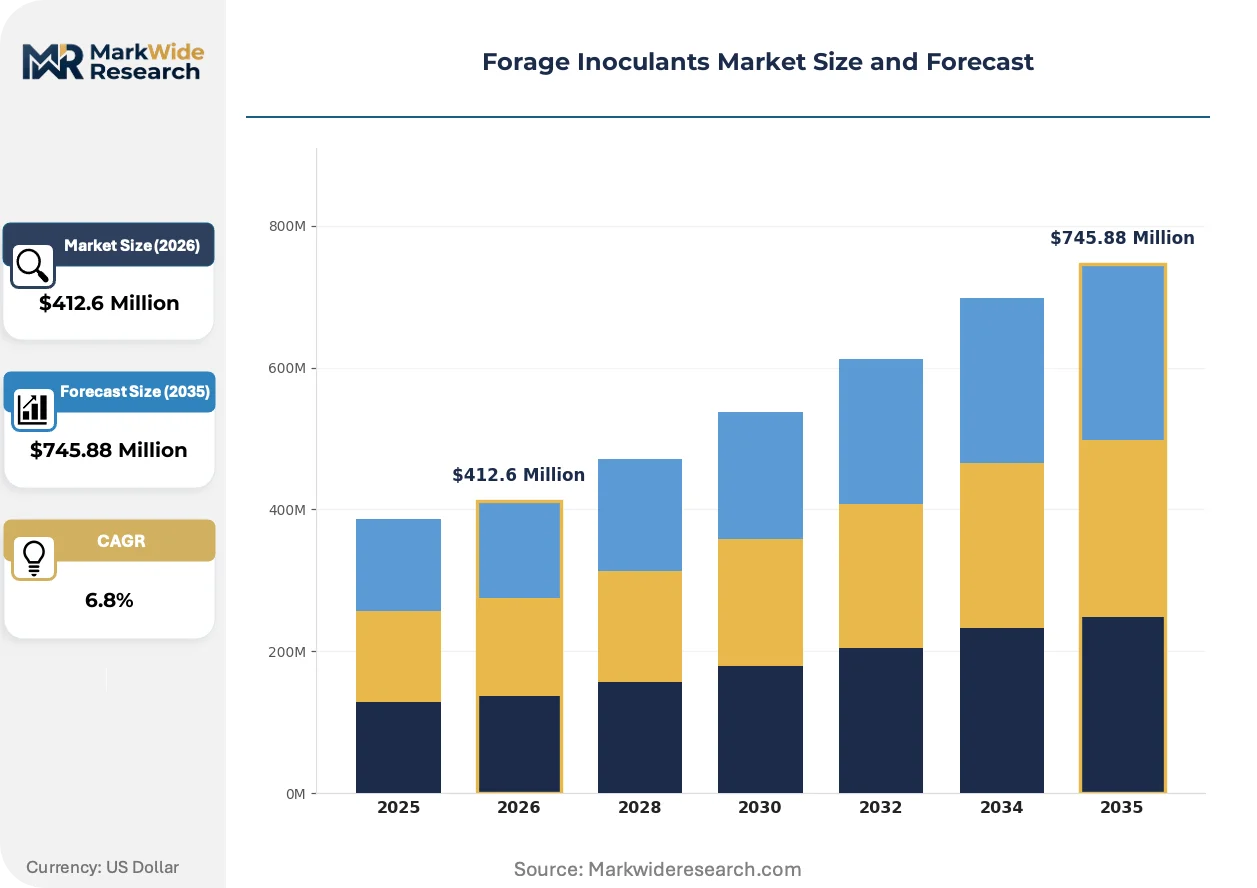
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powder, Pellet Formulation: Single Strain, Multi Strain, Custom Blend, Organic Application: Silage, Hay, Green Chop, Corn End User: Dairy Farms, Livestock Farms, Commercial Feedlots, Organic Farmers |
| Companies Covered | Cargill, ADM, Corteva Agriscience, Lallemand, Chr. Hansen, Kemin Industries, DuPont, Volac International, Agri-King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forage Inoculants Market Emerging Trajectories
Formulation science and regulatory compliance frameworks are converging to reshape competitive positioning in microbial silage preservation, with shelf-life extension and strain specificity emerging as primary battlegrounds.
Multi-strain inoculant technology is consolidating performance benchmarks across high-value dairy segments. These preparations combine Lactobacillus plantarum, L. buchneri, and Enterococcus faecium to address sequential fermentation phases. Large-scale operations in Wisconsin and the Netherlands are adopting these systems at accelerating rates. The technology is consolidating supplier margins by compressing single-strain commoditization while rewarding integrated strain-bank capabilities.
REACH and EU F-Gas Regulation compliance requirements are elevating documentation burdens for biological feed additive suppliers. Strain characterization, environmental fate studies, and residue monitoring now accompany every registration dossier. North American exporters targeting European dairy cooperatives face extended validation timelines. These suppliers are responding by front-loading EFSA pre-submission consultations and building dedicated regulatory affairs functions.
Buyer consolidation among dairy cooperatives is compressing supplier negotiation leverage and unbundling traditional service packages. Large procurement consortia in Denmark and California are separating forage testing from inoculant supply, demanding standalone pricing transparency. Channel intermediaries face margin compression as direct manufacturer relationships proliferate. This pattern is most visible in the Upper Midwest and Northern Europe where cooperative density highest.
Forage Inoculants Market Segmentation
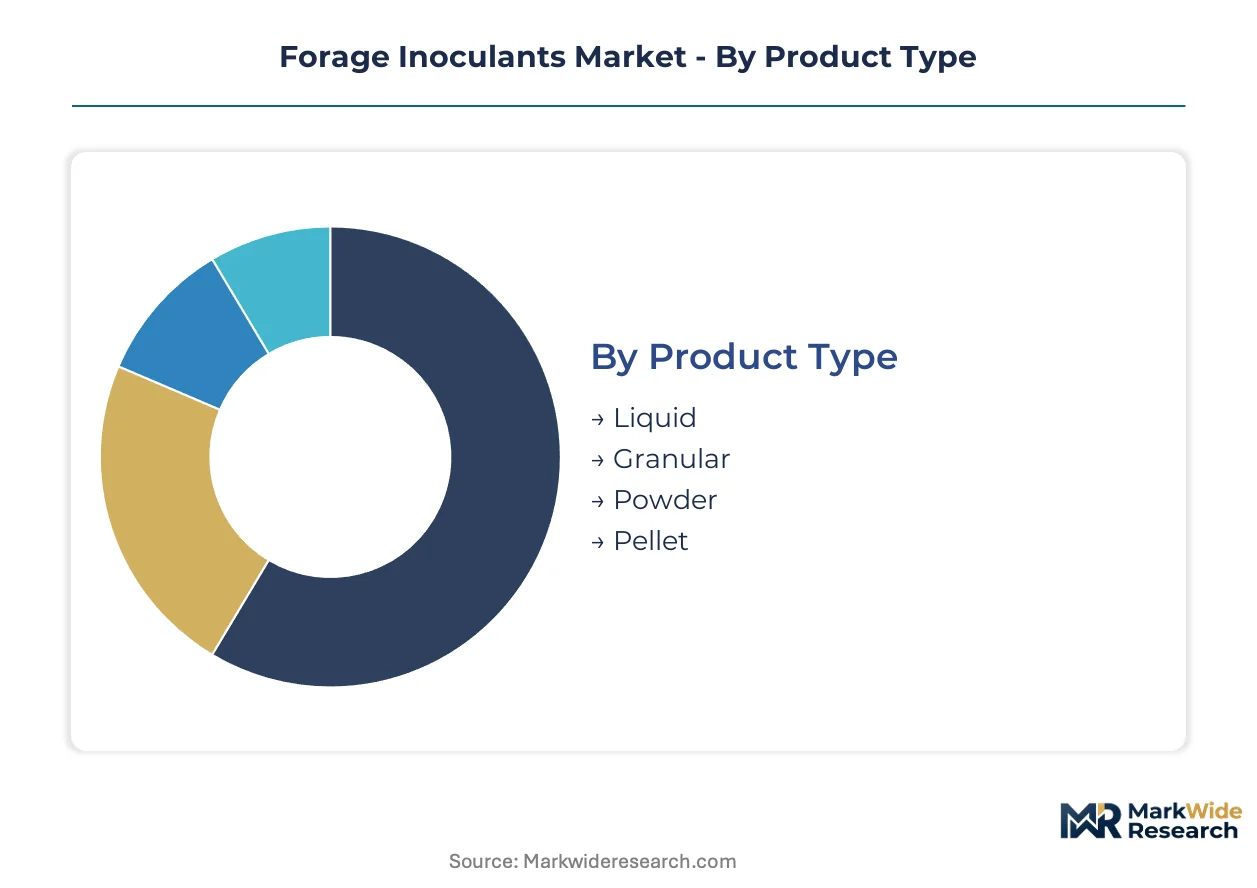
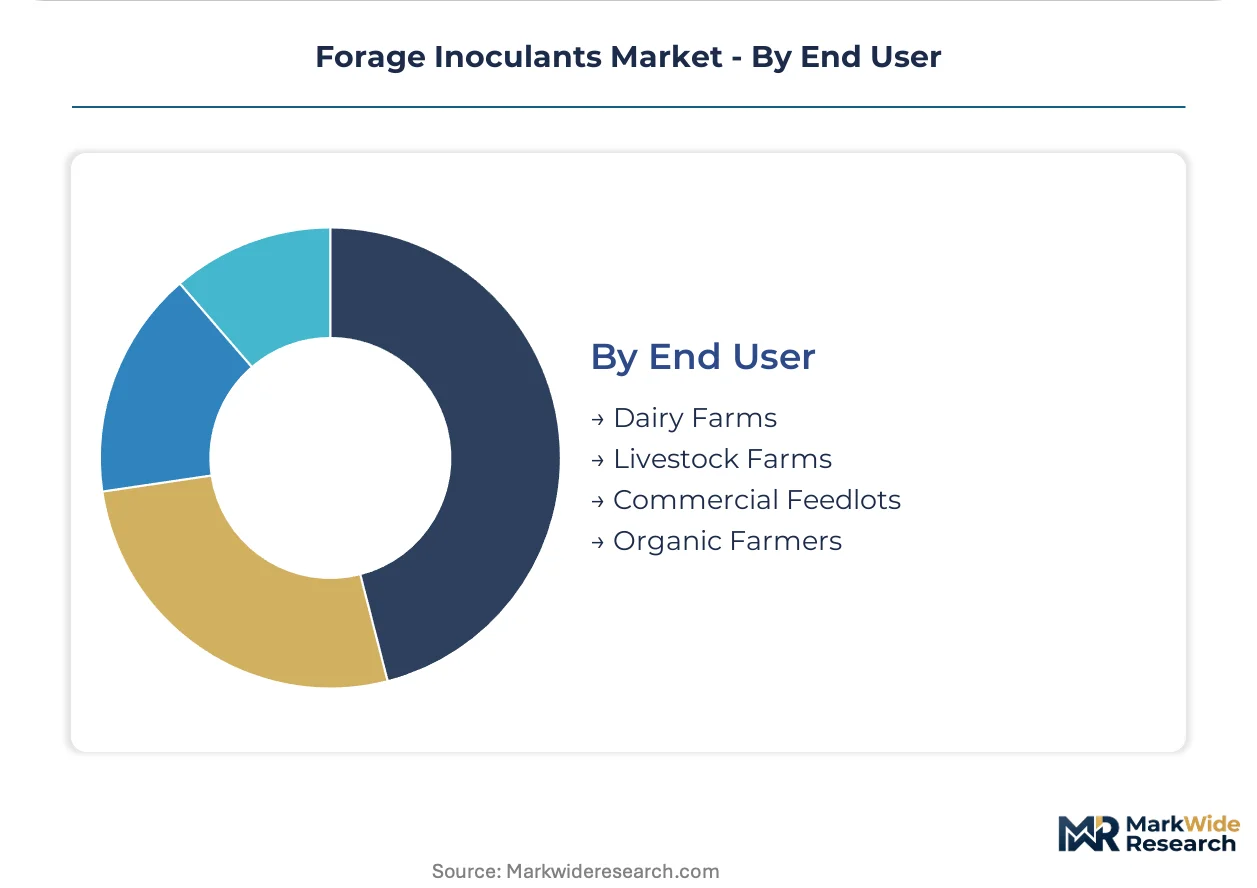
Forage inoculant procurement patterns diverge sharply by operation scale and mechanization level, with tank-mixing infrastructure dictating formulation choices while regulatory certification filters supplier eligibility. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Buyers in this category separate by mechanization intensity and batch size, not by crop type or geography.
- Liquid:Tank-mixable suspensions containing 100,000+ colony-forming units per gram enable uniform spray application across large-scale silage windrows. Demand concentrates in Wisconsin dairy belts and California Central Valley operations where 1,000+ head dairies maintain dedicated applicator trucks and calibrated mixing stations.
- Granular:Free-flowing carriers impregnated with freeze-dried cultures suit smaller livestock farms lacking liquid handling infrastructure. Adoption is climbing fastest in Paraguay and Argentina's Mato Grosso region where mid-scale feedlots are converting from propionic acid preservatives.
- Powder:Dry concentrates packaged in moisture-barrier sachets for manual distribution; preferred by organic-certified operations in Denmark and the Netherlands with limited capital equipment.
- Pellet:Compressed formulations with extended ambient stability; niche positioning for remote grazing operations in Australia's Queensland where cold-chain logistics prove unreliable.
Volume sits with liquid; growth tilts toward granular.
Formulation:
Price-to-performance expectations stratify this category, with certification premiums widening spreads between commodity and validated offerings.
- Multi Strain:Combinations of Lactobacillus plantarum, L. buchneri, and Enterococcus faecium address sequential fermentation phases from initial acidification through aerobic stability. Premium positioning in Dutch and Danish cooperative procurement where EFSA-registered strains command validated efficacy documentation.
- Single Strain:Isolated Lactobacillus plantarum preparations for cost-sensitive commodity silage; dominant in Brazilian grain-fed beef operations where fermentation control demands are less stringent than dairy applications.
- Custom Blend:Crop-specific formulations calibrated to alfalfa versus corn silage dry matter profiles; expanding most quickly in precision dairy operations across California's San Joaquin Valley.
- Organic:Strain selections pre-screened against EU organic livestock standards and USDA National Organic Program inputs lists; mandatory for certified operations in Germany's Bavaria and Austria's dairy cooperatives.
Revenue concentrates in multi-strain; certification requirements are accelerating organic formulation share gains.
Application:
Moisture content at harvest and anaerobic sealing feasibility determine technical requirements across crop types.
- Silage:High-moisture forage preserved in sealed bunkers or bags; the dominant application channel where L. buchneri specifically targets aerobic stability during feed-out. Concentrated demand in North American and European dairy belts.
- Hay:Dried forage with limited fermentation window; inoculant value proposition centers on mold inhibition rather than pH reduction, with uptake concentrated in Australia's export hay industry.
- Green Chop:Fresh-cut forage fed immediately with minimal storage; microbial additives focus on palatability retention in tropical dairy systems.
- Corn:High-sugar substrate requiring rapid acidification to prevent clostridial spoilage; specialized formulations with accelerated Lactobacillus activity dominate Midwest US and Chinese corn belts.
Volume dominance remains with silage; corn-specific formulations are climbing the fastest on dairy nutrition intensification.
End User:
Procurement sophistication and regulatory exposure vary dramatically by operation type and scale.
- Commercial Feedlots:Large-scale operations with dedicated nutritionists and forage testing protocols; bundled service relationships with integrated animal nutrition platforms.
- Dairy Farms:Milk quality premiums and enteric methane accounting drive biological additive adoption; EFSA and EPA registration requirements filter supplier pools.
- Livestock Farms:Diverse species operations with fragmented procurement; price-sensitive segment where synthetic acid substitution economics remain contested.
- Organic Farmers:Certification-constrained sourcing with mandatory biological preservation methods; premium pricing tolerance for validated organic-compliant strains.
Procurement volume aggregates at commercial feedlots; organic farmer segment offers steepest expansion trajectory on regulatory mandate tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's dairy belt anchors commercial inoculant consumption through its concentration of 1,000+ head operations running dedicated applicator infrastructure. The United States, Germany, Brazil, Netherlands, and Australia represent the five national markets where procurement patterns diverge most sharply by scale and regulatory exposure.
United States
Midwest corn silage operations and California Central Valley dairies drive volume through bundled nutrition service relationships. EPA biopesticide registration requirements filter supplier pools to credentialed strain banks. Wisconsin and Iowa dairy cooperatives are converting liquid application systems to multi-strain formulations at accelerating rates.
Germany
Bavarian organic dairy cooperatives mandate biological preservation methods under EU organic livestock standards. EFSA strain-level identification and stability testing extend registration timelines beyond product development cycles. Northern German feed manufacturers are front-loading pre-submission consultations to accelerate market access.
Brazil
Mato Grosso feedlots and São Paulo state dairy clusters are displacing chemical preservatives with microbial systems at commercial scale. MAPA registry for biological products shapes efficacy validation standards. Large-scale operations in Brazil's central-west region maintain dedicated applicator trucks for liquid tank-mixing.
Netherlands
Dutch dairy cooperatives redirect procurement toward EFSA-registered strains demonstrating enteric methane reduction. EU Green Deal Farm to Fork strategy tightens sustainability benchmarks for feed additives. Friesland and Gelderland dairy belts are unbundling forage testing from inoculant supply, demanding standalone pricing transparency.
Australia
Queensland grazing operations and New South Wales export hay producers adopt pellet formulations where cold-chain logistics prove unreliable. TGA oversight of veterinary biologicals shapes import documentation requirements. Victoria's dairy regions are testing granular forms for mid-scale farms with limited mechanization.
Forage Inoculants Market Vendor Landscape
Premium-margin players sit above commodity-margin players across strain-bank depth and regulatory dossier completeness. The market structures around three tiers: integrated animal nutrition platforms with bundled service capabilities, specialized microbial suppliers with proprietary fermentation technology, and regional distributors serving price-sensitive livestock operations. Consolidation pressures concentrate among mid-scale suppliers lacking dedicated regulatory affairs functions. Licensing friction around proprietary Lactobacillus and Pediococcus strains is compressing new entrant viability.
Within the integrated nutrition tier, Cargill and ADM occupy positions spanning North American dairy belts with bundled forage testing and inoculant supply relationships. Lallemand anchors the specialized microbial segment through its Canadian-based fermentation expertise. These three exemplify divergent strategic postures: nutrition platforms leverage service integration while microbial specialists concentrate on strain-bank differentiation and freeze-dried formulation stability.
| Leading Market Players |
|---|
| Cargill |
| ADM |
| Corteva Agriscience |
| Lallemand |
| Chr. Hansen |
| Kemin Industries |
| DuPont |
| Volac International |
| Agri-King |
| Others |
Supply Flow & Price Mechanics
Fermentation scientists concentrated in Canada's Quebec corridor and France's Brittany region command wage premiums that propagate through multi-strain formulation costs, widening spreads between validated premium tiers and commodity single-strain alternatives. Labor-cost differentials between these specialized biotechnology clusters and generic chemical preservative manufacturing zones in Brazil's industrial southeast shape procurement trade-offs for mid-scale dairy operations.
Pricing Analysis
Yield-guarantee contracts tied to dry matter recovery rates anchor value-based pricing for EFSA-registered multi-strain formulations. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified custom blends from MAPA-registered commodity preparations from unlicensed regional alternatives. Price differentiation hinges on strain-bank documentation depth and cold-chain stability certification. Cost compression in the economy tier intensifies because Brazilian feedlots are converting from propionic acid without upgrading to validated microbial systems. Organic-certified dairy cooperatives in Northern Europe exhibit lowest price sensitivity; grain-fed beef operations in South America's central-west region demonstrate highest.
Supply Chain Analysis
EFSA strain-level identification and EPA biopesticide registration requirements gate supplier eligibility, filtering distribution networks to credentialed manufacturers with complete regulatory dossiers. Manufacturing concentrates in Canada, France, and Denmark where proprietary Lactobacillus cultivation infrastructure is anchored. Raw material flows draw from specialized freeze-drying equipment, pharmaceutical-grade culture media, and moisture-barrier packaging substrates. Single-source vulnerability runs through European freeze-drying capacity for high-concentration formulations. Distribution runs through integrated animal nutrition platforms in North America and specialized microbial distributors in South America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: EFSA's Feed Additives Regulation creates a barrier-to-entry moat that consolidates margin pools among dossier-complete incumbents while filtering out unsubstantiated strain claims.
For Market Incumbents: Anticipate strain patent expirations and front-load R&D investment into next-generation Pediococcus and Lactobacillus buchneri isolates with enhanced aerobic stability profiles. Defensive consolidation through captive supply of freeze-drying capacity in Quebec and Brittany clusters will lock in formulation cost advantages against emerging Brazilian challengers. For New Entrants and Emerging Players: Direct-to-feedlot digital platforms bypassing traditional cooperative procurement channels offer the most penetrable route into Brazil's Mato Grosso region where MAPA registration requirements remain less stringent than EFSA timelines. White-space targets include granular formulation adoption among Paraguayan mid-scale operations and organic-certified custom blends for German Bavarian cooperatives. For Investors and Strategic Acquirers: Re-rating potential sits with specialized microbial suppliers possessing complete EFSA dossiers given EU Green Deal methane-reduction mandates tightening procurement criteria. Long-term viability favors strain-bank depth over service integration. The signal to watch is unbundling of forage testing from inoculant supply in Dutch and Danish cooperative tenders.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Pre-Submission Consultation | Front-loading regulatory engagement compresses market access timelines for novel strains. |
| Strain Bank Expansion | Proprietary Lactobacillus buchneri isolates defend margin position against commoditization. |
| Freeze-Drying Capacity Addition | Captive production in Quebec and Brittany clusters reduces cold-chain dependency risks. |
| Direct Feedlot Platform Launch | Bypassing cooperative procurement intermediaries captures Brazilian Mato Grosso volume. |
| Organic Certification Pathway | EU organic livestock standards under EFSA oversight open premium positioning. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fermentation scientists, dairy cooperative procurement managers, regulatory affairs directors at biological product firms, and MAPA registration consultants provided ground-truth validation. Secondary sources included EFSA feed additive registry databases, EPA biopesticide registration records, Brazilian MAPA biological product listings, and EU organic certification body directories. Bottom-up strain-level demand modeling triangulated against top-down dairy herd size projections across the analysis window.
Granularity-level modeling operated at the intersection of formulation type, mechanization intensity, and regulatory certification tier. Segmentation dimensions included product form, strain composition, application crop, and end-user operation scale. CAGRs were derived through log-linear trend fitting across annual volume estimates. Industry-specific forecast inputs incorporated dairy herd consolidation rates and EU Green Deal implementation trajectories.
Inputs from EFSA registration databases and MAPA biological product registries were available through the study window; gaps in real-time dairy cooperative procurement transaction data introduce uncertainty bands around price elasticity estimates. Forecasts reflect documented assumptions regarding strain stability and regulatory timeline continuity. A model refresh is warranted upon material change in EU Farm to Fork strategy implementation pace or Brazilian MAPA registry procedural reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
North America Silage Inoculant Market