
 Europe Agricultural Microbials Market | 2026-2036
Europe Agricultural Microbials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Microbials Market Foresight
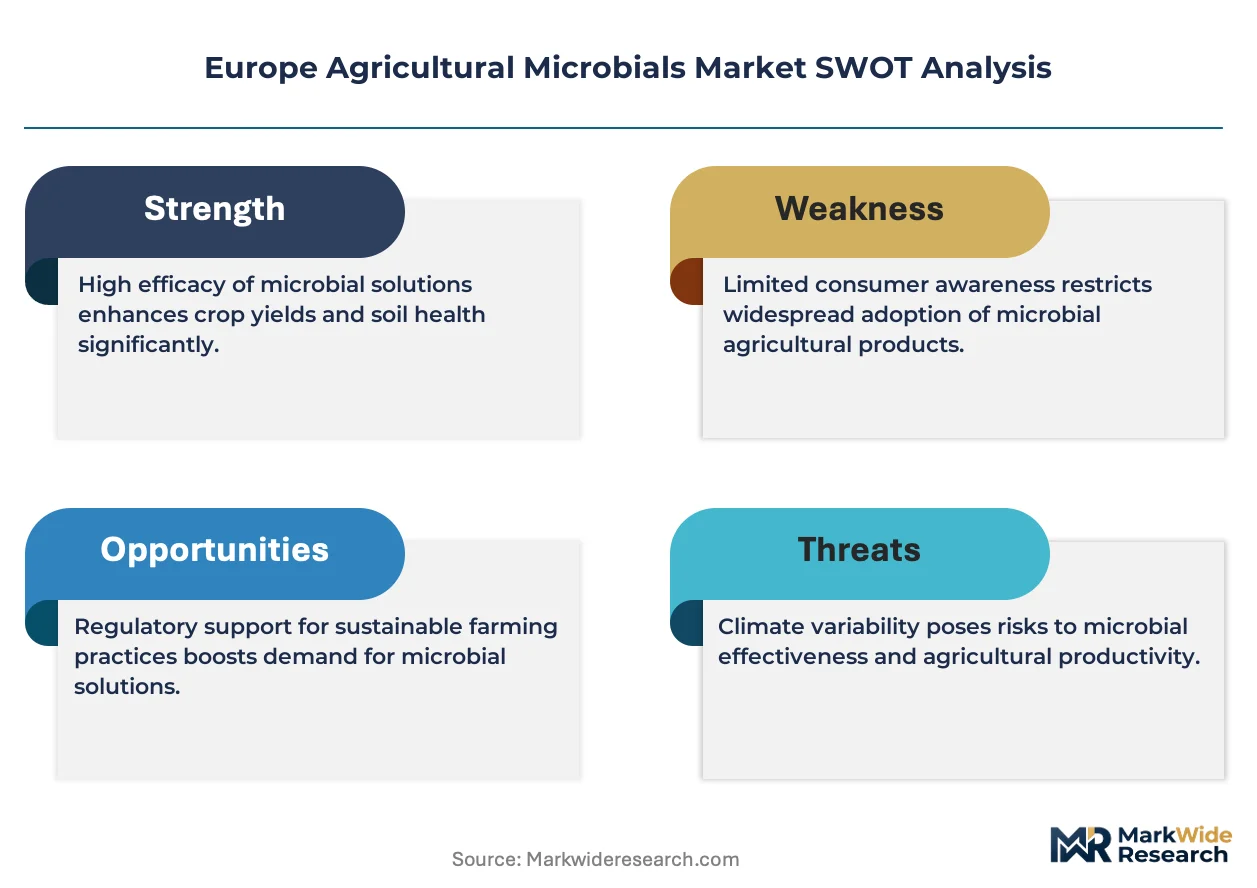
The EU Green Deal is rebalancing input procurement across European agriculture by embedding biological targets into subsidy frameworks. BASF SE leverages its fermentation capacity in Ludwigshafen to sustain a dominant position in bacterial inoculants. Bayer AG anchors its microbial pipeline through integrated seed treatment platforms that compete with conventional chemistry portfolios. Syngenta Group differentiates via biocontrol strains positioned for vine and vegetable crops across Mediterranean supply chains.
Europe agricultural microbials comprise live or dormant microorganisms—bacteria, fungi, protozoa, and viruses—formulated at colony-forming unit densities between 10^6 and 10^9 CFU per gram, applied to seeds, soil, or foliage to enhance nutrient cycling, suppress pathogens, or induce systemic resistance in host plants. Bacteria-based formulations lead current volume due to established Bacillus and Pseudomonas strain libraries, while fungi segments expand fastest as Trichoderma and Beauveria products displace soil fumigants in protected horticulture. Application through seed treatment commands premium positioning because of precise dosing and early plant establishment benefits, whereas soil health applications occupy broader acreage with lower per-hectare margins.
The European Commission's Farm to Fork Strategy and REACH frameworks shape product registration pathways, with EFSA conducting novel food and feed risk assessments that determine strain authorization timelines. Member state regulators in France and Germany enforce additional national biocontrol standards that fragment market access procedures. Stakeholders must monitor evolving EU MDR and F-Gas Regulation spillovers that could reclassify microbial manufacturing inputs or restrict formulation solvents.
Market Dynamics
The EU Green Deal's binding pesticide reduction targets are restructuring input procurement across European agriculture, embedding biological substitution mandates into Common Agricultural Policy subsidy frameworks that now require documented microbial input adoption for full payment eligibility.
Growth Catalysts
- Farm to Fork Strategy:The European Commission's pesticide reduction roadmap mandates 50% synthetic chemical cuts by 2030, forcing cooperative procurement shifts toward bacterial inoculants and fungal biocontrols in France and Germany.
- Protected horticulture expansion:Spanish and Italian greenhouse operators are scaling Trichoderma-based soil treatments to replace methyl bromide fumigants ahead of F-Gas Regulation phase-out deadlines.
- Seed treatment integration:Precision application technologies enable micro-encapsulated Bacillus formulations at planting, capturing farmer preference for early-season plant establishment protocols.
Market Restraints
- Strain registration timelines:EFSA novel food and feed risk assessments impose 18-36 month authorization windows that freeze product commercialization and tie up R&D capital.
- Fermentation capacity concentration:Contract manufacturing for high-density bacterial cultures clusters in Germany's Rhine corridor, creating single-source vulnerability for formulations exceeding 10^9 CFU per gram.
- Conventional chemistry residual efficacy:Neonicotinoid seed treatments retain cost-per-hectare advantages in commodity grains, delaying microbial substitution in Polish and Romanian broadacre farming.
Strategic Opportunities
- Baltic and Eastern European penetration:Polish and Romanian farming cooperatives currently underindex on biological inputs relative to Western European adoption rates, presenting first-mover expansion potential.
- Vineyard biocontrol specialization:Downy mildew pressure in Bordeaux and Tuscany drives demand for Reynoutria sachalinensis and Bacillus subtilis combinations tailored to organic wine certification protocols.
- CSRD disclosure alignment:Corporate sustainability reporting mandates create procurement incentives for documented microbial input adoption as Scope 3 emissions reduction instruments in food processor supply chains.
Industry Challenges
- Formulation stability expertise:Shelf-life engineering for temperature-sensitive fungal spores requires specialized biochemistry talent scarce outside BASF's Ludwigshafen and Bayer's Monheim research clusters.
- Member state regulatory fragmentation:French ANSM and German BfR impose divergent national biocontrol standards atop EFSA baselines, multiplying compliance documentation burdens for cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Microbials Market |
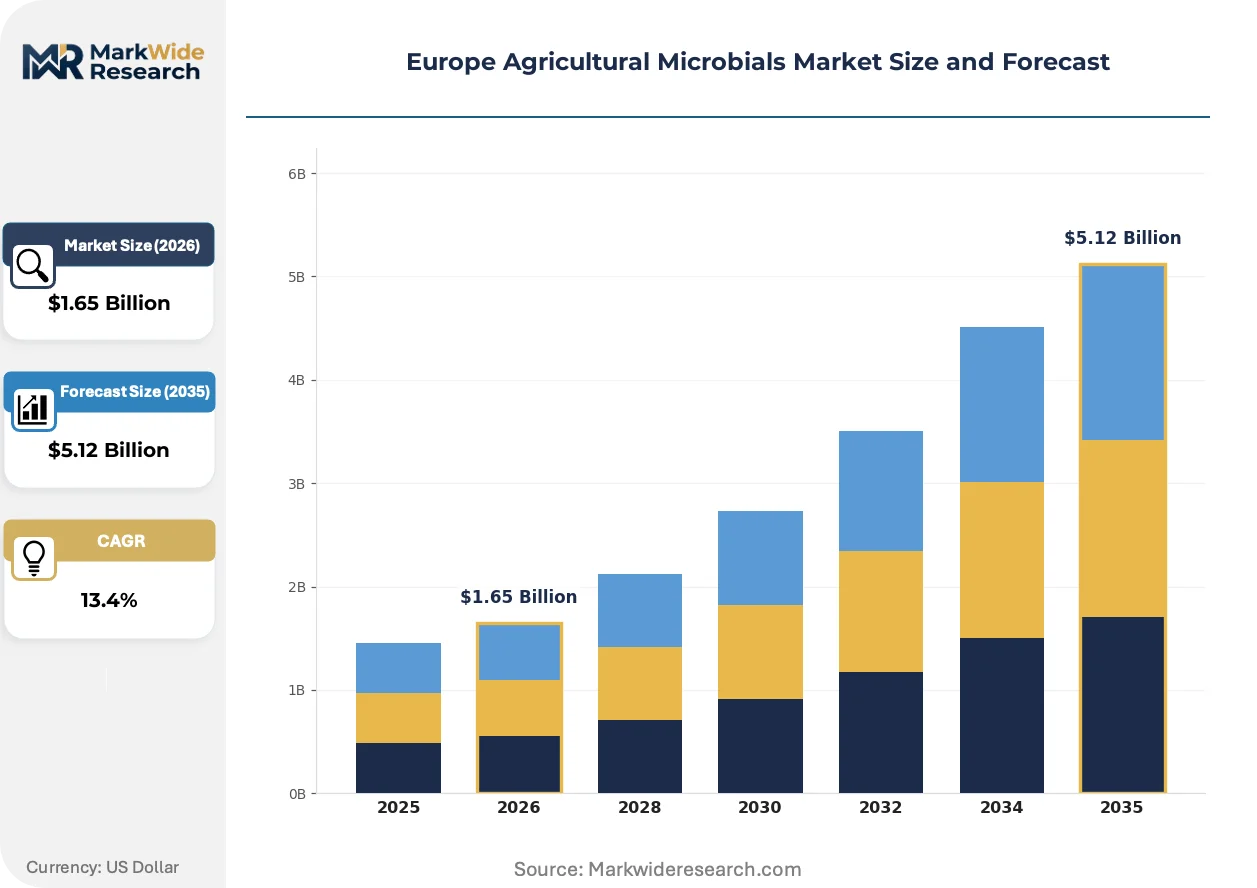
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $5.12 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungi, Bacteria, Protozoa, Viruses Application: Soil Health, Crop Protection, Seed Treatment, Fertilization End User: Farmers, Agricultural Cooperatives, Gardening Services, Crop Management Firms Distribution Channel: Online Retail, Agricultural Supply Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, Koppert Biological Systems, Certis Biologicals, Sumitomo Chemical, Lallemand Inc., Biolchim SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Microbials Market Shifts & Advancements
Live microbial consortia are displacing single-strain formulations as the dominant technical approach, with multi-species products commanding formulation premiums and reshaping manufacturing scale requirements across European supply chains.
RNA interference technology is expanding into agricultural microbials through spray-induced gene silencing platforms that target pest mRNA without transgenic modification. Bayer and Syngenta field trials across German sugar beet and French maize operations are accelerating regulatory familiarity. The technology is expanding into conventional chemistry displacement scenarios where microbial delivery vehicles reduce siRNA production costs below synthetic pesticide equivalents.
REACH framework revisions are tightening classification thresholds for microbial metabolites and formulation adjuvants, forcing reformulation of legacy Bacillus thuringiensis products. ECHA's 2024 guidance on nano-scale particle registration is capturing protein-based biopesticide carriers. German and Dutch registrants are responding by front-loading toxicology studies to preempt authorization delays.
Cooperative procurement consolidation is compressing supplier negotiation cycles across French and German farming alliances. Large-scale buying groups now demand multi-year biological input contracts with performance guarantees tied to yield outcomes. This shift is most visible in Denmark's Arla Foods dairy cooperative network, where farmer-members must document microbial soil health investments to maintain milk premium contracts.
Europe Agricultural Microbials Market Segmentation
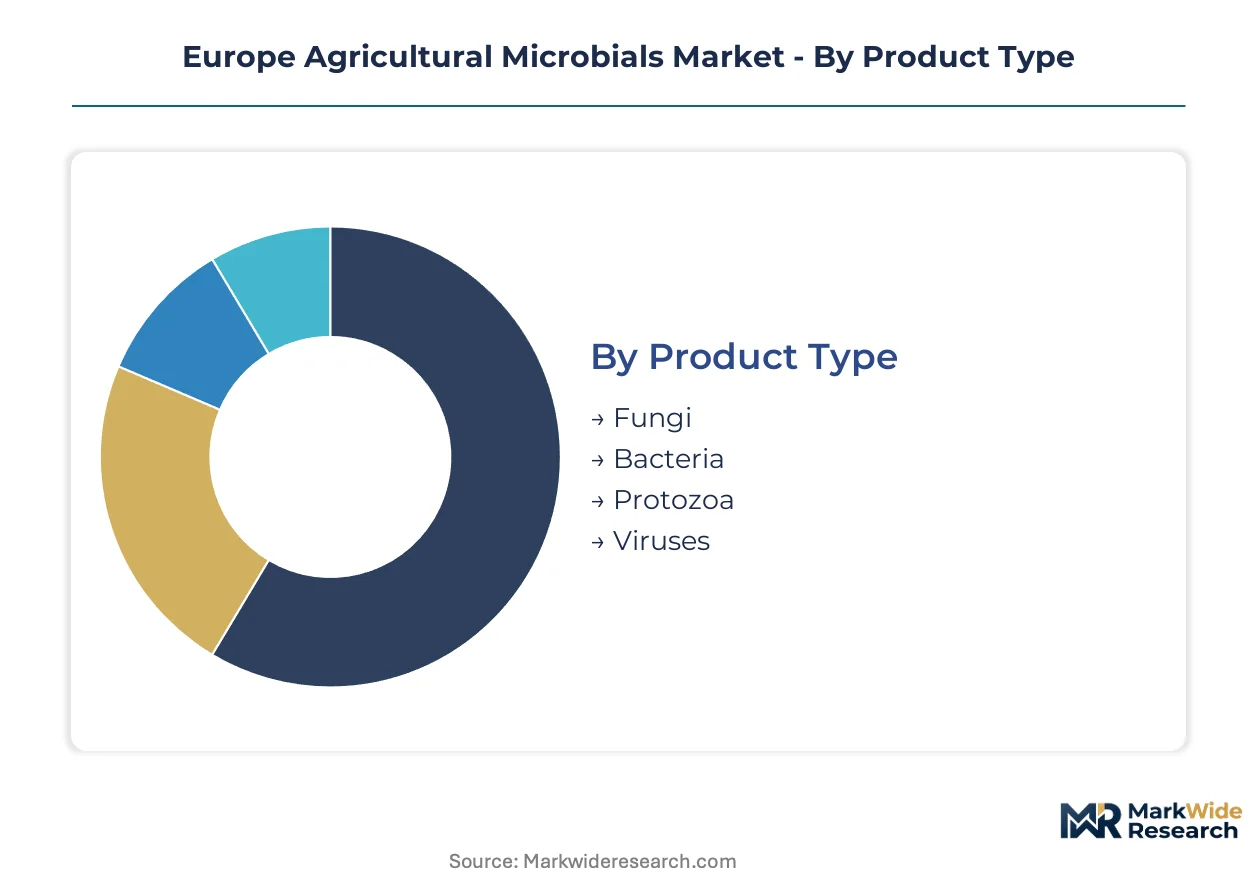
Segmentation in the Europe agricultural microbials market reveals how formulation chemistry, application timing, and procurement channels create distinct margin profiles. Buyers optimize across these dimensions based on crop value intensity and regulatory compliance requirements.
Product Type:
Bacterial formulations anchor standalone soil and foliar programs, while fungi increasingly embed into integrated pest management stacks for high-value horticulture.
- Fungi:Trichoderma and Beauveria species dominate protected horticulture across Spain and Italy, displacing methyl bromide fumigants under F-Gas Regulation timelines. Demand concentrates in Mediterranean greenhouse clusters where organic certification premiums justify per-hectare cost premiums.
- Bacteria:Bacillus and Pseudomonas strain libraries command the largest formulation volumes, with Bacillus subtilis seed treatments penetrating French and German broadacre farming through cooperative procurement frameworks.
- Protozoa:Niche soil health applications in viticulture and orchard systems, primarily through French biological input distributors serving organic wine certification protocols.
- Viruses:Baculovirus-based biocontrols for lepidopteran pests in specialty vegetable production, limited by narrow host ranges and temperature stability constraints.
Bacteria leads volumes today; fungi is gaining share fastest.
Application:
Application timing determines integration depth with farm equipment and precision agriculture infrastructure across European farming systems.
- Seed Treatment:Micro-encapsulated Bacillus formulations applied at planting capture farmer preference for early establishment protocols. German and French cooperatives pilot precision dosing equipment that integrates microbial inoculants with conventional seed coatings.
- Soil Health:Broad-acre applications occupy the largest treated hectare base but carry lower per-hectare margins. Polish and Romanian farming cooperatives underindex here relative to Western European adoption rates.
- Crop Protection:Foliar biocontrol sprays for vine and vegetable crops across Bordeaux and Tuscany supply chains, timed to downy mildew pressure windows and organic certification harvest intervals.
- Fertilization:Microbial biofertilizers enhancing nitrogen fixation and phosphorus solubilization, primarily in legume rotations and organic systems with restricted synthetic input allowances.
Soil health dominates hectare coverage; seed treatment commands the steepest expansion trajectory.
End User:
End user structure reflects the consolidation of European agricultural procurement and the fragmentation of specialty crop production.
- Farmers:Individual growers in Southern Europe and Eastern Europe purchase through agricultural supply stores with limited technical support, constraining adoption of multi-strain consortia requiring application expertise.
- Agricultural Cooperatives:Large-scale buying groups in France and Germany negotiate multi-year biological input contracts with performance guarantees. Denmark's Arla Foods network mandates documented microbial soil health investments for milk premium eligibility.
- Gardening Services:Municipal and commercial landscaping contractors in urban peripheries, sourcing through wholesale distributors with limited strain-specific technical guidance.
- Crop Management Firms:Precision agriculture service providers bundling microbial applications with drone-based monitoring and variable-rate equipment across German sugar beet and French maize operations.
Agricultural cooperatives concentrate procurement volume today; crop management firms are expanding most quickly.
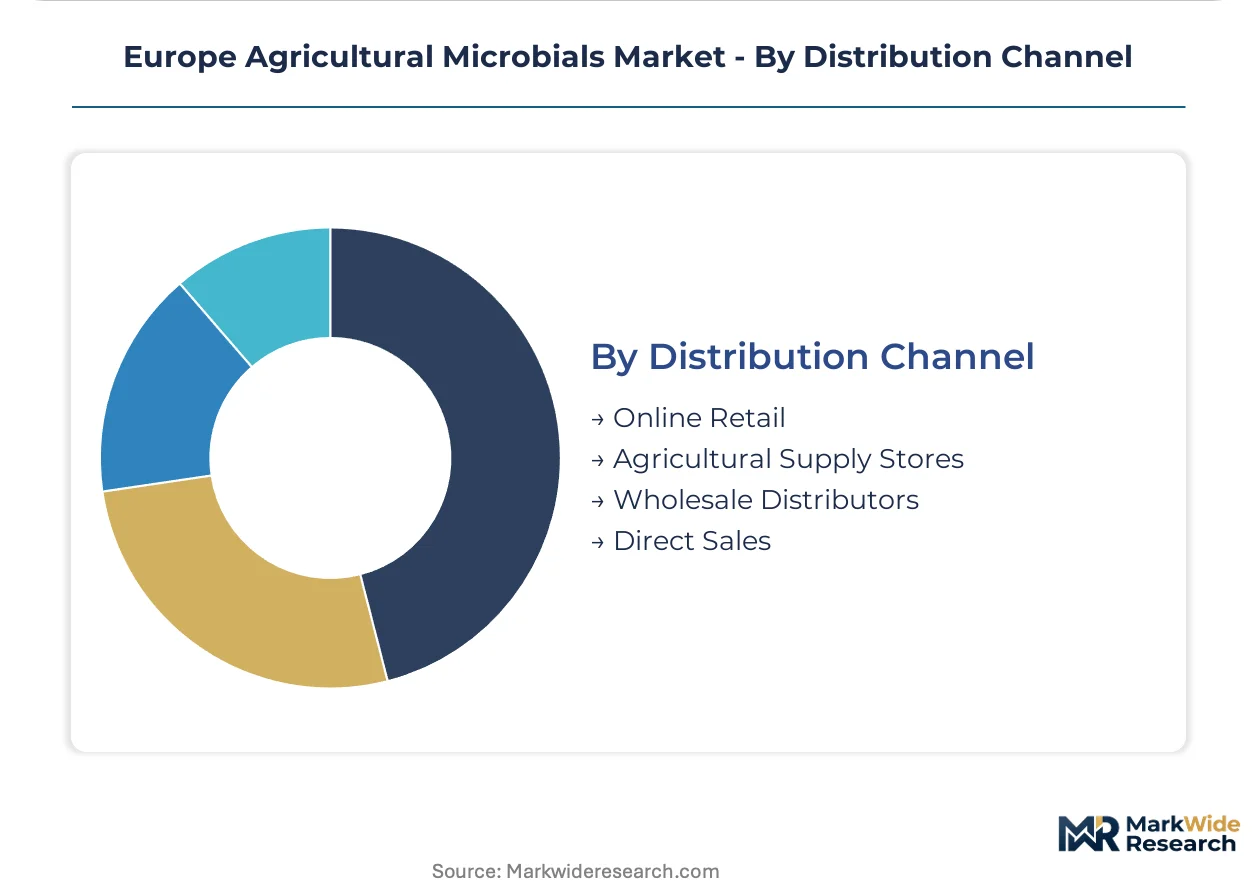
Distribution Channel:
Channel structure varies with product complexity, with technical formulations requiring advisory touchpoints that online retail cannot replicate.
- Agricultural Supply Stores:Dominant channel for bacterial inoculants and standard biocontrols, with French and German store networks providing EFSA registration guidance and application timing calendars.
- Wholesale Distributors:Primary route for large-volume cooperative procurement, with Rhine corridor distributors controlling fermentation-derived product flows from Ludwigshafen manufacturing clusters.
- Direct Sales:Technical fungal formulations and multi-strain consortia requiring shelf-life management protocols, sold through manufacturer agronomist relationships in protected horticulture.
- Online Retail:Emerging channel for smaller-scale gardening and specialty crop applications, constrained by temperature-controlled logistics requirements for live microbial products.
Agricultural supply stores lead transaction volumes today; direct sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological input manufacturing first scaled in Germany's Rhine corridor during the 1990s, establishing Europe's foundational fermentation infrastructure for agricultural microbials.
Germany
Large-scale farming cooperatives in Lower Saxony and North Rhine-Westphalia pilot bacterial inoculants at commercial scale, driven by Common Agricultural Policy subsidy frameworks requiring documented microbial adoption. The German Federal Office of Consumer Protection and Food Safety enforces national biocontrol standards atop EFSA baselines. Ludwigshafen hosts concentrated fermentation capacity for high-density bacterial cultures exceeding 10^9 CFU per gram.
France
Vineyard biocontrol demand concentrates in Bordeaux and Champagne, where downy mildew pressure drives adoption of Bacillus subtilis combinations for organic wine certification. The French National Agency for Food, Environmental and Occupational Health Safety imposes additional registration requirements that fragment cross-border market access. Agricultural cooperatives in Île-de-France negotiate multi-year biological input contracts with performance guarantees tied to yield outcomes.
Spain
Greenhouse operators in Almería and Valencia scale Trichoderma-based soil treatments to replace methyl bromide fumigants ahead of F-Gas Regulation phase-out deadlines. Specialty crop producers expand biological input programs for protected horticulture serving Northern European export markets. Andalusian distribution networks channel fermentation-derived products from Rhine corridor manufacturing clusters.
Italy
Organic wine certification protocols in Tuscany and Piedmont sustain niche demand for protozoa-based soil health applications through specialized biological input distributors. The Farm to Fork Strategy's pesticide reduction targets accelerate cooperative procurement shifts toward fungal biocontrols in Emilia-Romagna's vegetable supply chains. Mediterranean greenhouse clusters in Sicily trial multi-strain consortia for integrated pest management stacks.
Poland
Broadacre farming cooperatives in Greater Poland and Silesia underindex on biological inputs relative to Western European adoption rates, presenting first-mover expansion potential. Neonicotinoid seed treatments retain cost-per-hectare advantages in commodity grains, delaying microbial substitution. The national agricultural regulator enforces EU Green Deal alignment through subsidy eligibility documentation requirements.
Europe Agricultural Microbials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and strain registration expertise, with bacterial inoculants commanding standard margins and multi-species fungal consortia capturing formulation premiums. The market structures around three archetypes: integrated agrochemical conglomerates with seed treatment platforms, specialized biological input manufacturers with fermentation captive supply, and cooperative-linked distributors with technical advisory capabilities. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with precision agriculture service providers.
Within the integrated conglomerate tier, BASF SE and Bayer AG exemplify players leveraging captive fermentation infrastructure and seed treatment integration to sustain positioning. Koppert Biological Systems occupies a specialist position among dedicated biological input manufacturers. These three entities represent divergent strategic postures: chemical-heritage conglomerates diversifying through microbial pipelines versus purpose-built biological specialists with technical advisory depth.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Koppert Biological Systems |
| Certis Biologicals |
| Sumitomo Chemical |
| Lallemand Inc. |
| Biolchim SpA |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between organic-compliant microbial consortia and standard bacterial inoculants manifests in parallel pricing premiums and supply chain complexity. Premium formulations command multi-tier markups through specialized distribution networks, while commodity-grade products flow through consolidated cooperative procurement channels in France and Germany.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with strain registration tier and fermentation density as primary differentiation drivers. Premium multi-species fungal consortia capture formulation premiums through organic certification alignment, while economy-tier Bacillus inoculants face cost compression from cooperative volume aggregation. Agricultural cooperatives in Denmark and Germany exhibit lowest price sensitivity due to subsidy-linked procurement mandates, whereas individual farmers in Poland and Romania prioritize per-hectare cost minimization.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's Farm to Fork Strategy are reshaping sourcing patterns toward Rhine corridor manufacturing clusters in Germany. High-density bacterial cultures draw from fermentation infrastructure concentrated in Ludwigshafen and Monheim, with Trichoderma spore supplies resting on Italian and Spanish production nodes. Single-source vulnerability concentrates in contract manufacturing exceeding 10^9 CFU per gram densities. Distribution runs through agricultural supply stores and wholesale distributors serving cooperative procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe agricultural microbials market functions as a stable compounder, with binding pesticide reduction targets under the EU Green Deal embedding biological substitution into irreversible procurement frameworks.
For Market Incumbents: Anchor market position through backward integration into captive fermentation capacity and seed treatment platform control. Synthetic chemistry residual efficacy in Polish and Romanian commodity grains presents substitution threat requiring cooperative partnership investment. Prioritize strain registration pipeline acceleration to preempt EFSA authorization bottlenecks. For New Entrants and Emerging Players: The F-Gas Regulation in Europe opens a window for Trichoderma-based soil treatment specialization in Spanish and Italian greenhouse clusters. Polish and Romanian farming cooperatives underindex on biological inputs relative to Western European adoption rates, presenting first-mover expansion potential. Pursue direct sales relationships with protected horticulture operators requiring shelf-life management protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation capacity scarcity intersects with cooperative procurement consolidation. Five-to-ten-year viability hinges on regulatory tailwind durability and strain library depth. Target specialized biological input manufacturers with technical advisory capabilities and captive supply infrastructure. Watch EFSA authorization timeline compression as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive supply of high-density bacterial cultures insulates against Rhine corridor single-source vulnerability. |
| Seed Treatment Platform Integration | Precision dosing equipment in German cooperatives locks in early-season application preference. |
| Multi-Species Consortium Development | Live microbial combinations command formulation premiums across Mediterranean greenhouse supply chains. |
| EFSA Registration Front-Loading | Preemptive toxicology studies reduce 18-36 month authorization timeline exposure. |
| Cooperative Procurement Partnership | Multi-year biological input contracts with French and German farming alliances secure volume commitments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, agricultural cooperative procurement leads, biological input distributors, and EFSA regulatory affairs specialists with secondary validation. Data sources included customs and trade flow records, Cefic chemical industry reports, SEC 10-K filings from listed agrochemical conglomerates, and EFSA novel food and feed risk assessment databases. Bottom-up strain registration tracking and top-down cooperative procurement surveys enabled triangulation across market size estimates.
Segment-weighting approaches modeled value and volume trajectories across the projection horizon by product type, application timing, end-user structure, and distribution channel, with additional granularity on organic certification tier and cooperative membership density. CAGRs were derived from regression analysis against pesticide reduction policy implementation schedules and subsidy framework adoption curves. Forecast inputs incorporated F-Gas Regulation phase-out timelines and REACH framework revision impacts on formulation chemistry.
Revisions become necessary when EFSA authorization timelines extend beyond baseline assumptions, when fermentation capacity concentration triggers supply disruption, or when neonicotinoid regulatory exemptions delay microbial substitution in Eastern European commodity grains. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market