
 Qatar Greenhouse Market | 2026-2036
Qatar Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Greenhouse Market Intelligence
Qatar's National Food Security Strategy is hardening procurement mandates for locally grown vegetables across government-backed retail and hospitality buyers. Hassad Food leverages its sovereign wealth backing to anchor large-scale controlled-environment production in Al Shahaniya. Horizon Doha competes on technology leadership in climate-controlled greenhouse design for premium crop segments. Pergola Contracting & Green Houses specializes in custom-built installations that dominate the private agricultural investment channel.
A greenhouse is an enclosed structure with transparent or translucent covering materials—typically tempered glass, polycarbonate panels, or polyethylene films—that permits solar radiation entry while trapping thermal energy to maintain regulated growing conditions. Structural frameworks employ galvanized steel or aluminum alloys engineered to withstand wind loads exceeding 120 km/h in Gulf coastal environments. Hydroponic systems and climate control technologies command the highest margin pools as growers prioritize water-use efficiency in an arid climate with negligible rainfall. Automated irrigation and sensor technologies represent the fastest-expanding technology segment as precision agriculture protocols reduce nutrient waste and labor dependency.
The Ministry of Municipality and Environment enforces agricultural land-use zoning and greenhouse construction permits under Qatar's food security framework, while the Qatar General Organization for Standardization and Metrology sets product quality benchmarks for domestically cultivated produce. Compliance with these dual regulatory layers shapes market access for imported greenhouse technologies and mandates local adaptation to extreme heat and salinity conditions. Stakeholders must monitor evolving subsidy allocations for energy-efficient cooling systems and desalinated water infrastructure as policy trade-offs between fiscal sustainability and import independence intensify.
Market Dynamics
Qatar's National Food Security Strategy is restructuring procurement mandates across government-backed retail and hospitality channels, forcing rapid capacity buildout in controlled-environment agriculture ahead of import substitution deadlines.
Growth Catalysts
- Import Substitution Mandates:Qatar's food security framework imposes hard targets for domestic vegetable production, compelling retail chains to source from local hydroponic operators rather than Saudi and Jordanian suppliers.
- Desalinated Water Infrastructure:The Ministry of Municipality and Environment channels subsidized desalinated water to Al Khor and Al Wakrah agricultural zones, slashing input costs for greenhouse operators dependent on artificial irrigation.
- Energy-Efficient Cooling Subsidies:Policy allocations for evaporative cooling and solar-powered climate control systems reduce operational expenditure for controlled-environment facilities facing 50°C summer peaks.
Market Restraints
- Capital Intensity of Controlled Systems:Automated hydroponic installations require substantial upfront investment in sensor networks and climate control hardware, limiting private agricultural investment to sovereign-backed entities.
- Technical Workforce Scarcity:Precision agriculture expertise in nutrient solution management and integrated pest management remains concentrated among expatriate specialists, constraining operational scale-up.
- Salinity Stress on Equipment:Coastal greenhouse clusters in Al Wakrah face accelerated corrosion of galvanized steel frameworks and irrigation components from airborne salt deposition.
Strategic Opportunities
- Al Shahaniya Expansion Corridor:Proximity to Doha's logistics infrastructure and lower land costs position this zone for large-scale tomato and cucumber cultivation serving hypermarket distribution centers.
- Pharmaceutical-Grade Botanicals:Climate-controlled environments enable high-value saffron and medicinal herb production for Gulf pharmaceutical manufacturers seeking regional API sourcing.
- Solar-Hydroponic Convergence:Integration of photovoltaic arrays with closed-loop irrigation systems creates off-grid production models for remote agricultural settlements beyond central grid capacity.
Industry Challenges
- Certification Timeline Compression:Qatar General Organization for Standardization and Metrology quality benchmarks for pesticide residue and traceability require 12-18 month validation cycles, delaying market entry for new cultivators.
- Integration Complexity with Legacy Distribution:Traditional wholesale markets in Doha's Central Market lack cold-chain infrastructure compatible with hydroponic produce shelf-life requirements, forcing parallel logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Greenhouse Market |
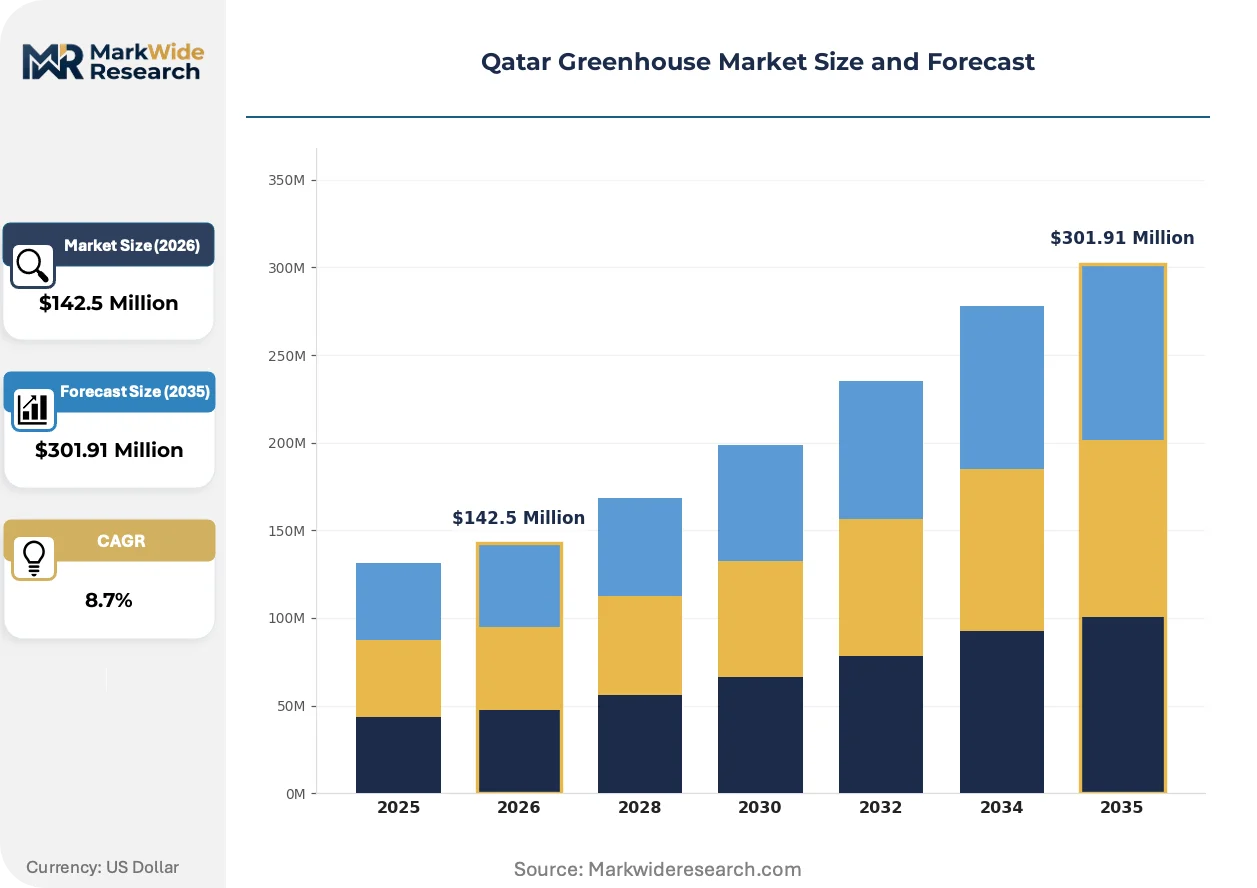
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponic Systems, Organic Grow Bags, Greenhouse Covers, Nutrient Solutions Installation Type: Permanent Structures, Mobile Units, Custom-built Greenhouses, Temporary Installations End User: Agricultural Producers, Research Institutions, Landscaping Services, Hobbyist Gardeners Technology: Automated Irrigation, Climate Control Systems, LED Grow Lights, Sensor Technologies |
| Companies Covered | Horizon Doha, Hassad Food, Pergola Contracting & Green Houses, Spanish Greenhouse Technology Companies (Joint Ventures), Ministry of Municipality and Environment (MME), Naas Group, Al Dafna Greenhouse, Local Agricultural Investment Entities, Qatari Agricultural Development Company (AGRICO), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Greenhouse Market Strategic Shifts & Innovations
Precision agriculture protocols are compressing resource consumption benchmarks while sensor-driven automation reshapes labor models across Qatar's controlled-environment facilities.
Automated nutrient dosing systems equipped with ion-selective electrodes and machine learning feedback loops are electrifying water-use efficiency standards in hydroponic operations. Large-scale producers in Al Khor are deploying these systems to cut fertilizer waste by half while maintaining yield consistency. The technology is compressing operational cost structures for facilities competing against subsidized imports from Iran and Turkey.
The Ministry of Municipality and Environment tightened agricultural land-use zoning enforcement under Qatar's food security framework, requiring environmental impact assessments for all new greenhouse construction permits. This regulatory friction is extending project timelines by 8-14 months but is channeling investment toward pre-approved industrial zones with existing desalination hookups. Smaller private operators are consolidating into agricultural cooperatives to share compliance costs and permit processing resources.
Hypermarket procurement teams are unbundling after-sales service from equipment supply contracts, demanding standalone technical support agreements with 4-hour response guarantees for climate control failures. This purchasing pattern is displacing turnkey installation vendors who previously bundled hardware with limited warranty coverage. The shift is most visible in Lulu and Carrefour Qatar's supplier qualification protocols for local greenhouse produce sourcing.
Qatar Greenhouse Market Segmentation
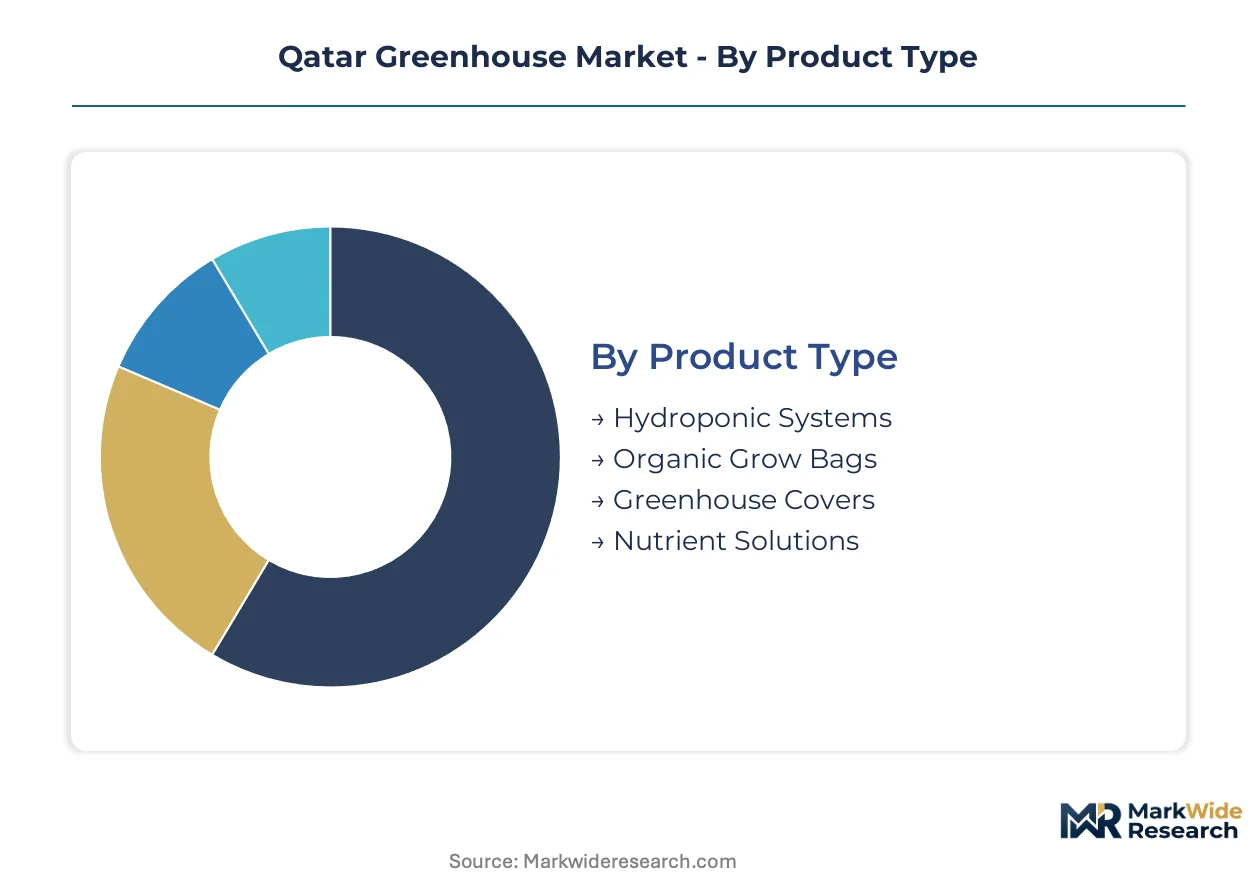
Qatar's greenhouse market fragments across four structural dimensions that determine capital deployment patterns and technology procurement cycles. Product type and technology segments concentrate margin capture, while installation and end-user categories shape project financing structures and operational scale.
Product Type:
Replacement cycles for core growing infrastructure accelerate as operators modernize Al Khor and Al Wakrah facilities to meet tightened food security procurement standards.
- Hydroponic Systems:Soil-less cultivation platforms using NFT, DWC, or aeroponic configurations dominate large-scale commercial operations. Demand concentrates among Al Shahaniya producers supplying government-mandated retail contracts, driven by water-use efficiency requirements in Qatar's arid climate.
- Greenhouse Covers:Multi-layer polyethylene films and polycarbonate panels engineered for 120 km/h wind loads and 50°C thermal stress. Al Wakrah coastal clusters prioritize UV-stabilized materials with enhanced salt corrosion resistance.
- Organic Grow Bags:Coco coir and peat-based substrates for soil-buffered cultivation in smaller-scale operations.
- Nutrient Solutions:Pre-formulated hydroponic fertilizers and pH buffering agents for closed-loop irrigation systems.
Hydroponic Systems sits at the top of the volume ranking, with Greenhouse Covers climbing the fastest.
Installation Type:
Cost tier differentiation separates sovereign-backed permanent facilities from private agricultural investments seeking lower capital exposure.
- Permanent Structures:Galvanized steel or aluminum-framed facilities with integrated climate control and fixed foundation anchoring. Hassad Food's Al Shahaniya operations anchor demand for these installations serving hypermarket distribution networks.
- Custom-built Greenhouses:Bespoke designs accommodating crop-specific light transmission and cooling requirements. Pergola Contracting dominates this channel for private investors targeting premium tomato and cucumber segments.
- Mobile Units:Relocatable tunnel structures for seasonal crop rotation or land-lease flexibility.
- Temporary Installations:Low-cost polyethylene tunnels for hobbyist or trial cultivation with minimal infrastructure commitment.
Permanent Structures command the largest installed base, though Custom-built Greenhouses is gaining share fastest among private capital entrants.
End User:
Customer type determines technology sophistication thresholds and service contract structures across Qatar's agricultural value chain.
- Agricultural Producers:Commercial-scale operators supplying retail chains under National Food Security Strategy procurement mandates. Lulu and Carrefour Qatar's supplier qualification protocols drive demand for traceability-integrated growing systems.
- Research Institutions:Qatar University and agricultural extension centers piloting climate-adapted cultivars and precision agriculture protocols.
- Landscaping Services:Commercial nursery operations supplying municipal greening projects and private estate contracts.
- Hobbyist Gardeners:Residential consumers in Doha's expatriate communities pursuing small-scale vegetable cultivation.
Agricultural Producers represents the dominant demand source, with Research Institutions expanding most quickly on state-funded agricultural R&D allocations.
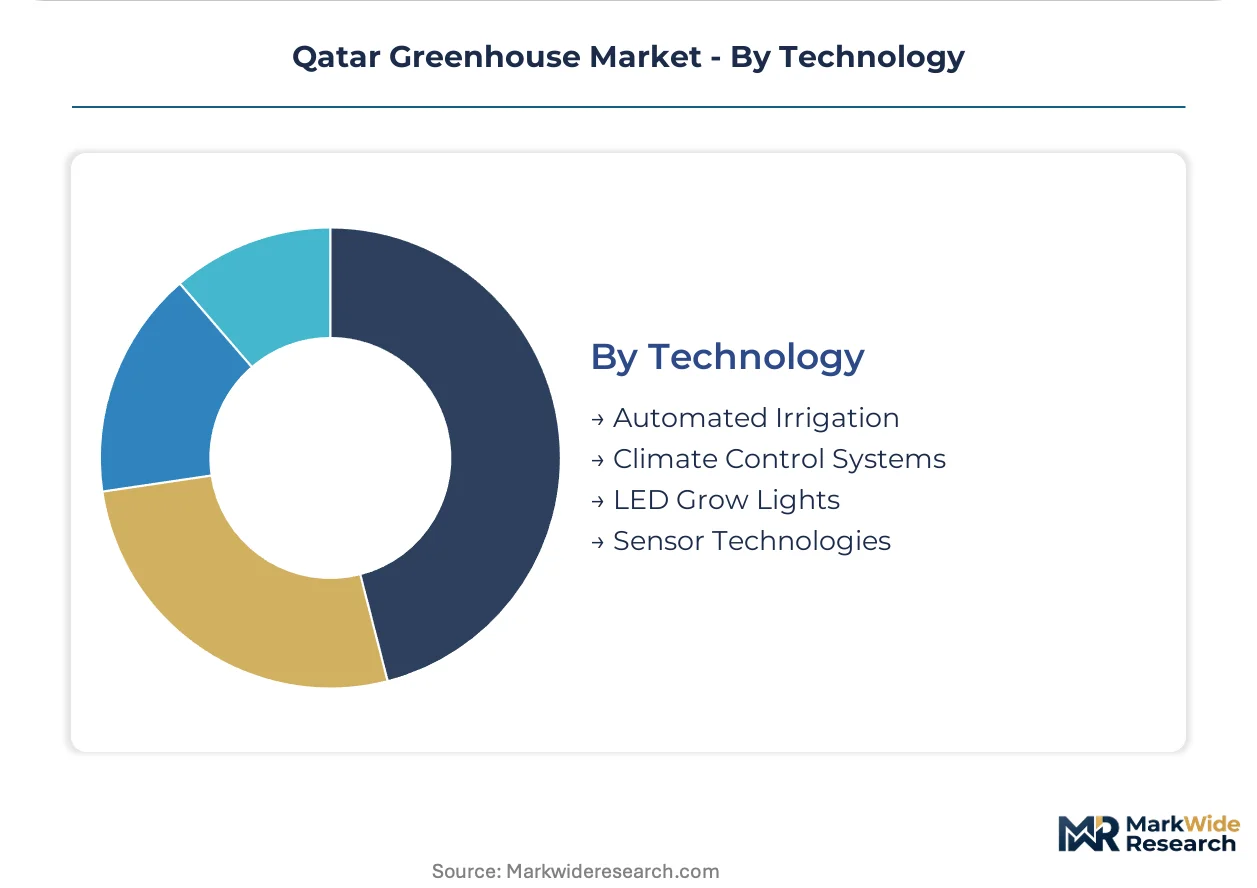
Technology:
Margin concentration tracks automation intensity as labor scarcity and precision agriculture protocols reshape operational economics.
- Automated Irrigation:Sensor-networked drip and NFT systems with programmable nutrient dosing and pH regulation. Large Al Khor producers deploy these systems to compress fertilizer waste while maintaining yield consistency against Iranian and Turkish import competition.
- Climate Control Systems:Evaporative cooling, fogging, and ventilation automation managing 50°C summer peaks. Subsidized energy-efficient cooling allocations from the Ministry of Municipality and Environment reduce operational expenditure for adopters.
- Sensor Technologies:IoT-enabled environmental monitoring for light, humidity, and substrate moisture with cloud-based analytics.
- LED Grow Lights:Supplemental spectrum-tuned lighting for year-round production and photoperiod manipulation.
Automated Irrigation leads technology procurement volumes, while Sensor Technologies shows the steepest expansion trajectory on falling hardware costs and precision agriculture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controlled-environment agriculture in Qatar traces its modern lineage to post-2017 food security investments that transformed coastal desert zones into intensive hydroponic production clusters. Sovereign capital deployment concentrated initial capacity around Al Khor and Al Wakrah, establishing the geographic template for subsequent expansion.
Al Khor
Al Khor hosts the densest concentration of large-scale hydroponic facilities serving government-mandated retail procurement contracts. The Ministry of Municipality and Environment channels subsidized desalinated water infrastructure to this zone, slashing irrigation input costs for operators. Tomato and cucumber cultivation dominates Al Khor's greenhouse clusters, with automated nutrient dosing systems compressing fertilizer waste benchmarks against Iranian import competition.
Al Wakrah
Al Wakrah's coastal greenhouse clusters confront accelerated equipment corrosion from airborne salt deposition, driving demand for UV-stabilized covering materials and enhanced steel galvanization. The Qatar General Organization for Standardization and Metrology enforces pesticide residue benchmarks that extend certification timelines for new cultivators entering this zone. Private agricultural investors favor Al Wakrah for custom-built installations targeting premium crop segments.
Al Shahaniya
Al Shahaniya anchors sovereign-backed production at scale, with Hassad Food operating permanent steel-framed facilities integrated with hypermarket distribution networks. Lower land costs and proximity to Doha's logistics infrastructure position this corridor for capacity expansion under tightened import substitution deadlines. Climate control automation manages 50°C summer thermal stress through subsidized evaporative cooling allocations.
Doha Metropolitan Area
Doha's urban periphery concentrates research institutions piloting climate-adapted cultivars and precision agriculture protocols. Qatar University agricultural extension centers collaborate with commercial operators to validate sensor-driven automation for nutrient solution management. The Central Market's legacy wholesale infrastructure forces parallel cold-chain investment from hydroponic producers seeking retail channel access.
Qatar Greenhouse Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and sovereign backing dimensions. The vendor base stratifies between turnkey installation providers and standalone equipment fabricators, with consolidation pressure intensifying as hypermarket procurement teams unbundle after-sales service from hardware supply. Three archetypes dominate: sovereign-anchored scale operators, technology-specialized design firms, and custom fabrication contractors serving private capital. Competitive moves concentrate on strategic partnerships for desalination infrastructure access and portfolio diversification into pharmaceutical-grade botanicals.
Within the sovereign-backed tier, Hassad Food exemplifies scale-driven vertical integration from production through distribution. Horizon Doha occupies a position among technology-focused design specialists, while Pergola Contracting & Green Houses anchors the custom fabrication segment for private agricultural investors. Spanish Greenhouse Technology Companies, operating through joint venture structures, represent international technology transfer archetypes adapting European controlled-environment systems to Gulf coastal conditions. Naas Group and Al Dafna Greenhouse sit within mid-scale commercial operator categories, with AGRICO representing agricultural development company structures consolidating smaller cultivators under cooperative compliance frameworks.
| Leading Market Players |
|---|
| Horizon Doha |
| Hassad Food |
| Pergola Contracting & Green Houses |
| Spanish Greenhouse Technology Companies (Joint Ventures) |
| Ministry of Municipality and Environment (MME) |
| Naas Group |
| Al Dafna Greenhouse |
| Local Agricultural Investment Entities |
| Qatari Agricultural Development Company (AGRICO) |
| Others |
Cost & Logistics Intelligence
Hypermarket procurement teams at Lulu and Carrefour Qatar anchor pricing power in the Qatar greenhouse market, forcing three-tier pricing stratification across premium climate-controlled installations, standard turnkey systems, and economy-grade polyethylene tunnels.
Pricing Analysis
Project-based contract pricing dominates greenhouse procurement, with after-sales service unbundling now standard practice. Price differentiation tracks certification tier under Qatar General Organization for Standardization and Metrology benchmarks and automation intensity in climate control systems. Cost compression in standard-tier installations is intensifying because Spanish and Dutch equipment suppliers compete aggressively on turnkey packages. Private agricultural investors show highest price sensitivity, while sovereign-backed operators prioritize performance guarantees over capital expenditure.
Supply Chain Analysis
Qatar General Organization for Standardization and Metrology certification timelines gate market access, compressing supplier qualification cycles to 12-18 months. Equipment supply concentrates in Spain, the Netherlands, and China for greenhouse framing, climate control hardware, and sensor networks respectively. Galvanized steel frameworks, polycarbonate panels, and automated nutrient dosing systems constitute critical input dependencies. Single-source vulnerability runs through European climate control technology providers. Distribution runs through government-mandated retail procurement channels and direct-to-producer equipment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
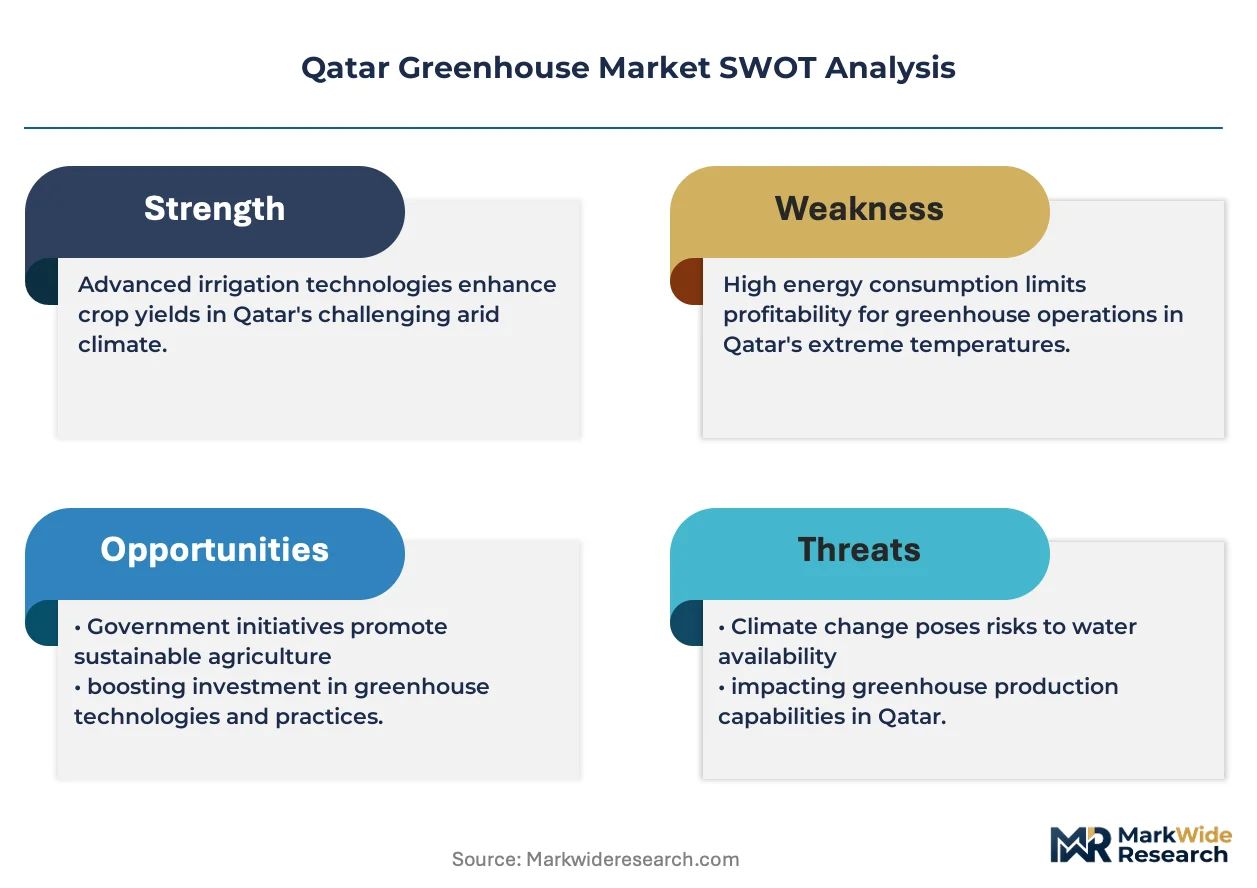
The Qatar greenhouse market represents a late-cycle quality story as National Food Security Strategy procurement mandates harden specifications toward traceability-integrated, climate-resilient production systems.
For Market Incumbents: Extend service contract portfolios to capture recurring revenue streams as hypermarket buyers demand 4-hour response guarantees for climate control failures. Deepen backward integration into desalinated water infrastructure access through Ministry of Municipality and Environment partnerships. Sovereign-backed scale operators threaten margin compression for technology-specialized design firms lacking captive distribution networks. For New Entrants and Emerging Players: E-commerce platforms for hobbyist greenhouse kits offer lowest competitive density among private capital channels. Al Wakrah's custom-built installation segment shows penetrable white space for European technology joint ventures targeting premium crop producers. A technical advisory-led go-to-market angle bypasses incumbent bundling advantages in after-sales support. For Investors and Strategic Acquirers: Sovereign wealth entities are the most active acquirer in this space, consolidating agricultural cooperatives under compliance-sharing frameworks. The five-to-ten year viability window favors targets with Ministry of Municipality and Environment permit pre-approval and existing desalination hookups. Monitor subsidy allocation shifts for energy-efficient cooling systems as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Desalination Infrastructure Partnership | Ministry of Municipality and Environment water subsidies slash operational expenditure for Al Khor operators. |
| Climate Control Technology Licensing | European joint ventures transfer evaporative cooling systems adapted to 50°C Gulf thermal stress. |
| Pharmaceutical-Grade Botanicals Diversification | Saffron and medicinal herb production targets Gulf API manufacturers seeking regional sourcing. |
| Sensor Network Integration | IoT-enabled nutrient dosing cuts fertilizer waste for Al Khor producers competing against Turkish imports. |
| Solar-Hydroponic Convergence | Photovoltaic arrays with closed-loop irrigation enable off-grid production beyond central grid capacity. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from greenhouse operations managers at Al Khor and Al Wakrah facilities, procurement leads at Lulu and Carrefour Qatar, Ministry of Municipality and Environment agricultural zoning officers, climate control technology suppliers, and precision agriculture specialists. Secondary validation drew from Qatar General Organization for Standardization and Metrology quality benchmarks, customs import records for greenhouse equipment, Ministry of Municipality and Environment subsidy allocation disclosures, and sovereign wealth fund agricultural investment filings. Bottom-up installation counts and top-down food security procurement value estimates were triangulated.
Historical reference periods anchored volume and value projections across the analysis window. The modeling framework segmented by product type, installation category, end-user archetype, and technology intensity, with additional dimensioning for regulatory compliance tier. CAGRs were derived from fitted growth curves against import substitution mandate timelines. Forecast inputs incorporated desalinated water infrastructure expansion schedules and evaporative cooling subsidy allocation trajectories.
The model assumes a particular technology adoption path; alternative pathways for solar-hydroponic integration would alter the outlook. Forecasts reflect assumptions about National Food Security Strategy procurement enforcement continuity and Ministry of Municipality and Environment permit processing timelines. A model refresh is warranted upon material change in subsidy allocations for energy-efficient cooling systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dry Onion Market
Vegetables
Peas Market
Vegetables
United States Microgreens Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Field Peas Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Roselle Market
Vegetables
Dried Vegetable Market
Vegetables
IQF Vegetables Market
Vegetables
Greenhouse Produce Market
Vegetables
Asia-Pacific Peas Market