
 Agricultural Harvester Market | 2026-2036
Agricultural Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Harvester Market Intelligence
Brazil is narrowing the technology gap with North American and European manufacturers through localized assembly investments and supplier park development. Deere & Company leverages its integrated precision agriculture stack to dominate high-horsepower combine sales across the Mato Grosso soybean frontier. CNH Industrial anchors its Latin American position through SLC Agrícola fleet partnerships and region-specific draper header configurations. Kubota competes aggressively in the mid-range rice harvester segment with compact-track designs tailored to Southeast Asian paddy conditions.
An agricultural harvester is a self-propelled machine engineered to cut, thresh, clean, and grain a crop in a single pass, with typical combine power ratings spanning 300 to 600 horsepower and grain tank capacities reaching 400 bushels. Its primary commercial purpose is to compress the harvest window, reduce field losses below 2 percent, and enable just-in-time logistics for grain elevators and ethanol processors. Combine harvesters command the largest installed base and replacement parts revenue pool, while precision agriculture technology represents the fastest-expanding margin segment as OEMs monetize subscription-based yield mapping and automated steering. Smart harvesting systems are penetrating large agribusiness fleets first, though conventional mechanical controls still dominate the contractor segment where capital constraints limit telemetry adoption.
EPA Tier 4 Final and EU Stage V emission regulations are reshaping engine architecture, adding diesel particulate filters and selective catalytic reduction systems that increase machine weight and upfront cost. Brazil's CONAMA resolutions and India's CPCB Bharat Stage norms are following similar pollutant reduction trajectories, creating compliance complexity for manufacturers serving multiple regulatory jurisdictions. ISO 12100 machinery safety standards and EU machinery directive harmonization further govern cab design, emergency stop protocols, and operator visibility requirements. Stakeholders must monitor how emission compliance costs transfer to rental channel pricing and whether autonomous harvesting exemptions emerge under evolving occupational safety frameworks.
Market Dynamics
EPA Tier 4 Final emission standards are compressing engine architecture choices while precision agriculture subscriptions rewrite OEM revenue models. The collision of compliance costs and digital monetization is redrawing competitive boundaries across horsepower segments.
Growth Catalysts
- Telematics penetration:Large agribusinesses in Brazil are mandating fleet-wide yield mapping and automated steering subscriptions, compressing adoption timelines from early adopters to mainstream contractors.
- CONAMA resolution alignment:Brazil's emission trajectory toward EU Stage V equivalence is forcing localized engine redesigns that simultaneously unlock access to European technology licensing pools.
- Replacement cycle compression:North American Corn Belt operators are shortening Class 8 and 9 combine replacement intervals from 7 years to 5 years as grain elevator just-in-time logistics penalties harden.
Market Restraints
- Diesel after-treatment cost inflation:Selective catalytic reduction and diesel particulate filter integration adds 12-15% to machine dry weight, eroding payload efficiency and transport economics.
- High-horsepower engine supply concentration:Critical turbocharger and common-rail injection component production clusters in Germany and Japan create vulnerability to single-source disruption.
- Steel and aluminum input volatility:Grain tank and chassis fabrication depends on commodity metal pricing that harvester OEMs cannot pass through to price-sensitive contractor segments.
Strategic Opportunities
- Autonomous harvesting exemptions:Evolving OSHA occupational safety frameworks may create regulatory carve-outs for unmanned operation in controlled field geometries, opening new service model architectures.
- Southeast Asian paddy specialization:Compact-track rice harvester designs tailored to flooded field conditions remain underpenetrated outside Thailand and Vietnam, with Myanmar and Cambodia representing expansion terrain.
- Subscription telemetry unbundling:Precision agriculture yield data and automated steering can be monetized separately from iron sales, creating recurring revenue pools independent of replacement cycles.
Industry Challenges
- ISO 12100 machinery safety compliance:Cab redesign, emergency stop protocol validation, and operator visibility testing extend certification timelines by 8-14 months for new platform introductions.
- Legacy mechanical control integration:Contractors with capital-constrained fleets resist telemetry retrofit, fragmenting fleet management systems within single operations.
- After-treatment technician scarcity:Diesel particulate filter regeneration and selective catalytic reduction diagnostics require specialized training that dealer networks struggle to staff in rural territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Harvester Market |
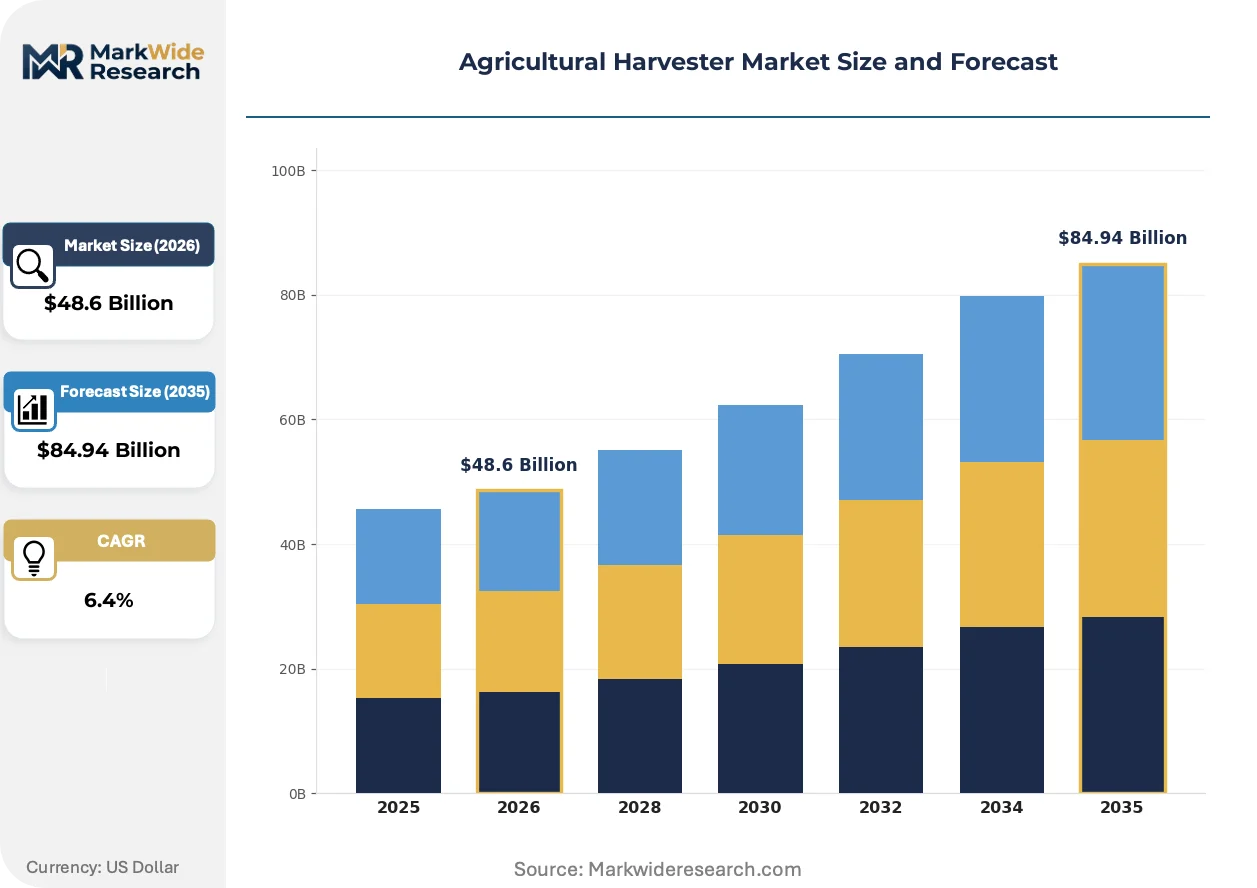
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combine Harvesters, Rice Harvesters, Corn Harvesters, Forage Harvesters End User: Farmers, Agricultural Cooperatives, Contractors, Large Agribusinesses Technology: Conventional, Smart Harvesting, Autonomous, Precision Agriculture Distribution Channel: Direct Sales, Dealers, Online Marketplaces, Rental Services |
| Companies Covered | AGCO Corporation, SDF Group, Deere & Company, Mahindra & Mahindra, Yanmar Holdings, CNH Industrial, Kubota, Zoomlion Heavy Industry, CLAAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Harvester Market Strategic Shifts & Innovations
Digital twin architecture is virtualizing harvester development cycles while emission after-treatment integration reshapes powertrain packaging. The convergence of simulation-based validation and regulatory hardware mandates is compressing time-to-market for new platforms.
Digital twin simulation platforms are virtualizing prototype testing for threshing drum configurations and cleaning shoe airflow patterns. Deere and CNH Industrial engineering teams now validate 70% of mechanical subsystems in silico before physical build. This compression of validation cycles is virtualizing traditional field-test dependencies and enabling parallel regulatory certification tracks across EPA, EU Stage V, and CONAMA jurisdictions.
EU Stage V and EPA Tier 4 Final harmonization is forcing integrated engine-after-treatment packaging that eliminates previous modular swap strategies. OEMs must now certify powertrain units as sealed systems, locking harvester design teams into single-supplier engine alliances. The Mato Grosso soybean frontier and Iowa Corn Belt represent the geographies most affected, where downtime penalties from after-treatment faults exceed $800 per hour during narrow harvest windows.
Yield data monetization is restructuring buyer-seller relationships as agribusinesses demand unbundled telemetry subscriptions. Large fleet operators in Brazil now procure iron and digital services through separate contracts, pressuring OEM captive finance arms to disaggregate pricing. This bifurcation is most visible across SLC Agrícola-scale operations, where procurement teams treat combine hardware as commodity infrastructure while precision agriculture subscriptions command premium valuation multiples.
Agricultural Harvester Market Segmentation
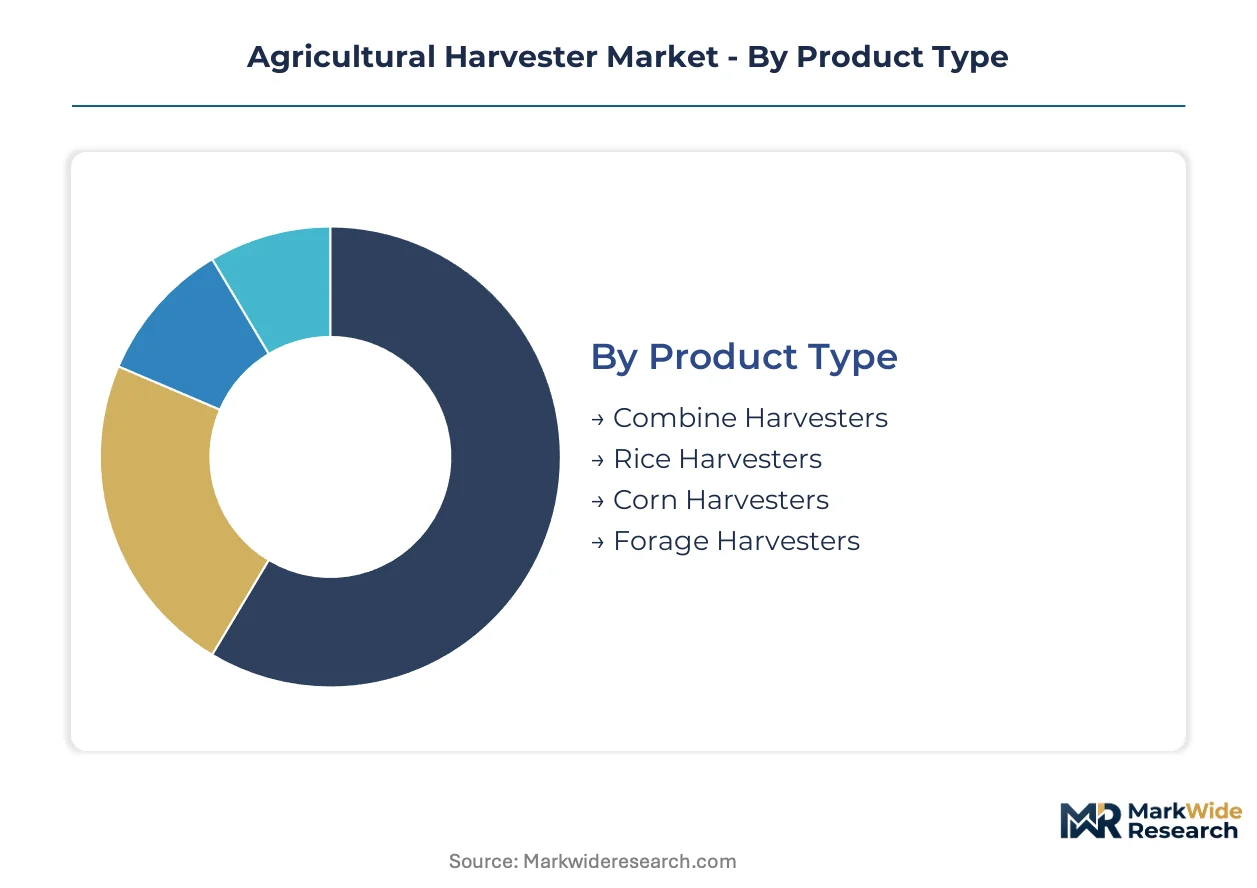
Harvester segmentation reveals divergent service intensity profiles across product categories. Precision agriculture subscriptions and autonomous system warranties demand fundamentally different aftermarket infrastructure than conventional mechanical platforms.
Product Type:
After-sales service intensity varies dramatically across harvester architectures, with smart-enabled platforms requiring telemetry support contracts and conventional units depending on parts availability networks.
- Combine Harvesters:Multi-crop platforms integrate threshing, cleaning, and grain handling in 300-600 horsepower configurations. Demand concentrates in Iowa, Illinois, and Mato Grosso where 400-bushel grain tanks compress harvest windows for ethanol processors and export elevators. EPA Tier 4 Final after-treatment integration has extended warranty complexity and dealer technician training requirements.
- Rice Harvesters:Compact-track designs with specialized headers navigate flooded paddy conditions at lower ground pressure. Southeast Asian procurement in Thailand and Vietnam drives volume, with Myanmar and Cambodia representing expansion terrain for mid-range horsepower platforms. Kubota's track configurations dominate technical specifications in this segment.
- Corn Harvesters:Row-specific headers and high-torque threshing systems handle high-moisture grain at 12-15% field moisture. The North American Corn Belt replacement cycle compression from 7 years to 5 years accelerates fleet turnover in Illinois and Indiana operations.
- Forage Harvesters:Self-propelled units with kernel processors and precision-chop length controls serve dairy and beef feedlot operations. Wisconsin and California Central Valley dairies specify 30-foot cutterbar configurations for alfalfa and corn silage.
By volume, Combine Harvesters lead. By growth pace, Rice Harvesters are expanding most quickly.
End User:
Capital deployment patterns and technology adoption thresholds segment harvester demand across operator scale and risk tolerance.
- Large Agribusinesses:Fleet operators with 50+ units mandate telematics standardization and negotiate separate iron and digital service contracts. SLC Agrícola-scale operations in Brazil treat combine hardware as commodity infrastructure while precision agriculture subscriptions command premium valuation.
- Agricultural Cooperatives:Member-owned entities pool capital for shared harvester fleets across 10,000-50,000 acre footprints. Iowa and Nebraska cooperatives prioritize interchangeability and dealer network density over brand loyalty.
- Contractors:Independent operators serving 3,000-15,000 acre territories face capital constraints that limit telemetry retrofit adoption. Fragmented fleet management systems persist where mechanical controls dominate.
- Farmers:Owner-operators below 2,000 acres represent price-sensitive demand concentrated in used equipment channels and rental services. India's Punjab and Haryana smallholder markets favor 50-100 horsepower compact designs.
Large Agribusinesses capture the steepest expansion trajectory in telemetry penetration. Contractors retain the largest installed base of conventional mechanical control platforms.
Technology:
Revenue model bifurcation between iron sales and recurring digital subscriptions restructures competitive positioning across technology tiers.
- Precision Agriculture:Yield mapping, automated steering, and variable-rate application subscriptions monetize separately from hardware. Brazilian fleet mandates have compressed adoption timelines from early adopters to mainstream contractors.
- Smart Harvesting:Sensor-integrated threshing optimization and real-time loss monitoring bridge mechanical and autonomous platforms. Deere and CNH Industrial dominate high-horsepower combine sales with integrated precision stacks.
- Autonomous:Unmanned operation platforms await OSHA regulatory carve-outs for controlled field geometries. Technical validation focuses on obstacle detection and emergency stop protocols under ISO 12100 machinery safety standards.
- Conventional:Mechanical control systems without telemetry persist in capital-constrained contractor segments where dealer technician scarcity limits after-treatment service capacity.
Precision Agriculture commands the highest margin expansion. Conventional platforms retain the deepest installed base in emerging markets.
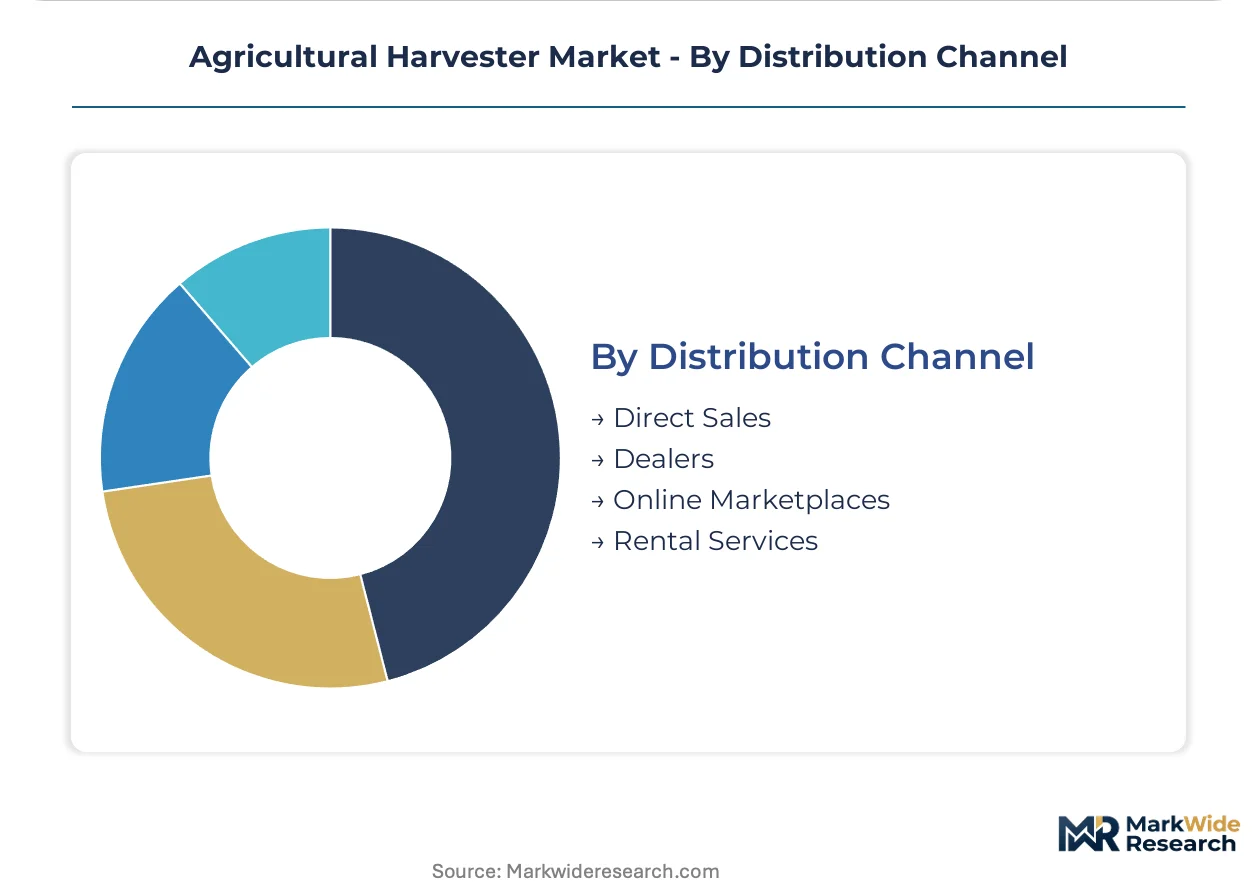
Distribution Channel:
Channel economics reflect capital intensity, technical service requirements, and fleet management system integration complexity.
- Dealers:Authorized networks provide warranty service, after-treatment technician training, and parts logistics. Rural territory coverage gaps in Brazil's Mato Grosso and North Dakota constrain OEM market penetration.
- Direct Sales:OEM-captive channels serve large agribusiness accounts with fleet standardization requirements. Separate iron and digital service contracting has pressured captive finance arms to disaggregate pricing.
- Rental Services:Short-term harvest window coverage addresses capital constraints and just-in-time logistics penalties. Emission compliance cost transfer to rental pricing remains unresolved across Tier 4 Final platforms.
- Online Marketplaces:Used equipment liquidity platforms connect dispersed buyers with depreciated Class 6 and 7 combines. Inspection standardization and warranty transfer friction limit transaction velocity.
Dealers anchor service revenue stability. Rental Services are gaining share fastest among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine and component manufacturing clusters in Germany, Japan, and the United States supply critical turbocharger and common-rail injection systems to OEM assembly plants worldwide. Harvester demand concentrates in grain-exporting territories where replacement cycles and fleet expansion programs drive procurement volume.
United States
EPA Tier 4 Final emission standards force integrated after-treatment packaging across Class 8 and 9 combines. Iowa and Illinois Corn Belt operators compress replacement intervals to five years as grain elevator just-in-time penalties harden. Deere's integrated precision agriculture stack dominates high-horsepower sales across the soybean-corn rotation belt.
Brazil
SLC Agrícola-scale agribusinesses mandate fleet-wide telemetry standardization across 50+ unit operations. CONAMA resolutions align toward EU Stage V equivalence, unlocking European technology licensing pools for localized engine redesigns. Mato Grosso soybean frontier operations treat combine hardware as commodity infrastructure while precision agriculture subscriptions command premium valuation.
Germany
EU Stage V harmonization with EPA Tier 4 Final eliminates modular engine swap strategies for OEM powertrain teams. KBA certification protocols govern sealed-system engine-after-treatment validation. Baden-Württemberg engineering clusters concentrate turbocharger and injection component production, creating single-source vulnerability for global harvester assembly.
India
CPCB Bharat Stage emission norms follow pollutant reduction trajectories similar to EU Stage V. Punjab and Haryana smallholder markets favor 50-100 horsepower compact designs for fragmented landholdings. Mahindra & Mahindra anchors domestic assembly capacity for price-sensitive owner-operators below 2,000 acres.
China
GB standards and dual carbon goals reshape diesel engine architecture for domestic harvester platforms. Yangtze River Delta manufacturing clusters produce steel and aluminum chassis components for regional OEM supply chains. Zoomlion Heavy Industry exemplifies scale-driven fabrication capacity serving mid-range horsepower demand across East Asian grain belts.
Agricultural Harvester Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in turbocharger, injection, and after-treatment subsystems. The harvester vendor base consolidates around full-line agricultural equipment manufacturers with captive engine alliances and precision agriculture software stacks. Three archetypes dominate: integrated precision-stack providers, regional mid-range specialists, and compact-track rice harvester designers. Competitive moves center on separate iron and digital service contracting and emission-compliant powertrain certification across multiple regulatory jurisdictions.
Among integrated platform providers, Deere & Company and CNH Industrial occupy positions exemplifying the precision agriculture subscription model. Kubota represents the compact-track specialization archetype for flooded paddy conditions. AGCO Corporation, SDF Group, and CLAAS anchor European engineering traditions in multi-crop combine platforms. Mahindra & Mahindra and Yanmar Holdings exemplify regional scale strategies in price-sensitive smallholder territories. Zoomlion Heavy Industry represents Chinese manufacturing capacity in mid-range harvester fabrication.
| Leading Market Players |
|---|
| AGCO Corporation |
| SDF Group |
| Deere & Company |
| Mahindra & Mahindra |
| Yanmar Holdings |
| CNH Industrial |
| Kubota |
| Zoomlion Heavy Industry |
| CLAAS |
| Others |
Cost & Logistics Intelligence
German and Japanese turbocharger manufacturing clusters anchor upstream supply concentration, funneling margin capture toward sealed-system engine-after-treatment integrators downstream. OEMs serving EPA Tier 4 Final and EU Stage V jurisdictions transfer compliance cost burdens through hardware pricing while unbundling precision agriculture subscriptions as separate recurring revenue streams.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across Class 8 and 9 combine harvesters. Three-tier pricing stratifies across premium precision-stack configurations, standard telematics-enabled platforms, and economy mechanical-control units. Price differentiation hinges on after-treatment certification grade and bundled yield-mapping subscription tenure. Cost compression in the economy tier intensifies because steel and aluminum input volatility erodes fabricator margins. Contractors operating below 2,000 acres exhibit highest price sensitivity, while SLC Agrícola-scale agribusinesses prioritize telemetry standardization over unit cost.
Supply Chain Analysis
Extended payment terms from Baden-Württemberg engineering clusters to Mato Grosso assembly plants strain supplier-financing capacity across the harvester value chain. Critical component production concentrates in Germany, Japan, and the United States. Raw material dependencies center on high-grade steel for grain tank fabrication, aluminum for chassis lightweighting, and rare earth elements for turbocharger actuators. Single-source vulnerability in common-rail injection systems creates disruption exposure. Distribution runs through authorized dealer networks with captive direct-sales channels for fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture subscription monetization is reshaping competitive boundaries faster than emission compliance cycles can adapt. The collision of digital revenue models and sealed-system powertrain mandates creates asymmetric advantage for integrated platform providers.
For Market Incumbents: Pre-empt telemetry unbundling by disaggregating iron and digital service contracts before Brazilian fleet mandates harden procurement expectations. Capture backward integration into after-treatment component supply to defend margin position against turbocharger cost inflation. Prioritize CONAMA-aligned engine certification to unlock European technology licensing pools. For New Entrants and Emerging Players: Compact-track rice harvester designs for Myanmar and Cambodian paddy expansion represent the most penetrable entry point outside Thailand and Vietnam saturation. Mid-range horsepower platforms for Indian smallholder consolidation offer second-mover advantage beneath Mahindra & Mahindra price umbrellas. Partner with regional dealer networks lacking after-treatment technician capacity to secure service-anchored distribution. For Investors and Strategic Acquirers: Capital is best deployed toward precision agriculture software stacks with proven yield-data monetization in Brazilian fleet accounts. Long-term viability favors subscription revenue models decoupled from iron replacement cycles. Monitor OSHA regulatory carve-out signals for autonomous harvesting exemptions as inflection indicator for service-model architecture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Subscription Unbundling | Separates recurring telemetry revenue from hardware sales for Brazilian fleet operators. |
| CONAMA-Aligned Engine Certification | Unlocks EU Stage V technology licensing for Mato Grosso assembly localization. |
| After-Treatment Technician Training Programs | Addresses dealer network scarcity in rural North Dakota and Mato Grosso territories. |
| Compact-Track Rice Harvester Expansion | Targets Myanmar and Cambodian paddy terrain with Kubota-proven technical specifications. |
| Digital Twin Platform Integration | Compresses 70% of mechanical subsystem validation into silico testing before physical build. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at SLC Agrícola-scale operations, dealer network service managers in Iowa and Mato Grosso, after-treatment technician training coordinators, and OEM powertrain engineering leads. Secondary validation drew from EPA certification filings, CONAMA resolution documentation, EU Stage V type-approval records, and KBA sealed-system validation protocols. Bottom-up unit shipment modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Calibration against historical replacement cycle data and fleet telemetry adoption curves refined projection parameters. Segmentation dimensions spanned product architecture, end-user scale, technology tier, and distribution channel. CAGRs derived from regression analysis of equipment shipment volumes correlated with grain price volatility and ethanol processor capacity expansion. Industry-specific forecast inputs included diesel after-treatment cost pass-through elasticity and precision agriculture subscription renewal rates.
Practitioners should monitor OSHA autonomous harvesting regulatory developments and CONAMA resolution implementation timing for early signals of demand inflection. Forecasts reflect documented assumptions regarding emission compliance cost trajectories and telematics penetration ceilings. Macroeconomic commodity price collapse, sudden regulatory exemption reversals, or breakthrough battery-electric harvester commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
France Agricultural Machinery Market