
 North America Animal Feed Additives Market | 2026-2036
North America Animal Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Animal Feed Additives Market Analysis
Subscription-based formulation software is realigning how feed additive portfolios reach livestock producers across North America. Cargill Incorporated leverages its digital nutrition platforms to embed precision-feeding algorithms directly into customer operations. BASF SE anchors its position through backward integration into vitamin precursor chemistry, controlling raw material quality from synthesis through finished premix. DSM-Firmenich AG differentiates by sustaining one of the region's deepest R&D pipelines for next-generation eubiotics and gut health modifiers.
Animal feed additives comprise biologically active compounds—amino acids, vitamins, enzymes, and antioxidants—typically incorporated at inclusion rates between 0.01% and 1.0% of total feed mass to optimize nutrient bioavailability, growth efficiency, or animal health outcomes. These substances undergo spray-drying, microencapsulation, or granulation to survive pelleting temperatures exceeding 80°C and ensure homogeneous distribution in finished feed. Amino acids and enzymes command the largest share of product value owing to their quantifiable impact on feed conversion economics in broiler and swine operations. Liquid formulations are gaining traction among large-scale dairy and aquaculture facilities seeking automated dosing integration, while powder and pellet forms still dominate contract feed manufacturing where batch flexibility matters most.
The U.S. FDA and the Canadian Food Inspection Agency jointly shape market access through residue-monitoring protocols and approval pathways for novel feed ingredients, with the FDA's Veterinary Feed Directive having permanently altered how medicated additives move through distribution channels. State-level implementation of California's Proposition 12 housing standards and similar welfare regulations across the U.S. Northeast is redirecting additive demand toward stress-reduction and immunity-support categories rather than pure growth promotion. Stakeholders must now decide whether to build captive formulation capabilities or deepen partnerships with premix specialists as regulatory fragmentation between U.S. federal and provincial Canadian frameworks intensifies compliance complexity.
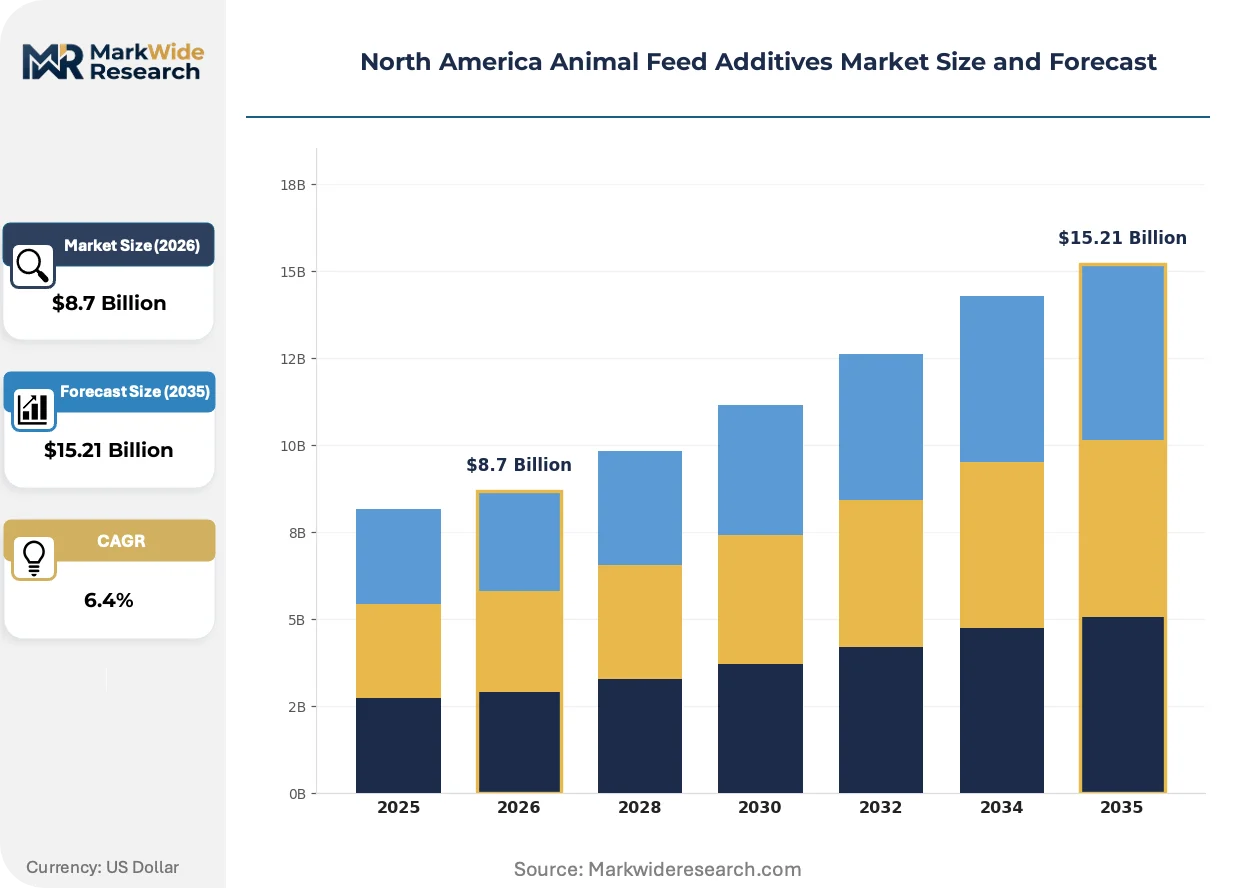
Market Dynamics
Precision-feeding algorithms embedded through subscription software platforms are restructuring how livestock producers procure and deploy additive formulations, compressing traditional distributor margins while elevating technical service expectations.
Growth Catalysts
- Veterinary Feed Directive compliance:FDA's 2017 framework permanently altered medicated additive distribution, redirecting investment toward functional alternatives like phytogenics and organic acids in U.S. swine and poultry operations.
- Midwest integrated operations:Bulk procurement from Iowa, Illinois, and Minnesota pork and dairy cooperatives is consolidating demand for customized premix solutions with embedded amino acid optimization.
- Enzyme engineering advances:Thermostable xylanase and phytase variants now survive pelleting above 85°C, enabling broader adoption across contract feed manufacturing facilities.
Market Restraints
- Vitamin precursor supply concentration:Backward integration into vitamin A and E synthesis concentrates among three chemical conglomerates, exposing formulators to raw material allocation risk.
- State-level regulatory fragmentation:California's Proposition 12 housing standards and pending Massachusetts ballot measures create incompatible additive specifications across U.S. distribution networks.
- Plant protein digestibility gaps:Exogenous enzyme supplementation cannot fully compensate for anti-nutritional factors in soybean meal and canola cake, limiting complete antibiotic replacement in certain diet formulations.
Strategic Opportunities
- Canadian prairie expansion:Alberta and Saskatchewan feedlot consolidation is outpacing local premix capacity, creating entry points for U.S. formulators with cold-chain logistics expertise.
- Eubiotic R&D pipelines:Next-generation postbiotics and quorum-sensing inhibitors targeting necrotic enteritis in broilers represent underserved therapeutic categories with premium pricing potential.
- Liquid dosing automation:Dairy operations exceeding 5,000 head in Wisconsin and New York are retrofitting mixer wagons with precision injection systems, favoring liquid enzyme and acidifier formats.
Industry Challenges
- Formulation chemist scarcity:The intersection of animal nutrition science and process engineering expertise required for microencapsulation development exceeds current North American graduate program output.
- Novel ingredient approval timelines:FDA Center for Veterinary Medicine's 18-24 month evaluation window for new feed ingredients delays commercialization of fermentation-derived proteins and algae-based omega-3 sources.
- Legacy ERP integration:Mid-scale feed mills operating 1990s-era batching software face prohibitive retrofit costs to interface with cloud-based additive ordering platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Animal Feed Additives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Antioxidants, Enzymes End User: Dairy Farms, Poultry Farms, Swine Producers, Aquaculture Form: Liquid, Pellet, Powder, Granule Application: Nutrition Enhancement, Growth Promotion, Health Improvement, Performance Optimization |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, BASF SE, DSM-Firmenich AG, Evonik Industries AG, Adisseo, Nutreco NV, Alltech, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Animal Feed Additives Market Emerging Trajectories
Biological feed additives are displacing chemotherapeutic growth promoters through converging pressures from regulatory restriction, residue testing sensitivity, and packer procurement specifications.
Microencapsulation via lipid-matrix spray chilling is overtaking traditional granulation for heat-sensitive probiotics and essential oils. Large broiler integrators in the U.S. Southeast are mandating encapsulated formats for all gut health additives by 2026. This specification is compressing commodity premix margins while rewarding suppliers with in-house encapsulation assets.
The FDA's expanded enforcement of the Veterinary Feed Directive is tightening custody documentation requirements across medicated feed distribution. Feed mills must now maintain prescription-linked batch records for seven years, elevating compliance software adoption. Smaller regional formulators in the U.S. Mountain West are consolidating or exiting rather than absorbing audit infrastructure costs.
Direct contracting between livestock cooperatives and additive manufacturers is fragmenting traditional distributor relationships. Iowa and Nebraska pork producer groups now negotiate amino acid pricing through collective purchasing agreements, bypassing regional feed dealers. This disintermediation concentrates most visibly among operations exceeding 50,000 head annual capacity.
North America Animal Feed Additives Market Segmentation
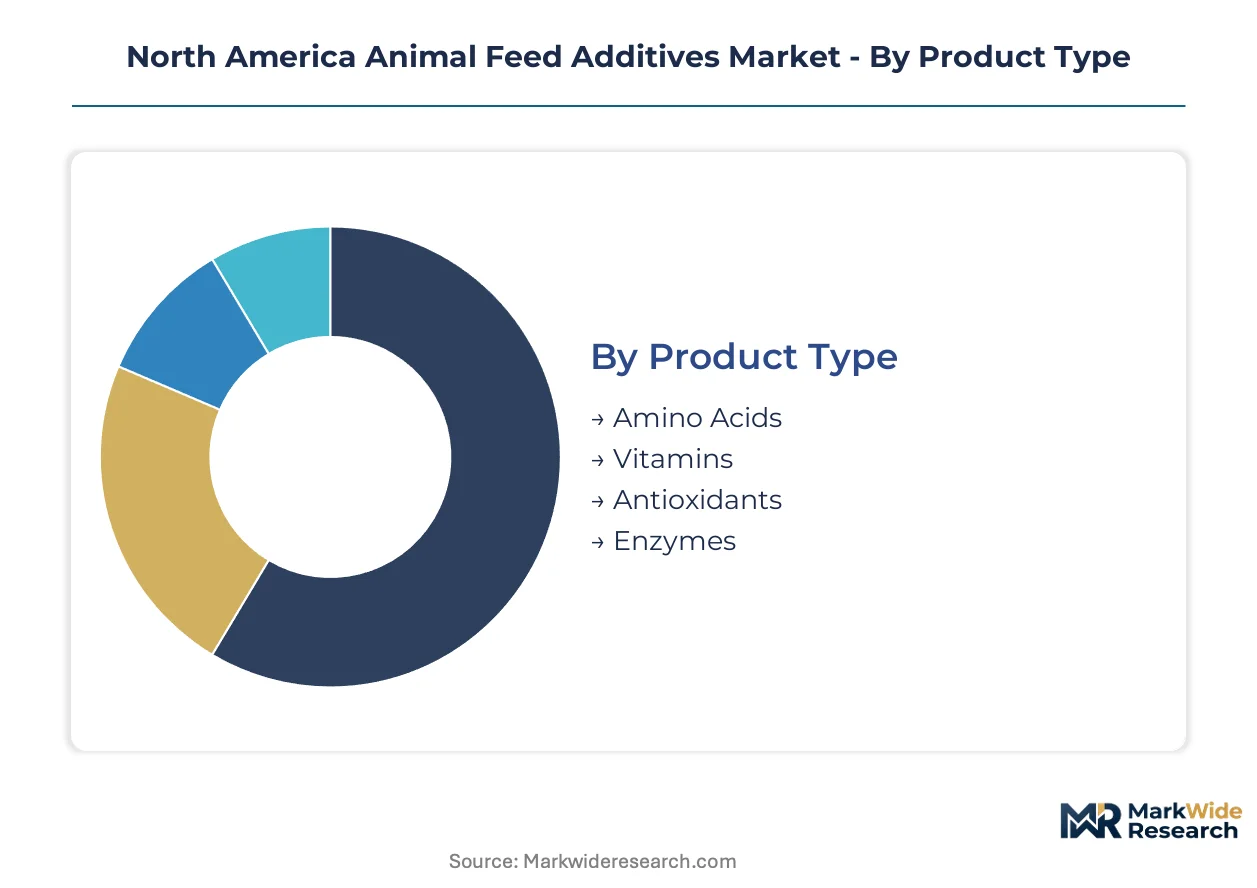
Feed additive procurement in North America diverges sharply between commodity-scale operations demanding bulk amino acid premixes and precision livestock farms seeking microencapsulated specialty actives. Understanding these fault lines reveals where formulation margins concentrate and where distributor relationships fracture.
Product Type:
Standardized commodity chemistry dominates volume flows while custom-engineered biologicals capture premium positioning across this spectrum.
- Amino Acids:Lysine, methionine, threonine, and tryptophan constitute the foundational building blocks of least-cost ration formulation software. Midwest pork integrators in Iowa and Illinois drive bulk procurement through long-term offtake agreements with synthetic lysine manufacturers.
- Enzymes:Thermostable phytase and xylanase variants now survive pelleting temperatures exceeding 85°C, unlocking broader adoption across contract feed manufacturing. Broiler operations in the U.S. Southeast mandate these for improved phosphorus release and reduced environmental loading.
- Vitamins:Fat-soluble and water-soluble micronutrients require stabilization against oxidation during feed storage.
- Antioxidants:Synthetic phenolic compounds and natural tocopherol blends protect lipid fractions in high-fat dairy rations.
Most installed capacity flows through Amino Acids. Expansion is steepest in Enzymes.
End User:
Scale thresholds and automation readiness separate facilities that buy commodity premixes from those demanding precision-dosed liquid systems.
- Poultry Farms:Vertically integrated broiler and layer operations from Georgia to Arkansas deploy enzyme and amino acid blends through automated feed mills with real-time formulation adjustment. Feed conversion ratio economics dominate procurement criteria.
- Dairy Farms:Operations exceeding 5,000 head in Wisconsin and New York retrofit mixer wagons with precision injection systems for liquid acidifiers and rumen-protected amino acids. Herd management software integration drives additive selection.
- Swine Producers:Iowa and Minnesota cooperatives consolidate demand for customized premix solutions with embedded gut health modifiers.
- Aquaculture:Pacific Northwest and Atlantic Canada salmonid operations favor astaxanthin and omega-3 enrichment for flesh pigmentation and fillet quality.
Volume concentrates in Poultry Farms. Technology upgrade cycles run fastest through Dairy Farms.
Form:
Heat stability requirements and dosing infrastructure determine whether producers accept powder trade-offs or invest in liquid handling systems.
- Powder:Spray-dried and standard-grind formats dominate contract feed manufacturing where batch flexibility and rapid product changeover matter most. Mid-scale mills across the U.S. Mountain West rely on powder for multi-species formulation.
- Liquid:Automated dosing integration favors large-scale dairy and aquaculture facilities seeking precise inclusion control and reduced dust exposure. Wisconsin and New York operations lead retrofit adoption.
- Pellet:Extruded carriers protect actives during pelleting but require compatible binder systems.
- Granule:Intermediate sizing reduces segregation in bulk handling systems.
Current throughput peaks in Powder. Infrastructure investment tilts toward Liquid.
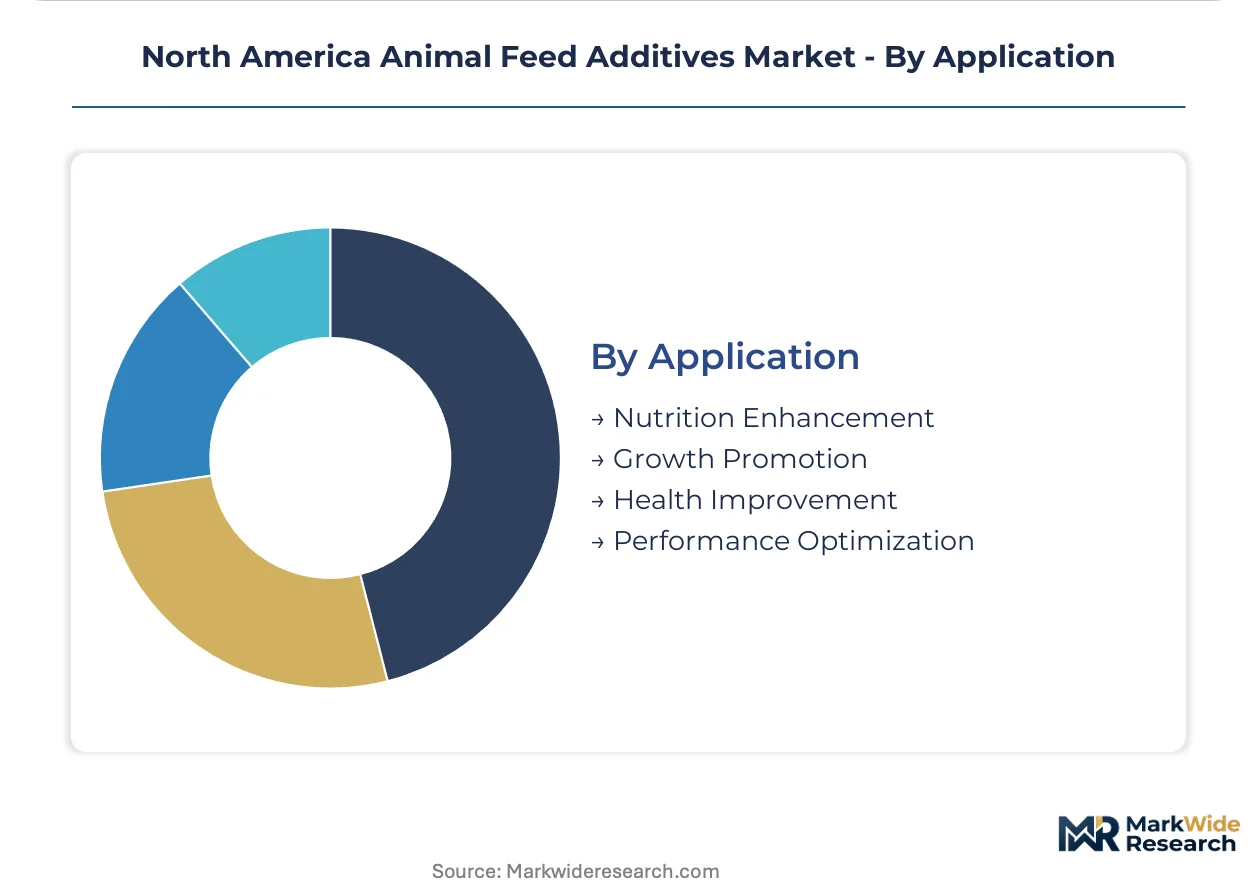
Application:
Regulatory pressure on growth promotion has collapsed that category while redistributing value toward health-focused and performance-optimizing functions.
- Nutrition Enhancement:Amino acid balancing and vitamin fortification address digestibility gaps in plant protein diets. Soybean meal and canola cake anti-nutritional factors drive exogenous enzyme supplementation across U.S. swine operations.
- Health Improvement:Postbiotics, organic acids, and phytogenics target necrotic enteritis in broilers and subclinical mastitis reduction in dairy herds. California Proposition 12 housing stress protocols accelerate immunity-support category demand.
- Growth Promotion:FDA Veterinary Feed Directive restrictions have permanently shifted this category toward non-antibiotic alternatives.
- Performance Optimization:Feed conversion efficiency and carcass yield metrics guide additive selection in integrated pork and poultry systems.
Established demand centers on Nutrition Enhancement. Policy tailwinds favor Health Improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater additive volume than Canada, though Canadian prairie feedlot consolidation is accelerating faster than local supply capacity can match. Mexico's livestock sector is expanding enzyme adoption in poultry-dense regions, creating a three-speed North American landscape.
United States
Midwest integrated pork and dairy operations in Iowa, Illinois, and Minnesota consolidate demand for customized premix solutions with embedded amino acid optimization. The FDA's Veterinary Feed Directive permanently altered medicated additive distribution, redirecting investment toward functional alternatives. Large broiler integrators across Georgia and Arkansas now mandate microencapsulated gut health additives by 2026.
Canada
Alberta and Saskatchewan feedlot consolidation is outpacing local premix capacity, creating entry points for U.S. formulators with cold-chain logistics expertise. Health Canada and the Canadian Food Inspection Agency jointly shape market access through residue-monitoring protocols for novel feed ingredients. Atlantic Canada salmonid operations favor astaxanthin and omega-3 enrichment for flesh pigmentation and fillet quality.
Mexico
Poultry farms across central Mexico are expanding amino acid and enzyme blends to improve feed conversion ratios in broiler operations. The country's national agricultural regulator enforces import documentation for vitamin premixes crossing from U.S. border states. Guanajuato and Querétaro industrial corridors host expanding contract feed manufacturing facilities serving domestic protein demand.
North America Animal Feed Additives Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition platforms capturing premium positioning in precision-feeding software while regional premix houses defend commodity amino acid volumes. The vendor base concentrates among three strategic archetypes: backward-integrated chemical conglomerates controlling vitamin precursor synthesis, digital-nutrition platforms embedding algorithms directly into customer operations, and R&D-intensive specialists sustaining deep pipelines for next-generation biologicals. Capacity expansion and strategic partnerships dominate competitive moves, as players decide between building captive formulation capabilities or deepening ties with premix specialists.
Within the backward-integrated tier, BASF SE and DSM-Firmenich AG exemplify how chemical synthesis heritage translates into raw material quality control from precursor through finished premix. Cargill Incorporated anchors the digital-nutrition archetype, leveraging subscription-based formulation software to embed precision-feeding algorithms directly into livestock producer operations. These three entities occupy positions that concentrate formulation margins while compressing traditional distributor relationships across the Midwest and Southeast.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| BASF SE |
| DSM-Firmenich AG |
| Evonik Industries AG |
| Adisseo |
| Nutreco NV |
| Alltech |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Formulation chemist scarcity in the U.S. Midwest and Canadian prairie provinces widens labor-cost differentials that translate directly into pricing-tier spreads across customized premix solutions.
Pricing Analysis
Capacity additions in Iowa and Illinois are reshaping price floors for commodity amino acid premixes even as encapsulated specialty actives command sustained premiums. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated gut health modifiers from standard-grind vitamin blends and bulk synthetic lysine. Price differentiation rests on certification grade for FDA Veterinary Feed Directive compliance and volume scale in cooperative procurement agreements. Cost compression in standard amino acids is intensifying because direct contracting between livestock cooperatives and manufacturers bypasses traditional distributor markups. Iowa pork producer groups exceeding 50,000 head annual capacity demonstrate least price sensitivity, while mid-scale feed mills across the U.S. Mountain West face acute margin pressure.
Supply Chain Analysis
Return flows of expired vitamin premixes and off-specification enzyme lots from dairy operations in Wisconsin and New York feed into refurbishment channels for animal nutrition applications. Raw material supply concentrates in China for synthetic lysine precursors, Germany for vitamin A and E synthesis intermediates, and the Netherlands for fermentation-derived enzyme cultures. The North American feed additive supply chain draws from soybean meal processing co-products across the U.S. Midwest and canola cake from Canadian prairie crush facilities. Single-source vulnerability in vitamin precursor synthesis among three chemical conglomerates exposes formulators to raw material allocation risk. Distribution runs through integrated nutrition platforms embedding precision-feeding algorithms directly into livestock producer operations, compressing traditional regional feed dealer margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Animal Feed Additives Market functions as a geographic-arbitrage play: Alberta and Saskatchewan feedlot consolidation outpaces local premix capacity, while FDA compliance costs in the U.S. elevate entry barriers that Canadian operations partially circumvent through Health Canada equivalency pathways.
For Market Incumbents: Extend backward integration into vitamin precursor chemistry to secure raw material quality control from synthesis through finished premix, insulating against allocation risk from concentrated suppliers. Deepen cloud-based formulation software penetration among Midwest pork integrators to embed switching costs before regional premix houses consolidate. The threat of direct cooperative contracting fragments traditional distributor relationships and compresses margin capture in commodity amino acids. For New Entrants and Emerging Players: Precision liquid dosing automation for dairy operations exceeding 5,000 head offers the most penetrable wedge in Wisconsin and New York, where retrofit demand for mixer wagon injection systems outstrips incumbent service capacity. Target Alberta and Saskatchewan feedlot consolidation with cold-chain logistics expertise, as local premix capacity lags behind demand growth. A go-to-market angle anchored in subscription-based formulation software with embedded amino acid optimization algorithms bypasses capital-intensive manufacturing assets. For Investors and Strategic Acquirers: Chemical conglomerates with captive vitamin synthesis assets are the most active acquirer in this space, seeking to extend downstream into formulated premix capabilities. Long-term viability favors targets with in-house microencapsulation assets and FDA Center for Veterinary Medicine approval track records for novel feed ingredients. The signal to watch is FDA enforcement intensity around Veterinary Feed Directive custody documentation requirements, which accelerates consolidation among smaller regional formulators unable to absorb audit infrastructure costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Precursor Synthesis | BASF SE and DSM-Firmenich AG control raw material quality from chemical synthesis through finished premix. |
| Cloud-Based Formulation Software Deployment | Cargill Incorporated embeds precision-feeding algorithms directly into Iowa and Illinois livestock producer operations. |
| Microencapsulation Asset Expansion | Large broiler integrators in Georgia and Arkansas mandate encapsulated gut health additives by 2026. |
| Cold-Chain Logistics Network Buildout | U.S. formulators capture Alberta and Saskatchewan feedlot demand outpacing local premix capacity. |
| Novel Ingredient Regulatory Approval Investment | FDA Center for Veterinary Medicine evaluation windows delay commercialization of fermentation-derived proteins. |
Methodological Framework
Bottom-up livestock operation modeling reconciled against top-down additive manufacturing capacity tracking forms the analytical core of this study. Primary interviews with feed mill plant managers, livestock cooperative procurement leads, premix formulation chemists, and FDA regulatory affairs specialists combined with secondary validation from USDA National Agricultural Statistics Service data, FDA Veterinary Feed Directive enforcement records, Canadian Food Inspection Agency residue-monitoring protocols, and SEC 10-K filings from publicly traded chemical conglomerates. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production disclosures.
Input-output matrices map amino acid, enzyme, vitamin, and antioxidant flows across poultry, dairy, swine, and aquaculture end-uses, with segmentation dimensions spanning product type, end user, form, and application function. CAGRs derive from regression analysis against historical feed conversion ratio improvements, regulatory shift timelines, and technology adoption curves in precision-feeding software deployment. Industry-specific forecast inputs include thermostable enzyme engineering advances and state-level regulatory fragmentation around housing welfare standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA novel ingredient approval timelines, vitamin precursor supply concentration disruptions, and cooperative procurement consolidation patterns. Practitioners should monitor FDA Veterinary Feed Directive enforcement intensity, Alberta feedlot capacity expansion rates, and encapsulated additive specification mandates from large broiler integrators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market