
 Global Inoculants Market | 2026-2036
Global Inoculants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inoculants Market Outlook
Market Context
Precision fermentation and cell-culture stabilization is reconfiguring how live microbial inoculants are manufactured, scaled, and delivered to farm gate. BASF SE leverages integrated strain development pipelines from industrial biotechnology platforms to sustain cost leadership in high-volume soybean markets. Novozymes A/S anchors its position through specialized enzyme-inoculant combinations that differentiate performance in drought-stressed soils. Bayer AG competes by controlling distribution networks across North American corn belts, extending technical advisory services directly to agronomists.
Technical Definition and Segment Structure
Inoculants are live microbial preparations, typically containing rhizobia, azospirillum, or phosphate-solubilizing bacteria at colony-forming unit concentrations exceeding 10^9 CFU per gram, applied to seeds or soil to enhance nutrient acquisition and plant metabolic function. Liquid inoculants dominate volume due to ease of tank-mixing with seed treatment chemistry, though granular formulations command margin premiums in no-till systems where seed-applied products face placement constraints. Microbial formulations lead absolute sales across the analysis window while organic-certified variants capture the fastest expansion as export-oriented growers in Brazil and Argentina face EU residue protocol compliance.
Regulatory Environment and Outlook
The EPA governs microbial pesticide registration under FIFRA in the United States, while Brazil's national biosafety regulator, CTNBio, evaluates transgenic and novel strain releases under Law 11.105. REACH and the EU Fertilizing Products Regulation now mandate full strain characterization and ecotoxicological dossiers for market entry, elevating compliance costs for smaller suppliers. Stakeholders must monitor how divergent national biosecurity frameworks reshape strain patent strategies and cross-border licensing terms.
Market Dynamics
Biological nitrogen fixation is displacing synthetic fertilizer dependency across major soybean belts, driven by EU Green Deal residue protocols and Brazilian distributor bundling strategies that embed microbial formulations into precision planting services.
Growth Catalysts
- EU Fertilizing Products Regulation:Mandatory strain characterization dossiers redirect procurement toward certified microbial suppliers, accelerating organic-certified formulation adoption among export-oriented growers.
- Precision fermentation:Industrial biotechnology platforms cut manufacturing costs for live microbial stabilisation, enabling cost-competitive rhizobial products at farm gate.
- Brazil's Cerrado belt:Input distributors bundle inoculants with seed treatment and planting services, creating embedded demand channels that lock in grower loyalty.
Market Restraints
- Strain patent fragmentation:Divergent national biosecurity frameworks complicate cross-border licensing, elevating compliance costs for multi-territory suppliers.
- CTNBio evaluation timelines:Brazil's biosafety regulator imposes extended review periods for novel strain releases, delaying product commercialisation by 18-24 months.
- Phosphate-solubilising bacteria substitution:Rock phosphate mining cost volatility creates intermittent price advantages for conventional fertiliser, eroding microbial value propositions in low-margin seasons.
Strategic Opportunities
- Argentina's Pampas region:Underpenetrated no-till systems present granular formulation demand as growers face placement constraints with liquid seed-applied products.
- Enzyme-inoculant convergence:Drought-stressed soil performance bundles create differentiation premiums in water-scarce production zones.
- US IRA conservation incentives:Biological input tax credits under the Inflation Reduction Act redirect corn belt procurement toward nitrogen-fixing microbial alternatives.
Industry Challenges
- Cell-culture stabilisation expertise:Live microbial viability maintenance requires specialised fermentation technologists, creating talent scarcity in manufacturing hubs.
- REACH ecotoxicological dossiers:Full strain characterization mandates compress certification timelines, forcing smaller suppliers to outsource regulatory compliance.
- Tank-mix compatibility validation:Seed treatment chemistry interactions demand extensive field testing, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inoculants Market |
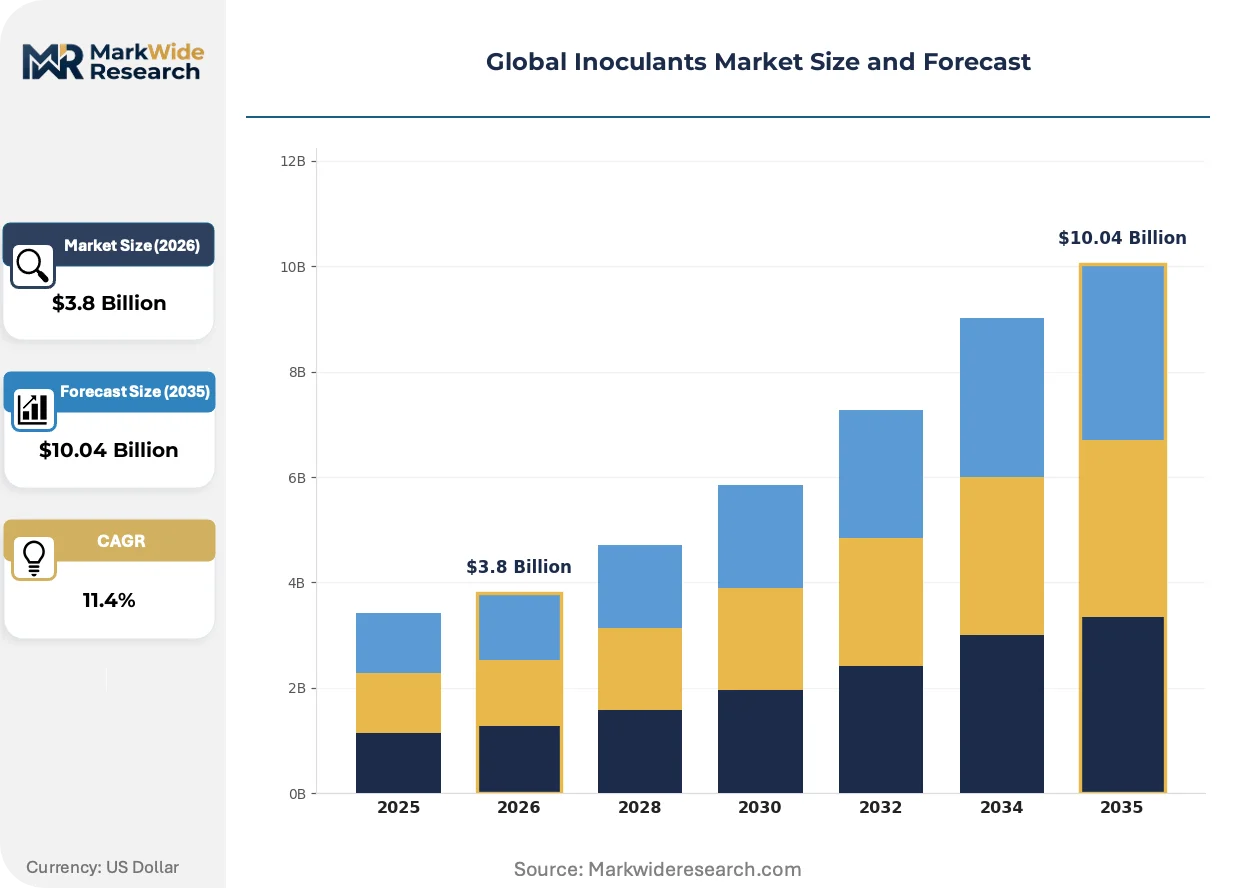
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Inoculants, Dry Inoculants, Granular Inoculants, Pelleted Inoculants Application: Agriculture, Horticulture, Forestry, Aquaculture Formulation: Microbial, Chemical, Organic, Synthetic Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Bayer AG, Novozymes A/S, Corteva, Inc., Syngenta Group Co., Ltd., Verdesian Life Sciences, Advanced Biological Marketing Inc., Rizobacter, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inoculants Market Strategic Shifts
Precision fermentation infrastructure and regulatory chemistry mandates are compressing traditional manufacturing and distribution models, embedding biological inputs deeper into agronomic service bundles.
Lyophilised cell-culture stabilisation preserves rhizobial viability at ambient temperatures, eliminating cold-chain dependency. Brazilian distributors adopt shelf-stable formulations for remote Cerrado farm belts. Ambient storage is rendering obsolete refrigerated logistics networks that previously constrained market access.
REACH and the EU Fertilizing Products Regulation now mandate complete strain genome sequencing and ecotoxicological profiling. Compliance costs filter marginal suppliers from European markets. Organic-certified variants capture fastest expansion as residue protocol adherence becomes non-negotiable for export eligibility.
Outcome-based agronomic advisory bundles displace standalone product sales. North American corn belt buyers demand guaranteed nitrogen-fixation performance metrics, not colony-forming unit counts. Distributor agronomists in Mato Grosso now price inoculants per hectare of biological nitrogen delivered, shifting risk from grower to supplier.
Global Inoculants Market Segmentation
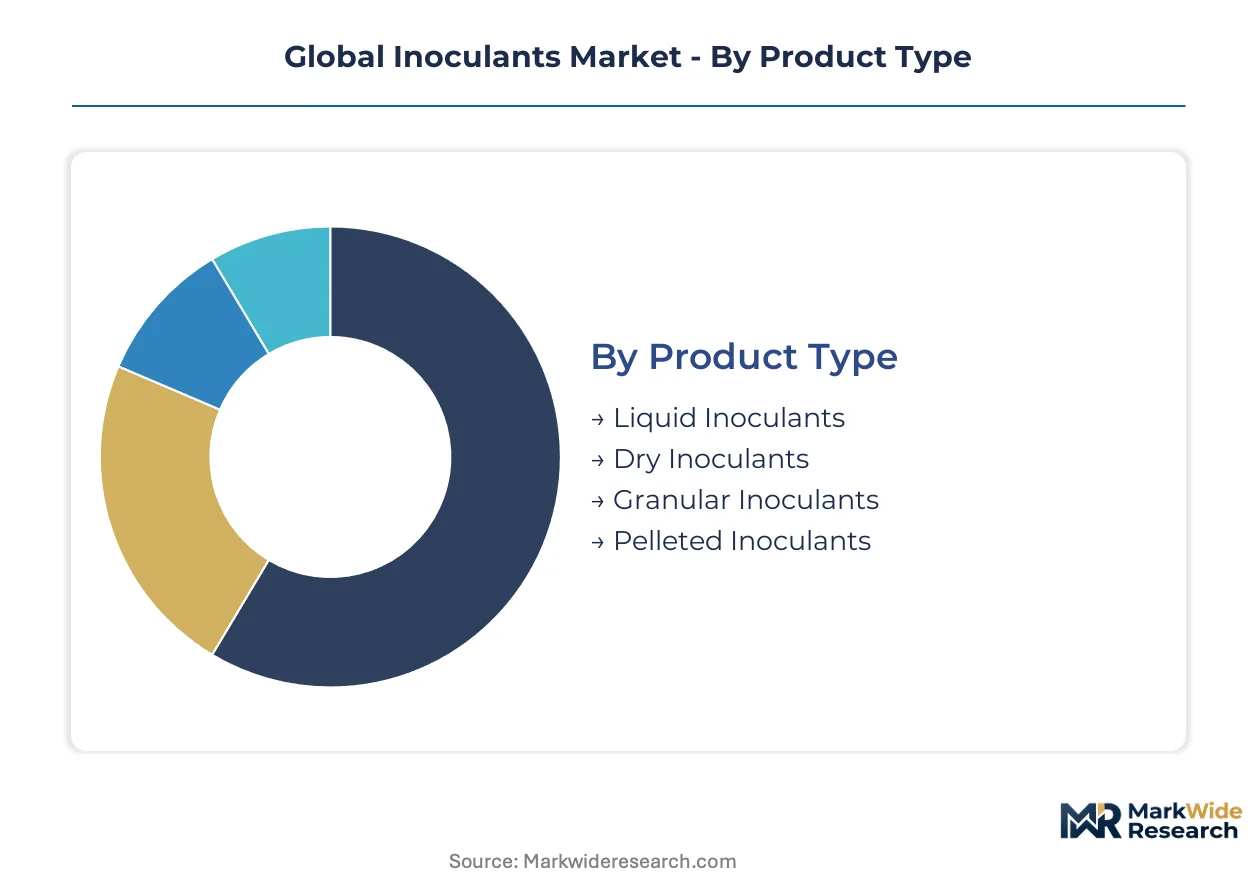
Inoculants exhibit distinct performance profiles across physical forms and delivery channels. Segmentation reveals where manufacturing scale, regulatory compliance, and agronomic service bundling concentrate commercial value.
Product Type:
Mature liquid formulations dominate high-volume soybean belts while emerging solid-state technologies address no-till placement constraints.
- Liquid Inoculants:Aqueous suspensions of rhizobia or azospirillum at 10^9 CFU per milliliter enable seamless tank-mixing with seed treatment chemistry. Brazilian distributors in Mato Grosso bundle liquid formulations with precision planting services, locking in grower loyalty through embedded delivery channels.
- Dry Inoculants:Lyophilized powder preparations achieve ambient temperature stability, eliminating cold-chain dependency for remote Cerrado farm belts. Shelf-stable dry formats expand market access beyond refrigerated logistics networks.
- Granular Inoculants:Clay-based carriers position microbes in the root zone independent of seed placement.
- Pelleted Inoculants:Compressed matrix formulations suit specialty horticulture applications requiring metered dosing.
Liquid inoculants handle the majority of throughput; dry inoculants are the fastest mover on share.
Application:
Cost tiers separate commodity row-crop deployment from premium horticultural and specialty segments.
- Agriculture:Large-scale soybean, corn, and wheat production drives absolute volume, with biological nitrogen fixation displacing synthetic fertilizer across Brazil, Argentina, and the United States.
- Horticulture:High-value vegetable and fruit systems command formulation premiums for phosphate-solubilizing and plant-growth-promoting rhizobacteria.
- Forestry:Eucalyptus and pine plantation nurseries in Brazil adopt mycorrhizal inoculants for establishment-phase root colonization.
- Aquaculture:Probiotic water treatment formulations for shrimp and finfish ponds represent an emerging application with distinct regulatory pathways.
Agriculture commands the dominant share of volume; aquaculture is expanding most quickly as producers seek antibiotic alternatives.
Formulation:
Customer type bifurcates between certified organic export growers and conventional commodity producers.
- Microbial:Live bacterial and fungal preparations containing rhizobia, azospirillum, or phosphate-solubilizing organisms at standardized CFU concentrations.
- Chemical:Synthetic additive combinations that enhance microbial survival or nutrient chelation.
- Organic:Certified-compliant live cultures meeting EU Fertilizing Products Regulation and USDA National Organic Program standards for residue protocol adherence.
- Synthetic:Laboratory-cultured strain variants with targeted metabolic pathway engineering.
Microbial formulations anchor the installed base; organic-certified variants are gaining share fastest under tightening EU import requirements.
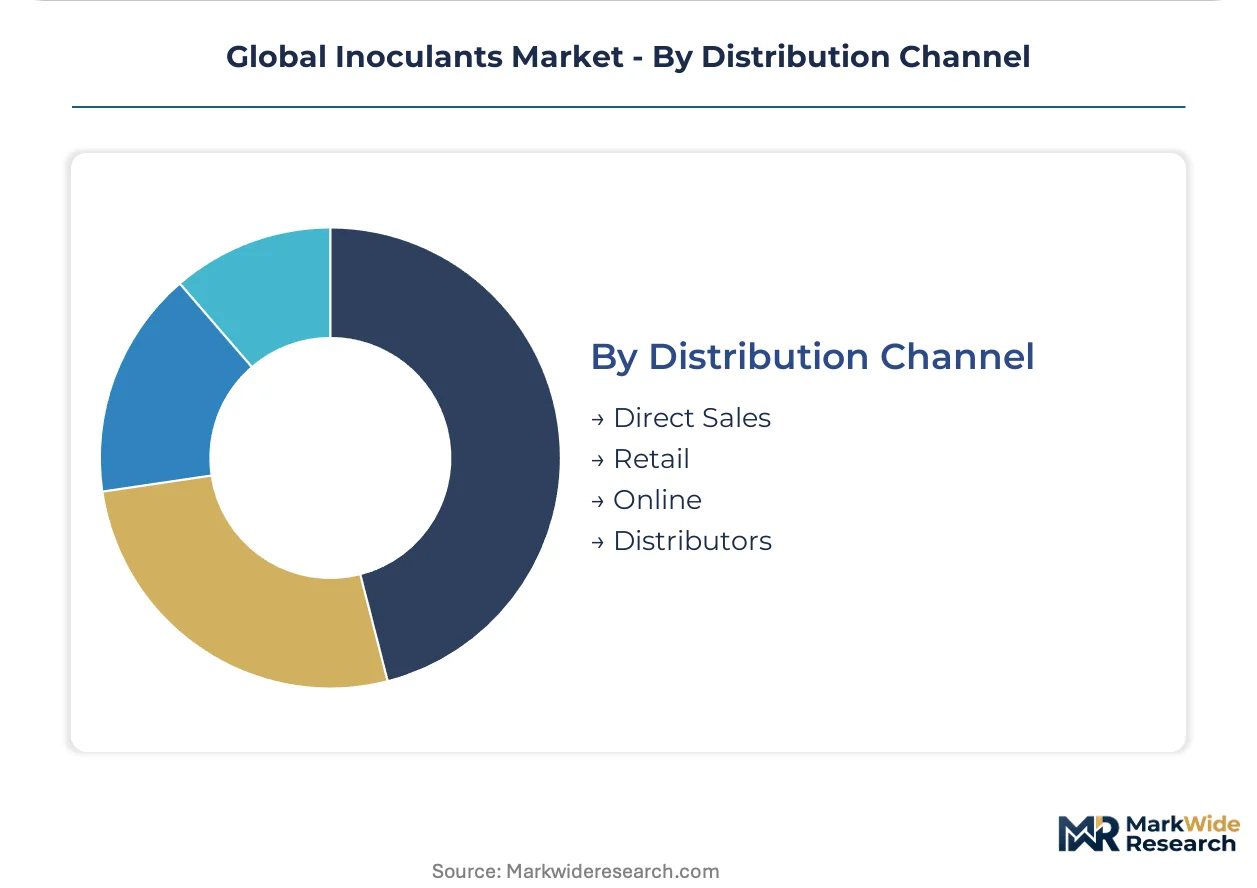
Distribution Channel:
Supply concentration favors integrated distributor networks over fragmented retail and direct models.
- Direct Sales:Manufacturer agronomists deliver technical advisory and performance guarantees to large-scale farming cooperatives.
- Retail:Farm supply stores serve smallholder and mid-scale producers with standardized off-the-shelf formulations.
- Online:E-commerce platforms enable remote procurement for specialty and organic-certified products with complex specification requirements.
- Distributors:Input bundlers in Brazil's Cerrado embed inoculants within precision planting and seed treatment service packages.
Distributors handle the majority of throughput; direct sales are climbing the fastest as outcome-based agronomic advisory displaces standalone product transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports inoculant-treated soybeans to European Union buyers facing strict EU Green Deal residue protocols, creating a compliance-driven trade corridor that reshapes procurement patterns across South American farm belts.
Brazil
Soybean expansion in Mato Grosso and the Cerrado drives rhizobial inoculant consumption as farmers substitute biological nitrogen fixation for synthetic fertilizers. CTNBio regulates novel strain releases under Law 11.105, imposing extended review timelines that delay commercialization. Input distributors in Rondonópolis now bundle inoculants with precision planting equipment, embedding microbial products into agronomic service packages.
United States
Corn belt growers redirect procurement toward nitrogen-fixing alternatives under Inflation Reduction Act conservation incentives. The EPA governs microbial pesticide registration through FIFRA, requiring extensive ecotoxicological dossiers for market entry. Agronomists in Iowa and Illinois demand outcome-based performance guarantees rather than colony-forming unit specifications, shifting commercial risk from growers to suppliers.
Argentina
No-till soybean systems in the Pampas region generate demand for granular formulations where liquid seed-applied products face placement constraints. The national agricultural technology institute evaluates strain efficacy for regional soil conditions. Rosario-based cooperatives are expanding procurement of shelf-stable dry inoculants to eliminate cold-chain dependency for remote farm belts.
Germany
Industrial biotechnology platforms in Baden-Württemberg and North Rhine-Westphalia supply precision fermentation infrastructure for live microbial stabilization. REACH mandates full strain characterization and genome sequencing, elevating compliance costs that filter marginal suppliers from European markets. BASF SE leverages integrated strain development pipelines from Ludwigshafen to sustain cost leadership in high-volume segments.
India
Pulse cultivation in Maharashtra and Madhya Pradesh creates demand for rhizobial formulations compatible with smallholder procurement patterns. The Food Safety and Standards Authority of India regulates microbial additive safety for agricultural applications. Input retailers in Nashik are expanding distribution of affordable liquid inoculants through regional cooperative networks serving rain-fed production zones.
Global Inoculants Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent distribution architectures. The vendor base separates into integrated agrochemical conglomerates with captive distribution networks and dedicated microbial technology firms with technical advisory capabilities. Two strategic archetypes dominate: fermentation-scale leaders optimizing manufacturing cost curves, and formulation specialists commanding performance premiums in stress-condition applications. Competitive moves concentrate on backward integration into strain development pipelines and geographic licensing partnerships that navigate fragmented national biosecurity frameworks.
Among integrated agrochemical conglomerates, BASF SE and Bayer AG occupy positions anchored by industrial biotechnology platforms and controlled distribution networks across major soybean and corn belts. Novozymes A/S exemplifies the enzyme-inoculant convergence archetype, representing specialists who differentiate through drought-stressed soil performance bundles. These three companies illustrate how competitive positioning separates scale-driven manufacturing leaders from technical differentiation specialists in microbial agricultural inputs.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Novozymes A/S |
| Corteva, Inc. |
| Syngenta Group Co., Ltd. |
| Verdesian Life Sciences |
| Advanced Biological Marketing Inc. |
| Rizobacter |
| Lallemand Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Brazilian fermentation facilities is compressing liquid inoculant margins while simultaneously accelerating supplier consolidation and tiered pricing stratification across export-oriented markets.
Pricing Analysis
Next-generation lyophilized dry formulations command 40-60% premiums over conventional liquid suspensions, while legacy refrigerated products face accelerated price erosion. Pricing stratifies across premium, standard, and economy tiers based on strain certification tier under EU Fertilizing Products Regulation and volume scale of distributor bundling agreements. Cost compression in standard-grade liquid formulations is intensifying because precision fermentation infrastructure is lowering manufacturing thresholds for regional suppliers. Smallholder cooperatives in India's rain-fed zones exhibit highest price sensitivity, while EU-facing export growers in Brazil's Mato Grosso demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Tariff exposure between Brazil and European Union markets dominates supply chain risk calculations for rhizobial strain suppliers navigating residue protocol compliance. Manufacturing gravity centers on Brazil, Germany, and the United States, with strain development pipelines anchored in Baden-Württemberg biotechnology clusters and Mato Grosso distributor networks. Live culture production rests on specific fermentation feedstocks, specialized cold-chain logistics for non-lyophilized products, and CTNBio-certified strain repositories. Single-source vulnerability concentrates in Brazilian distributor bundling channels that lock in grower loyalty through embedded service packages. Distribution runs through integrated input bundlers in South American soybean belts, direct manufacturer agronomist relationships in North American corn belts, and regional cooperative networks serving Indian pulse cultivation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against synthetic fertilizer substitution as rock phosphate price volatility intermittently erodes microbial value propositions in low-margin production seasons.
For Market Incumbents: Insulate market position by deepening backward integration into strain development pipelines and securing CTNBio pre-approval for novel rhizobial variants before competitors complete review timelines. Prioritize certification investment under REACH and EU Fertilizing Products Regulation to filter marginal suppliers from European procurement channels. For New Entrants and Emerging Players: Argentina's Pampas region presents underpenetrated no-till acreage where granular formulation demand outstrips liquid product placement capabilities. Target drought-stressed soil performance bundles as the most penetrable application segment, deploying enzyme-inoculant convergence technologies through Rosario-based cooperative partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as industrial biotechnology platforms achieve manufacturing scale. Long-term viability favors acquisition targets with captive strain libraries and distributor bundling relationships in Brazil's Cerrado belt. Watch for CTNBio approval velocity as the signal indicating competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Patent Portfolio Expansion | CTNBio and REACH dossier preparation secures multi-territory market access against fragmented biosecurity frameworks. |
| Precision Fermentation Scale-Up | Industrial biotechnology infrastructure in Baden-Württemberg cuts unit costs for ambient-stable live microbial products. |
| Distributor Bundling Partnerships | Embedded service packages in Mato Grosso and Rondonópolis lock in grower loyalty through outcome-based pricing. |
| Organic Certification Investment | EU Fertilizing Products Regulation compliance opens export-oriented Brazilian and Argentine farm belt procurement. |
| Enzyme-Inoculant Convergence R&D | Drought-stressed soil performance bundles command differentiation premiums in water-scarce Cerrado production zones. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with strain development scientists at industrial biotechnology platforms, regulatory affairs leads navigating CTNBio and EPA FIFRA pathways, distributor agronomists bundling inoculants with precision planting services, and procurement managers at large-scale farming cooperatives in Brazil and Argentina. Secondary validation drew from CTNBio strain approval databases, EPA microbial pesticide registrations, EU Fertilizing Products Regulation certification listings, and customs trade data for inoculant-treated soybean exports. Bottom-up volume modeling triangulated against top-down market sizing across fermentation capacity disclosures and distributor revenue proxies.
Calibration against historical strain adoption curves and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include physical formulation type, application crop, certification tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration rates for biological nitrogen fixation versus synthetic fertilizer substitution. Industry-specific forecast inputs incorporated CTNBio review timeline distributions and EU Green Deal residue protocol implementation phasing.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, rock phosphate mining cost volatility, or EU import tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding strain viability maintenance, distributor bundling penetration, and regulatory harmonization progress. Material shifts in CTNBio approval velocity or REACH dossier requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Feed Prebiotics Market