
 Synthetic Pesticide Market | 2026-2036
Synthetic Pesticide Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Pesticide Market Analysis
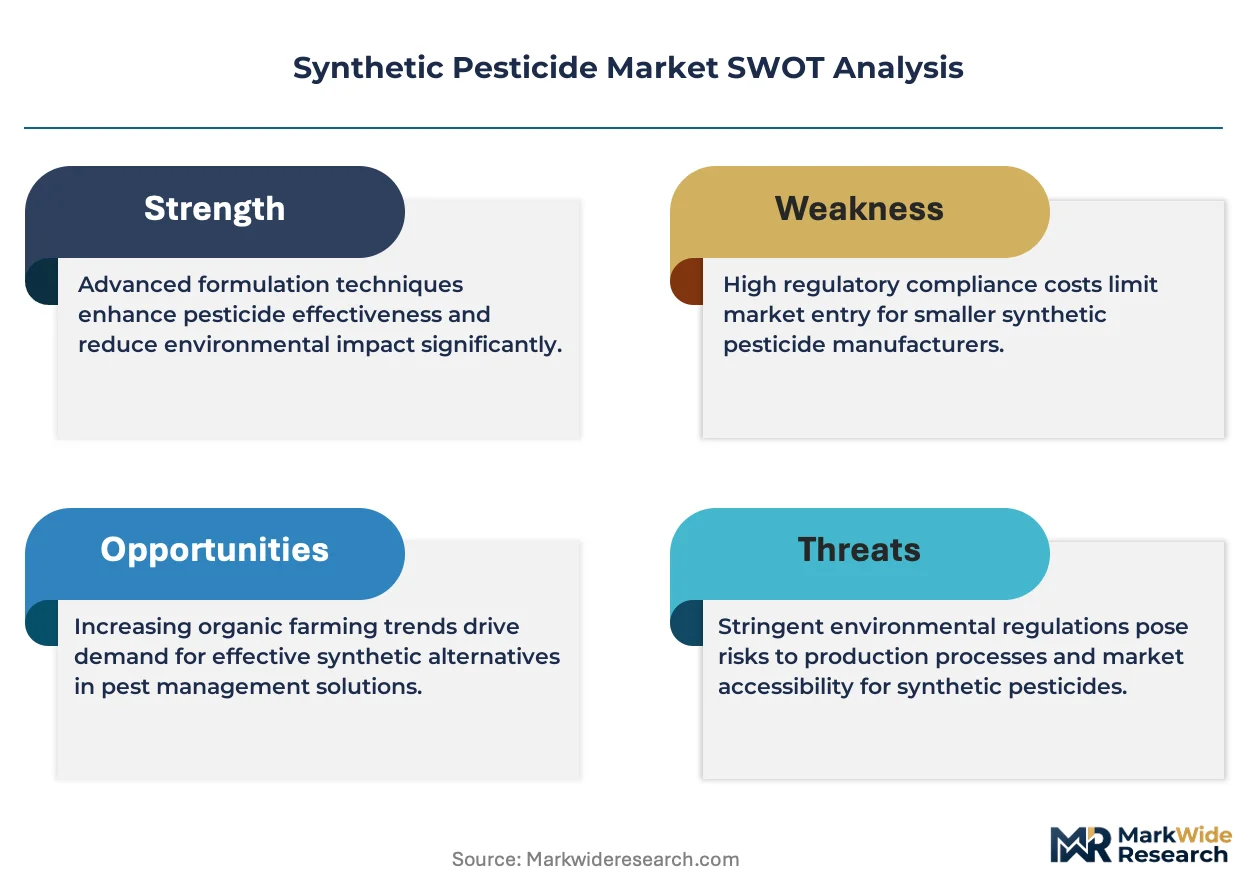
A capital-intensity divergence between integrated multinationals and asset-light generics is reorganizing competitive tiers in synthetic pesticides. Bayer AG leverages its seed-chemistry integration to sustain premium positioning across glyphosate-tolerant systems. UPL Limited anchors its portfolio in post-patent molecules and competes aggressively on cost in emerging markets.
Synthetic pesticides are chemically formulated biocidal agents designed to disrupt pest physiology through neurotoxic, hormonal, or metabolic pathways, typically manufactured via multi-step organic synthesis with active ingredient concentrations ranging from 15% to 95% in commercial formulations. These compounds serve primarily to protect yield and quality in commercial agriculture, public health vector control, and structural pest management. Herbicides command the largest revenue pool given their deployment across row-crop monocultures, while neonicotinoid chemistry faces structural contraction under pollinator-risk assessments. Liquid formulations dominate volume throughput due to ease of tank-mixing and aerial application compatibility, though granule demand is strengthening in rice-paddy systems where drift control matters.
The EPA re-evaluates organophosphate tolerances under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU Green Deal accelerates active-substance withdrawals under hazard-based cut-off criteria. India's Central Insecticides Board mandates dual-label warnings in 22 official languages, tightening market access for imported formulations. Stakeholders must monitor regulatory divergence between residue-tolerance jurisdictions and biopesticide substitution mandates to calibrate portfolio allocation and registration investment.
Market Dynamics
The EU Green Deal's hazard-based cut-off criteria for active substance approvals is forcing a structural portfolio recomposition among synthetic pesticide manufacturers, compressing legacy chemistry pipelines while accelerating reformulation investments toward reduced-risk profiles.
Growth Catalysts
- Herbicide-tolerant trait adoption:Specialty crop producers in Brazil are expanding herbicide programs to manage glyphosate-resistant weed populations, driving volume demand for diversified mode-of-action chemistries.
- Smallholder consolidation:India's wheat-rice belt is experiencing accelerated consolidation among smallholder farms, creating addressable demand for packaged crop protection solutions at scale.
- Residue limit harmonization pressures:The EU Green Deal's Farm to Fork strategy is tightening maximum residue limits, compelling export-oriented growers in multiple jurisdictions to upgrade to compliant formulations.
Market Restraints
- Active ingredient cost volatility:Petrochemical feedstock price swings directly compress formulation margins, particularly for organophosphate and pyrethroid chemistries with complex synthesis pathways.
- Regulatory withdrawal cascades:The EU's hazard-based cut-off criteria under Regulation 1107/2009 is systematically removing neonicotinoid and organophosphate registrations, eliminating revenue pools without immediate substitute availability.
- Biopesticide substitution threat:Microbial and biochemical alternatives are capturing share in specialty crop segments where residue sensitivity and pollinator proximity elevate their relative value proposition.
Strategic Opportunities
- Rice-paddy formulation innovation:Granule and controlled-release formats for flooded cultivation systems offer drift-control advantages that liquid formulations cannot match, with Southeast Asian markets showing particular receptivity.
- India's multilingual label mandate:The Central Insecticides Board's dual-label requirement in 22 official languages creates a compliance barrier that favorably positions domestic formulators with established regulatory infrastructure.
- Precision application convergence:Integration of drone-based variable-rate application with sensor-guided pest detection is opening demand for ultra-low-volume formulations compatible with electrostatic and rotary atomization systems.
Industry Challenges
- Regulatory submission capacity constraints:The volume of data requirements for new active substance dossiers under EU 1107/2009 and EPA FIFRA re-evaluations exceeds the available toxicology and environmental fate study capacity at contracted laboratories.
- Formulation chemist scarcity:Specialized expertise in surfactant-solvent compatibility for tank-mix systems and controlled-release polymer matrices is concentrating at a shrinking number of research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Pesticide Market |
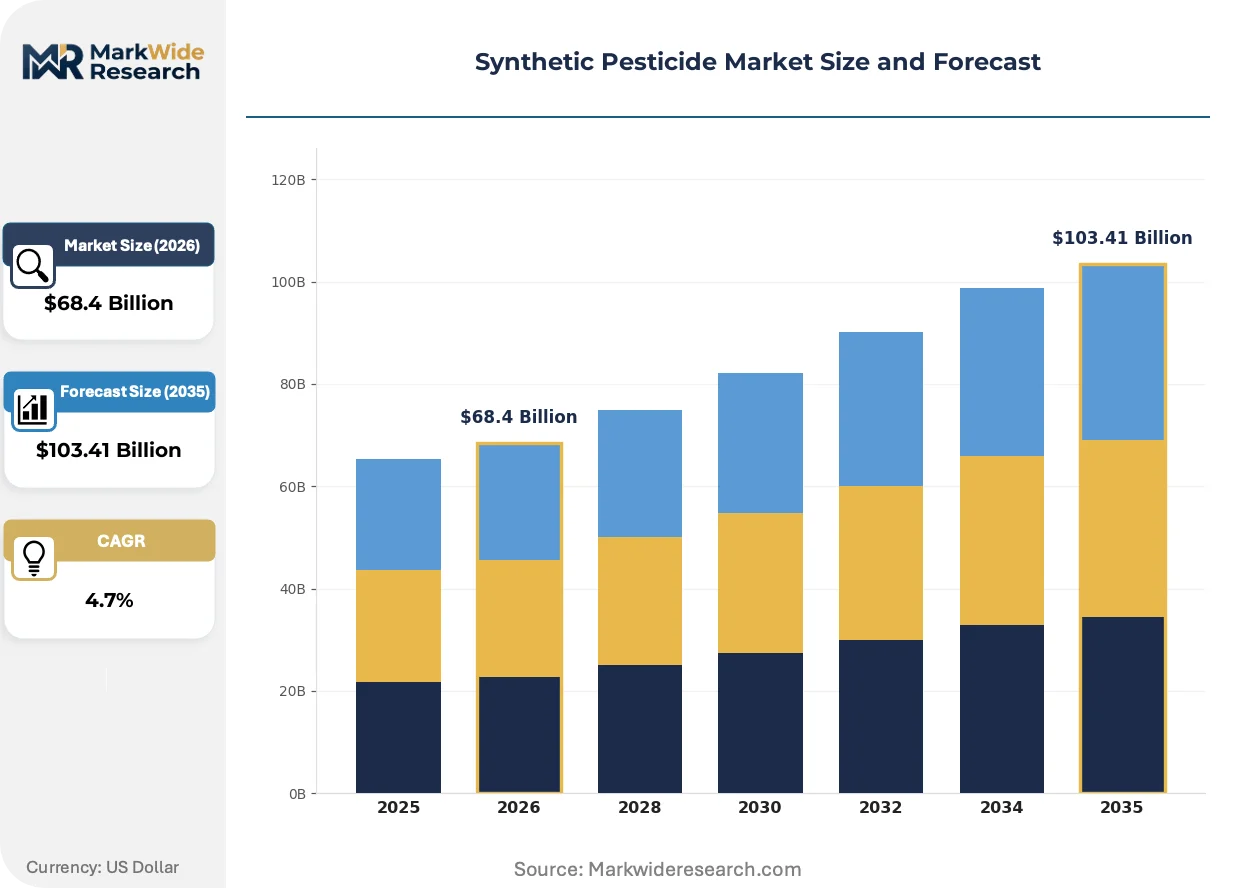
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural, Commercial, Residential, Public Health Chemical Composition: Organophosphates, Carbamates, Pyrethroids, Neonicotinoids Formulation: Granules, Liquids, Concentrates, Emulsifiable Solutions |
| Companies Covered | Corteva Agriscience, Sumitomo Chemical Co., Ltd., BASF SE, ADAMA Ltd., UPL Limited, Bayer AG, FMC Corporation, Nufarm Limited, Syngenta Crop Protection AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Pesticide Market Emerging Trajectories
Active ingredient delivery systems are undergoing fundamental redesign as regulatory pressure on conventional chemistries intersects with precision agriculture infrastructure deployment, compressing effective dose rates while expanding application specificity.
Nano-encapsulation technology is miniaturizing active ingredient particles to sub-micron scales, enabling targeted release triggered by pest-specific enzymes or environmental conditions. Large-scale row-crop operators in the US Corn Belt are piloting these formulations for resistance management. The structural consequence is a compression in per-hectare active ingredient volumes without yield protection degradation.
The EPA's ongoing organophosphate tolerance re-evaluation under FIFRA Section 408 is systematically reducing allowable residues across multiple food-use registrations. This regulatory pressure is accelerating the transition to reduced-risk alternatives in fruit and vegetable production. California's Department of Pesticide Regulation is enforcing additional buffer requirements that disproportionately affect aerial application-dependent growers.
Consolidated procurement by agricultural input retailers is displacing traditional distributor networks in North American row-crop markets. Co-operatives and multi-state retail chains are negotiating direct manufacturer relationships, extracting volume-based rebates and technical service commitments. This channel compression is most visible in the US Midwest where three input retailers now control over half of glyphosate volume distribution.
Synthetic Pesticide Market Segmentation
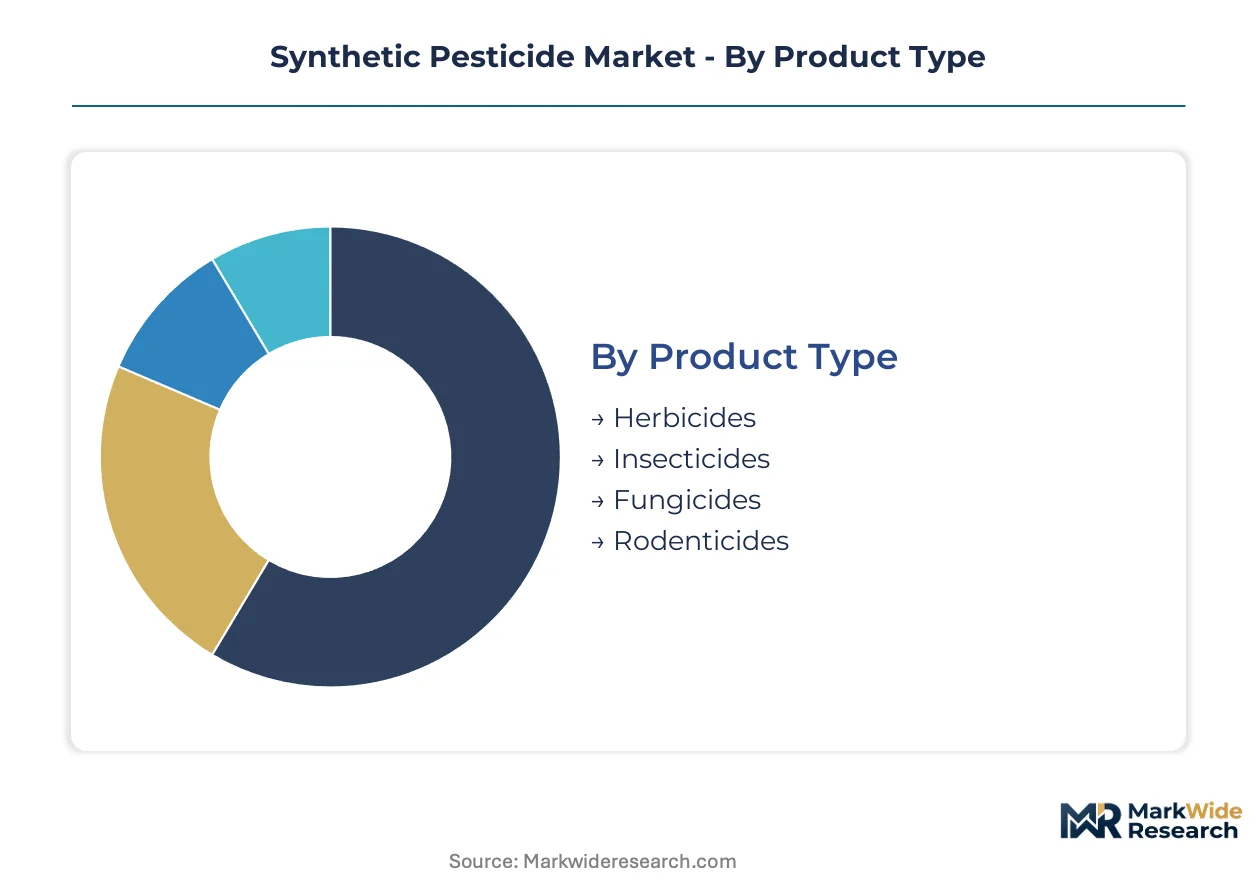
Segmentation in synthetic pesticides reveals how margin pools concentrate around formulation complexity and regulatory tolerance rather than active ingredient chemistry alone. Understanding these divides enables targeted portfolio allocation amid diverging regional standards.
Product Type:
Margin pools concentrate in herbicides where trait-linked systems command premium pricing, while insecticide profitability erodes under pollinator-risk regulatory pressure.
- Herbicides:These compounds disrupt plant metabolic pathways through enzyme inhibition, with glyphosate-tolerant systems dominating row-crop monocultures in Brazil and the US Midwest. Specialty crop producers in Brazil are expanding programs to manage resistant weed populations, driving diversified mode-of-action demand.
- Insecticides:Neurotoxic agents targeting pest nervous systems face structural contraction as the EU Green Deal's hazard-based cut-off criteria systematically removes neonicotinoid registrations. California's Department of Pesticide Regulation enforces additional buffer requirements that disproportionately affect aerial application-dependent growers.
- Fungicides:Protectant and systemic chemistries prevent yield loss from crop diseases in humid cultivation zones.
- Rodenticides:Anticoagulant and acute toxic formulations serve structural pest management and public health vector programs.
The dominant share belongs to herbicides, while fungicides are closing the gap fastest as climate volatility intensifies disease pressure.
Application:
Revenue concentration tilts toward agricultural end-uses where volume throughput offsets thinner per-unit margins, while public health applications sustain price premiums through tender-based procurement.
- Agricultural:Row-crop and specialty crop protection accounts for the majority of volume demand, with India's wheat-rice belt consolidation creating addressable demand for packaged solutions at scale. The EU Green Deal's Farm to Fork strategy tightens maximum residue limits, compelling export-oriented growers to upgrade formulations.
- Commercial:Turf, ornamental, and industrial vegetation management requires specialized application equipment and licensing protocols.
- Residential:Consumer-ready formulations with reduced toxicity profiles serve home garden and lawn care segments.
- Public Health:Vector control programs for malaria, dengue, and zika mitigation operate through government tender mechanisms with stringent efficacy specifications.
Agricultural demand anchors volume, though public health procurement maintains the steepest price premiums per active ingredient unit.
Chemical Composition:
Cost structures diverge sharply based on synthesis pathway complexity and feedstock exposure to petrochemical volatility.
- Organophosphates:These ester-based neurotoxic agents face systematic tolerance reductions as the EPA re-evaluates residues under FIFRA Section 408. California enforces additional restrictions beyond federal minimums, compressing addressable market scope.
- Carbamates:Reversible acetylcholinesterase inhibitors with shorter residual persistence serve markets with stringent re-entry interval requirements.
- Pyrethroids:Synthetic analogs of natural pyrethrins dominate residential and public health applications due to low mammalian toxicity.
- Neonicotinoids:Systemic nicotine-derived compounds face active-substance withdrawals across EU jurisdictions under pollinator-risk assessments.
Pyrethroids hold the largest remaining revenue pool, while carbamates are expanding most quickly as growers seek alternatives to restricted chemistries.
Formulation:
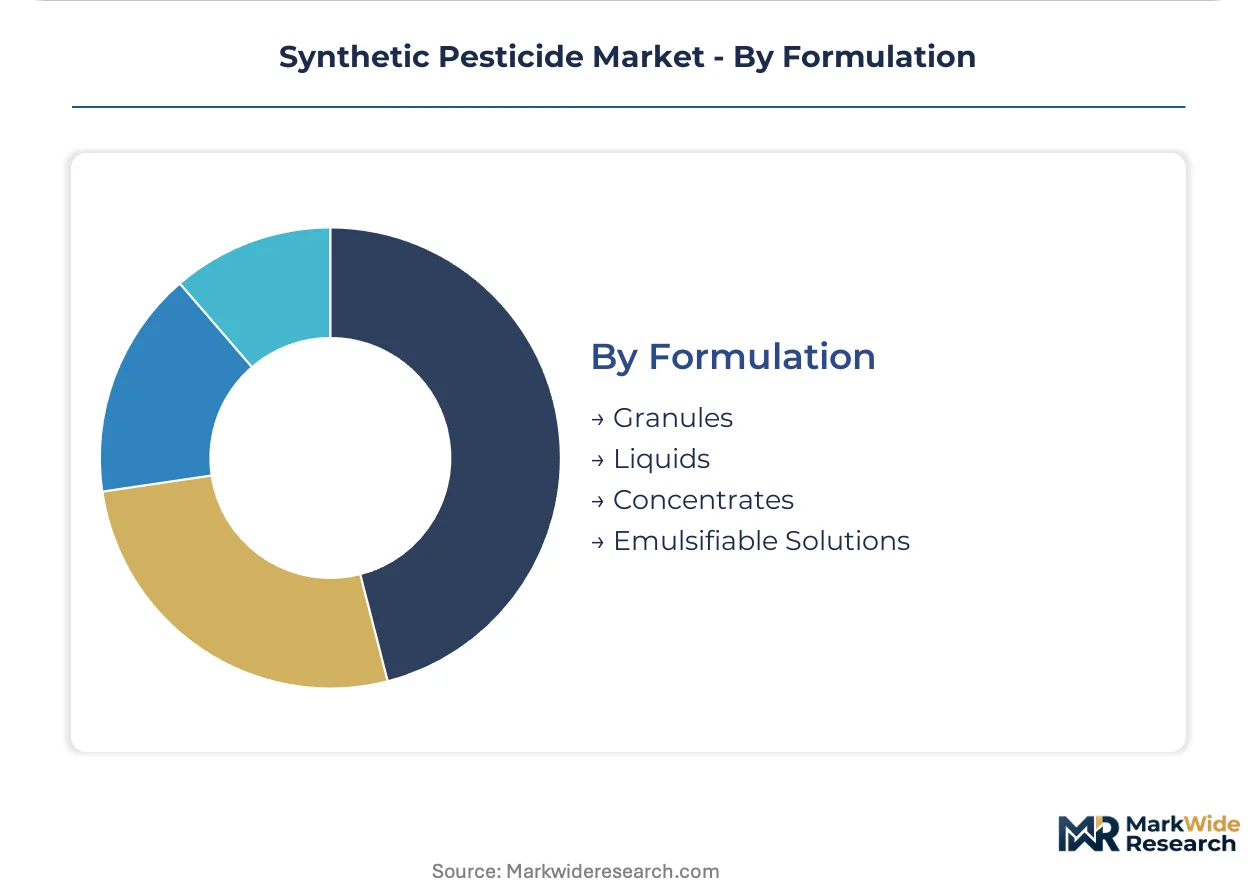
Application method compatibility and drift-control properties determine pricing power, with controlled-release technologies commanding substantial premiums.
- Liquids:Emulsifiable and soluble concentrates dominate volume throughput due to tank-mixing flexibility and aerial application compatibility across the US Corn Belt. Large-scale operators pilot nano-encapsulated variants for resistance management.
- Granules:Controlled-release matrices for flooded rice systems offer drift-control advantages that liquid formulations cannot match, with Southeast Asian markets showing particular receptivity.
- Concentrates:High-active-ingredient formulations reduce transport and storage costs for remote agricultural regions.
- Emulsifiable Solutions:Oil-based carriers enhance penetration of waxy leaf surfaces in specialty crop applications.
Liquid formats retain the dominant position, though granule demand is climbing fastest as rice-paddy systems prioritize drift mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across agricultural economies. Brazilian soybean growers absorb premium herbicide pricing through trait-linked systems, while Indian smallholders remain acutely price-sensitive in unbranded generic markets. European horticultural exporters face the steepest compliance cost escalation under tightening residue mandates.
United States
Large-scale corn and soybean operators in the Midwest Corn Belt drive volume demand for glyphosate-tolerant systems and diversified mode-of-action chemistries. The EPA's ongoing organophosphate tolerance re-evaluation under FIFRA Section 408 systematically reduces allowable residues across food-use registrations. California's Department of Pesticide Regulation enforces additional buffer requirements beyond federal minimums, compressing aerial application scope in the Central Valley.
Brazil
Specialty crop producers in Mato Grosso and São Paulo states are expanding herbicide programs to manage glyphosate-resistant weed populations in soybean monocultures. ANVISA maintains registration pathways distinct from EU hazard-based criteria, preserving access to chemistries withdrawn in European markets. The Cerrado agricultural frontier continues absorbing imported formulation capacity as domestic synthesis infrastructure lags demand growth.
India
Smallholder consolidation across Punjab and Haryana in the wheat-rice belt creates addressable demand for packaged crop protection solutions at scale. The Central Insecticides Board mandates dual-label warnings in 22 official languages, tightening market access for imported formulations. Domestic formulators in Gujarat and Maharashtra leverage established regulatory infrastructure to capture share from multinational entrants facing compliance barriers.
Germany
Integrated agrochemical-seed operations anchor European innovation pipelines, with Bayer AG maintaining headquarters and R&D concentration in Leverkusen. The EU Green Deal's hazard-based cut-off criteria under Regulation 1107/2009 systematically removes neonicotinoid and organophosphate registrations, forcing portfolio recomposition. German formulators increasingly serve as regulatory compliance gateways for export-oriented growers in third-country markets.
China
Domestic producers supply the majority of global technical-grade active ingredient output, concentrating manufacturing in Jiangsu and Shandong provinces. The Ministry of Ecology and Environment enforces stricter environmental impact assessments for chemical synthesis facilities under dual carbon goals. Export-oriented formulators face divergent residue tolerance requirements between EU, US, and emerging market jurisdictions, complicating batch allocation decisions.
Synthetic Pesticide Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated multinationals with seed-chemistry integration command premium positioning through trait-linked systems, while asset-light generic specialists compete aggressively on price in post-patent molecule markets. Three archetypes dominate: R&D-intensive innovators with biological discovery platforms, integrated agribusiness conglomerates with captive distribution, and regional formulators with regulatory compliance advantages. Competitive moves concentrate on portfolio diversification into biopesticide adjacencies and geographic expansion through distributor acquisition in consolidating procurement channels.
Among integrated agribusiness conglomerates, Bayer AG and Corteva Agriscience exemplify the seed-chemistry integration archetype that sustains premium pricing power. BASF SE occupies a position bridging proprietary active ingredient innovation with broad formulation expertise. On the cost-competitive vector, UPL Limited and ADAMA Ltd. represent the asset-light generic specialist model, leveraging post-patent molecule portfolios and emerging market regulatory infrastructure to capture volume share.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| ADAMA Ltd. |
| UPL Limited |
| Bayer AG |
| FMC Corporation |
| Nufarm Limited |
| Syngenta Crop Protection AG |
| Others |
Supply Flow & Price Mechanics
Technical-grade active ingredient capacity utilization in Jiangsu and Shandong provinces shapes global price floors, as Chinese manufacturers supply the majority of global output and dictate cost baselines for downstream formulators in Brazil, India, and Germany.
Pricing Analysis
After-sales technical service contracts and resistance management advisory programs drive lifetime value for integrated multinationals, while transactional spot markets dominate generic trade. Three-tier pricing structure across premium proprietary, standard branded, and economy generic levels separates Bayer AG's trait-linked systems from UPL Limited's post-patent molecules. Cost compression in organophosphate and pyrethroid tiers is intensifying because petrochemical feedstock volatility squeezes synthesis margins. Smallholder farmers in India's wheat-rice belt exhibit the highest price sensitivity, whereas Brazilian soybean operators absorb premiums through yield-linked returns.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of technical-grade active ingredient flows from Chinese manufacturing clusters to Southeast Asian formulation plants and onward to Brazilian port terminals. Supply concentrates in China, India, and Germany, with Jiangsu province hosting the densest synthesis infrastructure. Formulation depends on petrochemical-derived intermediates, surfactant packages, and polymer encapsulation materials. Single-source vulnerability in Chinese technical-grade output creates systemic exposure to environmental compliance shutdowns under Ministry of Ecology and Environment enforcement. Distribution runs through agricultural input retailers and co-operative procurement networks that are consolidating rapidly in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise has become the binding constraint, as surfactant-solvent compatibility knowledge and controlled-release polymer matrix design concentrate at shrinking research institutions and contract laboratories.
For Market Incumbents: Shield glyphosate-tolerant system revenues by accelerating diversified mode-of-action herbicide registration ahead of EU 1107/2009 withdrawal cascades. Deepen backward integration into technical-grade active ingredient synthesis in jurisdictions with regulatory divergence from EU hazard-based criteria, preserving access to chemistries withdrawn in European markets. Prioritize captive supply of nano-encapsulation capacity to defend premium positioning in resistance management segments. For New Entrants and Emerging Players: Lead with precision application convergence opportunities, targeting drone-compatible ultra-low-volume formulation gaps in Southeast Asian rice-paddy systems where drift control commands substantial premiums. India's multilingual label mandate creates a compliance moat favoring domestic formulators with established Central Insecticides Board infrastructure, making Gujarat and Maharashtra regulatory clusters the most penetrable entry points. Pursue direct procurement relationships with consolidating agricultural input retailers to bypass traditional distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated agribusiness conglomerates with seed-chemistry linkages and long-term trait licensing agreements, suggesting superior cash flow quality relative to pure-play generic manufacturers. Over the medium-term horizon, portfolio viability hinges on biopesticide adjacency diversification and reduced-risk chemistry pipelines. Target acquisition archetypes should emphasize regional formulators with regulatory compliance advantages in high-barrier markets. Monitor EPA organophosphate tolerance re-evaluation velocity as the critical inflection signal for legacy chemistry revenue cliff timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Synthesis | Captures margin pool concentration in Chinese manufacturing clusters while hedging regulatory withdrawal risk. |
| Nano-Encapsulation Capacity Buildout | Enables targeted release formulations that command premiums in US Corn Belt resistance management programs. |
| Dual-Label Compliance Infrastructure Investment | Positions domestic formulators to capture share from multinational entrants facing India's 22-language mandate. |
| Drone-Compatible Formulation Development | Opens demand in Southeast Asian rice systems where electrostatic and rotary atomization systems expand. |
| Biopesticide Adjacency Acquisition | Diversifies revenue exposure away from EU Green Deal hazard-based cut-off criteria compression. |
Methodological Framework
Initial hypotheses were tested against primary input from agrochemical R&D directors, regulatory affairs specialists at multinational formulators, procurement leads at agricultural input retailers, and plant managers at Chinese technical-grade manufacturing facilities, then refined through secondary validation against customs trade data, EPA FIFRA registration databases, EU 1107/2009 active substance review records, and SEC 10-K filings from listed agrochemical conglomerates. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Variance decomposition across the projection horizon isolates drivers by product type, chemical composition, formulation format, application end-use, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macro agricultural output forecasts and crop protection intensity trends. Mode-of-action substitution dynamics and pollinator-risk regulatory velocity served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained smallholder consolidation trajectories in India, continued EU hazard-based withdrawal schedules, or stable petrochemical feedstock pricing would require recalibration. Practitioners should keep alternative scenarios live as EPA organophosphate tolerance re-evaluation timelines and Ministry of Ecology and Environment enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Acaricides Market
Crop Protection
Avicides Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Propiconazole Market
Crop Protection
Europe Insecticides Market
Crop Protection
Nematicides Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Tembotrione Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
Global Insecticides Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Global Algaecides Market
Crop Protection
United States Nematicides Market
Crop Protection
Dicamba Market