
 Pest Control Market | 2026-2036
Pest Control Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Control Market Intelligence
Certified entomologist staffing shortages across North America and Western Europe is unwinding service capacity and lengthening response times for complex infestation cases. Rollins leverages its university partnership pipeline to sustain technician recruitment in secondary metros where competitors face attrition. Orkin dominates residential route density through proprietary scheduling algorithms that maximize daily service stops. Rentokil anchors commercial account retention with IoT-enabled remote monitoring systems that reduce emergency call frequency.
Pest control encompasses the systematic management of arthropod, rodent, and avian species through chemical, biological, and physical intervention protocols, typically requiring applicator licensing under FIFRA and state-equivalent statutes. The practice centers on preventing economic loss, disease vector transmission, and structural damage across built environments and agricultural operations. Chemical treatment still occupies the largest revenue share among service types, though biological control is gaining traction in food processing and organic agriculture applications where residue restrictions apply. Integrated pest management commands premium pricing from agribusinesses and government agencies seeking multi-tactic compliance documentation.
EPA FIFRA registration requirements, ECHA REACH biocidal product regulations, and state-level structural pest control boards collectively elevate compliance costs and limit unlicensed market entry. These frameworks favor established operators with dedicated regulatory affairs staff over fragmented local competitors. Stakeholders must monitor evolving pollinator protection label language and neonicotinoid restrictions, as these chemical class limitations will force faster portfolio restructuring than most service networks currently assume.
Market Dynamics
EPA FIFRA re-registration deadlines are compressing conventional insecticide availability while accelerating biological formulation procurement across commercial service networks.
Growth Catalysts
- Neonicotinoid Restrictions:EPA pollinator protection label language is redirecting food processing facilities toward biological control formulations with zero residue tolerance compliance.
- Multi-Site Hospitality Contracts:Healthcare and hotel chains in the United States are consolidating vendor relationships under standardized preventive management programs.
- IoT Remote Monitoring:Sensor-based detection systems are reducing emergency service frequency and anchoring long-term commercial account retention.
Market Restraints
- Pyrethroid Supply Concentration:Active ingredient manufacturing clusters in China create input cost volatility and formulation bottlenecks for conventional service providers.
- Certified Entomologist Scarcity:North American university pipeline limitations constrain service capacity expansion for complex infestation protocols.
- Biological Efficacy Windows:Narrow temperature and humidity ranges for microbial agents limit deployment geography compared to chemical alternatives.
Strategic Opportunities
- Organic Agriculture Certification:USDA National Organic Program residue standards are creating dedicated service tiers for biological-only intervention protocols.
- Smart Building Integration:Convergence of IoT sensors with building management systems enables predictive pest risk scoring for facility managers.
- Secondary Metro Penetration:University partnership pipelines for technician training unlock service density in mid-sized United States markets where competitors face attrition.
Industry Challenges
- Applicator Licensing Timelines:State-level structural pest control board examination backlogs delay workforce expansion in high-demand corridors.
- Legacy Route Optimization:Proprietary scheduling algorithm integration with existing dispatch systems requires substantial IT infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Control Market |
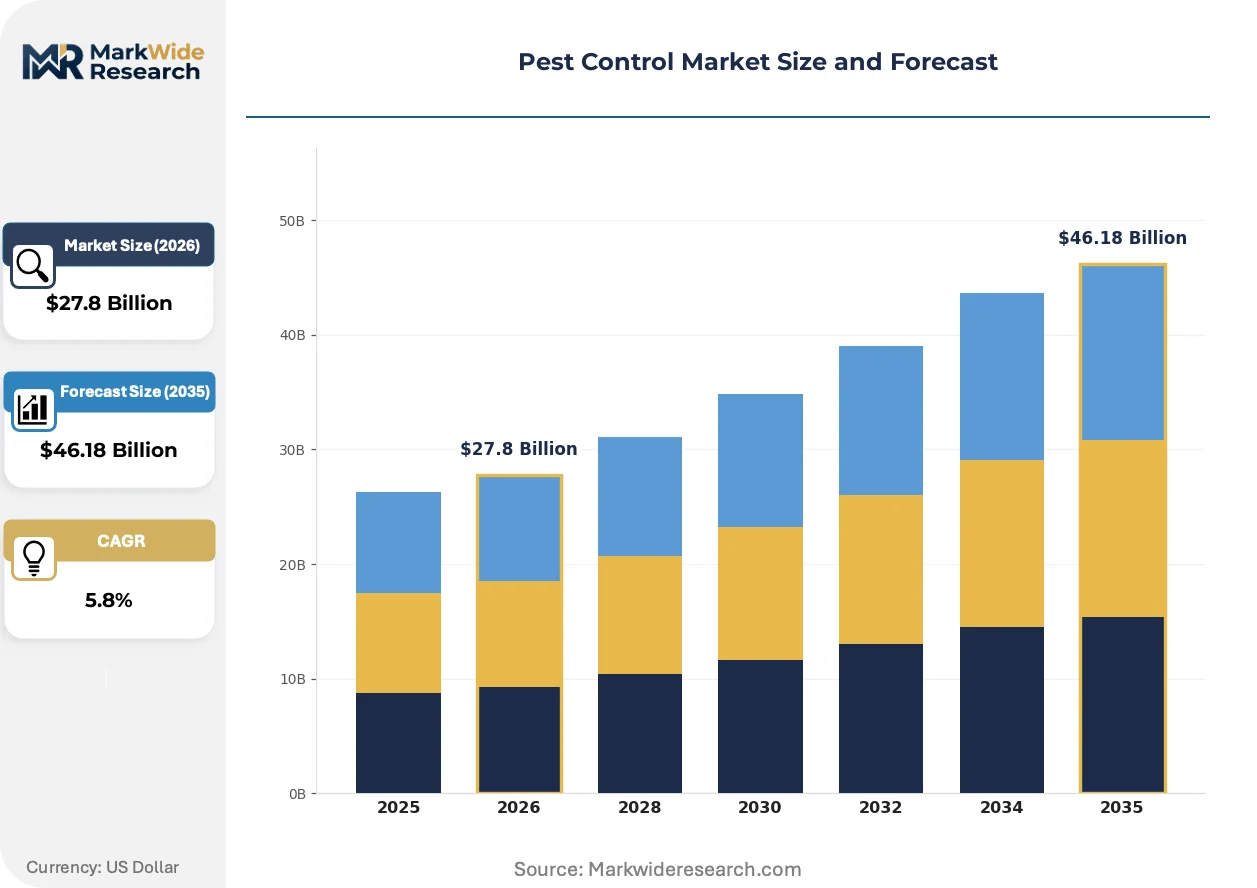
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Rodenticides, Termiticides, Herbicides, Fungicides Application: Residential Premises, Commercial Facilities, Agricultural Fields, Warehouses, Public Spaces End User: Homeowners, Food Processing Plants, Agribusinesses, Government Agencies, Hospitality Providers Service Type: Chemical Treatment, Biological Control, Mechanical Trapping, Fumigation, Integrated Pest Management |
| Companies Covered | Ehrlich, Hawx, Orkin, Rollins, TruGreen, Terminix, Aptive, ServiceMaster, Rentokil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Control Market Strategic Shifts & Innovations
Digital detection technologies and residue-free mandates are restructuring service delivery economics while compressing response-time expectations across commercial accounts.
Precision pheromone disruption systems are decomposing traditional perimeter-spray revenue models. Food processing plants in the United States are adopting these species-specific mating interference protocols within eighteen-month procurement cycles. The technology is decomposing chemical treatment frequency and enabling subscription-based monitoring contracts with higher margin retention.
ECHA REACH biocidal product authorization timelines are extending registration costs for conventional actives. European Union member states now require comprehensive pollinator risk assessments for pyrethroid renewals. Organic agriculture operators and zero-residue food processors are accelerating biological formulation procurement ahead of anticipated chemical class restrictions.
Facility managers are consolidating pest control spend under integrated facility management umbrellas. Third-party property management platforms are displacing direct vendor relationships in multi-site healthcare and hospitality portfolios. This bundling is most visible in United States metropolitan corridors where real estate investment trusts standardize service specifications across asset portfolios.
Pest Control Market Segmentation
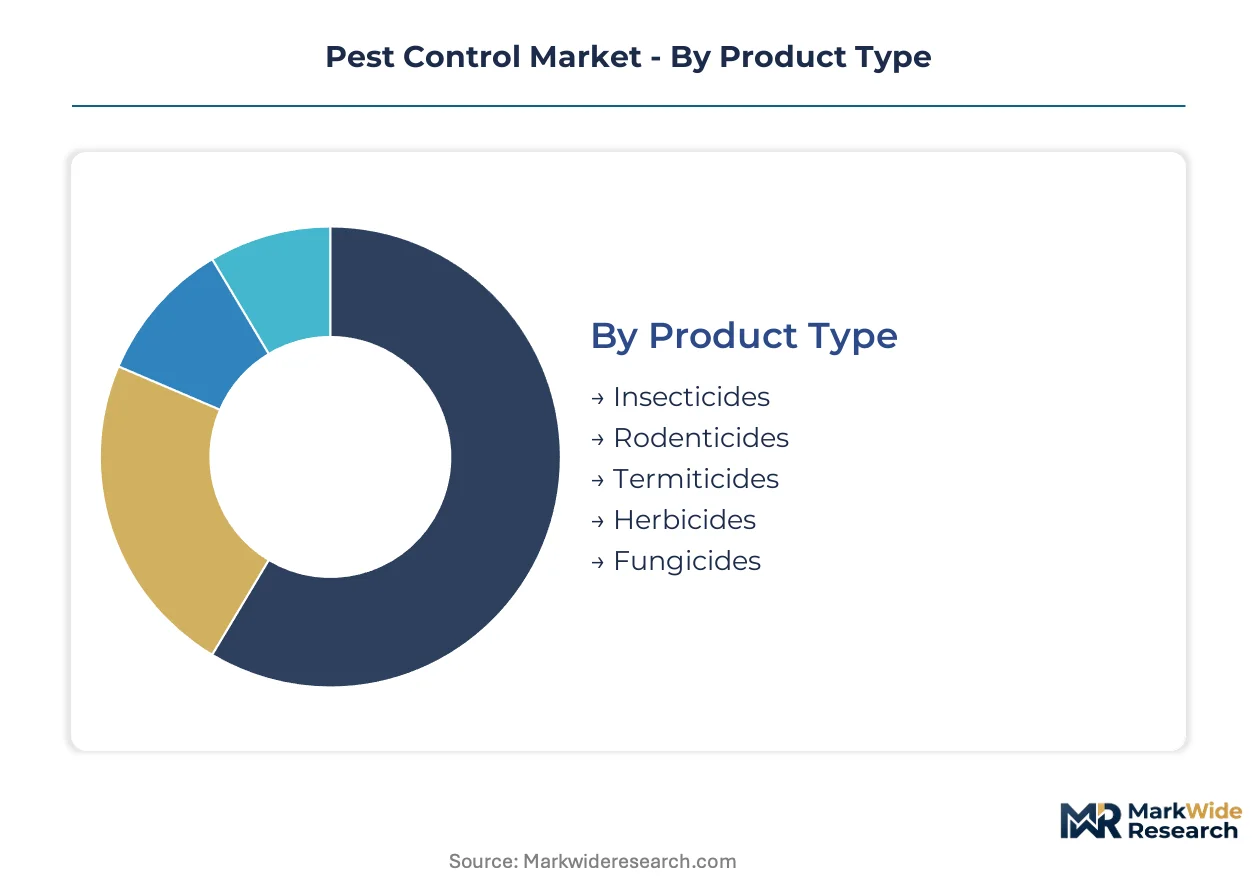
Pest control procurement splits across chemical and biological intervention classes, each carrying distinct EPA FIFRA registration burdens and residue compliance thresholds. Service providers structure pricing and technician certification requirements differently across these boundaries.
Product Type:
EPA re-registration timelines and pollinator protection label mandates are compressing conventional active ingredient availability while elevating biological formulation procurement.
- Insecticides:Synthetic pyrethroids and neonicotinoids dominate commercial service revenue despite tightening EPA pollinator protection language. Food processing facilities in the United States are accelerating procurement shifts toward microbial alternatives ahead of anticipated chemical class restrictions.
- Rodenticides:Anticoagulant formulations face secondary toxicity scrutiny under EPA risk assessments, constraining perimeter deployment around wildlife corridors. Warehouse operators in California and New York are adopting non-toxic mechanical alternatives to preempt regulatory exposure.
- Termiticides:Soil-applied barrier treatments require state-specific applicator licensing under structural pest control board statutes.
- Herbicides:Agricultural field applications dominate volume, with glyphosate alternatives gaining traction in organic certification zones.
- Fungicides:Post-harvest treatment protocols for grain storage facilities drive concentrated demand in Midwest agricultural corridors.
Insecticides handle the majority of throughput; biological alternatives are climbing the fastest on share.
Application:
Facility risk profiles and inspection frequency requirements create distinct margin structures across deployment settings.
- Commercial Facilities:Food processing plants and pharmaceutical manufacturing sites command premium preventive contracts with zero-tolerance residue standards. Multi-site operators in Texas and Illinois are consolidating vendor relationships under standardized IoT-enabled monitoring protocols.
- Residential Premises:Subscription-based perimeter treatments generate recurring revenue with lower technician certification thresholds than commercial accounts. Route density algorithms maximize daily service stops in metropolitan corridors.
- Agricultural Fields:Seasonal application windows and weather dependency compress revenue recognition into concentrated periods.
- Warehouses:Fumigation protocols for commodity storage require specialized confined-space certifications.
- Public Spaces:Municipal vector control contracts carry budget volatility and political procurement cycles.
Commercial Facilities capture the highest contract values; Residential Premises provide the most predictable recurring revenue base.
End User:
Procurement sophistication and compliance documentation requirements segment the customer base sharply.
- Food Processing Plants:USDA and FDA audit readiness mandates drive integrated pest management adoption with comprehensive service documentation. Zero-residue tolerance protocols are redirecting procurement toward biological control formulations.
- Agribusinesses:Large-scale row crop operators negotiate volume-based chemical treatment pricing with seasonal flexibility clauses.
- Homeowners:Price-sensitive demand concentrates in suburban corridors with high property turnover rates.
- Government Agencies:Vector control districts operate on municipal budget cycles with extended procurement timelines.
- Hospitality Providers:Brand reputation sensitivity drives rapid response service tier premiums.
Food Processing Plants anchor commercial margin expansion; Agribusinesses represent the deepest volume concentration.
Service Type:
Technical complexity and labor intensity diverge substantially across intervention methodologies.
- Integrated Pest Management:Multi-tactic protocols combining monitoring, exclusion, and targeted treatment command premium pricing from compliance-driven accounts. Government agencies and organic-certified agribusinesses require extensive documentation that elevates service stickiness.
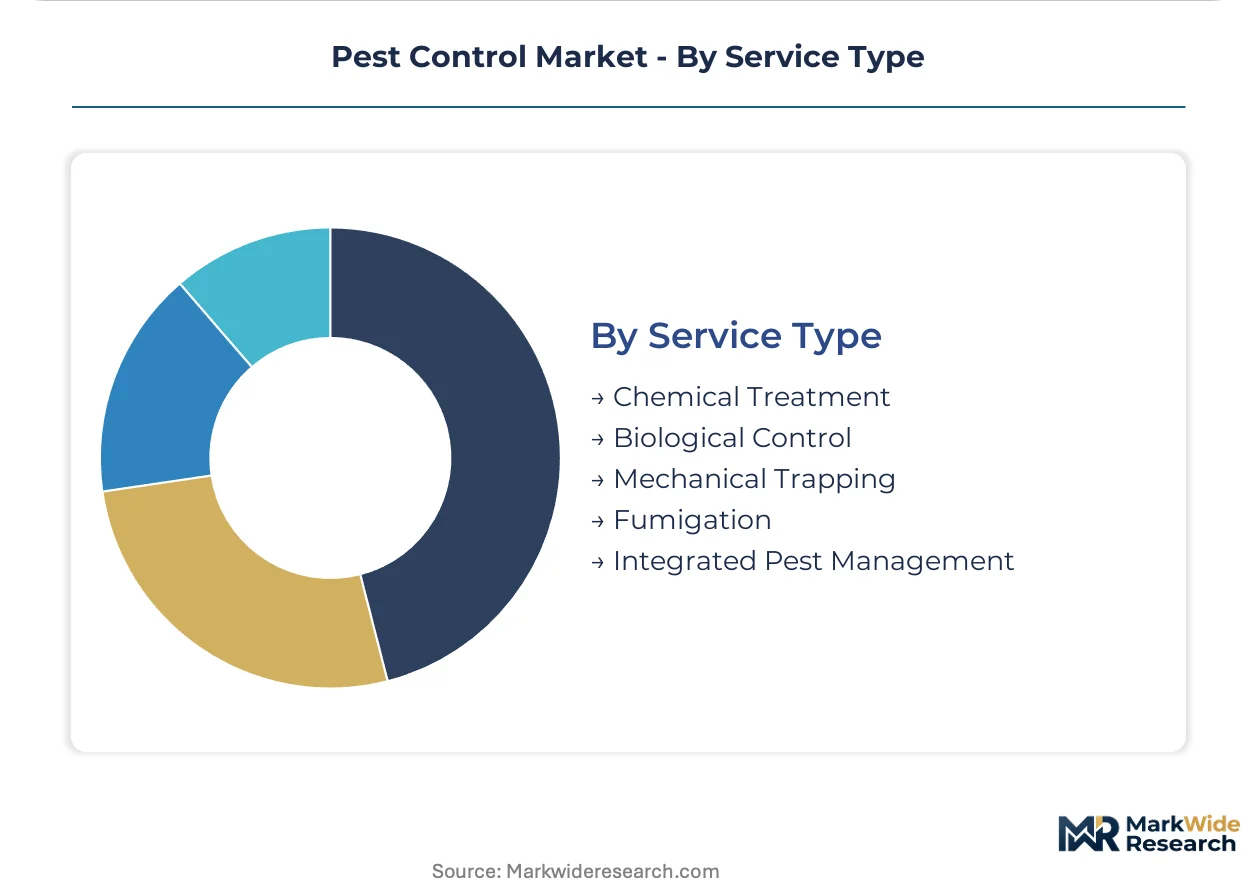
- Chemical Treatment:Conventional perimeter and broadcast applications still occupy the largest revenue share despite regulatory compression on active ingredient availability.
- Biological Control:Microbial and botanical formulations face narrow temperature efficacy windows that constrain deployment geography.
- Mechanical Trapping:Sensor-integrated systems enable predictive service scheduling with lower labor intensity.
- Fumigation:Confined-space certification requirements and liability exposure limit provider competition.
Chemical Treatment maintains the broadest deployment base; Integrated Pest Management is gaining share fastest among premium commercial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States prioritizing preventive commercial contracts while European procurement accelerates biological formulation shifts under REACH pressure.
United States
Multi-site hospitality and healthcare operators in Texas and Illinois are consolidating vendor relationships under standardized IoT-enabled monitoring protocols. EPA FIFRA re-registration deadlines are compressing conventional insecticide availability for food processing facilities. The Midwest agricultural corridor anchors grain storage fumigation demand, with Indiana and Ohio operators requiring specialized confined-space certifications.
Germany
Industrial facilities in Bavaria and North Rhine-Westphalia are adopting precision pheromone disruption systems for species-specific mating interference. ECHA REACH biocidal product authorization timelines are extending registration costs for pyrethroid formulations. The Stuttgart industrial cluster is driving biological control procurement ahead of anticipated chemical class restrictions.
China
Active ingredient manufacturing concentration in Jiangsu and Shandong provinces creates input cost volatility for global formulation supply. The country's national environmental regulator is tightening discharge standards for chemical production facilities. Yangtze River Delta agribusinesses are expanding integrated pest management documentation for export compliance.
Brazil
São Paulo and Minas Gerais row crop operators negotiate volume-based chemical treatment pricing with seasonal flexibility clauses. ANVISA residue monitoring protocols are redirecting organic certification zones toward microbial alternatives. The Mato Grosso soybean belt is concentrating biological formulation trials ahead of EU import tolerance tightening.
Australia
New South Wales and Victoria grain storage operators drive post-harvest fungicide demand under strict export phytosanitary requirements. The national agricultural regulator is reviewing anticoagulant rodenticide secondary toxicity assessments. Perth metropolitan commercial facilities are piloting sensor-integrated mechanical trapping for predictive service scheduling.
Pest Control Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the pest control market structure. Rollins and Rentokil anchor the upper tier through multi-brand platform strategies, while regional specialists concentrate on single-service verticals or geographic pockets. Three archetypes dominate: national route-density optimizers, commercial IoT-enabled monitoring providers, and agricultural seasonal contractors. Consolidation through franchise network acquisition and proprietary scheduling algorithm deployment represent the dominant competitive moves.
Within the national platform tier, Orkin and Terminix exemplify route-density optimization through proprietary technology integration, while Rentokil occupies a position as the commercial monitoring archetype with European regulatory compliance depth. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Ehrlich |
| Hawx |
| Orkin |
| Rollins |
| TruGreen |
| Terminix |
| Aptive |
| ServiceMaster |
| Rentokil |
| Others |
Cost & Logistics Intelligence
Long-term preventive service contracts with embedded IoT monitoring provisions lock in multi-year revenue visibility while securing priority access to certified technician pools and biological formulation supply. Food processing facilities in the United States negotiate these agreements to guarantee zero-residue compliance documentation under tightening EPA FIFRA timelines.
Pricing Analysis
Subscription-based preventive contracts dominate commercial accounts, with pricing stratifying across premium IPM tiers, standard chemical treatment bundles, and economy perimeter-spray options. Certification grade under USDA National Organic Program standards and volume scale across multi-site portfolios drive price differentiation. Cost compression in standard chemical tiers is intensifying because pyrethroid supply volatility from Chinese manufacturing clusters feeds input cost uncertainty. Residential homeowners exhibit highest price sensitivity, while pharmaceutical manufacturing sites accept premium positioning for audit-ready documentation.
Supply Chain Analysis
Inventory buffers for microbial formulations remain constrained by narrow temperature efficacy windows that compress distribution lead times versus chemical alternatives. Active ingredient manufacturing concentrates in China, India, and Germany, with synthetic pyrethroid production anchored in Jiangsu province and biological fermentation capacity clustering in Bavaria. Formulation supply rests on pyrethroid precursors, Bacillus thuringiensis cultures, and precision pheromone synthesis inputs. Single-source vulnerability in Chinese pyrethroid intermediates creates tariff exposure and logistics chokepoint risk. Distribution runs through national service networks with regional blending facilities and direct technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biological control formulations that displace conventional chemical revenue streams under pollinator protection mandates. Defense requires repositioning service portfolios before regulatory compression accelerates.
For Market Incumbents: Shield recurring revenue by embedding IoT-enabled remote monitoring into long-term commercial contracts, reducing emergency call frequency and elevating switching costs. Accelerate backward integration into biological formulation supply through captive fermentation capacity or exclusive offtake agreements with microbial producers. EPA FIFRA re-registration timelines threaten pyrethroid-dependent service tiers. For New Entrants and Emerging Players: Anchor in secondary United States metros where certified entomologist scarcity constrains incumbent expansion, exploiting university partnership pipelines for technician recruitment. Target organic agriculture certification zones with biological-only intervention protocols, where USDA National Organic Program residue standards create dedicated service tiers underserved by chemical-focused networks. Lead with precision pheromone disruption systems to decompose traditional perimeter-spray models. For Investors and Strategic Acquirers: Regional IoT-enabled monitoring specialists with established food processing plant relationships represent the most defensible acquisition profile for portfolio exposure. Biological formulation capabilities and EPA regulatory affairs depth separate viable long-term assets from stranded chemical-dependent service networks. Watch for pollinator protection label language acceleration as the inflection signal forcing faster portfolio restructuring than incumbent planning assumptions currently reflect.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Capacity Expansion | Captures procurement shifts from food processing facilities under EPA pollinator mandates. |
| IoT Monitoring Platform Integration | Reduces emergency service frequency and anchors long-term commercial account retention. |
| University Partnership Pipeline Development | Unlocks certified technician supply in secondary metros where competitors face attrition. |
| Precision Pheromone Technology Licensing | Enables subscription-based monitoring contracts with higher margin retention than chemical sprays. |
| Organic Certification Service Tier Launch | Addresses USDA National Organic Program residue standards with dedicated biological-only protocols. |
Research Approach
A spread of perspectives from service operations directors, EPA regulatory affairs leads, food processing facility managers, and agricultural procurement officers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA FIFRA registration databases, ECHA REACH biocidal product authorization timelines, USDA National Organic Program standards, and state-level structural pest control board examination records. Bottom-up technician deployment modeling and top-down service revenue aggregation were triangulated against customs data for active ingredient imports.
Segmentation dimensions modeled include intervention methodology, facility risk profile, applicator certification tier, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base growth, contract renewal rates, and formulation substitution elasticities. Forecast inputs incorporated EPA re-registration timeline acceleration, neonicotinoid restriction propagation, and IoT sensor adoption curves in commercial facilities.
Decision-makers should treat outputs as directional under assumptions of steady EPA pollinator protection enforcement and stable pyrethroid supply from Chinese manufacturing; material deviation in either would warrant model refresh. Biological efficacy window constraints and certified entomologist pipeline limitations represent specific risk factors that could compress or extend projected growth trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Acephate Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Soil Fumigant Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
China Insecticide Market
Crop Protection
Tebuconazole Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Metamifop Market
Crop Protection
Pest Control Products Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Global Turf Protection Market
Crop Protection
Hungary Crop Protection Chemicals Market