
 Pest Management Services Market | 2026-2036
Pest Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Management Services Market Analysis
Remote sensing and IoT-enabled trap monitoring is rewriting operational workflows across the pest management sector. Rentokil Initial plc leverages connected device networks to deliver predictive intervention schedules for large commercial accounts. Rollins, Inc. sustains dense branch-level coverage across North American metropolitan corridors through its Orkin franchise model. Ecolab Inc. anchors food safety-adjacent pest programs with chemistry formulations aligned to FSMA audit requirements.
Pest management services encompass systematic inspection, treatment, and prevention protocols targeting arthropod, rodent, and avian infestations in built environments and agricultural settings, typically employing application equipment calibrated to 0.5–2.0 gallons per 1,000 square feet for residual insecticide barriers. The primary commercial purpose centers on protecting property integrity, human health, and regulatory compliance across facilities subject to third-party audit standards. Termite treatment commands premium pricing per service event due to structural warranty obligations and specialized baiting system installation requirements. Integrated pest management represents the fastest-growing technology category as facility managers shift from calendar-based spraying to threshold-driven biological and mechanical interventions. Residential end users generate the highest transaction frequency though commercial contracts yield superior lifetime value through multi-year service agreements.
EPA registration requirements under FIFRA govern all pesticide products deployed by service technicians, while OSHA standards mandate hazard communication and personal protective equipment protocols for applicator workforces. State-level departments of agriculture impose additional certification reciprocity rules that constrain cross-border technician deployment and influence regional operator consolidation patterns. Stakeholders must monitor evolving biopesticide registration pathways and pollinator protection label amendments to anticipate chemistry portfolio transitions.
Market Dynamics
Integrated pest management protocols are displacing calendar-based chemical spraying across commercial property portfolios, driven by tightening EPA FIFRA registration requirements and municipal procurement mandates for biological and mechanical intervention thresholds.
Growth Catalysts
- EPA FIFRA Registration Pathways:Accelerated biopesticide approval timelines under EPA Section 3 registrations are expanding service provider chemistry portfolios beyond conventional neurotoxic formulations.
- Food Processing Facilities:FSMA preventive controls mandates are compelling food manufacturers to adopt third-party audited pest management programs with documented intervention thresholds.
- IoT Sensor Networks:Remote monitoring hardware is enabling predictive service scheduling that reduces emergency callback frequency and extends contract renewal rates.
Market Restraints
- Technician Certification Reciprocity:State-level department of agriculture licensing requirements prevent cross-border workforce deployment, constraining national operator scalability.
- Active Ingredient Supply Concentration:Pyrethroid and neonicotinoid manufacturing concentrates in Chinese chemical producers, exposing service providers to import tariff volatility.
- Structural Warranty Obligations:Termite baiting system installations carry multi-year performance guarantees that compress margin recovery timelines and elevate litigation exposure.
Strategic Opportunities
- India Urban Municipal Contracts:Swachh Bharat Mission sanitation infrastructure investments are creating tender opportunities for vector control services in rapidly densifying metropolitan corridors.
- Avian Deterrent Systems:Airport authority wildlife hazard management mandates are opening specialized service niches combining laser technology with pyrotechnic protocols.
- Green Building Certification Alignment:LEED v4.1 and WELL Building Standards IPM prerequisites are creating specification advantages for providers with documented non-chemical intervention capabilities.
Industry Challenges
- Entomology Technician Pipeline:University agricultural extension programs are producing insufficient board-certified entomologists to staff regional technical director positions.
- Legacy Route Management Software:Franchise operators face integration friction when migrating from paper-based service logs to cloud-based customer relationship management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Management Services Market |
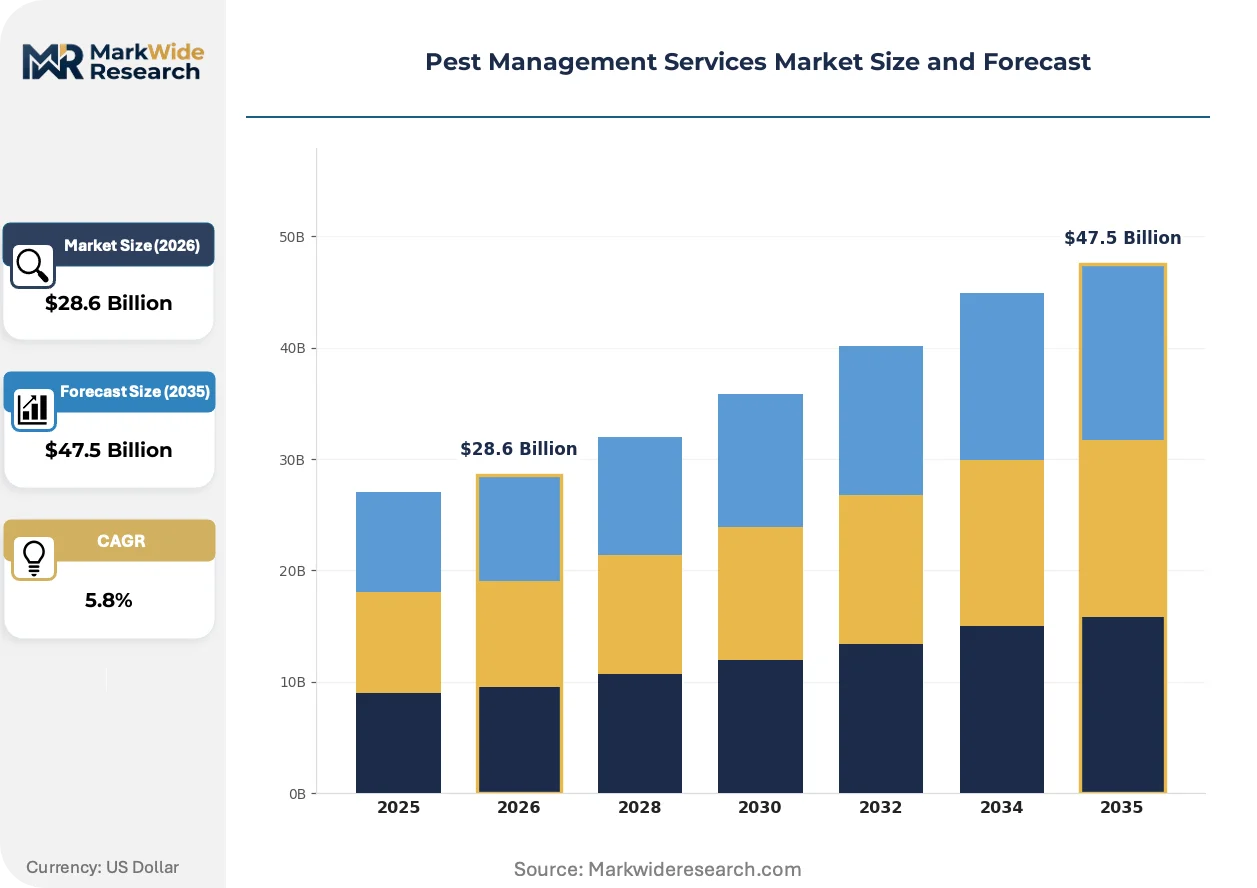
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rodent Control, Termite Treatment, Insect Extermination, Fumigation End User: Residential, Commercial, Agriculture, Hospitality Distribution Channel: Direct Sales, Online, Retail, Franchising Technology: Chemical, Biological, Integrated Pest Management, Mechanical |
| Companies Covered | Rentokil Initial plc, Rollins, Inc., Ecolab Inc., The ServiceMaster Company, LLC., BASF SE, Bayer AG, Anticimex, FMC Corporation, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Management Services Market Emerging Trajectories
Digital infrastructure is compressing the information asymmetry between service technicians and facility managers, enabling real-time infestation documentation and automated compliance reporting that reduces audit preparation labor.
Connected pheromone trap arrays are virtualizing the traditional scout-and-spray service model. Food processing plant maintenance directors are deploying these networks across warehouse zones to detect stored-product moth populations before visible damage occurs. This virtualization is compressing emergency response revenue while expanding recurring monitoring contract penetration.
EU Green Deal Farm-to-Fork pesticide reduction targets are cascading into commercial pest management through ECHA biocidal product authorization reviews. The regulatory consequence is accelerated withdrawal of chlorpyrifos and neonicotinoid formulations from professional use catalogs. German and French facility managers are responding by specifying biological control agents and heat treatment protocols in tender documents.
Facility managers are unbundling after-sales service from equipment procurement, separating initial installation from ongoing monitoring contracts. This pattern disrupts the traditional bundled warranty model and exposes standalone equipment suppliers to price pressure. The shift is most visible in United States healthcare and pharmaceutical manufacturing verticals where capital expenditure approval cycles have elongated.
Pest Management Services Market Segmentation
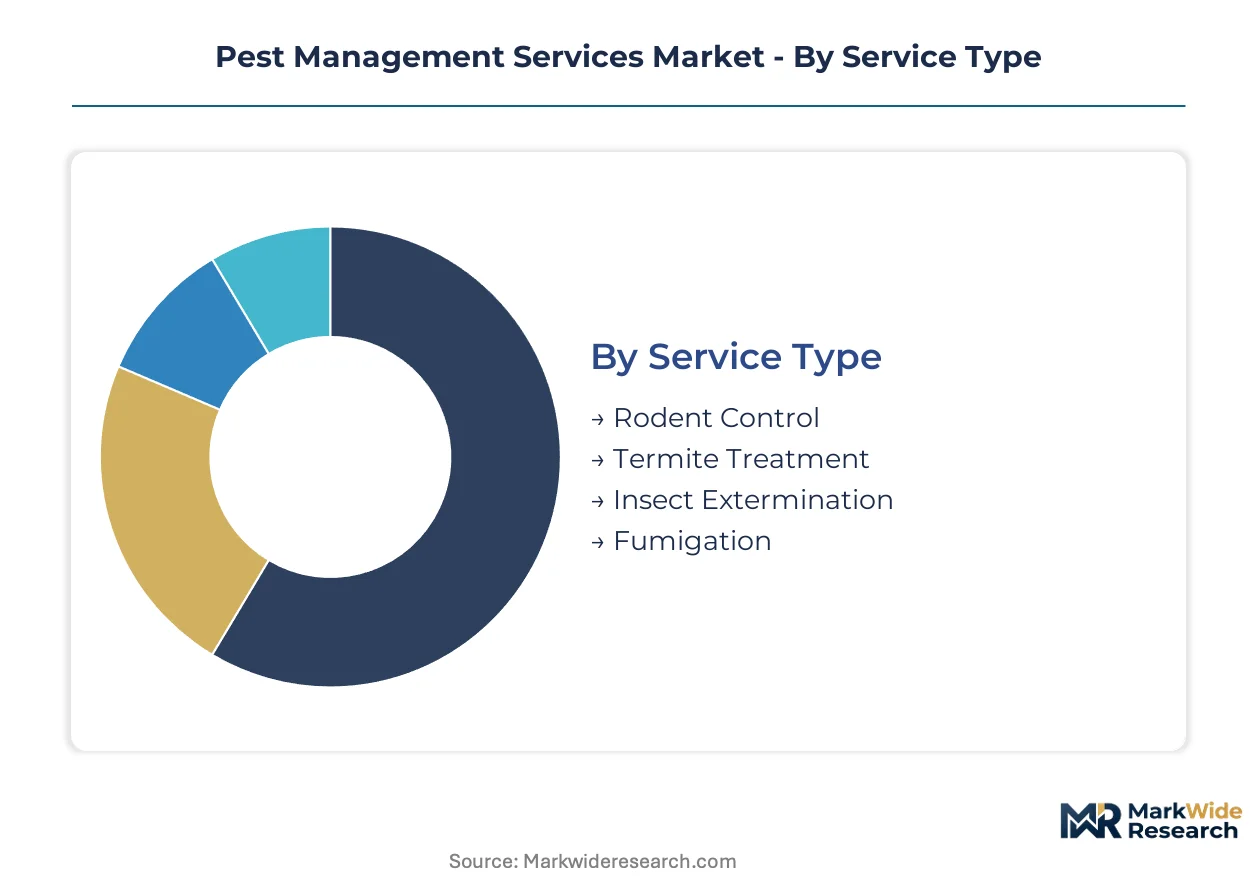
Service specialization dictates margin structure and capital intensity across the pest management sector. Technology selection increasingly determines regulatory compliance posture and contract renewal rates. Distribution channel configuration shapes geographic reach and customer acquisition economics.
Service Type:
Application complexity and warranty obligations separate premium service tiers from commodity offerings.
- Termite Treatment:Specialized baiting systems and soil barrier applications require structural warranty coverage spanning multiple years. Demand concentrates in United States Sun Belt states where subterranean termite pressure drives annual contract renewals and elevates customer lifetime value.
- Insect Extermination:Residual insecticide barriers and targeted crack-and-crevice applications address cockroach, ant, and occasional invader populations. Food processing facilities in the United States specify these services under FSMA preventive controls mandates with documented intervention thresholds.
- Rodent Control:Exclusion protocols and trapping programs target commensal rodent populations in urban commercial corridors.
- Fumigation:Whole-structure gas treatments address commodity storage and shipping container infestations with specialized containment requirements.
Termite treatment commands the established base. The steepest expansion runs through integrated pest management protocols embedded in commercial contracts.
End User:
Customer type determines service frequency, pricing power, and procurement sophistication.
- Commercial:Multi-year service agreements with documented audit trails dominate property management and food manufacturing verticals. United States municipal procurement standards now mandate IPM protocols for public buildings, compressing calendar-based chemical spraying margins.
- Residential:Quarterly perimeter treatments and emergency response calls generate highest transaction frequency with lower per-event pricing.
- Agriculture:Field crop and greenhouse operations require seasonally intensive programs aligned with harvest windows and export phytosanitary requirements.
- Hospitality:Brand reputation sensitivity drives zero-tolerance pest policies with 24-hour response SLAs in hotel and restaurant operations.
Commercial contracts anchor provider revenue stability. Residential channels deliver volume velocity but compress margin through price transparency.
Distribution Channel:
Route density and customer relationship ownership vary sharply across go-to-market configurations.
- Franchising:Orkin and similar networks achieve metropolitan coverage through owner-operated branches with localized customer relationships and technician retention.
- Direct Sales:National accounts teams pursue enterprise contracts with centralized procurement and multi-site standardization requirements.
- Online:Digital booking platforms aggregate consumer demand for one-time services with limited technician assignment control.
- Retail:Big-box partnerships move DIY pesticide formulations with professional service upsell attachments.
Franchising controls the incumbent footprint. Direct sales penetration is climbing fastest among food safety-audited manufacturing verticals.
Technology:
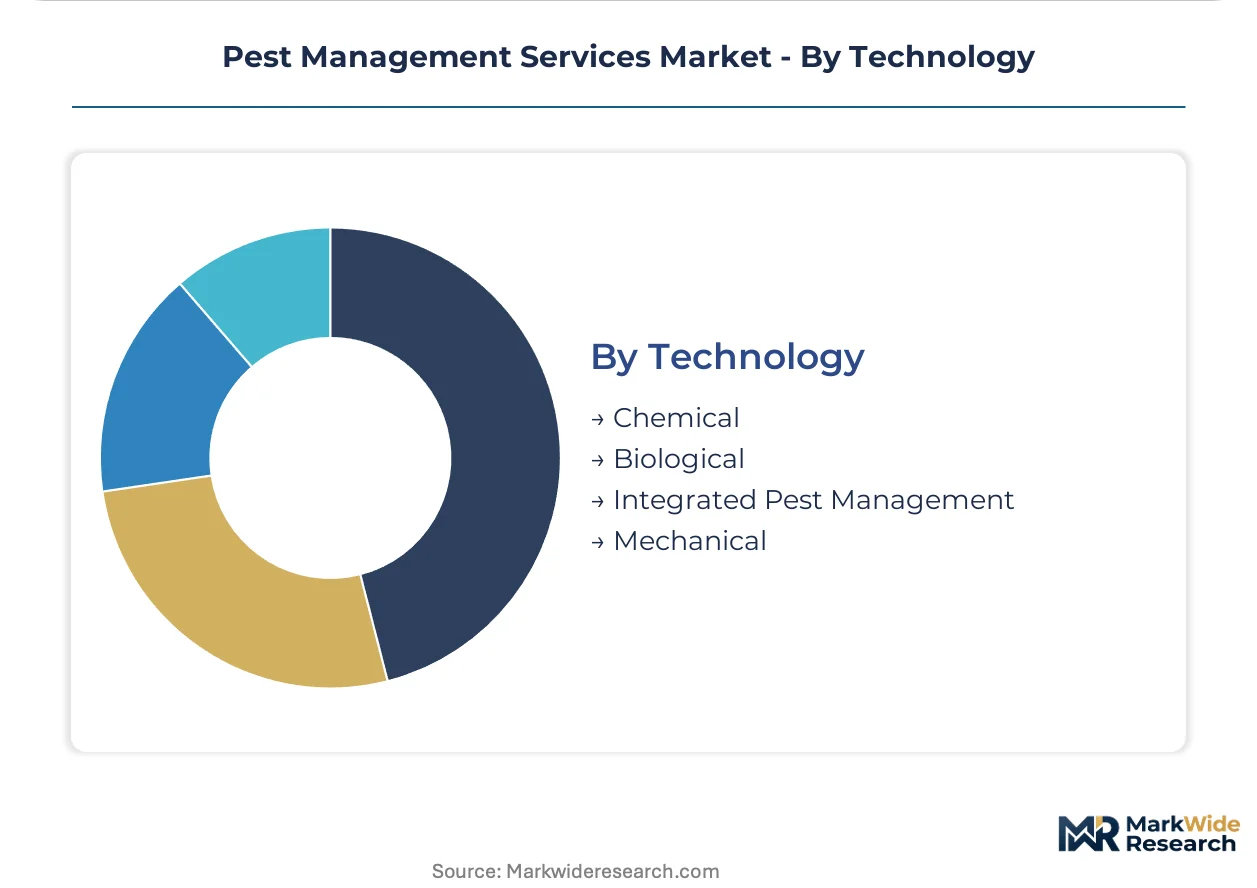
Regulatory pressure on active ingredients is accelerating chemistry portfolio transitions.
- Integrated Pest Management:Threshold-driven biological and mechanical interventions displace preventive spraying through monitoring-based decision protocols. United States EPA biopesticide registration expansions under Section 3 pathways enable service provider formulation diversification beyond conventional neurotoxic chemistry.
- Chemical:Pyrethroid and neonicotinoid formulations face ECHA biocidal product authorization reviews cascading from EU Green Deal Farm-to-Fork targets.
- Biological:Pheromone disruption and beneficial organism releases target specific pest populations with reduced non-target effects.
- Mechanical:Physical exclusion, heat treatment, and trapping systems address regulatory restrictions on indoor pesticide application.
Chemical applications retain the volume base. IPM adoption is expanding most quickly through municipal procurement mandates and third-party audit requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pest management providers export technical expertise and equipment packages to Canadian and Mexican facilities seeking FSMA-aligned audit protocols. Cross-border service agreements concentrate in Great Lakes manufacturing corridors and maquiladora zones.
United States
Commercial real estate portfolios and food processing facilities drive contracted service expansion. EPA FIFRA registration pathways under Section 3 accelerate biopesticide approvals for professional applicators. Service density clusters in Sun Belt states where subterranean termite pressure sustains multi-year warranty contracts.
Germany
Industrial facility managers specify heat treatment and biological control agents in procurement tenders. ECHA biocidal product authorization reviews cascade from EU Green Deal Farm-to-Fork targets, withdrawing chlorpyrifos formulations. Chemical producers in the Rhine-Ruhr region reformulate professional use catalogs toward reduced-risk chemistry.
China
Urban densification and export-oriented food manufacturing expand commercial pest control demand. The Ministry of Ecology and Environment tightens pesticide discharge standards for applicator operations. Yangtze River Delta warehousing clusters adopt IoT-enabled monitoring for stored-product moth prevention.
India
Swachh Bharat Mission sanitation infrastructure investments create municipal vector control tender opportunities. Central Insecticides Board registration requirements govern pyrethroid formulations deployed in urban corridors. Maharashtra and Gujarat pharmaceutical manufacturing zones specify third-party audited pest programs for export compliance.
Brazil
Agricultural commodity storage and urban commercial property growth sustain service provider expansion. ANVISA pesticide re-registration reviews align with Mercosur harmonization pressures. São Paulo state food processing corridors concentrate demand for documented intervention threshold protocols.
Pest Management Services Market Vendor Landscape
On the supply side, the industry is consolidating through regional operator acquisitions and franchise network densification. Three archetypes dominate: chemistry-anchored conglomerates with agricultural adjacencies, service-specialized operators with dense branch infrastructure, and technology-integrated platforms deploying predictive monitoring. Competitive moves center on M&A for route density and strategic partnerships for sensor network deployment.
Within the integrated service tier, Rentokil Initial plc and Rollins, Inc. exemplify branch-level coverage models, while Ecolab Inc. occupies a position bridging food safety compliance and pest management protocols. These operators represent contrasting approaches to technician workforce scale and customer relationship ownership across metropolitan corridors.
| Leading Market Players |
|---|
| Rentokil Initial plc |
| Rollins, Inc. |
| Ecolab Inc. |
| The ServiceMaster Company, LLC. |
| BASF SE |
| Bayer AG |
| Anticimex |
| FMC Corporation |
| Syngenta |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese pyrethroid active ingredient production is compressing formulation costs for service providers while simultaneously elevating price competition in commoditized residential spraying segments. This utilization dynamic rewards operators with backward-integrated chemistry sourcing or proprietary biopesticide portfolios that escape commodity pricing gravity.
Pricing Analysis
Current-generation chemical barrier treatments, prior-generation calendar-spray maintenance contracts, and next-generation IoT-enabled predictive service models occupy distinct pricing strata. Three-tier pricing structure across predictive monitoring, integrated management protocols, and reactive emergency response separates technology-enabled providers from commodity applicators. Pricing pressure stems from EPA biopesticide registration expansions that dilute chemistry differentiation and compress premium capture for conventional neurotoxic formulations. Residential end users exhibit highest price sensitivity through digital platform transparency, while food processing facilities under FSMA mandates demonstrate lowest sensitivity due to audit failure costs.
Supply Chain Analysis
Contract manufacturing of pheromone lure substrates and sensor hardware concentrates in Shenzhen electronics clusters and Jiangsu chemical processing zones. Active ingredient synthesis draws from Zhejiang pyrethroid producers and Hubei neonicotinoid specialists, with formulation packaging anchored in Texas and Ohio distribution hubs. Single-source vulnerability in Chinese active ingredient supply exposes service providers to tariff volatility and phytosanitary export delays. Distribution runs through franchised branch networks for commercial accounts and digital booking platforms for residential demand aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in municipal procurement niches where IPM mandates outpace incumbent technician certification capacity. Procurement is shifting from bundled equipment-service contracts toward unbundled monitoring subscriptions that favor specialized sensor platform providers.
For Market Incumbents: Pre-empt biopesticide formulation commoditization by securing exclusive distribution agreements with EPA-registered microbial product developers. Consolidate regional operators in Sun Belt states where termite warranty contracts anchor customer lifetime value. Vertical integration into pheromone lure manufacturing reduces sensor network deployment costs and defends margin position against standalone hardware suppliers. For New Entrants and Emerging Players: Build out avian deterrent service capabilities targeting airport authority wildlife hazard mandates, a segment with limited specialist competition and premium pricing power. India urban municipal vector control tenders represent the most penetrable geography, with Swachh Bharat Mission infrastructure investments outpacing established operator presence. Partner with IoT hardware OEMs to white-label predictive monitoring platforms for pharmaceutical manufacturing verticals requiring documented intervention thresholds. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-enabled monitoring segments as hardware commoditization reduces deployment costs. Long-term viability over the coming decade favors operators with dense branch infrastructure capable of same-day emergency response SLAs. Acquisition targets should demonstrate technician certification reciprocity across multiple state jurisdictions. The signal to watch is EPA Section 3 registration velocity for microbial formulations, indicating chemistry portfolio transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Deployment | IoT-enabled trap arrays compress emergency response revenue while expanding recurring monitoring contract penetration. |
| Biopesticide Registration Investment | EPA Section 3 pathway expertise diversifies chemistry portfolios beyond conventional neurotoxic formulations facing withdrawal. |
| State Certification Reciprocity Expansion | Multi-jurisdictional technician licensing enables cross-border workforce deployment and accelerates regional consolidation. |
| Food Safety Audit Alignment | FSMA preventive controls documentation capabilities secure multi-year manufacturing contracts with elevated switching costs. |
| Green Building Certification Integration | LEED v4.1 and WELL Building Standards IPM prerequisites create specification advantages in commercial real estate procurement. |
Methodological Framework
The analysis maps termite treatment, insect extermination, rodent control, and integrated pest management service lines, each validated through entomology technical directors, facility maintenance managers, and state department of agriculture licensing officials. Primary interviews with franchise operations executives, commercial property procurement leads, and food safety audit specialists were cross-referenced against EPA FIFRA registration databases, OSHA enforcement records, and municipal procurement contract disclosures. Secondary validation drew from state pesticide regulatory filings, branch-level service route data, and third-party audit certification registries. Bottom-up technician workforce modeling and top-down contract value aggregation were triangulated to reconcile segment estimates.
Assumptions held fixed include EPA biopesticide registration pathway timelines and state-level certification reciprocity rules, while variables included IoT sensor adoption velocity and EU Green Deal regulatory cascade timing. The projection horizon spans service type, end user vertical, distribution channel, and technology category dimensions. CAGRs were derived from contract renewal rate analysis and monitoring hardware penetration curves. Forecast inputs incorporated technician labor supply constraints and active ingredient import tariff exposure.
Stress conditions across EPA registration delays, pollinator protection label amendments, and pyrethroid supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that state-level licensing fragmentation or accelerated neonicotinoid withdrawal could materially revise trajectory. Quarterly review of EPA Section 3 approval velocity and municipal IPM procurement mandate adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Fungicide Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Propiconazole Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Europe Molluscicides Market
Crop Protection
US Pest Control Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Global Turf Protection Market
Crop Protection
North America Nematicides Market
Crop Protection
Fumigation Service Market
Crop Protection
India Herbicide Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Global Termite Control Market
Crop Protection
Global Algaecides Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Chile Crop Protection Chemicals Market