
 Microbial Agricultural Inoculants Market | 2026-2036
Microbial Agricultural Inoculants Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Agricultural Inoculants Market Foresight
Strain purity certification at 10⁸ CFU per gram is collapsing the gap between commodity inoculants and premium biologicals. BASF SE leverages its Rhizovital platform to anchor microbial formulation leadership across European cereal systems. Bayer AG sustains R&D intensity through its BioScience division, while Novonesis A/S differentiates via enzymatic co-formulation expertise in legume nodulation products.
Microbial agricultural inoculants are live microbial preparations, typically formulated at 1×10⁶ to 1×10⁹ viable cells per milliliter, applied to seeds or soil to enhance nutrient acquisition, nitrogen fixation, or disease suppression in crop systems. Their primary commercial purpose is to reduce synthetic fertilizer dependency while maintaining yield trajectories in intensive and organic farming alike. Bacteria-based formulations dominate volume due to established rhizobial and azotobacter manufacturing infrastructure, though biopesticides containing entomopathogenic fungi command premium positioning in fruit and vegetable applications. The cereals application segment absorbs the largest share of bacterial inoculants, yet legume systems generate disproportionate margin capture through strain-specific matching requirements.
The US EPA regulates microbial pesticides under FIFRA, while the EU Fertilizing Products Regulation harmonizes CE-marking requirements for biostimulant inoculants across member states. Brazil's national agricultural regulator enforces MAPA registration for imported biological formulations, creating a compliance threshold that filters non-specialized suppliers. India's Central Insecticides Board mandates CIBRC clearance for biopesticide microbes under the Insecticides Act. Stakeholders must monitor evolving strain patent landscapes and country-specific efficacy trial protocols to secure durable market access.
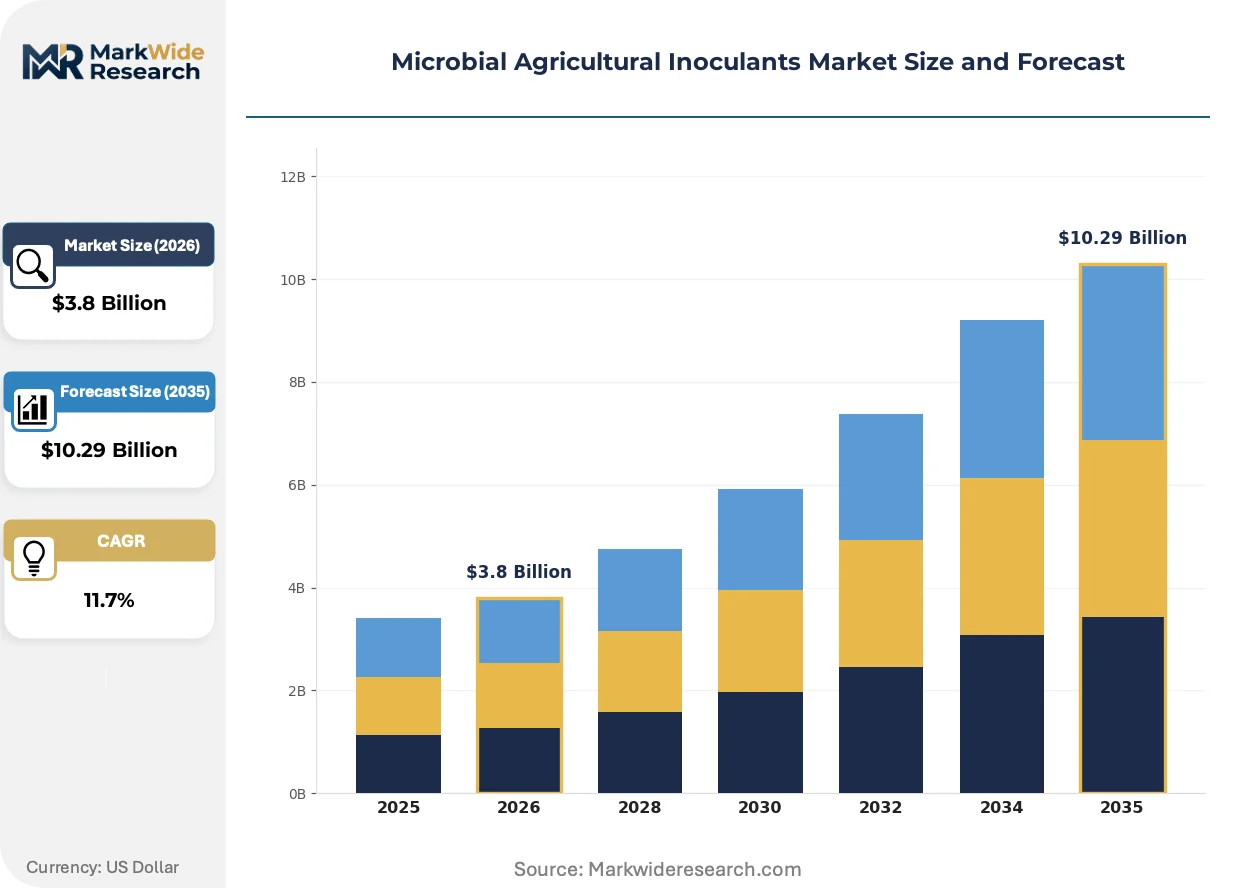
Market Dynamics
Strain certification thresholds at 10⁸ CFU per gram are compressing margins for undifferentiated suppliers while rewarding vertically integrated formulators with captive fermentation capacity.
Growth Catalysts
- EU Fertilizing Products Regulation:Harmonized CE-marking pathways accelerate biostimulant registration timelines across member states, reducing multi-market compliance costs for specialized inoculant developers.
- Soybean-corn rotation intensity:Row-crop producers in Brazil's Cerrado expansion zones and the US Corn Belt are embedding rhizobial inoculants as standard practice, creating sustained pull for high-purity formulations.
- Enzymatic co-formulation advances:Novonesis and comparable specialists are integrating lytic enzymes with nodulation bacteria, extending shelf stability and improving rhizosphere colonization rates in legume systems.
Market Restraints
- Fermentation input volatility:Molasses and yeast extract prices fluctuate with sugar commodity cycles, compressing gross margins for manufacturers lacking long-term agricultural feedstock contracts.
- Brazil MAPA registration concentration:Imported biological formulations face extended efficacy trial protocols, filtering non-specialized suppliers and consolidating access among established registrants.
- Live-cell stability constraints:Temperature excursion tolerance remains technically limited, restricting distribution radius and cold-chain economics for premium multi-strain products.
Strategic Opportunities
- India CIBRC pathway expansion:Central Insecticides Board clearance protocols for biopesticide microbes under the Insecticides Act create first-mover positioning in underpenetrated rice-wheat systems.
- RNA-interference convergence:Pairing RNAi triggers with entomopathogenic fungi enables dual-mode pest suppression, opening premium positioning in protected vegetable cultivation.
- Direct-to-farm digital channels:Agronomic advisory platforms are disintermediating traditional cooperatives, enabling strain-specific matching services that capture margin from precision application.
Industry Challenges
- Strain characterization expertise scarcity:Functional genomics and metabolomic profiling capabilities remain concentrated among academic and large-formulator laboratories, constraining independent verification.
- Multi-jurisdiction patent thickets:Overlapping claims on rhizobial strain modifications and formulation adjuvants complicate freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Agricultural Inoculants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Biofertilizers, Biopesticides Application: Cereals, Fruits, Vegetables, Legumes End User: Agricultural Producers, Organic Farmers, Commercial Growers, Home Gardeners Distribution Channel: Online Retailers, Agricultural Supply Stores, Direct Sales, Distributors |
| Companies Covered | BASF SE, Bayer AG, Corteva, Syngenta Group, UPL, Nufarm, Novonesis A/S, FMC Corporation, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Agricultural Inoculants Market Shifts & Advancements
Live-cell formulation science is splitting the competitive landscape between commodity manufacturers and precision biological specialists, with certification standards and delivery mechanisms driving divergence.
Multi-strain consortia containing both nitrogen-fixing bacteria and phosphate-solubilizing fungi are bifurcating the cereals inoculant segment. Large-scale grain operations in Argentina and Ukraine are adopting these combinations at accelerating rates. This convergence is compressing standalone bacterial products into price-tendered commodity tiers while elevating integrated formulations to premium positioning.
REACH registration requirements for microbial metabolites are tightening disclosure obligations for European biostimulant suppliers. Industrial consequence includes elevated toxicology study costs and extended dossier preparation timelines. Specialty fruit and vegetable formulators are responding by consolidating strain libraries and outsourcing regulatory compliance to specialized consultancies.
Certification-driven procurement now dominates large-scale row-crop purchasing decisions, displacing price-first supplier selection. Agricultural cooperatives in the US Midwest and Paraná state are mandating third-party CFU verification and strain-identity documentation. This behavioral shift is most visible in soybean seed treatment contracts, where guaranteed nodulation scores now determine supplier retention.
Microbial Agricultural Inoculants Market Segmentation
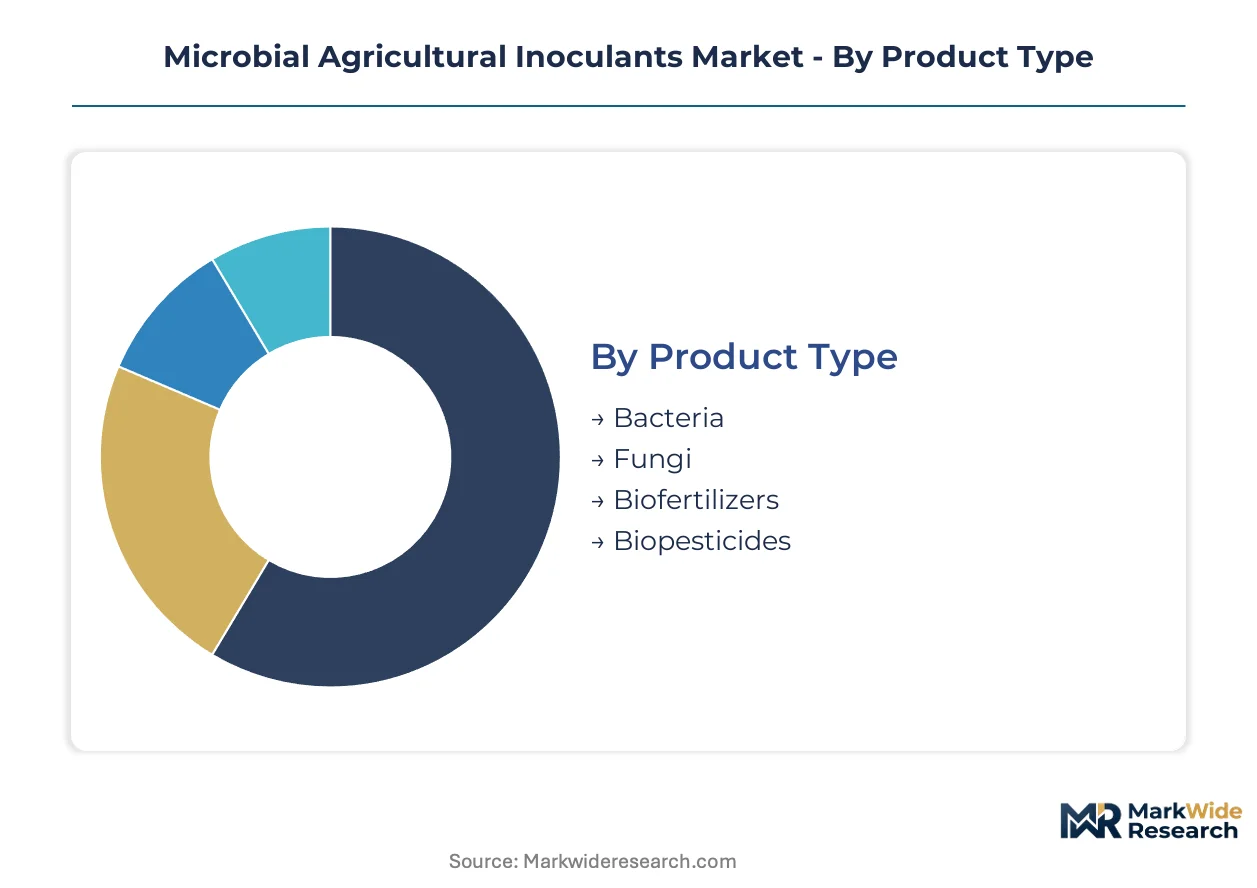
Segmentation in microbial agricultural inoculants determines margin capture and regulatory pathway complexity. Strain certification requirements and application-specific efficacy protocols fragment competitive positioning across product tiers and end-use channels.
Product Type:
Biopesticides face acute substitution pressure from synthetic chemistries and RNA-interference technologies, while bacteria-based formulations benefit from entrenched manufacturing infrastructure and farmer familiarity.
- Bacteria:Rhizobial and azotobacter preparations dominate commercial volumes through established nitrogen-fixation protocols in soybean and corn systems. Demand concentrates in Brazil's Cerrado expansion zones and the US Corn Belt, where row-crop producers embed inoculants as standard rotation practice.
- Fungi:Entomopathogenic and mycorrhizal formulations command premium positioning in high-value fruit and vegetable applications, though temperature stability constraints restrict distribution radius. European protected cultivation clusters absorb disproportionate share of Trichoderma-based soil treatments.
- Biofertilizers:Multi-strain consortia integrating phosphate-solubilizing microbes with nitrogen-fixing bacteria are displacing standalone products in Argentine and Ukrainian grain operations.
- Biopesticides:Beauveria bassiana and Metarhizium formulations target chewing insect complexes in organic vegetable systems, requiring EPA FIFRA or EU Fertilizing Products Regulation registration for market access.
Bacteria retains volume leadership; biopesticides holds the steepest expansion curve.
Application:
Cost-tier stratification separates commodity grain applications from premium horticultural systems, with certification-grade requirements driving divergence in procurement behavior.
- Cereals:Wheat, corn, and rice systems absorb the largest bacterial inoculant volumes through seed treatment and soil drench applications. Procurement in the US Midwest and India's rice-wheat belt prioritizes CFU verification and strain-identity documentation over price tendering.
- Legumes:Soybean, pea, and lentil cultivation generates disproportionate margin capture through strain-specific rhizobial matching requirements. Brazil's MAPA registration mandates filter non-specialized suppliers, consolidating access among established formulators.
- Fruits:Orchard and vineyard applications favor fungal biopesticides for soil-borne disease suppression, with EU REACH registration requirements elevating toxicology study costs for metabolite disclosure.
- Vegetables:Protected cultivation in Spain's Almería region and China's Shandong province drives demand for entomopathogenic fungi with extended shelf stability specifications.
Cereals retains volume leadership; legumes holds the steepest expansion curve.
End User:
Customer-type fragmentation creates parallel channel strategies, with commercial scale operations demanding certification rigor that home gardeners ignore.
- Agricultural Producers:Large-scale row-crop operations in North America and Brazil mandate third-party CFU verification and guaranteed nodulation scores in supplier contracts. Direct-to-farm digital channels are disintermediating traditional cooperatives for strain-specific matching services.
- Commercial Growers:Specialty fruit and vegetable operations in California's Central Valley and Italy's Po Valley prioritize enzymatic co-formulation advances for rhizosphere colonization rates.
- Organic Farmers:Certification-compliant input requirements under USDA Organic or EU Organic Regulation restrict acceptable strain sources and adjuvant chemistries.
- Home Gardeners:Small-format retail packaging through online channels captures margin from convenience positioning, though live-cell stability constraints limit product assortment.
Agricultural Producers retains volume leadership; Commercial Growers holds the steepest expansion curve.
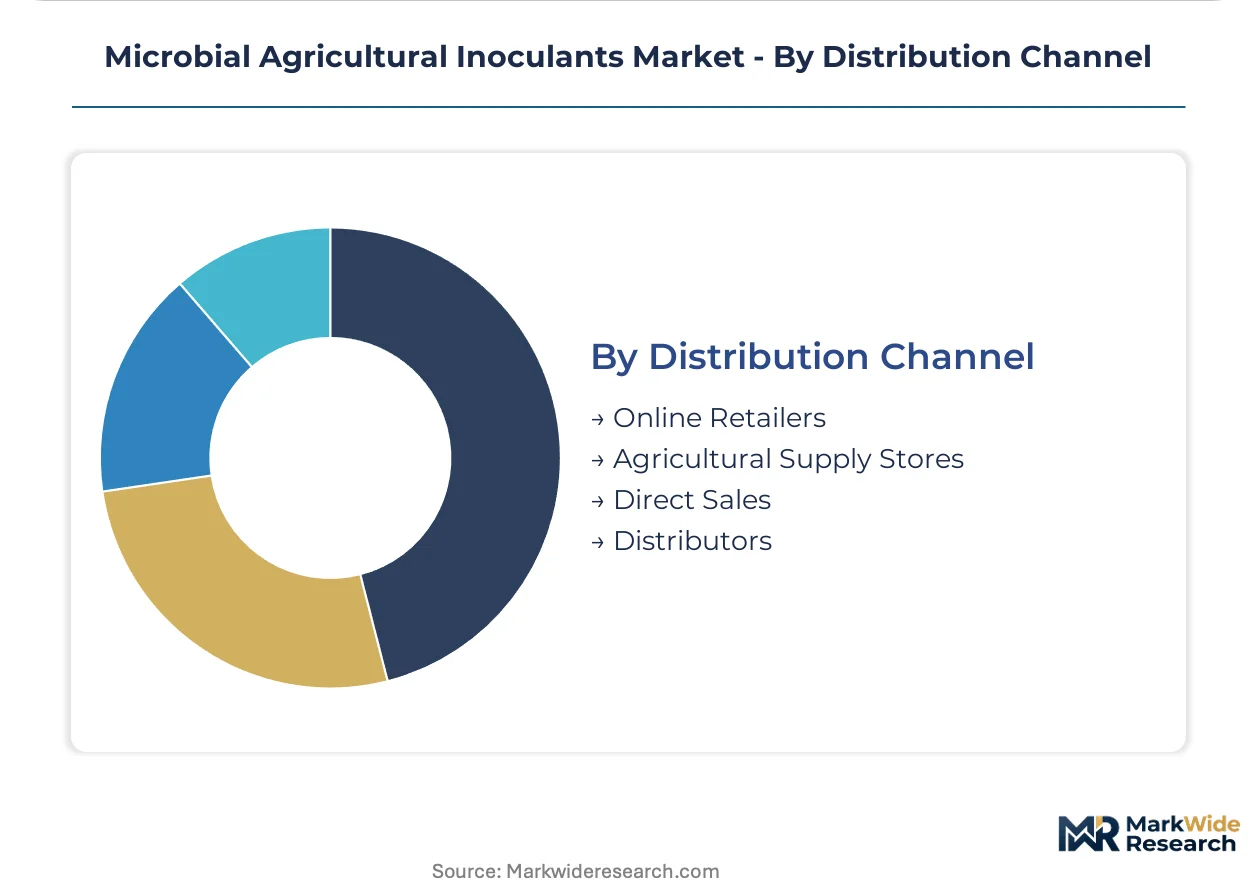
Distribution Channel:
Supply concentration among agricultural supply stores faces disintermediation pressure from direct digital channels and manufacturer-owned distribution assets.
- Agricultural Supply Stores:Cooperative and independent retail networks in the US Corn Belt and Brazil's Mato Grosso state maintain inventory depth for commodity bacterial formulations. Cold-chain infrastructure investments determine premium product access.
- Direct Sales:Manufacturer agronomist teams provide strain-matching advisory services that capture margin from precision application in soybean seed treatment contracts.
- Distributors:Regional biological specialists manage MAPA and EPA registration complexity for imported formulations, filtering market access.
- Online Retailers:E-commerce platforms penetrate home gardener and small-scale organic segments, though temperature excursion tolerance restricts live-cell product assortment.
Agricultural Supply Stores retains volume leadership; Direct Sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity and registration infrastructure cluster in jurisdictions with established biologics manufacturing. Brazil, the United States, Germany, India, and Argentina concentrate strain development, regulatory expertise, and farmer adoption networks.
Brazil
Soybean-corn rotation intensity in Mato Grosso and Paraná drives rhizobial inoculant consumption at industrial scale. MAPA registration protocols filter imported formulations, consolidating access among established domestic and multinational registrants. The Cerrado expansion zones around Rondonópolis embed inoculants as standard agronomic practice.
United States
The Corn Belt's row-crop producers mandate third-party CFU verification in seed treatment contracts. EPA FIFRA oversight governs biopesticide microbes while USDA programs incentivize nitrogen-fixation alternatives. Chicago-based cooperatives and Des Moines agronomy platforms disintermediate traditional supply chains for strain-matching services.
Germany
European cereal systems absorb bacterial formulations through Rhine-Ruhr distribution networks. ECHA REACH requirements tighten metabolite disclosure for biostimulant suppliers, elevating toxicology study costs. BASF's Ludwigshafen operations anchor microbial formulation leadership across EU member states.
India
Rice-wheat belt procurement in Punjab and Haryana prioritizes biofertilizer cost efficiency over certification rigor. CIBRC clearance under the Insecticides Act creates compliance thresholds for biopesticide microbes. Maharashtra's Pune-Nashik corridor houses domestic fermentation capacity serving western and southern markets.
Argentina
Pampas grain operations adopt multi-strain consortia at accelerating rates, displacing standalone bacterial products. The national agricultural regulator enforces efficacy trial protocols for imported biologicals. Rosario's trading and logistics cluster concentrates formulation distribution for Mercosur export channels.
Microbial Agricultural Inoculants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated agrochemical conglomerates with captive fermentation capacity occupy premium positioning, while regional specialists compete on price in undifferentiated bacterial formulations. Three archetypes dominate: multinational platform owners, enzymatic co-formulation specialists, and commodity fermentation contractors. Consolidation pressure operates through MAPA registration accumulation in Brazil and EPA registration bundling in the United States.
Among diversified chemical conglomerates, BASF SE and Bayer AG exemplify platform-scale microbial capabilities, while Novonesis A/S occupies a distinct position as an enzymatic co-formulation specialist. These three anchors represent divergent strategic postures—captive supply chain control, R&D-intensive biological pipelines, and enzyme-bacteria integration expertise—each commanding different margin structures and customer retention mechanisms in legume and cereal systems alike.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva |
| Syngenta Group |
| UPL |
| Nufarm |
| Novonesis A/S |
| FMC Corporation |
| Sumitomo Chemical |
| Others |
Supply & Pricing Matrix
Molasses-to-yeast-extract substitution in fermentation media simultaneously redraws procurement geography toward Brazilian sugarcane belts and compresses gross margins for manufacturers lacking long-term agricultural feedstock contracts. This input pivot concentrates bargaining power among vertically integrated formulators with captive fermentation capacity while forcing spot-market buyers into price-tendered commodity tiers.
Pricing Analysis
The EU Fertilizing Products Regulation dictates the pricing tier structure across European biostimulant markets, mandating CE-marking compliance costs that stratify offerings by certification grade and strain-identity documentation. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed-nodulation-score formulations from undifferentiated bacterial products. Cost compression in standard tiers is intensifying because MAPA registration accumulation in Brazil filters non-specialized suppliers. Agricultural cooperatives in the US Midwest demonstrate least price sensitivity due to outcome-based procurement mandates, while India's rice-wheat belt buyers prioritize cost efficiency over certification rigor.
Supply Chain Analysis
Strategic stockpiling of freeze-dried master cultures dominates inventory strategy among premium formulators, contrasting with just-in-time molasses procurement that exposes commodity manufacturers to sugar commodity cycles. Manufacturing gravity centers on Brazil, Germany, and India, where fermentation infrastructure clusters near downstream agricultural demand. Raw material sourcing draws from Brazilian sugarcane molasses, European yeast extract processors, and Indian phosphate-solubilizing mineral deposits. Single-source vulnerability in rhizobial strain libraries creates concentration risk for multi-strain consortia producers. Distribution runs through agricultural supply cooperatives in the US Corn Belt and MAPA-registered distributors in Brazil's Mato Grosso state.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial agricultural inoculants are transitioning toward platform-economics dynamics where strain-matching algorithms and direct-to-farm digital channels create winner-take-most structures. Interoperability between formulation databases and precision agriculture platforms is consolidating customer switching costs around integrated ecosystem providers.
For Market Incumbents: Compound registration asset accumulation in Brazil and the United States to erect compliance barriers against emerging enzymatic co-formulation specialists. Prioritize backward integration into captive fermentation capacity to offset molasses price volatility. Deepen strain-library consolidation to defend against RNA-interference convergence threats in protected vegetable systems.
For New Entrants and Emerging Players: Anchor in India's CIBRC clearance pathway for biopesticide microbes, where regulatory infrastructure remains underdeveloped relative to demand in rice-wheat systems. Target specialty fruit and vegetable operations in Spain's Almería region with extended-shelf-stability fungal formulations. Pursue direct-to-farm digital channels that disintermediate cooperative gatekeepers for strain-specific matching services.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated formulators with MAPA and EPA registration bundling. Long-term viability hinges on accumulation of strain patent estates and enzymatic co-formulation capabilities. Acquisition targets should demonstrate metabolomic profiling expertise and established efficacy trial protocols. The signal to watch is Cerrado expansion zone procurement shifting from price-tendered to certification-mandated supplier selection.
| Strategic Initiative | Industry Significance |
|---|---|
| MAPA Registration Accumulation | Consolidates market access among established Brazilian and multinational registrants, filtering imported competition. |
| Enzymatic Co-formulation Development | Extends shelf stability and rhizosphere colonization rates, commanding premium positioning in legume systems. |
| Direct-to-Farm Digital Channel Buildout | Disintermediates agricultural cooperatives for strain-matching advisory services and precision application capture. |
| Strain Library Consolidation | Addresses REACH metabolite disclosure requirements while reducing freedom-to-operate risks from patent thickets. |
| Cold-Chain Infrastructure Investment | Expands distribution radius for temperature-sensitive multi-strain products into premium horticultural markets. |
Research Methodology
A spread of perspectives from fermentation plant managers, agricultural cooperative procurement leads, MAPA regulatory consultants, and seed treatment agronomists converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with downstream channel partners and technical R&D directors at formulation facilities. Secondary validation drew from EPA FIFRA registration databases, EU Fertilizing Products Regulation submission dossiers, MAPA biological product registries, and customs trade data on fermentation input flows. Bottom-up strain-level volume estimates were triangulated against top-down agricultural acreage penetration models.
Segmentation dimensions modeled include product type tier, crop application system, end-user scale category, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves calibrated to regulatory milestone timelines. Industry-specific forecast inputs incorporated MAPA registration approval velocities, Cerrado expansion zone planting intentions, and enzymatic co-formulation shelf-stability improvement trajectories.
Material uncertainties — strain patent litigation outcomes, molasses commodity price spikes, and RNA-interference technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway harmonization and farmer behavioral adoption thresholds. Revision becomes warranted when certification-mandated procurement penetration in soybean seed treatment contracts crosses critical mass thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Soil Inoculants Market