
 Agricultural Activator Adjuvants Market | 2026-2036
Agricultural Activator Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Activator Adjuvants Market Insights
North American surfactant producers is pivoting toward bio-based feedstocks to secure supply continuity amid petrochemical volatility. BASF SE leverages its integrated alkoxylate network to sustain cost advantages across herbicide adjuvant grades. Croda International Plc anchors its position through seed-treatment-specialized dispersants that dominate the premium formulation segment. Nufarm competes on geographic reach, with manufacturing footprints that extend across multiple agricultural basins.
Agricultural activator adjuvants are chemical or biological additives mixed with crop protection products to enhance spray droplet spreading, penetration, or retention on leaf surfaces; alkyl polyglucoside and organosilicone surfactants represent the dominant chemistries, with critical micelle concentration and equilibrium surface tension serving as key performance parameters that determine herbicide uptake efficiency. Surfactants command the largest product-type position due to their universal compatibility across glyphosate, dicamba, and glufosinate systems, while emulsifiers capture expanding share in oil-based formulation growth. Seed treatments represent the fastest-growing application vector as biological inoculant adoption drives demand for compatible wetting and dispersing systems.
The EPA enforces drift reduction technology standards and spray buffer zone requirements that directly shape adjuvant formulation specifications, while the EU REACH framework and F-Gas Regulation restrict certain fluorosurfactant chemistries and push formulators toward compliant alternatives. Brazil's national environmental regulator imposes rigorous aquatic toxicity thresholds that filter market access for non-compliant surfactant imports. Stakeholders must monitor evolving residue tolerance harmonization between major importing jurisdictions to anticipate reformulation cycles and registration investment priorities.
Market Dynamics
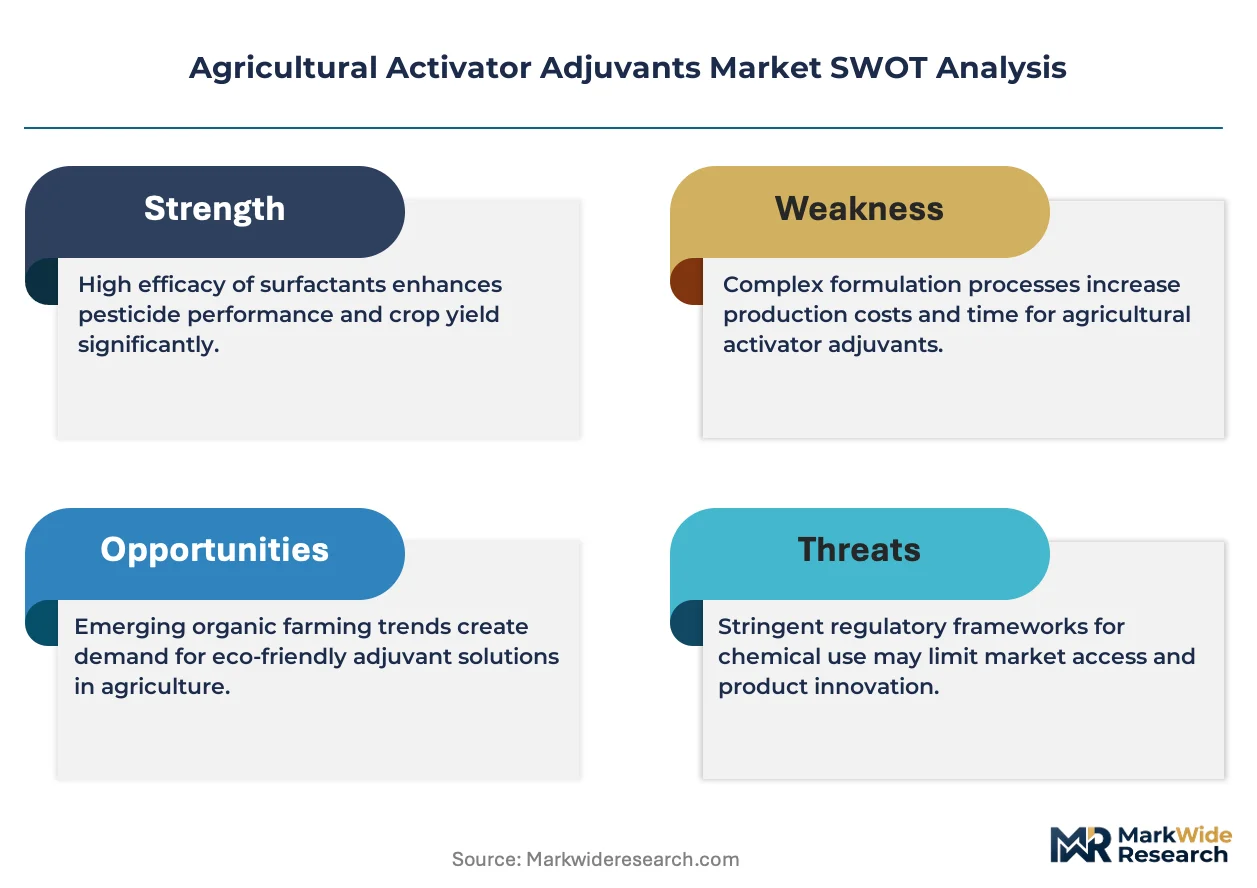
EPA drift reduction mandates and Brazil's aquatic toxicity thresholds are forcing surfactant formulators to rebuild product portfolios around low-volatile chemistries and bio-based feedstocks, compressing legacy registration timelines and redirecting R&D budgets toward compliance-first design.
Growth Catalysts
- Water restriction policies:California and Florida specialty crop operations face tightening irrigation allocations. Growers deploy activator adjuvants to maximize pesticide efficacy per gallon applied, converting water stress into demand for high-performance tank-mix partners.
- Glyphosate-resistant weed proliferation:Brazil's Cerrado soybean belt requires aggressive herbicide rotation. Adjuvant systems that unlock dicamba and glufosinate compatibility command premium positioning among large-scale operators managing resistant populations.
- REACH F-Gas fluorosurfactant phase-out:The EU restriction on persistent fluorinated chemistries creates immediate replacement demand. Formulators with compliant organosilicone and alkyl polyglucoside alternatives capture displaced volume across European agricultural markets.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and fatty alcohol price swings compress surfactant producer margins. Producers without integrated alkoxylation capacity face margin instability that constrains pricing flexibility.
- Registration timeline concentration:EPA 25(b) exempt status and full registration pathways bottleneck new entrants. The multi-year approval cycle for novel adjuvant chemistries limits competitive refresh rates.
- Biological inoculant incompatibility:Living microbial seed treatments degrade when exposed to conventional surfactant systems. Formulators lacking biological-compatible dispersant portfolios forfeit the fastest-growing application vector.
Strategic Opportunities
- Seed treatment biological convergence:Nitrogen-fixing and phosphorus-solubilizing inoculants require specialized wetting agents. Adjuvant suppliers with seed-treatment-dedicated R&D facilities capture premium positioning in this white space.
- ANVISA aquatic toxicity compliance arbitrage:Brazil's regulator maintains stricter surfactant environmental thresholds than neighboring Mercosur markets. First-movers with pre-validated low-toxicity portfolios establish defensive moats before regional harmonization.
- Drone application spray optimization:UAV spraying systems demand ultra-low-volume droplet engineering. Adjuvant formulators developing drift-reduction and evaporation-suppression chemistries for aerial platforms access an underdeveloped channel.
Industry Challenges
- Formulation chemist talent scarcity:The intersection of surfactant science, pesticide compatibility testing, and regulatory dossier preparation requires rare hybrid expertise. Recruitment competition from pharmaceutical and personal care sectors constrains R&D expansion.
- Residue tolerance harmonization complexity:MRL alignment between EPA, EFSA, and ANVISA remains incomplete. Formulators must maintain parallel product variants, multiplying inventory costs and complicating global supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Activator Adjuvants Market |
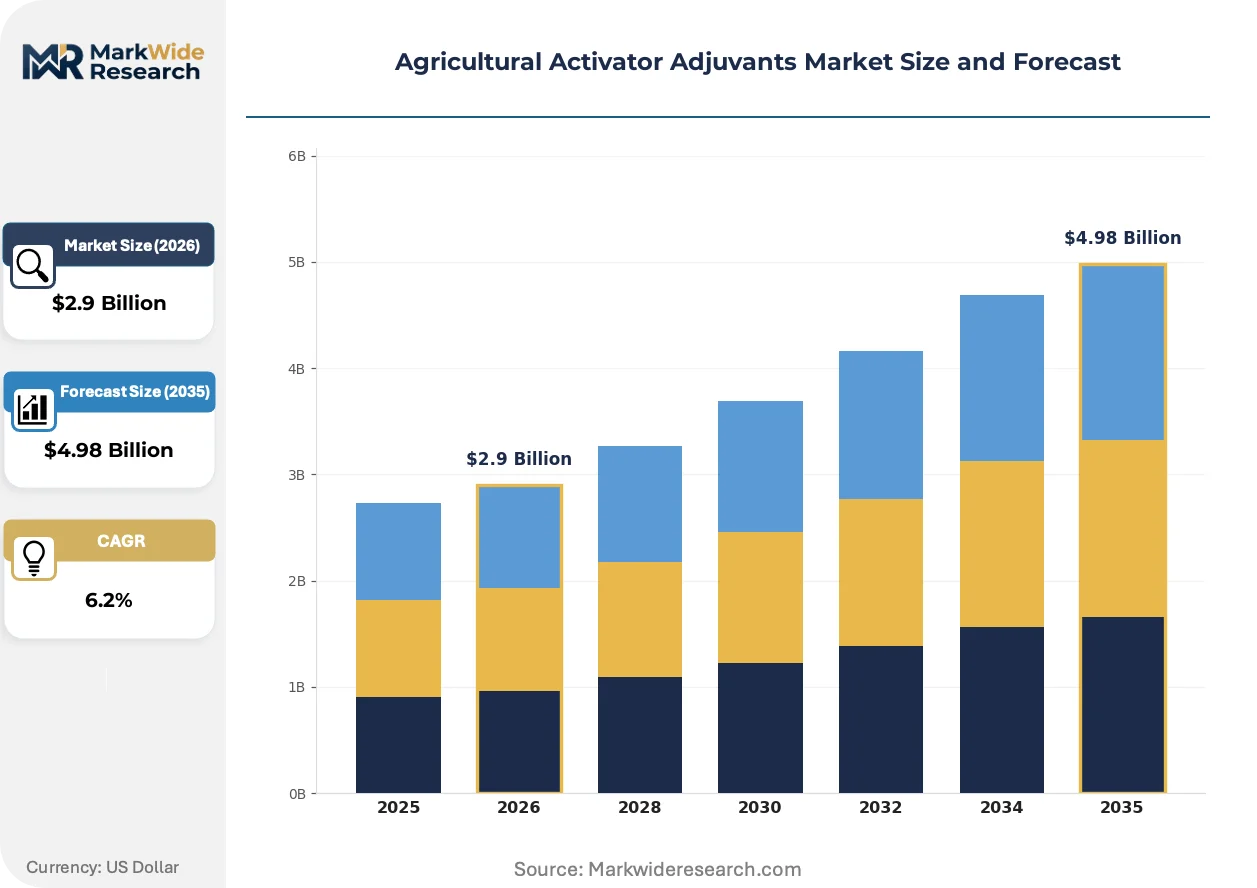
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Surfactants, Solubilizers, Dispersants Application: Herbicides, Insecticides, Fungicides, Seed Treatments Form: Liquid, Granular, Powder, Concentrate End User: Farmers, Agricultural Cooperatives, Commercial Growers, Distributors |
| Companies Covered | BASF SE, Solvay, Croda International Plc, Nufarm, CHS Inc., Stepan Company, Clariant, Evonik, Helena Agri-Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Activator Adjuvants Market Trends and Innovations
Formulation intelligence is migrating from empirical screening to predictive modeling, compressing development cycles while regulatory pressure simultaneously extends validation requirements. These intersecting forces reshape how adjuvant producers allocate technical resources.
Organosilicone super-spreading surfactants are automating droplet coverage optimization across drone and ground-rig spraying systems. Specialty crop operators in California's Central Valley and Florida's citrus belt have accelerated adoption to reduce water volumes per acre. The technology is automating the transition from volume-based to droplet-precision application protocols, compressing demand for conventional non-ionic surfactants.
EPA's updated spray drift reduction technology standards and buffer zone mandates now require documented adjuvant performance in wind tunnel validation. Formulators must redesign surfactant systems to achieve specific droplet size spectra classifications. The herbicide adjuvant segment bears the heaviest compliance burden, with glyphosate and dicamba tank-mix partners facing reformulation cycles to maintain label eligibility.
Large-scale Brazilian soybean cooperatives now consolidate adjuvant procurement through direct manufacturer contracts, bypassing traditional distribution tiers. This channel compression concentrates purchasing power among fewer buyers while rewarding suppliers with technical service capabilities and local blending infrastructure. The pattern is most visible in Mato Grosso and Goiás, where mega-farms operate integrated input sourcing programs.
Agricultural Activator Adjuvants Market Segmentation
Agricultural activator adjuvants serve divergent technical requirements across crop protection workflows. Buyers select chemistries based on compatibility with specific pesticide modes of action, application equipment constraints, and regulatory compliance burdens in their operating jurisdictions.
Product Type:
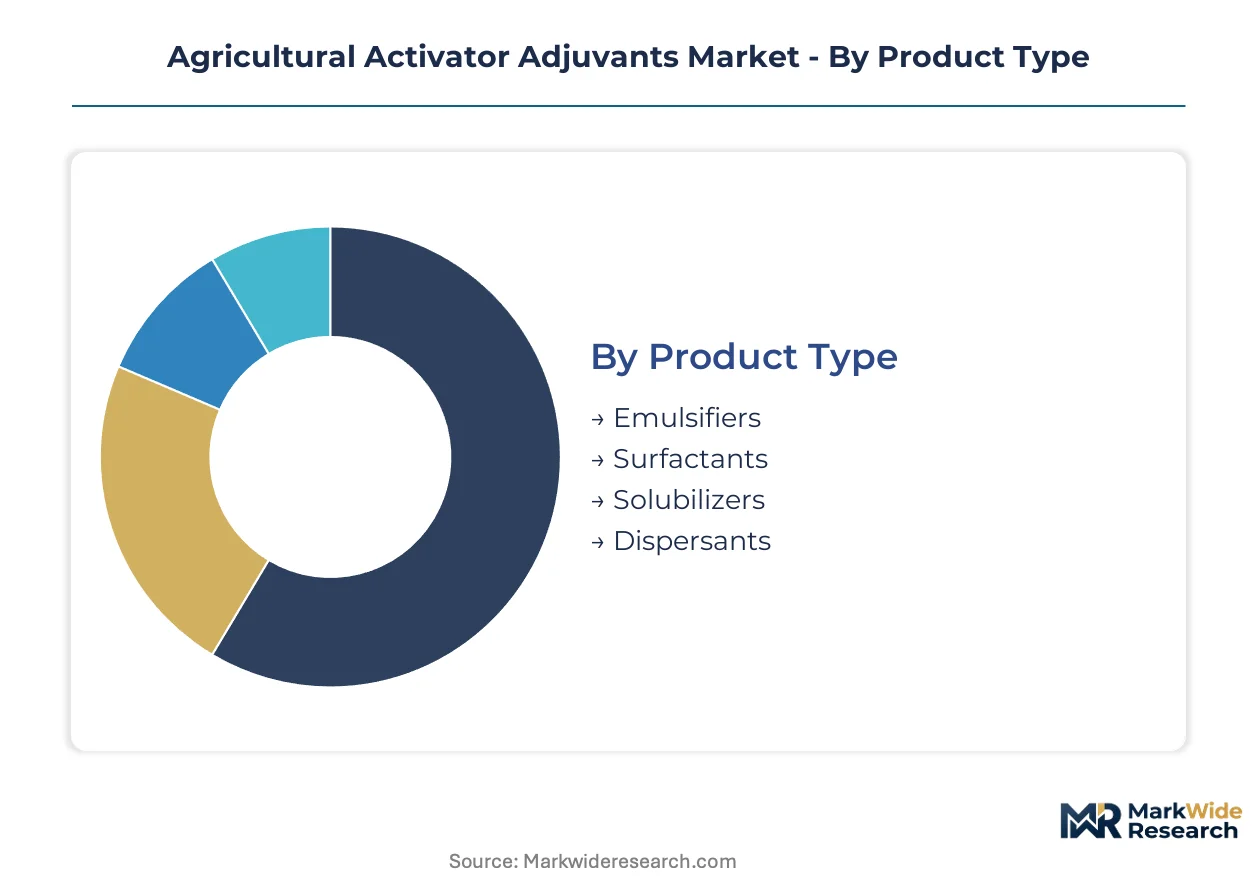
Formulation chemists prioritize surface tension reduction and emulsion stability when specifying adjuvant systems for tank-mix compatibility.
- Surfactants:Alkyl polyglucoside and organosilicone chemistries dominate herbicide tank-mix formulations. California specialty vegetable growers deploy these systems under irrigation restrictions to maximize glyphosate uptake per gallon applied.
- Emulsifiers:Oil-in-water systems stabilize petroleum-based carriers for lipophilic active ingredients. Brazil's Cerrado soybean operators require high-performance emulsifiers for dicamba and glufosinate rotation programs against resistant weed populations.
- Solubilizers:Co-solvent systems enhance water-insoluble pesticide dispersion. These additives address compatibility failures in hard water conditions prevalent across Midwestern US corn belts.
- Dispersants:Polymeric stabilizers prevent active ingredient agglomeration in suspension concentrates. Demand concentrates in seed treatment facilities preparing biological inoculant formulations.
Surfactants lead volumes today; dispersants are gaining share fastest.
Application:
Crop protection manufacturers specify adjuvant grades based on pesticide mode-of-action requirements and residue tolerance protocols in target export markets.
- Herbicides:Glyphosate, dicamba, and glufosinate systems require drift-reduction surfactants meeting EPA spray buffer zone mandates. Brazilian cooperatives consolidate procurement of these tank-mix partners for large-scale resistant weed management.
- Seed Treatments:Biological nitrogen-fixing inoculants demand specialized wetting agents preserving microbial viability. This segment climbs the fastest as microbial input adoption accelerates in North American and European row-crop markets.
- Insecticides:Penetration enhancers improve systemic neonicotinoid uptake in woody perennials. Florida citrus growers deploy these systems against Asian citrus psyllid pressure under tighter water allocation frameworks.
- Fungicides:Spreaders and stickers optimize protectant deposition on fruit surfaces. European wine grape producers specify these grades to meet EFSA residue tolerance thresholds in export-bound harvests.
Herbicide adjuvants dominate current procurement; seed treatment systems show steepest expansion trajectory.
Form:
Application equipment compatibility and storage logistics drive form selection across divergent farm scales and climatic conditions.
- Liquid:Ready-to-pour concentrates dominate commercial ground-rig operations. These forms allow rapid tank-mix preparation in Brazil's Mato Grosso mega-farms where application windows compress during seasonal weather patterns.
- Concentrate:Ultra-high-active formulations reduce freight costs for remote agricultural basins. Australian broadacre wheatbelt operators favor these systems given distribution distances from coastal manufacturing centers.
- Powder:Dry flowable grades serve aerial application platforms where liquid payload weight constrains drone range. UAV spraying contractors in California's Central Valley specify powder systems for ultra-low-volume protocols.
- Granular:Dust-free handling properties suit on-farm blending operations without sophisticated containment infrastructure. Smallholder cooperatives across India's Punjab region prefer granular forms for manual measuring accuracy.
Liquid forms capture the largest volume position; concentrates are expanding most quickly in freight-sensitive supply chains.
End User:
Procurement sophistication and technical service requirements separate buyer tiers in adjuvant specification and sourcing behavior.
- Commercial Growers:Large-scale specialty crop operators in California and Florida maintain direct manufacturer relationships for formulation customization. These buyers demand documented drift-reduction performance for regulatory compliance.
- Agricultural Cooperatives:Consolidated purchasing entities across Brazil's soybean belt negotiate volume contracts with technical service attachments. Co-ops increasingly bypass traditional distribution tiers to secure blending infrastructure access.
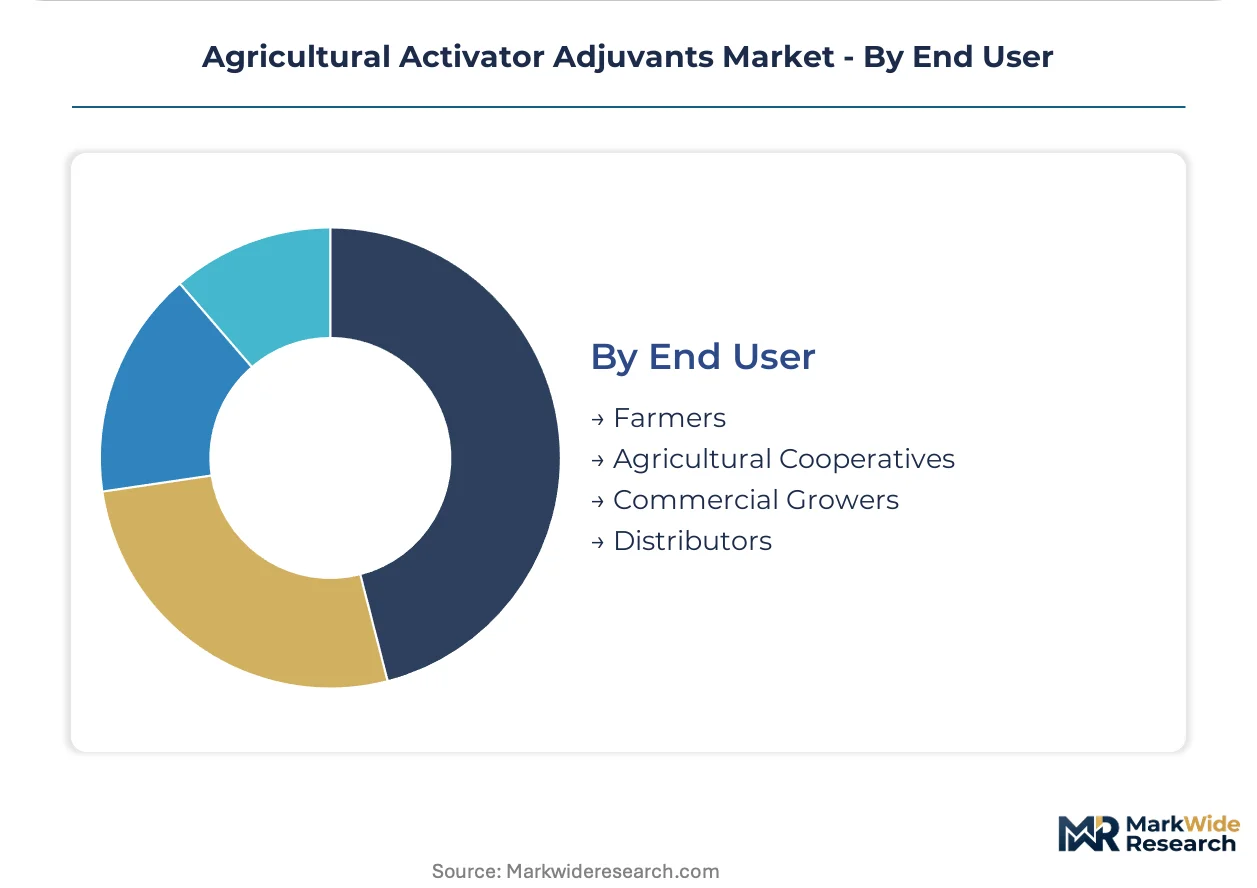
- Farmers:Individual row-crop producers rely on retailer recommendations for standard tank-mix compatibility. Price sensitivity dominates purchasing decisions in commodity crop segments with thin margin structures.
- Distributors:Regional input suppliers maintain inventory breadth across multiple crop protection portfolios. These intermediaries face margin compression as cooperative and direct-channel procurement concentrates.
Commercial growers lead absolute consumption; agricultural cooperatives are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined registration pathways and lower compliance costs. Brazil's ANVISA maintains stricter aquatic toxicity thresholds than neighboring Mercosur markets. The resulting cost-of-compliance gap attracts formulators seeking pre-validated low-toxicity portfolio positioning.
United States
California specialty crop growers and Florida citrus operators drive demand under tightening irrigation allocations. EPA drift reduction technology standards and spray buffer zone mandates reshape surfactant formulation specifications. The Central Valley cluster automates droplet-precision protocols through organosilicone super-spreading systems.
Brazil
Mato Grosso and Goiás mega-farms consolidate adjuvant procurement through direct manufacturer contracts for glyphosate-resistant weed management. ANVISA's rigorous aquatic toxicity thresholds filter market access for non-compliant surfactant imports. Large-scale cooperatives in the Cerrado region operate integrated input sourcing programs.
Germany
EU REACH framework and F-Gas Regulation restrictions on fluorosurfactant chemistries push formulators toward compliant organosilicone alternatives. Integrated alkoxylate networks sustain cost advantages across herbicide adjuvant grades. Industrial concentration in Ludwigshafen and surrounding chemical corridors anchors supply continuity.
China
Domestic glyphosate production scale generates captive demand for tank-mix surfactant systems. NMPA and evolving GB standards govern agrochemical additive registration timelines. Yangtze River Delta manufacturing clusters supply both domestic operators and export markets across Southeast Asia.
India
Punjab smallholder cooperatives prefer granular adjuvant forms for manual measuring accuracy without sophisticated containment infrastructure. BIS standards and state-level agricultural extension programs influence product specification. Distribution networks concentrate around Ludhiana and surrounding agrarian belts.
Agricultural Activator Adjuvants Market Competitive Landscape
German and Swiss producers anchor the premium formulation tier; US and Australian specialists hold positions in biological-compatible systems. The vendor base stratifies across integrated petrochemical majors, seed-treatment-focused dispersant suppliers, and regional blending operators. Three archetypes dominate: backward-integrated alkoxylate producers, seed-treatment R&D specialists, and geographic reach-focused multi-basin manufacturers. Competitive moves concentrate on portfolio diversification toward bio-based feedstocks and direct-channel technical service capabilities.
Among integrated chemical majors, BASF SE exemplifies the backward-integrated archetype through captive alkoxylate production. Croda International Plc occupies a position within the seed-treatment specialization tier. Nufarm represents the geographic reach model with multi-basin manufacturing footprints. These three anchors illustrate how competitive positioning fragments across technical capability vectors rather than consolidating around scale alone.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Croda International Plc |
| Nufarm |
| CHS Inc. |
| Stepan Company |
| Clariant |
| Evonik |
| Helena Agri-Enterprises |
| Others |
Pricing and Supply Chain Analysis
Brazilian agricultural cooperatives in Mato Grosso and Goiás concentrate purchasing power through direct manufacturer contracts, anchoring contract-based long-term offtake as the dominant pricing model across herbicide adjuvant grades. This buyer consolidation compresses distributor margins while rewarding suppliers with captive alkoxylation capacity and local blending infrastructure.
Pricing Analysis
Distributor margins face compression as large-scale cooperatives bypass traditional tiers for direct procurement. Three-tier pricing structure across premium, standard, and economy levels differentiates based on drift-reduction certification and volume scale. Cost compression in standard grades intensifies because ethylene oxide and fatty alcohol feedstock volatility constrains producer flexibility. Individual row-crop farmers exhibit highest price sensitivity, while California specialty crop operators prioritize performance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Yangtze River Delta, and Houston chemical corridors anchor hub-and-spoke patterns for surfactant intermediates. Manufacturing draws from ethylene oxide, fatty alcohol, and glucose feedstocks concentrated in Germany, China, and the United States. Single-source vulnerability in organosilicone super-spreader precursors threatens supply continuity for drone-application grades. Distribution runs through agricultural input retailers facing margin pressure from cooperative direct-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural activator adjuvants function as a stable compounder anchored by persistent glyphosate-resistant weed proliferation driving recurring tank-mix demand across Brazil's Cerrado and North American row-crop belts.
For Market Incumbents: Lock in backward integration into alkoxylate production to defend margin position against petrochemical volatility. Secure ANVISA pre-validated low-toxicity portfolios before Mercosur harmonization erodes compliance arbitrage. Prioritize seed-treatment-dedicated R&D facilities to capture biological inoculant adjuvant demand. For New Entrants and Emerging Players: Launch via direct technical service partnerships with Brazilian mega-farm cooperatives to bypass entrenched distribution tiers. Target drone-application spray optimization as the most penetrable white space, where ultra-low-volume droplet engineering remains underdeveloped. Pursue biological-compatible dispersant development for microbial seed treatment convergence. For Investors and Strategic Acquirers: Specialty chemical majors with agricultural divisions represent the most active acquirer in this space, seeking seed-treatment R&D capabilities and geographic footprint expansion. Mid-term viability rests on regulatory compliance infrastructure and bio-based feedstock transition readiness. Monitor ANVISA-EU REACH regulatory convergence as the key inflection signal for portfolio repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxylate Production | Captive ethylene oxide supply insulates margin stability against petrochemical price swings. |
| ANVISA Pre-Validation Investment | Early compliance with Brazil's aquatic toxicity thresholds establishes defensive market access moats. |
| Seed Treatment R&D Facility Buildout | Dedicated biological inoculant compatibility labs capture fastest-growing application vector expansion. |
| Drone Application Formulation Development | Ultra-low-volume droplet engineering unlocks underdeveloped aerial spraying channel penetration. |
| Direct Cooperative Channel Partnerships | Bypassing distribution tiers secures volume offtake with Mato Grosso mega-farm procurement programs. |
Research Methodology
Bottom-up crop protection modeling reconciled against top-down surfactant production tracking forms the analytical core of this study. Primary interviews with formulation chemists, agricultural cooperative procurement managers, seed treatment facility operators, and EPA regulatory affairs specialists combined with secondary validation from customs trade data, EPA registration databases, ANVISA compliance filings, and ACC sector reports. Triangulation between end-use demand signals and supply-side capacity announcements ensures cross-verified output integrity.
Input-output matrices segment volume and value projections across product type, application, form, and end-user dimensions throughout the forecast period. CAGRs derive from regression analysis against planted acreage trends, pesticide mode-of-action rotation patterns, and regulatory compliance cost trajectories. Modeled inputs include glyphosate-resistant weed infestation indices and irrigation restriction policy stringency across California and Florida growing regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH-F-Gas fluorosurfactant phase-out acceleration or ANVISA aquatic toxicity threshold unilateral tightening. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Baobab Market