
 Edible Fungus Market | 2026-2036
Edible Fungus Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Fungus Market Analysis
Controlled-environment agriculture with AI-driven climate optimization is reshaping year-round mushroom cultivation cycles. Monaghan Mushrooms leverages vertical farming infrastructure across Ireland and the United Kingdom. Costa Group anchors Australasian supply through integrated composting and harvesting operations. Monterey Mushrooms competes on scale with coast-to-coast distribution networks across the United States.
Edible fungus comprises macroscopic fruiting bodies of basidiomycete and ascomycete species, cultivated on sterilized substrates of straw, sawdust, or manure at temperatures between 12°C and 24°C with 80-95% relative humidity, serving as protein-rich food ingredients and functional extracts. Fresh mushrooms dominate volume throughput across retail and food service channels, while dried and powdered forms capture concentrated margin pools in supplement and ingredient applications. Food processors and restaurants drive demand for standardized, shelf-stable forms with consistent mycochemical profiles.
EU regulators enforce pesticide maximum residue limits under EFSA guidelines, while FDA oversees HACCP compliance for imported fungal products entering the United States. China's SAMR administers GB food safety standards for domestic cultivation and export certification. Stakeholders must monitor evolving mycotoxin testing protocols and substrate traceability requirements as biosecurity and clean-label priorities tighten across major consuming markets.
Market Dynamics
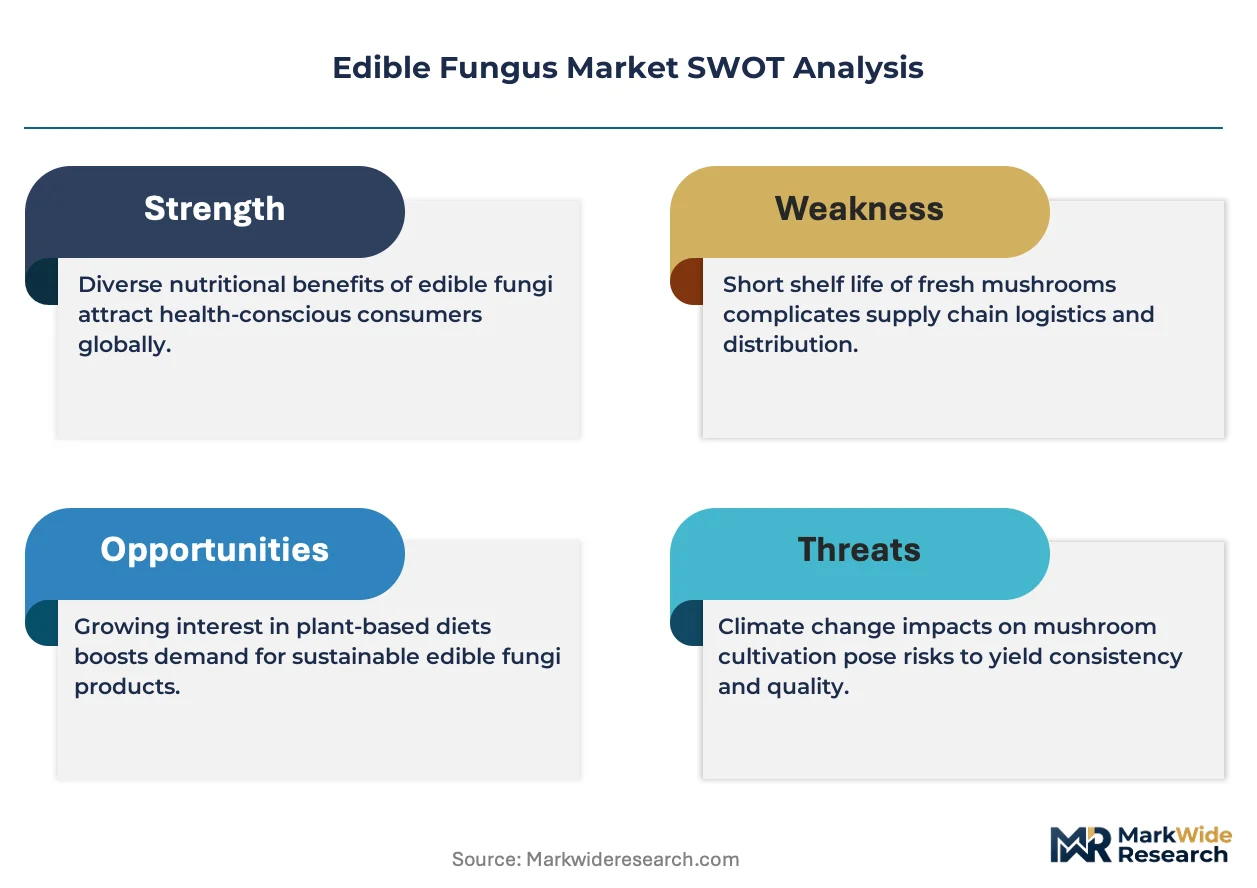
EU Green Deal sustainability mandates are restructuring substrate sourcing and carbon accounting across mushroom supply chains, forcing processors to certify compost origin and energy use in controlled-environment agriculture.
Growth Catalysts
- EU Green Deal procurement mandates:Food processors in Germany and France now require certified-sustainable substrate documentation, accelerating farm-level investment in circular composting systems.
- AI-driven climate optimization:Controlled-environment agriculture operators deploy machine learning to stabilize year-round yield curves, compressing harvest cycle variance from seasonal to weekly granularity.
- East Asia fresh demand concentration:China and Japan sustain premium pricing for shiitake and enoki through culinary tradition and functional-food positioning in retail channels.
Market Restraints
- Input cost volatility in sterilized substrates:Sawdust and straw prices fluctuate with timber harvest cycles and grain commodity markets, squeezing margin predictability for substrate producers.
- Supply concentration in East Asian spawn banks:Genetic material for commercial strains remains concentrated among Japanese and Chinese repository facilities, creating biosecurity and IP dependency risks.
- EFSA pesticide residue enforcement:Maximum residue limit testing protocols for imported dried mushrooms create border detention risk and working-capital compression for non-EU exporters.
Strategic Opportunities
- Underpenetrated functional extract applications:Beta-glucan and eritadenine isolates for pharmaceutical and nutraceutical formulators remain undersupplied relative to validated clinical demand.
- EU CSRD sustainability disclosure requirements:Mandatory scope-three emissions reporting creates first-mover advantage for vertically integrated operators with substrate-to-retail traceability systems.
- Convergence of solid-state fermentation and precision fermentation:Hybrid bioprocessing platforms enable mycelium-based meat analog production at scale, opening alternative protein channels beyond whole-mushroom formats.
Industry Challenges
- Mycologist and fermentation technologist scarcity:Specialized talent for strain development and bioreactor operation commands premium compensation, constraining expansion timelines for mid-scale facilities.
- HACCP compliance timeline for US market entry:FDA import alert protocols require validated hazard analysis documentation that delays first shipments by 6-18 months for new exporters.
- Substrate standardization delays:Absence of unified international standards for compost maturity and contaminant thresholds forces redundant testing across destination markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Fungus Market |
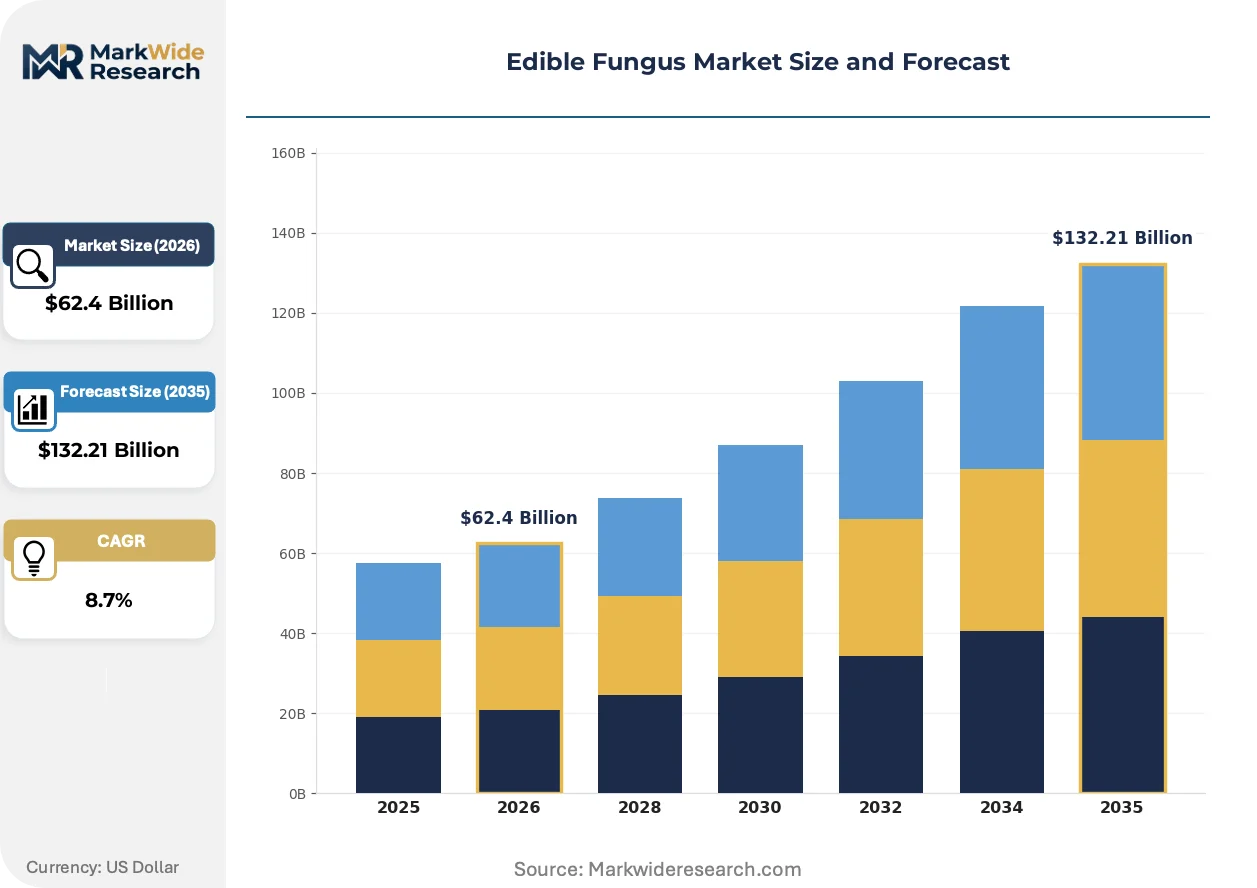
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mushrooms, Truffles, Morels, Chanterelles Form: Fresh, Dried, Powdered, Canned Distribution Channel: Retail, Wholesale, Online, Food Service End User: Households, Restaurants, Food Processors, Hotels |
| Companies Covered | Monaghan Mushrooms, Costa Group, Monterey Mushrooms, Okechamp, Shanghai Finc Bio-Tech, Bonduelle Group, Greenyard NV, Scelta Mushrooms BV, Drinkwater’s Mushroom Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Fungus Market Emerging Trajectories
Bioprocessing infrastructure is migrating from open-field composting to closed-loop bioreactor systems, compressing production cycles and enabling geographic decoupling from agricultural zones.
Automated harvesting robotics is migrating from experimental pilot installations to commercial deployment across vertical farming operations, with Irish and UK facilities leading integration of computer-vision sorting for bruise-free handling. Specialty mushroom producers adopt these systems to offset labor cost inflation and secure consistent pack-out grades for retail contracts. The technology is migrating from premium varietals toward commodity white button operations, compressing the cost gap between automated and manual harvesting.
China's SAMR has tightened GB food safety standards for mycotoxin testing in exported dried fungi, mandating expanded aflatoxin and ochratoxin screening protocols for all shipments entering domestic distribution. This regulatory compression forces export-oriented cultivators to upgrade in-house laboratory capacity or contract third-party certified testing, raising fixed-cost thresholds. Dried and powdered product categories face the steepest compliance burden, with many operators pivoting toward fresh-format exports to bypass extended certification timelines.
Food service distributors now specify lot-level mycochemical certificates as a condition of contract renewal, displacing commodity purchasing based on visual grade alone. This specification creep concentrates procurement authority among large-scale food service operators with technical sourcing teams, fragmenting volume among smaller restaurants unable to validate supplier claims. The pattern is most visible in German and French institutional catering channels, where EU public procurement directives amplify clean-label requirements.
Edible Fungus Market Segmentation
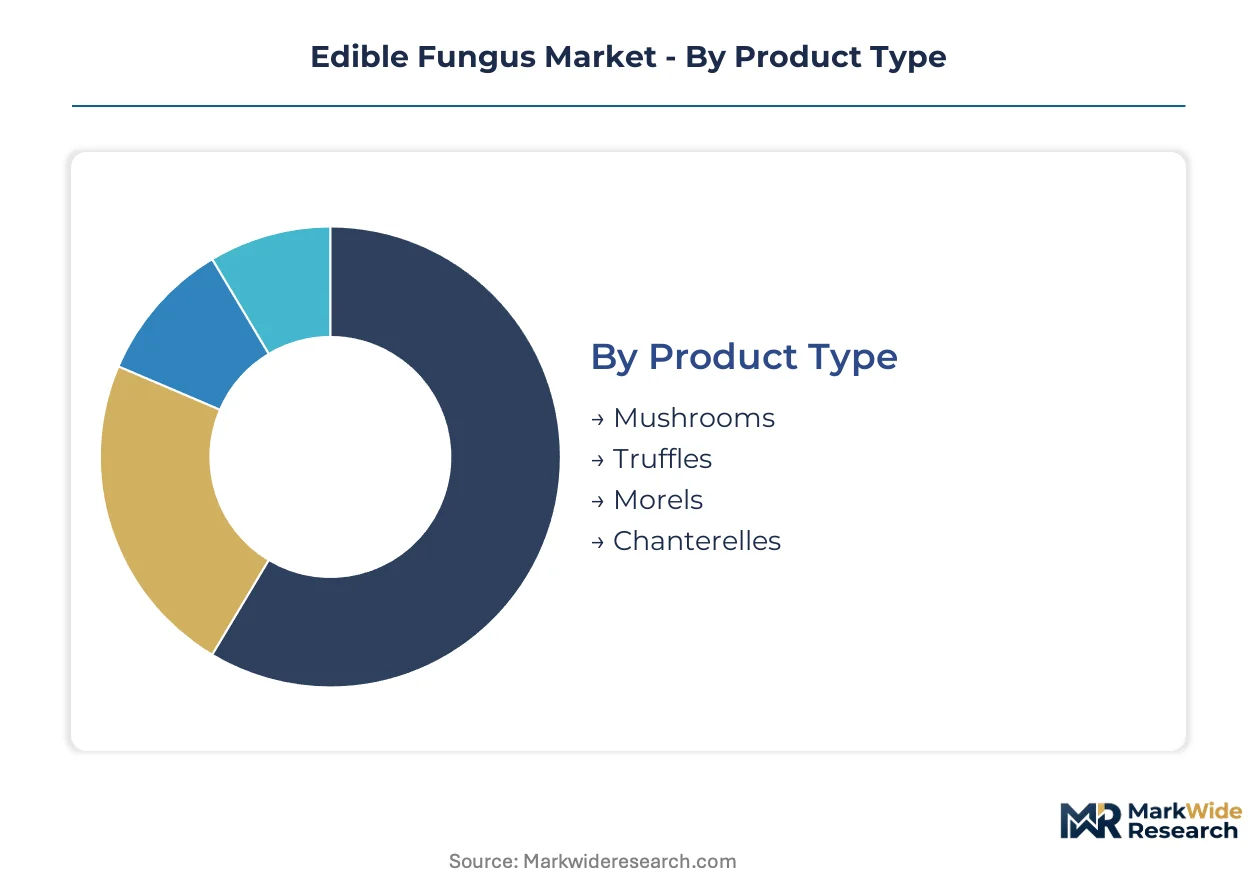
Segmentation in edible fungus markets exposes divergent margin structures across preservation states and channel economics. Cycle time, spoilage risk, and certification burden vary dramatically between fresh and processed formats, reshaping capital allocation and geographic sourcing strategies.
Product Type:
Harvest-to-sale velocity separates commodity mushrooms from foraged specialty varieties, with cultivation cycles ranging from six weeks for indoor-grown species to seasonal wild harvest windows for mycorrhizal fungi.
- Mushrooms:Cultivated basidiomycete species grown on sterilized substrates of straw, sawdust, or manure under controlled humidity and temperature regimes. Shiitake and oyster varieties concentrate demand in Japan and China through culinary tradition and functional-food retail positioning, with German institutional catering channels now mandating certified-organic documentation for contract renewal.
- Truffles:Hypogeous ascomycete fungi forming symbiotic relationships with oak and hazelnut root systems, requiring trained canines or pigs for harvest location. French and Italian procurement networks dominate premium pricing for Tuber melanosporum and Tuber magnatum, though Australian cultivation in Tasmania and Western Australia is compressing seasonal supply gaps.
- Morels:Conical-capped wild mushrooms harvested during brief spring fruiting periods across temperate forest zones. Himalayan supply from Kashmir and Himachal Pradesh feeds Indian domestic markets and dried export channels to Europe.
- Chanterelles:Funnel-shaped mycorrhizal species with apricot aroma and firm texture, foraged across Scandinavian and Baltic pine forests. Swedish and Finnish export cooperatives supply German and French wholesale markets during autumn harvest windows.
Mushrooms dominate installed base. Truffles are where expansion concentrates.
Form:
Preservation state determines working capital intensity and regulatory exposure, with fresh formats commanding premium pricing but compressed shelf life, while dried and powdered categories absorb higher compliance costs for mycotoxin certification.
- Fresh:Whole or sliced fruiting bodies maintained at 0-4°C with modified atmosphere packaging to retard enzymatic browning. Japanese and Chinese retail channels sustain volume concentration for shiitake and enoki, while Irish and UK vertical farming operations are displacing seasonal import dependency with year-round domestic supply.
- Dried:Dehydrated whole caps or slices rehydrated for culinary use, with moisture content standardized below 12% to prevent mold contamination. China's SAMR-mandated aflatoxin and ochratoxin screening protocols have raised fixed-cost thresholds for export-oriented cultivators, pushing many operators toward fresh-format pivots.
- Powdered:Fine-milled material for supplement, ingredient, and functional extract applications. Beta-glucan and eritadenine isolates for pharmaceutical formulators remain undersupplied relative to validated clinical demand.
- Canned:Brine-preserved whole or sliced mushrooms for food service and retail shelf-stable applications. German and French processors expanding procurement under EU Green Deal sustainability mandates favor canned formats for standardized inventory planning.
Fresh captures volume throughput. Powdered is climbing the fastest on margin expansion.
Distribution Channel:
Channel selection dictates traceability requirements and specification granularity, with food service and retail diverging on lot-level mycochemical documentation and sustainability certification.
- Retail:Supermarket chains and specialty grocers selling packaged fresh, dried, or processed formats to household consumers. German and French clean-label requirements are displacing commodity purchasing based on visual grade alone.
- Wholesale:Volume aggregation for redistribution to smaller retailers, restaurants, and institutional buyers. Irish and UK facilities leverage automated harvesting robotics with computer-vision sorting to secure consistent pack-out grades for wholesale contracts.
- Online:Direct-to-consumer and B2B platforms enabling specialty variety access outside traditional geographic supply zones. Dried and powdered categories migrate most naturally to e-commerce given extended shelf stability and lower cold-chain dependency.
- Food Service:Distributors supplying restaurants, hotels, and institutional catering with standardized specifications. Lot-level mycochemical certificates now condition contract renewal in German and French institutional channels.
Retail anchors volume. Food service is gaining share fastest on specification creep.
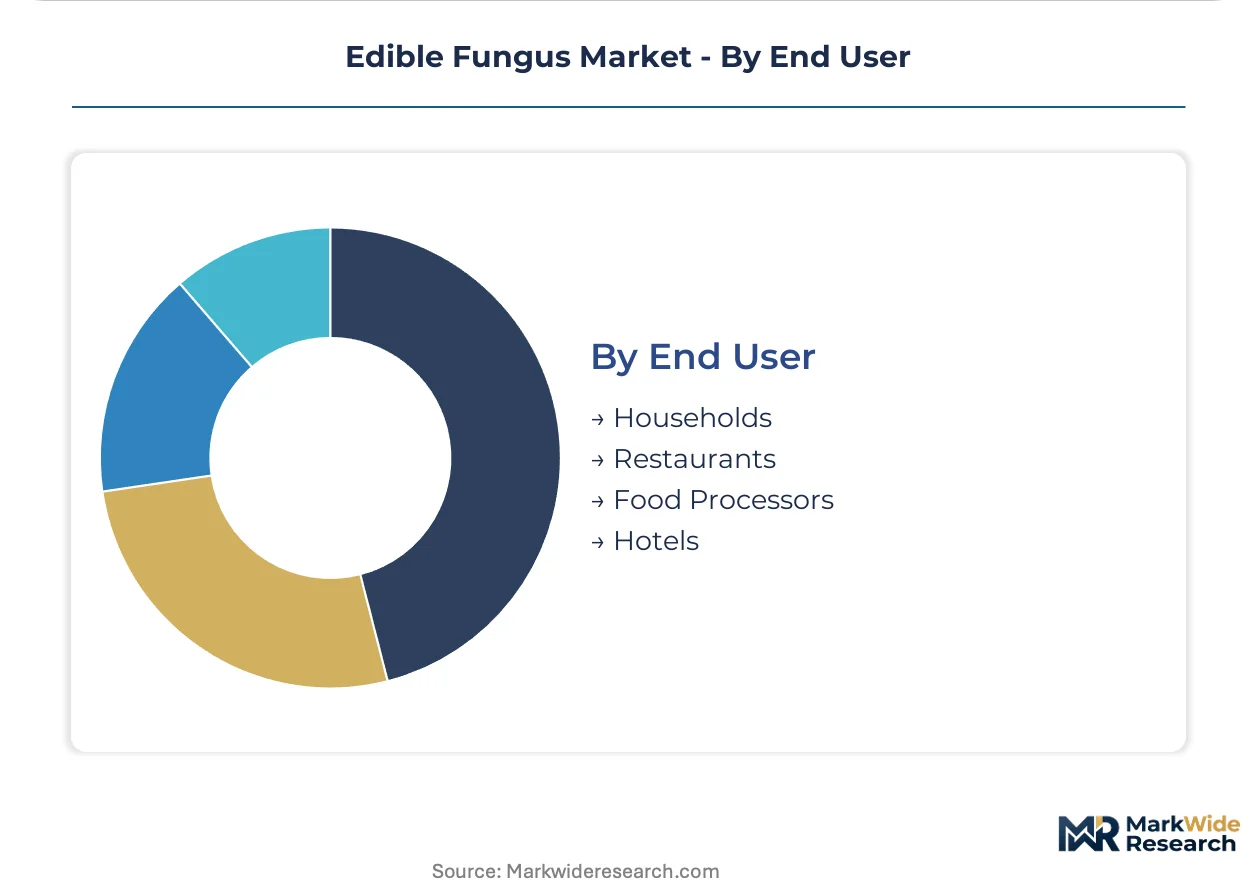
End User:
End-use concentration shapes product format preferences and price elasticity, with food processors and restaurants driving standardization while households absorb greater variety complexity.
- Households:Individual consumers purchasing through retail or online channels for home preparation. Japanese and Chinese culinary tradition sustains premium pricing for fresh shiitake and enoki in East Asian household demand.
- Restaurants:Independent and chain dining establishments sourcing through wholesale and food service distributors. Smaller restaurants face procurement authority fragmentation as technical sourcing teams concentrate among large-scale operators.
- Food Processors:Manufacturers incorporating fungal ingredients into prepared foods, sauces, and functional formulations. EU CSRD scope-three emissions reporting creates first-mover advantage for vertically integrated operators with substrate-to-retail traceability systems.
- Hotels:Hospitality operations with institutional catering requirements and banquet service volumes. EU public procurement directives amplify clean-label requirements in German and French hotel channels.
Households dominate consumption volume. Food processors are where specification investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major producing zones, with East Asian supply networks feeding premium fresh demand while European processors restructure procurement under sustainability mandates. The analysis maps five national markets where substrate sourcing, regulatory enforcement, and cultivation technology define competitive positioning.
China
Fresh shiitake and enoki consumption concentrates in domestic retail channels, with SAMR-administered GB standards tightening mycotoxin screening for dried export categories. Yangtze River Delta cultivation clusters pivot toward fresh-format shipments to bypass extended certification timelines, while spawn banks in Zhejiang and Fujian maintain genetic material concentration.
Japan
Meti-guided food safety protocols enforce residue testing for imported dried fungi, compressing working capital for non-domestic suppliers. Kanto region retail chains sustain premium pricing for domestically cultivated specialty varieties, with Nagano Prefecture vertical farms deploying AI climate optimization to stabilize year-round yield curves.
Germany
EU Green Deal procurement mandates now require certified-sustainable substrate documentation for institutional catering contracts, accelerating farm-level investment in circular composting systems. Bavarian food processors expand mushroom procurement under EFSA-guided pesticide residue limits, with Munich-based distributors specifying lot-level mycochemical certificates.
United States
FDA HACCP compliance timelines delay first shipments by 6-18 months for new exporters, creating defensive moats for established suppliers. Pennsylvania and California cultivation clusters anchor coast-to-coast distribution networks, with automated harvesting robotics migrating from experimental pilots toward commercial deployment.
France
ANSM-aligned biosecurity protocols intersect with EU CSRD scope-three emissions reporting, favoring vertically integrated operators with substrate-to-retail traceability. Périgord truffle procurement networks defend premium pricing for Tuber melanosporum, while Loire Valley mushroom farms adopt closed-loop bioreactor systems to compress production cycles.
Edible Fungus Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct tiers: multinational scale operators with integrated composting networks, regional specialists leveraging vertical farming infrastructure, and commodity traders arbitraging seasonal supply gaps. Strategic archetypes include sustainability-certified substrate controllers, AI-enabled climate optimization platforms, and functional extract formulators. Dominant competitive moves encompass backward integration into spawn genetics and strategic partnerships with food service distributors seeking traceability documentation.
Among Irish and UK-based cultivators, Monaghan Mushrooms occupies a position exemplifying vertical farming infrastructure deployment, while Costa Group anchors Australasian supply through integrated operations. Monterey Mushrooms represents the scale-driven archetype with extensive North American distribution reach. These three entities collectively illustrate the geographic and technological diversification strategies reshaping procurement authority concentration.
| Leading Market Players |
|---|
| Monaghan Mushrooms |
| Costa Group |
| Monterey Mushrooms |
| Okechamp |
| Shanghai Finc Bio-Tech |
| Bonduelle Group |
| Greenyard NV |
| Scelta Mushrooms BV |
| Drinkwater's Mushroom Ltd. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta cultivation clusters anchor fresh shiitake supply capacity, with their harvest velocity and cold-chain proximity to Shanghai export terminals translating directly into premium pricing power for domestic distributors over European importers facing extended certification timelines.
Pricing Analysis
Food processors and institutional catering buyers anchor contract-based pricing structures across German and French procurement channels, with three-tier pricing stratification across certified-organic, conventional fresh, and commodity canned formats. Price differentiation centers on EU Green Deal substrate documentation and lot-level mycochemical certification, both now mandatory for contract renewal. Cost compression in dried export tiers is intensifying because China's SAMR-mandated aflatoxin screening has raised fixed-cost thresholds, pushing many operators toward fresh-format pivots. Small independent restaurants exhibit highest price sensitivity as procurement authority fragments toward large-scale operators with technical sourcing teams.
Supply Chain Analysis
Sawdust and straw feedstock markets draw from timber harvest cycles across Scandinavia and grain commodity zones in Eastern Europe, with substrate producers facing margin unpredictability from input cost volatility. Spawn genetics concentrate in Zhejiang and Fujian repository facilities, creating single-source vulnerability for commercial strain access outside East Asia. Distribution runs through vertically integrated operators with substrate-to-retail traceability systems that satisfy EU CSRD scope-three emissions disclosure requirements, while fragmented wholesale channels serve smaller buyers without certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible fungus market functions as a defensive-moat story because regulatory entrenchment through EFSA pesticide residue limits and FDA HACCP compliance timelines creates 6-18 month barriers to entry that protect established suppliers from rapid competitive displacement.
For Market Incumbents: Harden biosecurity protocols and spawn bank control against Japanese and Chinese genetic material concentration risks by securing exclusive licensing agreements with Nagano Prefecture AI-optimized vertical farms or investing in captive strain development capabilities. Deepen backward integration into circular composting systems to satisfy EU Green Deal procurement mandates and defend margin position against substrate cost volatility. For New Entrants and Emerging Players: Establish a beachhead in functional extract applications where beta-glucan and eritadenine isolates remain undersupplied relative to pharmaceutical and nutraceutical formulator demand. Target Australian truffle cultivation in Tasmania and Western Australia, where seasonal supply gaps for Tuber melanosporum create penetrable white space outside French and Italian procurement network dominance. Pursue direct-to-specialty-distributor relationships that bypass fragmented wholesale channels. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-infrastructure play because mandatory scope-three emissions reporting under EU CSRD creates durable competitive advantage for operators with integrated substrate-to-retail traceability systems that smaller competitors cannot replicate. Target acquisition profiles should emphasize vertical farming facilities with automated harvesting robotics and computer-vision sorting capabilities. The signal to watch is consolidation among Irish and UK-based cultivators deploying AI-driven climate optimization, as this technology compression indicates margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Genetics | Reduces biosecurity dependency on Zhejiang and Fujian repository concentration. |
| AI-Driven Climate Optimization Deployment | Enables Nagano Prefecture-style year-round yield stabilization for premium varietals. |
| Circular Composting System Investment | Satisfies EU Green Deal substrate documentation requirements for German institutional contracts. |
| Automated Harvesting Robotics Integration | Compresses labor cost inflation and secures consistent pack-out grades for wholesale contracts. |
| Functional Extract Capacity Expansion | Addresses undersupply of beta-glucan isolates for pharmaceutical formulator demand. |
Methodological Framework
Cross-validation between executive interviews at substrate producers and secondary trade data anchors the qualitative findings in this study. Primary fieldwork engaged cultivation facility operators, food processor procurement leads, food service distributor category managers, and regulatory affairs specialists at export-oriented cultivators. Secondary sources included EFSA pesticide residue guidelines, FDA HACCP import alert protocols, SAMR GB food safety standards, customs records for dried fungi trade flows, and EU CSRD disclosure requirement documents. Bottom-up facility capacity assessments and top-down consumption estimates were reconciled through iterative triangulation.
Calibration against historical yield volatility and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation state, distribution channel, and end-user concentration, with additional granularity on certification tier and geographic supply cluster. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and policy mandate enforcement schedules. Key inputs encompassed compost maturity standard evolution and mycotoxin testing protocol expansion timelines.
Stress conditions across substrate input cost volatility, spawn supply disruption scenarios, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal procurement mandate adherence rates and AI climate optimization adoption curves. Cross-checking against customs trade volume data and food service distributor contract renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Soil Inoculants Market