
 North America Amino Acids Market | 2026-2036
North America Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Amino Acids Market Analytics
The capital-intensity divergence between microbial fermentation specialists and chemical synthesis operators is collapsing as fermentation technology scales beyond commodity grades. Ajinomoto Co., Inc. leverages its decades-long expertise in fermentation-based L-glutamate production to dominate food-grade supply chains across the United States. Evonik Industries AG sustains a differentiated position in pharmaceutical-grade amino acids through stringent European pharmacopeia compliance extended to its North American facilities.
North America amino acids comprise organic compounds containing amine and carboxyl functional groups, typically produced via Corynebacterium glutamicum fermentation or enzymatic hydrolysis of proteinaceous feedstocks, with purity specifications ranging from feed-grade to United States Pharmacopeia and Food Chemicals Codex standards for human and animal nutrition applications. L-glutamic acid and L-lysine command the largest volume positions in animal feed applications, where margin pools concentrate with integrated corn processors. Pharmaceutical-grade L-arginine and L-leucine represent the fastest-expanding value tier, driven by parenteral nutrition formulations and sports nutrition clinical validation.
The US FDA enforces Current Good Manufacturing Practice regulations for dietary supplement amino acids, while Health Canada's Natural and Non-prescription Health Products Directorate imposes distinct site licensing requirements that shape cross-border product registration strategies. The US EPA oversees fermentation facility effluent discharge permits, constraining capacity expansion timelines in water-stressed manufacturing zones. Stakeholders must monitor evolving monograph standards from the United States Pharmacopeia and potential alignment pressures between FDA and Health Canada purity testing protocols.
Market Dynamics
Fermentation technology scaling is collapsing the historical cost gap between microbial production and chemical synthesis, forcing incumbent producers to defend margin positions through pharmaceutical-grade certification ladders while corn belt processors consolidate feed-grade supply.
Growth Catalysts
- Peptide Drug Pipelines:Pharmaceutical manufacturers are expanding therapeutic peptide portfolios that require certified amino acid precursors, pulling demand toward USP-grade supply chains.
- US FDA Labeling Rules:Updated dietary supplement documentation requirements are tightening purity verification for imported raw materials, advantaging domestic fermentation facilities.
- Corn Belt Feedstock Concentration:Midwest corn processors leverage integrated starch-to-lysine pathways that slash logistics costs versus coastal importers.
Market Restraints
- Natural Gas Price Volatility:Ammonia synthesis for chemical amino acid routes faces input cost swings that compress operator margins during feedstock spikes.
- Chinese Fermentation Overcapacity:State-subsidized bulk lysine and glutamate exports flood spot markets, pressuring North American commodity-grade pricing.
- EPA Effluent Permits:Water-stressed manufacturing zones face extended approval timelines for fermentation capacity expansions.
Strategic Opportunities
- Canadian Site Licensing Arbitrage:Health Canada's Natural and Non-prescription Health Products Directorate offers faster registration pathways for cross-border supplement brands.
- Parenteral Nutrition Formulations:Hospital compounding pharmacies are expanding L-arginine and L-leucine sourcing for critical care applications.
- Enzymatic Hydrolysis Convergence:Protein upcycling technologies are unlocking non-GMO amino acid streams from dairy and meat processing waste.
Industry Challenges
- Fermentation Scale-Up Talent Gap:Corynebacterium glutamicum strain optimization and bioreactor engineering expertise concentrates at a handful of academic programs.
- Pharmacopeia Compliance Timelines:USP monograph alignment between FDA and Health Canada testing protocols remains unresolved, duplicating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Amino Acids Market |
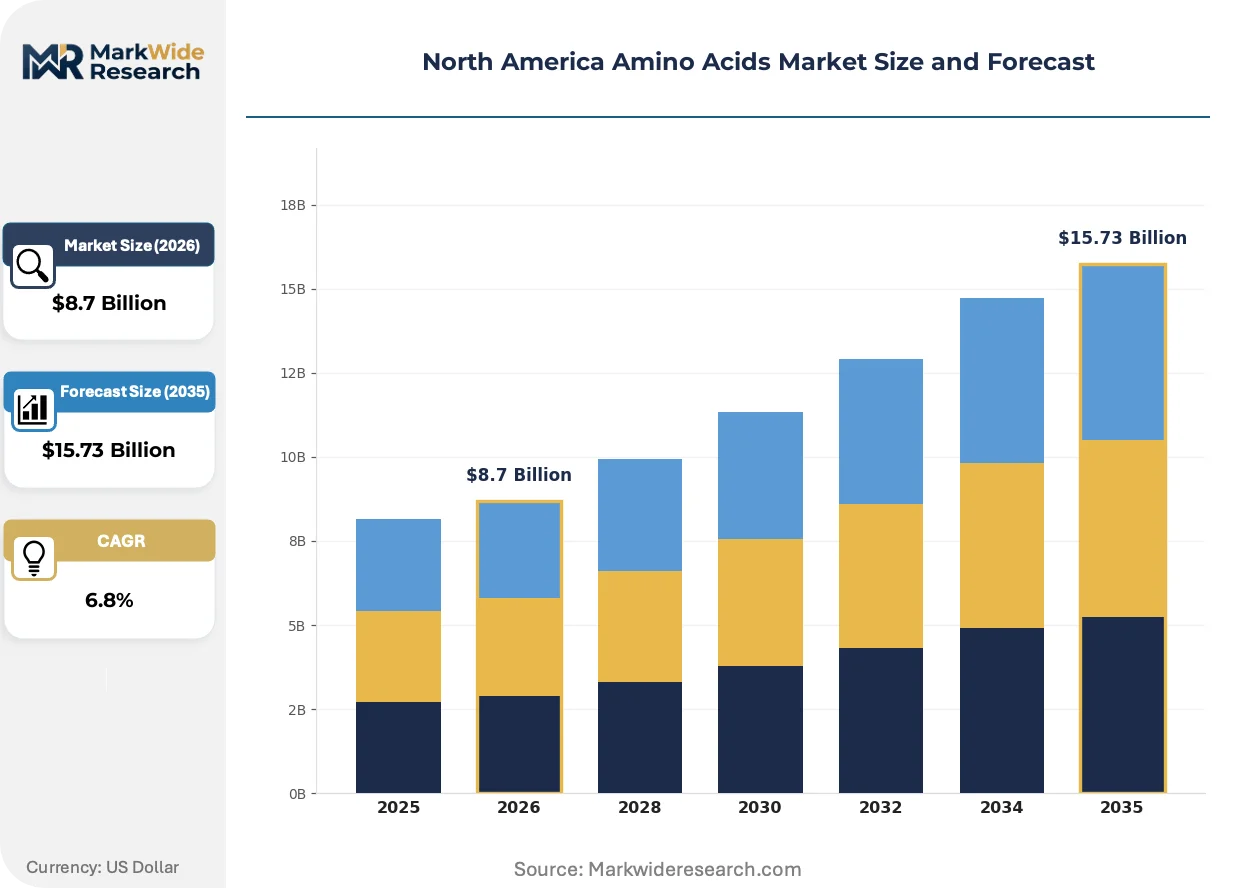
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamic Acid, L-Leucine, L-Lysine, L-Arginine End User: Food & Beverage, Pharmaceuticals, Animal Feed, Cosmetics Application: Nutritional Supplements, Animal Nutrition, Functional Foods, Feed Additives Form: Liquid, Powder, Granule, Crystal |
| Companies Covered | Archer Daniels Midland Co., Evonik Industries AG, Ajinomoto Co., Inc., Adisseo, Merck KGaA, IFF (Danisco Animal Nutrition), KYOWA HAKKO BIO CO., LTD., Prinova Group LLC., NOVUS INTERNATIONAL, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Amino Acids Market Evolving Landscape
Continuous fermentation systems and cell-free enzymatic synthesis are compressing batch cycle times while regulatory data harmonization pressures force certification investments upstream.
Single-use bioreactor systems are displacing stainless-steel infrastructure in pharmaceutical-grade amino acid production. Contract manufacturers serving parenteral nutrition formulators are adopting disposable contact surfaces to slash cross-contamination validation burdens. This modular approach is miniaturizing minimum efficient scale thresholds, enabling regional production nodes near compounding pharmacy clusters.
Health Canada's Natural and Non-prescription Health Products Directorate is tightening site licensing requirements for imported amino acid raw materials. Cross-border supplement brands now face dual-track registration strategies that extend time-to-market for new formulations. The US-Canada corridor bears the highest compliance friction, with brands accelerating domestic fermentation partnerships to bypass documentation gaps.
Hospital procurement groups are consolidating amino acid sourcing through group purchasing organizations that unbundle traditional distributor markups. Parenteral nutrition compounders in the US Midwest negotiate direct contracts with fermentation specialists, bypassing regional chemical distributors. This channel compression is most visible in tertiary care systems managing ICU formulary costs.
North America Amino Acids Market Segmentation
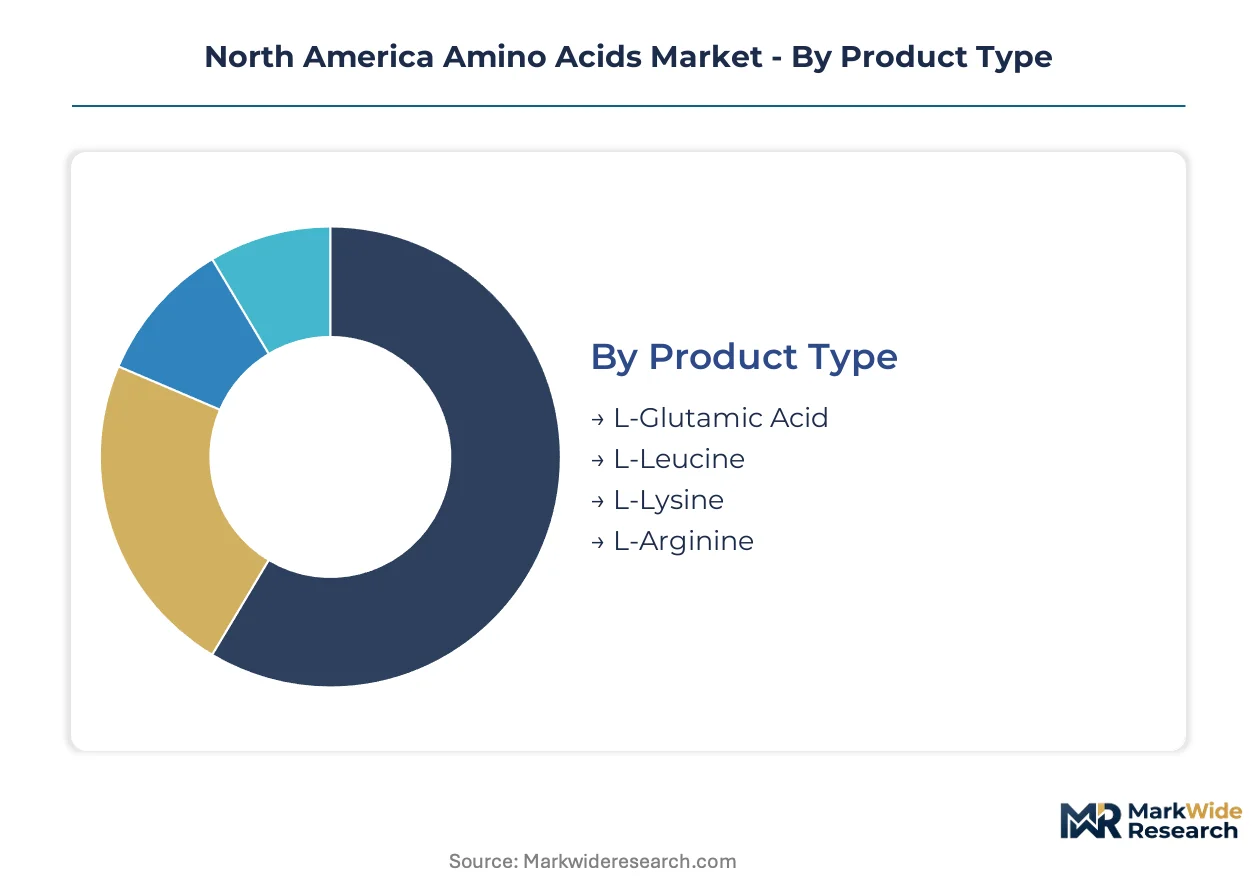
Segmentation in the North America amino acids market tracks how purity specifications, regulatory pathways, and feedstock integration create divergent margin pools across product grades and end-use channels.
Product Type:
FDA and Health Canada pharmacopeia standards split amino acid streams into commodity fermentation outputs versus certified pharmaceutical precursors with divergent documentation burdens.
- L-Glutamic Acid:Corynebacterium glutamicum fermentation yields this bulk amino acid for savory flavor enhancement and feed formulations. US Midwest corn processors dominate volume output through integrated starch-to-glutamate pathways that eliminate coastal logistics premiums.
- L-Lysine:Essential amino acid for swine and poultry nutrition specifications, produced via fermentation of dextrose from corn wet milling. Chinese state-subsidized exports pressure North American spot pricing, forcing domestic producers toward pharmaceutical-grade certification ladders.
- L-Leucine:Branched-chain amino acid for sports nutrition and parenteral nutrition compounding with stringent USP monograph compliance requirements.
- L-Arginine:Semi-essential amino acid for critical care formulations and cardiovascular therapeutic applications under FDA Current Good Manufacturing Practice oversight.
L-Glutamic acid handles the majority of throughput; L-arginine is expanding most quickly on share as peptide drug pipelines pull demand toward certified precursors.
End User:
Customer concentration patterns trace corn belt geography for feed applications versus coastal pharmaceutical clusters for certified grades.
- Food & Beverage:Flavor enhancement and umami delivery applications dominate L-glutamate offtake from fermentation specialists serving processed food manufacturers.
- Pharmaceuticals:Parenteral nutrition formulators and peptide drug manufacturers require USP-grade amino acids with full chain-of-custody documentation. Hospital compounding pharmacies in tertiary care systems negotiate direct contracts with fermentation specialists to bypass distributor markups.
- Animal Feed:Swine and poultry integrators in Iowa, Illinois, and Nebraska source lysine through corn processors with captive fermentation capacity, capturing logistics arbitrage versus coastal importers.
- Cosmetics:Skin conditioning and hair care formulations utilize amino acid derivatives with lower purity thresholds than pharmaceutical applications.
Animal feed commands volume concentration in the US Midwest; pharmaceuticals is climbing the fastest as peptide therapeutic pipelines expand.
Application:
Application tiering reflects how dosage form requirements cascade backward into raw material specification ladders.
- Nutritional Supplements:Dietary supplement manufacturers face tightened FDA labeling rules requiring purity verification for imported raw materials, advantaging domestic fermentation facilities with compliant documentation systems.
- Animal Nutrition:Feed formulation specifications for lysine and methionine equivalents concentrate procurement with integrated corn processors who control dextrose feedstock costs.
- Functional Foods:Protein fortification applications in beverages and bars require amino acid premixes with solubility profiles suited to liquid processing lines.
- Feed Additives:Antibiotic replacement strategies in poultry and swine production pull amino acid demand toward gut health optimization formulations.
Animal nutrition anchors bulk volume; nutritional supplements is gaining share fastest as clinical validation expands sports nutrition demand.
Form:
Physical form selection tracks downstream processing compatibility and stability requirements across dosage form manufacturing.
- Liquid:Aqueous solutions for parenteral nutrition compounding and beverage fortification with sterilization validation requirements.
- Powder:Spray-dried amino acids for tablet compression and capsule filling operations in dietary supplement manufacturing.
- Granule:Agglomerated particles for improved flow properties in high-speed feed milling and direct compression tableting.
- Crystal:High-purity crystalline grades for pharmaceutical synthesis and peptide coupling reactions requiring defined particle morphology.
Powder handles the majority of throughput; crystal is the fastest mover on share as pharmaceutical-grade demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American amino acid trade flows reflect a structural deficit in pharmaceutical-grade supply against surplus corn-belt fermentation capacity for feed-grade outputs. Import dependence concentrates in high-purity L-arginine and L-leucine streams from European and Asian pharmacopeia-certified facilities. Export competitiveness rests on integrated starch processors in the US Midwest leveraging captive dextrose feedstock.
United States
Peptide drug pipelines at Boston and San Francisco biotech clusters pull demand toward USP-grade L-arginine with full chain-of-custody documentation. FDA Current Good Manufacturing Practice enforcement for dietary supplements tightens purity verification requirements on imported raw materials. Iowa and Illinois corn processors dominate L-lysine output through integrated wet milling-to-fermentation pathways that eliminate coastal logistics premiums.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate imposes site licensing requirements that extend cross-border supplement registration timelines. Toronto-area compounding pharmacies negotiate direct contracts with fermentation specialists to bypass distributor markups on parenteral nutrition formulations. Vancouver and Montreal logistics hubs handle transshipment of European pharmaceutical-grade amino acids into US tertiary care systems.
Mexico
Poultry integrators in Jalisco and Guanajuato source feed-grade lysine through distributors serving the Bajío agricultural belt. COFEPRIS pharmaceutical regulations create documentation gaps for USP-grade imports that limit hospital formulary access to parenteral nutrition products. Northern border states concentrate maize-derived fermentation capacity serving both domestic animal nutrition and re-export to US feed compounders.
North America Amino Acids Market Competitive Landscape
Concentration sits with fermentation specialists integrated into corn wet milling operations and European pharmacopeia-certified manufacturers operating North American facilities. The vendor base splits between Midwest-based feed-grade producers capturing logistics arbitrage and coastal pharmaceutical-grade suppliers defending certification premiums. Two archetypes dominate: integrated agribusiness processors with captive starch feedstock, and specialty chemical houses with pharmacopeia compliance infrastructure. Competitive moves center on pharmaceutical-grade certification ladder climbs and direct contracting with hospital procurement groups.
Among Japanese fermentation specialists, Ajinomoto Co., Inc. occupies a position exemplifying decades-long Corynebacterium glutamicum strain optimization expertise applied to North American food-grade supply chains. German chemical conglomerate Evonik Industries AG represents the European pharmacopeia compliance archetype, with North American facilities extending stringent quality systems to pharmaceutical-grade amino acid production. Illinois-based agribusiness Archer Daniels Midland Co. anchors the integrated processor tier, leveraging captive corn starch supply for bulk lysine and glutamate output.
| Leading Market Players |
|---|
| Archer Daniels Midland Co. |
| Evonik Industries AG |
| Ajinomoto Co., Inc. |
| Adisseo |
| Merck KGaA |
| IFF (Danisco Animal Nutrition) |
| KYOWA HAKKO BIO CO., LTD. |
| Prinova Group LLC. |
| NOVUS INTERNATIONAL |
| Others |
Value Network & Pricing Analysis
Midwest corn wet milling capacity utilization above 85% creates feed-grade lysine price floors that coastal importers cannot match without absorbing dextrose logistics premiums. This scale concentration forces pharmaceutical-grade producers to defend margins through USP certification ladders rather than volume competition.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that separate USP-certified pharmaceutical grades from feed-grade commodity streams. Price differentiation hinges on FDA Current Good Manufacturing Practice compliance tier and volume scale commitments, with Chinese state-subsidized exports compressing spot market margins for bulk glutamate. Cost compression in feed-grade tiers is intensifying because of transshipped Asian fermentation capacity. Animal feed compounders in Iowa and Illinois exhibit highest price sensitivity; parenteral nutrition formulators demonstrate lowest sensitivity due to chain-of-custody documentation requirements.
Supply Chain Analysis
The United States and Canada anchor pharmaceutical-grade amino acid production through FDA and Health Canada pharmacopeia-certified facilities, while Mexico concentrates maize-derived feed-grade fermentation for domestic poultry integrators and US re-export. Raw material flows draw from Midwest corn starch, natural gas for ammonia synthesis, and imported L-arginine precursors from European pharmacopeia-certified sites. Single-source vulnerability concentrates in Chinese bulk lysine exports that flood spot markets during subsidy expansion cycles. Distribution runs through integrated corn processors for feed applications and direct hospital procurement contracts for parenteral nutrition grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification documentation services and strain optimization consulting are expanding faster than fermentation hardware sales as buyers prioritize compliance velocity over capacity expansion.
For Market Incumbents: Consolidate Corynebacterium glutamicum strain optimization expertise through targeted hiring from the handful of academic programs producing qualified bioprocess engineers. Capture backward integration into corn wet milling assets in Illinois and Nebraska to lock in dextrose feedstock costs against Chinese import volatility. FDA labeling rule tightening represents the primary regulatory threat requiring documentation system upgrades. For New Entrants and Emerging Players: Lead with enzymatic hydrolysis of dairy and meat processing waste to unlock non-GMO amino acid streams for premium supplement brands. Canadian site licensing arbitrage offers the most penetrable regulatory pathway for cross-border supplement formulations targeting US buyers. Direct contracting with Toronto-area compounding pharmacies provides the clearest go-to-market angle for parenteral nutrition grade entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with captive starch feedstock and established pharmacopeia compliance infrastructure over pure-play chemical synthesis operators. Long-term viability across the projection horizon rests on pharmaceutical-grade certification ladders that sustain margin premiums against commodity price erosion. Watch for EPA effluent permit approval velocity in water-stressed manufacturing zones as the inflection indicator for domestic capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captive dextrose supply eliminates coastal logistics premiums for Iowa and Illinois producers. |
| USP Monograph Compliance Investment | FDA Current Good Manufacturing Practice certification opens parenteral nutrition formulation contracts. |
| Direct Hospital Procurement Contracts | Group purchasing organization bypass slashes distributor markups for tertiary care systems. |
| Enzymatic Hydrolysis Scale-Up | Protein upcycling technology unlocks non-GMO amino acid streams from meat processing waste. |
| Canadian Site Licensing Partnership | Health Canada's Natural and Non-prescription Health Products Directorate offers faster cross-border registration pathways. |
Research Methodology
Cross-validation between fermentation plant managers and hospital pharmacy procurement leads anchors the qualitative findings on capacity utilization and parenteral nutrition sourcing patterns. Primary interviews with regulatory affairs specialists at FDA and Health Canada, technical R&D directors at corn processing facilities, and distribution channel partners handling cross-border supplement flows combined with secondary validation from SEC 10-K filings, customs and trade data, and USP monograph update records. Bottom-up strain optimization cost curves and top-down regional demand aggregation complete the triangulation.
Sensitivity analysis on natural gas price volatility and Chinese export subsidy levels shapes the forecast framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry, regulatory compliance pathway, and regional production hub clustering. CAGRs derive from fitted growth curves calibrated to peptide drug pipeline expansion rates and corn belt capacity utilization trajectories. Key inputs include hospital formulary adoption timelines for branched-chain amino acids and EPA effluent permit approval velocity.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of dietary supplement labeling rules or prolonged Chinese state subsidy expansion would require recalibration. Forecasts reflect documented assumptions regarding fermentation technology scaling trajectories and pharmacopeia harmonization progress between FDA and Health Canada. Recalibration cycles align with material shifts in EPA permitting timelines and peptide therapeutic approval velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Agricultural Microbials Market