
 Global Agricultural Inoculant Market | 2026-2036
Global Agricultural Inoculant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Inoculant Market Foresight
The capability gap between integrated biotech platforms and commodity blenders is unwinding competitive hierarchies in agricultural biologicals. BASF SE leverages its crop science pipeline to anchor microbial registration pathways across multiple jurisdictions. Lallemand Inc. specializes in yeast and bacteria strain banks that sustain fermentation consistency at commercial scale. Novozymes A/S competes through enzyme-microbe combination products that extend functionality beyond nitrogen fixation alone.
Agricultural inoculants are live microbial preparations containing defined cell counts of bacteria or fungi, typically formulated at concentrations exceeding 10^8 colony-forming units per gram, applied to seeds or soil to enhance nutrient availability through biological nitrogen fixation or phosphorus solubilization. Rhizobium dominates product type revenue due to established efficacy in legume symbiosis and decades of farmer familiarity. Mycorrhiza represents the fastest-expanding product category as drought stress amplifies demand for hyphal network water scavenging in row crops. Application through seed treatment commands margin concentration because coating equipment integration reduces per-acre labor cost versus foliar or soil-applied alternatives.
The EPA regulates microbial pesticide registration under FIFRA, requiring tiered toxicology and non-target organism studies that extend commercialization timelines for novel strains. Brazil's national biosafety commission and the EU's REACH framework impose additional strain-specific risk assessments that shape regional product portfolios. India's Central Insecticides Board mandates local field efficacy trials before import clearance, creating jurisdiction-specific formulation requirements. Stakeholders must monitor regulatory divergence between microbial pesticide and biofertilizer classification pathways, as reclassification triggers distinct data requirements and compliance costs that reshape market access strategies.
Market Dynamics
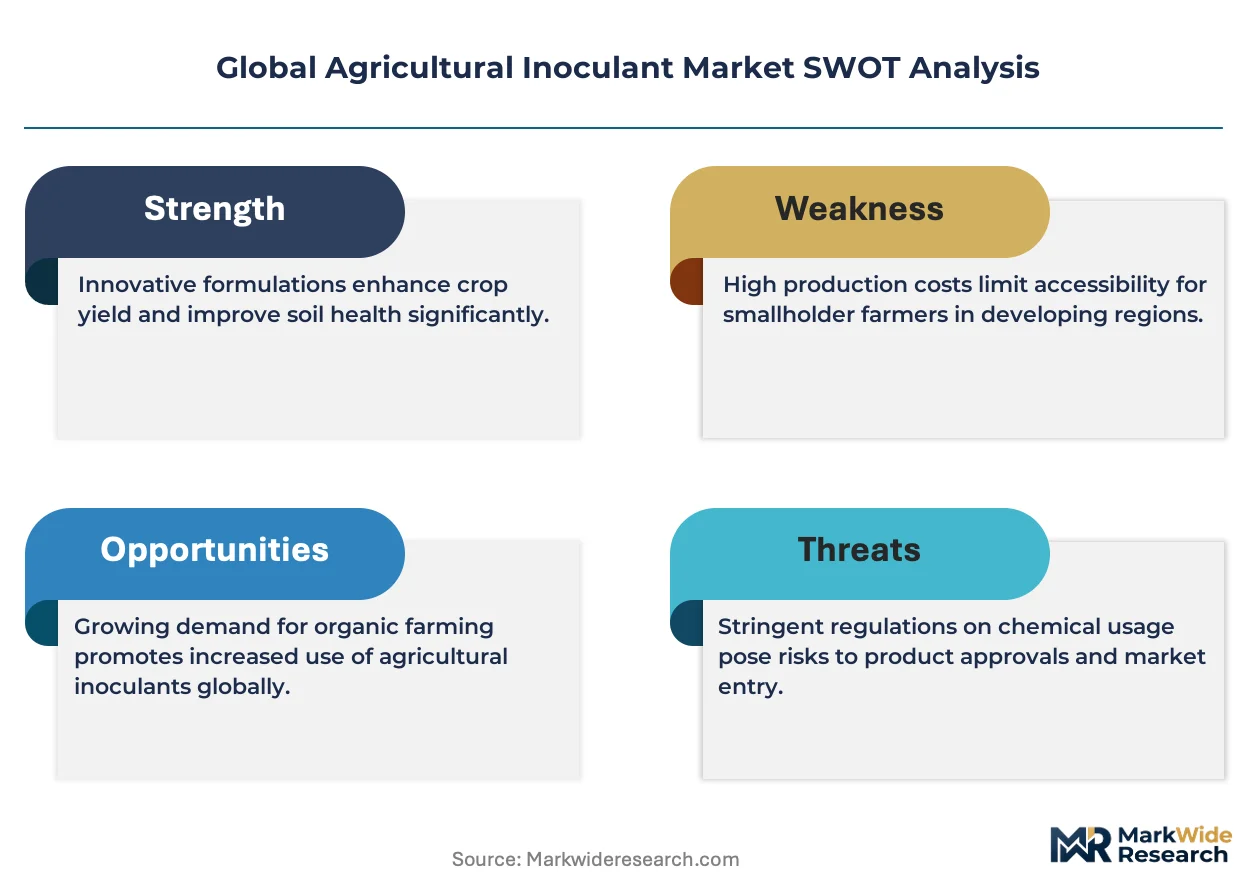
Regulatory divergence between microbial pesticide and biofertilizer classification pathways is fragmenting product registration strategies across jurisdictions. The EU Green Deal and F-Gas Regulation are compressing formulation chemistry timelines toward bio-based alternatives, while strain-specific risk assessments in Brazil and India force region-specific portfolio builds.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal redirects agricultural input subsidies toward biological nitrogen fixation, accelerating Rhizobium and mycorrhiza demand in German and French row-crop operations.
- Soybean-corn rotation intensity:Brazilian and Argentinian planting schedules concentrate commercial-scale legume inoculation, creating predictable seasonal demand anchors for formulated products.
- Phosphorus solubilization technology:Enzyme-microbe combination products extend functionality beyond nitrogen fixation alone, penetrating corn and wheat systems previously served by synthetic fertilizers.
Market Restraints
- Fermentation input cost volatility:Yeast extract and molasses price swings destabilize production economics for commercial-scale bacteria and fungi fermentation.
- Strain bank supply concentration:Proprietary yeast and bacteria strain repositories concentrate in North American and European biobanks, creating dependency risks for emerging market formulators.
- EPA FIFRA registration friction:Tiered toxicology and non-target organism studies extend commercialization timelines for novel microbial strains by 3-5 years versus biofertilizer pathways.
Strategic Opportunities
- Underpenetrated Indian smallholder segment:India's Central Insecticides Board mandates local field efficacy trials before import clearance, creating first-mover advantages for domestic formulation partnerships.
- Seed treatment equipment convergence:Coating equipment integration with precision planting systems reduces per-acre labor cost versus foliar alternatives, opening margin capture in US and Brazilian commercial operations.
- Carbon credit monetization frameworks:Emerging soil carbon protocols in Australia and Canada create verification pathways for biological nitrogen fixation as offset-generating practice.
Industry Challenges
- Microbial strain stability expertise gap:Commercial fermentation consistency at 10^8 CFU/gram concentrations requires specialized bioprocess engineering talent scarce outside established yeast and bacteria specialists.
- Multi-jurisdiction dossier complexity:Divergent data requirements between EPA FIFRA, EU REACH, and Brazil's national biosafety commission force parallel registration investments that strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Inoculant Market |
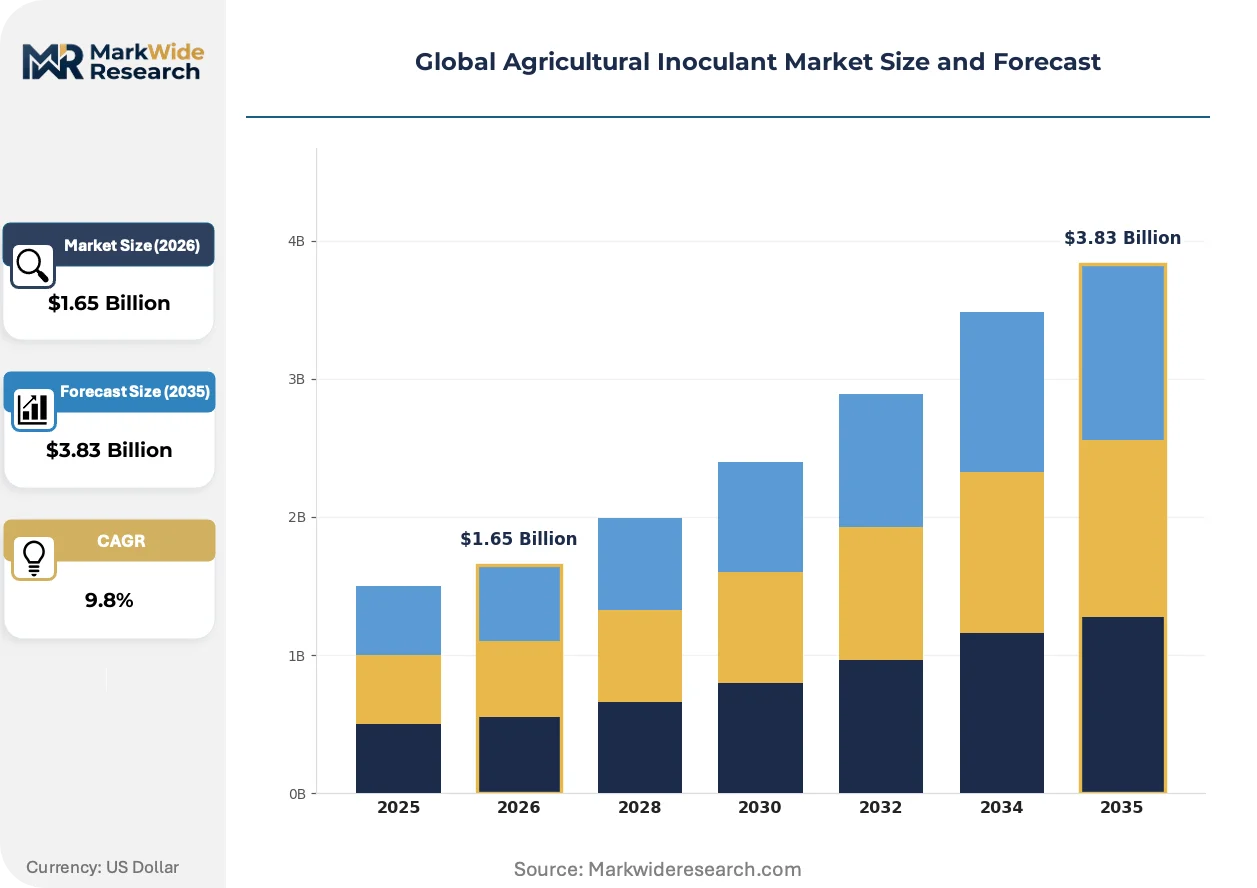
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.83 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhizobium, Azospirillum, Azotobacter, Phosphate-Solubilizing Bacteria, Mycorrhiza, Cyanobacteria Application: Legumes, Cereals, Vegetable Crops, Oilseeds, Fruits, Fiber Crops Form: Powder, Liquid, Granule, Pellet, Gel End User: Seed Treatment, Soil Application, Foliar Spray, Hydroponics |
| Companies Covered | Corteva Agriscience, Lallemand Inc., BASF SE, Lesaffre S.A., Rizobacter Argentina S.A., Bayer AG, Syngenta Group Co., Ltd., Chr. Hansen Holding A/S, Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Inoculant Market Shifts & Advancements
Biological input functionality is extending beyond single-nutrient delivery toward multi-mechanism soil health platforms. Formulators are converging enzyme, microbe, and biostimulant actives into integrated products that command premium positioning against commodity alternatives.
Multi-strain consortia technology is decomposing the historical dominance of single-organism inoculants in row-crop applications. Large-scale corn and wheat operators in the US Midwest are adopting triple-strain bacteria-fungi combinations at accelerating pace. This convergence is decomposing category boundaries between nitrogen fixation, phosphorus solubilization, and biostimulant products, forcing commodity blenders toward integrated platform investments or partnership dependencies.
REACH framework amendments are tightening strain-specific environmental fate data requirements for microbial products entering European markets. Industrial consequence includes mandatory extended terrestrial and aquatic ecotoxicology studies that add 18-24 months to registration timelines. Mycorrhiza formulations face the steepest compliance cost escalation, driving portfolio rationalization toward fewer, higher-volume strains with existing dossier completeness.
Farmer purchasing for biological inputs is consolidating through agronomy retail channels that bundle seed, chemistry, and microbial products into single-season programs. Independent distributors in Brazil and Argentina are losing share to multinational crop science retail networks that integrate inoculant recommendations into prescription planting protocols. This channel compression is most visible in soybean-intensive regions of Mato Grosso and Buenos Aires provinces where bundled program adoption exceeds 60% of commercial hectares.
Global Agricultural Inoculant Market Segmentation
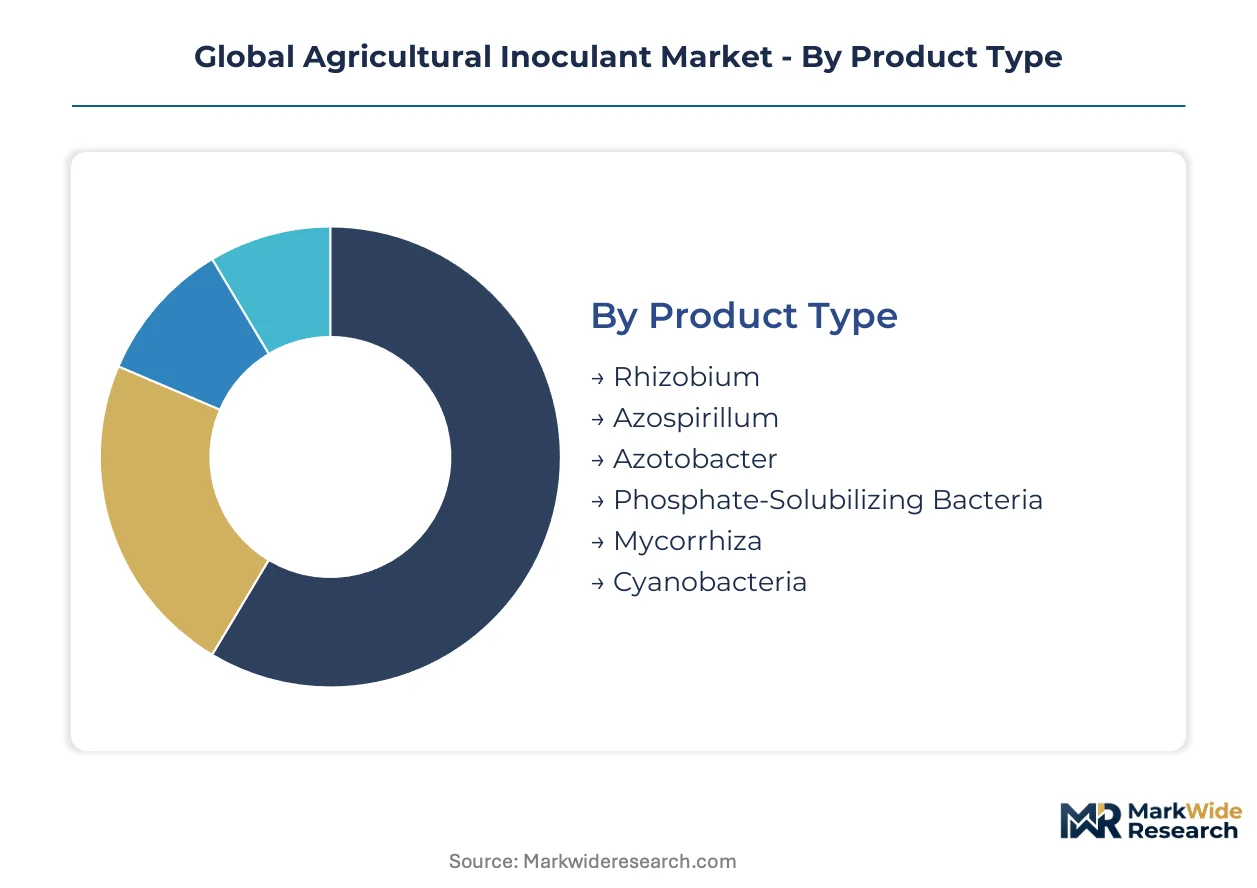
Segmentation in agricultural inoculants reveals how biological functionality maps to distinct farm operational requirements. Each dimension—microbial taxonomy, crop target, physical formulation, and application method—carries unique substitution pressures from synthetic chemistry alternatives and competing biological platforms.
Product Type:
Substitution pressure from synthetic nitrogen fertilizers weighs most heavily on single-mechanism bacterial inoculants, while multi-function microbial consortia demonstrate greater resilience against commodity urea and ammonium nitrate pricing cycles.
- Rhizobium:Symbiotic nitrogen-fixing bacteria forming root nodules on legume hosts, typically formulated at 10^9 CFU/gram. Brazilian and Argentinian soybean operations anchor commercial demand, though farmer price sensitivity spikes when synthetic urea discounts exceed 15%.
- Mycorrhiza:Arbuscular fungi establishing hyphal networks that scavenge water and phosphorus beyond root depletion zones. Drought stress in US Midwest corn and wheat systems accelerates adoption where irrigation constraints intensify.
- Azospirillum:Associative nitrogen-fixing bacteria colonizing cereal root surfaces without nodule formation.
- Azotobacter:Free-living soil bacteria converting atmospheric nitrogen with lower per-cell fixation rates than symbiotic alternatives.
- Phosphate-Solubilizing Bacteria:Microbial strains secreting organic acids that mineralize bound phosphorus in calcareous soils.
- Cyanobacteria:Photosynthetic nitrogen-fixers deployed primarily in rice paddies and aquatic agricultural systems.
Rhizobium anchors the volume base while Mycorrhiza gains share at the steepest rate.
Application:
Cost tier stratification separates commodity row crops from high-value specialty production, with per-acre biological input budgets varying by an order of magnitude between extensive cereal operations and intensive vegetable cultivation.
- Legumes:Soybean, alfalfa, and pulse crops with established Rhizobium symbiosis protocols. Brazilian Mato Grosso and Argentinian Buenos Aires provinces concentrate seasonal demand where crop rotation intensity sustains predictable inoculant procurement.
- Cereals:Corn, wheat, rice, and barley requiring associative or free-living nitrogen fixers. US Midwest operators adopt triple-strain bacteria-fungi combinations as synthetic fertilizer price volatility compresses operating margins.
- Vegetable Crops:High-value produce with elevated biological input budgets per hectare.
- Oilseeds:Canola, sunflower, and peanut systems expanding beyond traditional legume rotations.
- Fruits:Perennial orchards with multi-year mycorrhiza establishment timelines.
- Fiber Crops:Cotton and jute operations in water-stressed growing regions.
Cereals generate the broadest addressable hectarage while Vegetable Crops command the highest per-acre formulation premiums.
Form:
Application method compatibility drives physical formulation selection, with seed coating equipment specifications and irrigation infrastructure constraining viable product formats across different farm scales.
- Powder:Dried microbial preparations with extended ambient stability, compatible with standard seed treatment machinery. Dominates developing market smallholder segments where cold chain logistics remain underdeveloped.
- Liquid:Aqueous suspensions enabling precise dosing integration with precision planting systems. US and Brazilian commercial operations prefer liquid for automated coating line compatibility and reduced dust exposure.
- Granule:Carrier-based formulations for soil banding applications.
- Pellet:Compressed microbial preparations for spot placement near root zones.
- Gel:Viscous formulations optimizing seed adhesion and desiccation protection.
Powder formulations retain the widest geographic penetration while Liquid formats expand most quickly in mechanized farming regions.
End User:
Customer type fragmentation separates integrated seed-chemistry-biological bundling from standalone microbial procurement, with channel concentration reshaping margin capture across retail network tiers.
- Seed Treatment:Pre-plant microbial coating applied through dedicated treatment equipment. Margin concentration here reflects labor cost reduction versus foliar alternatives and prescription planting protocol integration in Brazilian and US commercial operations.
- Soil Application:Direct-to-soil microbial delivery through broadcast or banding equipment. Indian smallholder segments favor soil application where seed treatment infrastructure remains limited.
- Foliar Spray:Aerial or ground-rig microbial application during vegetative growth stages.
- Hydroponics:Recirculating system microbial inoculation for controlled-environment agriculture.
Seed Treatment commands the steepest margin structure while Soil Application retains the deepest volume penetration across emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder farmers in India exhibit acute price sensitivity to synthetic urea discounts exceeding 15%, while commercial operators in Brazil and the United States absorb biological input premiums when bundled with precision planting equipment. This elasticity divide separates volume markets from value capture zones across the agricultural inoculant landscape.
Brazil
Soybean-corn rotation intensity in Mato Grosso and Rio Grande do Sul generates predictable seasonal procurement cycles for Rhizobium formulations. ANVISA's national biosafety commission imposes strain-specific risk assessments that force portfolio localization for foreign entrants. Multinational crop science retail networks in Mato Grosso now bundle inoculant recommendations into prescription planting protocols covering over 60% of commercial hectares.
United States
Midwest corn and wheat operators adopt triple-strain bacteria-fungi combinations as synthetic fertilizer price volatility compresses operating margins. The EPA regulates microbial pesticide registration under FIFRA, requiring tiered toxicology studies that extend novel strain commercialization timelines by 3-5 years. Iowa and Illinois seed treatment infrastructure integrates liquid inoculant dosing with automated coating lines at accelerating pace.
Argentina
Buenos Aires province concentrates legume inoculation demand where crop rotation schedules sustain year-round formulation procurement. The country's national agricultural technology regulator mandates local field efficacy trials before import clearance, creating jurisdiction-specific dossier requirements. Domestic distributors in the Pampas region face share erosion to multinational retail networks bundling biological inputs with seed and chemistry programs.
India
Smallholder segments in Maharashtra and Gujarat favor soil application methods where seed treatment infrastructure remains limited. The Central Insecticides Board mandates local field efficacy trials before import clearance, creating first-mover advantages for domestic formulation partnerships. Punjab and Haryana rice-wheat systems show emerging penetration for cyanobacterial inoculants in flooded paddy cultivation.
Germany
Row-crop operations in Lower Saxony and Bavaria accelerate Rhizobium and mycorrhiza demand following EU Green Deal subsidy redirection toward biological nitrogen fixation. The EU REACH framework tightens strain-specific environmental fate data requirements, adding 18-24 months to registration timelines for novel microbial products. Industrial fermentation specialists in Baden-Württemberg concentrate proprietary yeast and bacteria strain repositories serving continental formulators.
Global Agricultural Inoculant Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in agricultural biologicals, with competitive position hinging on strain bank depth and multi-jurisdiction registration dossiers. Consolidation pressure runs highest where seed-chemistry-biological bundling compresses independent distributor margins. Three archetypes dominate: integrated crop science platforms with microbial registration pathways, fermentation specialists with commercial-scale strain consistency, and enzyme-microbe combination product innovators. Dominant competitive moves include strategic partnerships with precision planting equipment manufacturers and backward integration into proprietary strain repositories.
Within the integrated platform tier, BASF SE and Bayer AG exemplify crop science conglomerates leveraging existing regulatory infrastructure across multiple jurisdictions. Among fermentation specialists, Lallemand Inc. and Chr. Hansen Holding A/S occupy positions anchored by yeast and bacteria strain banks sustaining commercial-scale consistency. Novozymes A/S represents the enzyme-microbe combination archetype, extending functionality beyond nitrogen fixation into phosphorus solubilization and biostimulant adjacencies.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Lallemand Inc. |
| BASF SE |
| Lesaffre S.A. |
| Rizobacter Argentina S.A. |
| Bayer AG |
| Syngenta Group Co., Ltd. |
| Chr. Hansen Holding A/S |
| Novozymes A/S |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Brazilian soybean cooperatives and Rhizobium formulators lock in fermentation capacity and stabilize unit economics across volatile molasses input cycles. These contracts bundle seed treatment services with microbial supply, compressing price discovery into seasonal procurement windows tied to planting schedules in Mato Grosso and Rio Grande do Sul.
Pricing Analysis
After-sales technical service contracts drive lifetime value for commercial-scale operators, with formulation providers embedding agronomic advisory into multi-season programs. Three-tier pricing structure across premium, standard, and economy levels separates high-CFU consortia with extended viability guarantees from commodity powders. Cost compression in standard-tier powders is intensifying because Indian smallholders exhibit acute sensitivity to synthetic urea discounts exceeding 15%. Vegetable crop specialists absorb the steepest premiums, while cereal operators in the US Midwest negotiate volume-scaled seed treatment bundles.
Supply Chain Analysis
Strait of Hormuz transit underwrites yeast extract supply security for European fermentation specialists, with alternative routing through Suez adding 12-14 days to delivery schedules. Proprietary strain repositories concentrate in Germany, the United States, and Canada, drawing from molasses feedstock anchored in Brazilian sugarcane processing and Indian jaggery operations. Single-source vulnerability runs through North American yeast extract suppliers, where consolidation among three industrial bioprocessors creates dependency risk for emerging market formulators. Distribution runs through agronomy retail networks that bundle microbial inputs with seed and chemistry programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as synthetic fertilizer price volatility compresses operating margins and redirects procurement toward biological nitrogen fixation alternatives.
For Market Incumbents: Fortify proprietary strain bank depth through backward integration into cryopreserved repository operations, defending against emerging enzyme-microbe combination specialists. Expand fermentation capacity in Baden-Württemberg and Iowa to capture seed treatment equipment convergence in precision planting systems. Prioritize EPA FIFRA registration dossier completion for novel consortia strains before REACH amendments tighten environmental fate data requirements. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat smallholder segments where soil application methods dominate and domestic formulation partnerships unlock Central Insecticides Board clearance. Target cyanobacterial inoculants for Punjab rice-wheat systems as the most penetrable entry vector. Pursue white-label supply agreements with established fermentation specialists rather than building captive bioprocess capacity. For Investors and Strategic Acquirers: Regional strain repository specialists with completed Brazil ANVISA and India Central Insecticides Board dossiers represent priority acquisition targets, capturing jurisdiction-specific regulatory moats. Long-term viability hinges on carbon credit monetization framework maturation across Australian and Canadian soil carbon protocols. Monitor EU Green Deal subsidy execution velocity as the critical inflection signal for biological nitrogen fixation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Repository Expansion | Proprietary cryopreserved banks in Germany and Iowa secure fermentation consistency for commercial-scale consortia production. |
| Seed Treatment Equipment Integration | Liquid dosing compatibility with automated coating lines in Mato Grosso reduces per-acre labor cost versus foliar alternatives. |
| Multi-Jurisdiction Dossier Completion | Parallel EPA FIFRA and EU REACH submissions compress commercialization timelines for novel microbial strains by 18-24 months. |
| Domestic Formulation Partnership | Local field efficacy trials in Maharashtra satisfy Central Insecticides Board mandates and accelerate Indian market access. |
| Carbon Credit Verification Pathway | Australian soil carbon protocol registration enables biological nitrogen fixation offset monetization for commercial operators. |
Research Methodology
The analysis maps Rhizobium, mycorrhiza, and enzyme-microbe combination sub-sectors, each validated through fermentation process engineers, seed treatment equipment specialists, and agronomy retail procurement directors. Primary interviews with Brazilian cooperative managers, Indian smallholder extension officers, and German regulatory affairs leads combined with secondary validation from EPA FIFRA registration databases, EU REACH dossier filings, and ANVISA biosafety commission records. Bottom-up strain-level volume builds triangulated against top-down agricultural input expenditure flows from customs and trade data.
Consistency checks validated volume and value outputs against external benchmarks including fertilizer industry association reports and microbial pesticide registration trend analyses. Segmentation dimensions modeled encompass microbial taxonomy, crop target, physical formulation, and application method across the projection horizon. CAGRs derived from fitted growth curves incorporating EU Green Deal subsidy trajectory, synthetic fertilizer price volatility indices, and precision planting equipment penetration rates.
Underlying assumptions cover EU REACH framework amendment timing and Brazil ANVISA review cycle duration, with deviation risk concentrated in EPA FIFRA reclassification decisions and Indian urea subsidy policy shifts. Practitioners should keep alternative scenarios live as carbon credit protocol verification standards and seed treatment equipment interoperability specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market