
 South America Beta-Glucan Market | 2026-2036
South America Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
South America Beta-Glucan Market Analytics
Consolidation among Brazilian nutraceutical buyers is repositioning contract terms toward longer supply agreements with volume guarantees. Kerry Group PLC leverages its regional ingredient platform to secure multi-year partnerships with functional food manufacturers. Ceapro Inc. anchors its position through specialized extraction capabilities serving pharmaceutical-grade demand. Biospringer competes aggressively on yeast-derived beta-glucan pricing across Mercosur distribution channels.
Beta-glucan comprises a class of glucose polysaccharides linked by beta-glycosidic bonds, with molecular weight and branching patterns varying by source organism; yeast-derived forms typically contain beta-1,3/1,6 linkages valued for immunomodulatory activity, while cereal sources carry beta-1,3/1,4 structures favored for cholesterol management in functional food systems. Food Grade beta-glucan from oat and barley sources dominates volume flows into breakfast cereal and dairy applications across the region. Pharmaceutical Grade material commands premium positioning as Brazilian and Argentine regulators tighten purity documentation requirements for immune-modulating therapeutics. Mushroom-sourced beta-glucan occupies a specialized niche within nutraceutical formulations targeting adaptogenic positioning.
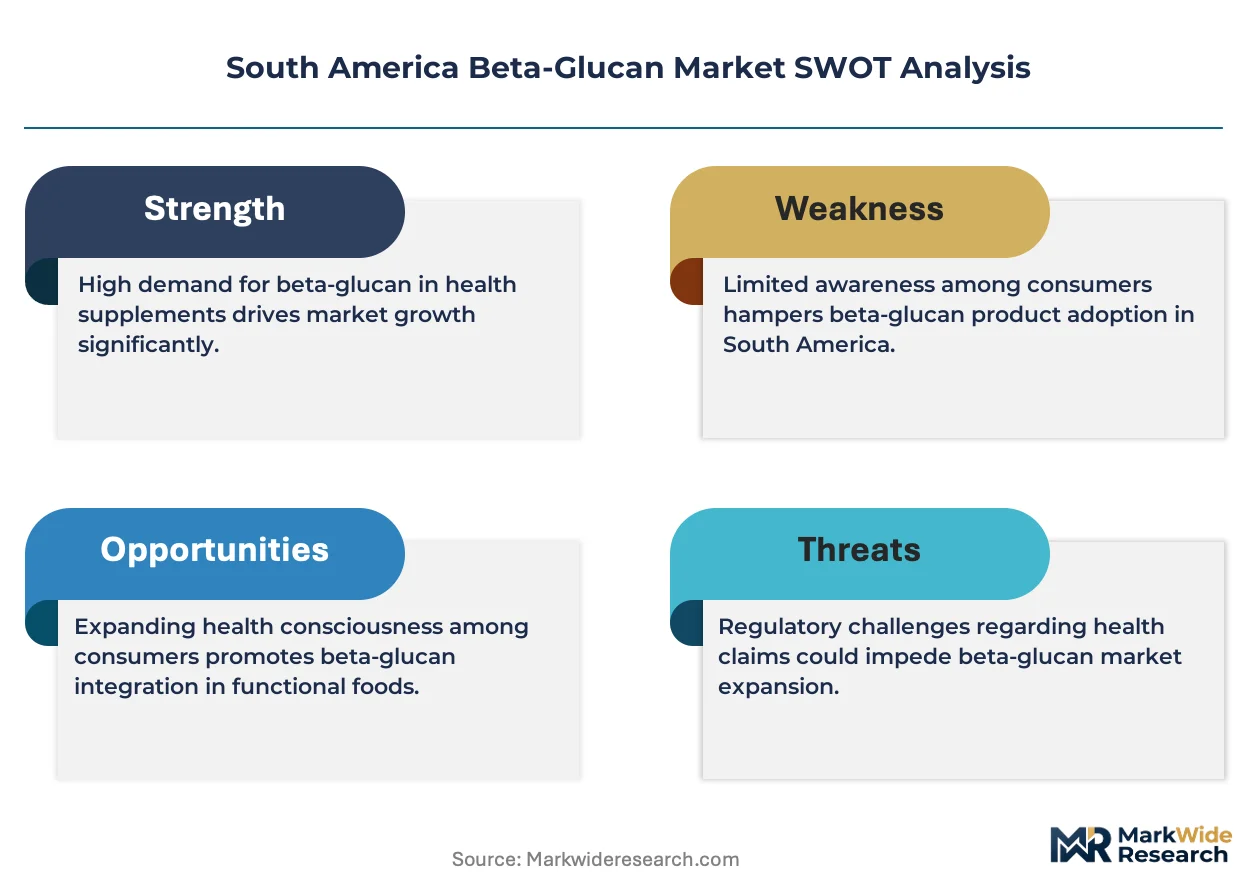
ANVISA governs novel food ingredient approvals and health claim substantiation in Brazil, while Argentina's national food regulator enforces Mercosur-aligned labeling standards that constrain unsubstantiated immune benefit messaging. Brazil's PLI scheme for biotechnology inputs indirectly supports domestic beta-glucan fermentation capacity expansion through equipment cost offsets. Stakeholders must monitor pending harmonization between Chile's food safety agency and Mercosur technical regulations, as divergence in beta-glucan dosage thresholds for health claims could fragment regional product formulation strategies and force parallel compliance investments.
Market Dynamics
ANVISA's compressed novel food registration timelines are restructuring procurement relationships across Brazil's nutraceutical corridor, forcing ingredient suppliers to pre-certify extraction protocols before contract negotiations conclude.
Growth Catalysts
- ANVISA Registration Acceleration:Brazil's streamlined novel food protocols reduce beta-glucan approval cycles from 24 months to 14 months, enabling faster product launches in functional dairy and breakfast cereal categories.
- Immune-Positioned Nutraceutical Demand:Argentine and Brazilian formulators are expanding yeast-derived beta-glucan volumes for supplement SKUs targeting respiratory health positioning in pharmacy channels.
- Sao Paulo Manufacturing Corridor Concentration:Southeast Brazil's processing cluster generates scale efficiencies in extraction and formulation that lower unit costs for Mercosur distribution.
Market Restraints
- Raw Material Input Volatility:Oat and barley feedstock prices fluctuate with Argentine agricultural output cycles, compressing margins for cereal-derived beta-glucan processors during drought periods.
- Extraction Technology Concentration:Pharmaceutical-grade purification capabilities cluster with a limited supplier base in southern Brazil, creating bottleneck risk for high-purity immune-modulating applications.
- Health Claim Regulatory Friction:Argentina's national food regulator enforces strict Mercosur-aligned substantiation standards that limit immune benefit messaging on packaging, constraining consumer pull-through.
Strategic Opportunities
- Chilean Market Entry:Chile's pending harmonization with Mercosur technical regulations creates first-mover positioning for beta-glucan suppliers establishing Santiago-based distribution before dosage threshold alignment finalizes.
- Mushroom-Derived Adaptogenic Positioning:Shiitake and reishi-sourced beta-glucan variants command premium pricing in Brazilian nutraceutical channels targeting stress-management and cognitive function applications.
- PLI Biotechnology Incentives:Brazil's production-linked incentive scheme for biotechnology inputs subsidizes fermentation equipment costs, enabling domestic capacity expansion for yeast-derived beta-glucan production.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:ANVISA's purity documentation requirements for immune-modulating therapeutics extend validation cycles, delaying revenue recognition for high-margin product segments.
- Cross-Border Formulation Standardization:Divergent beta-glucan dosage thresholds for health claims across Brazil, Argentina, and Chile force parallel product development tracks, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Beta-Glucan Market |
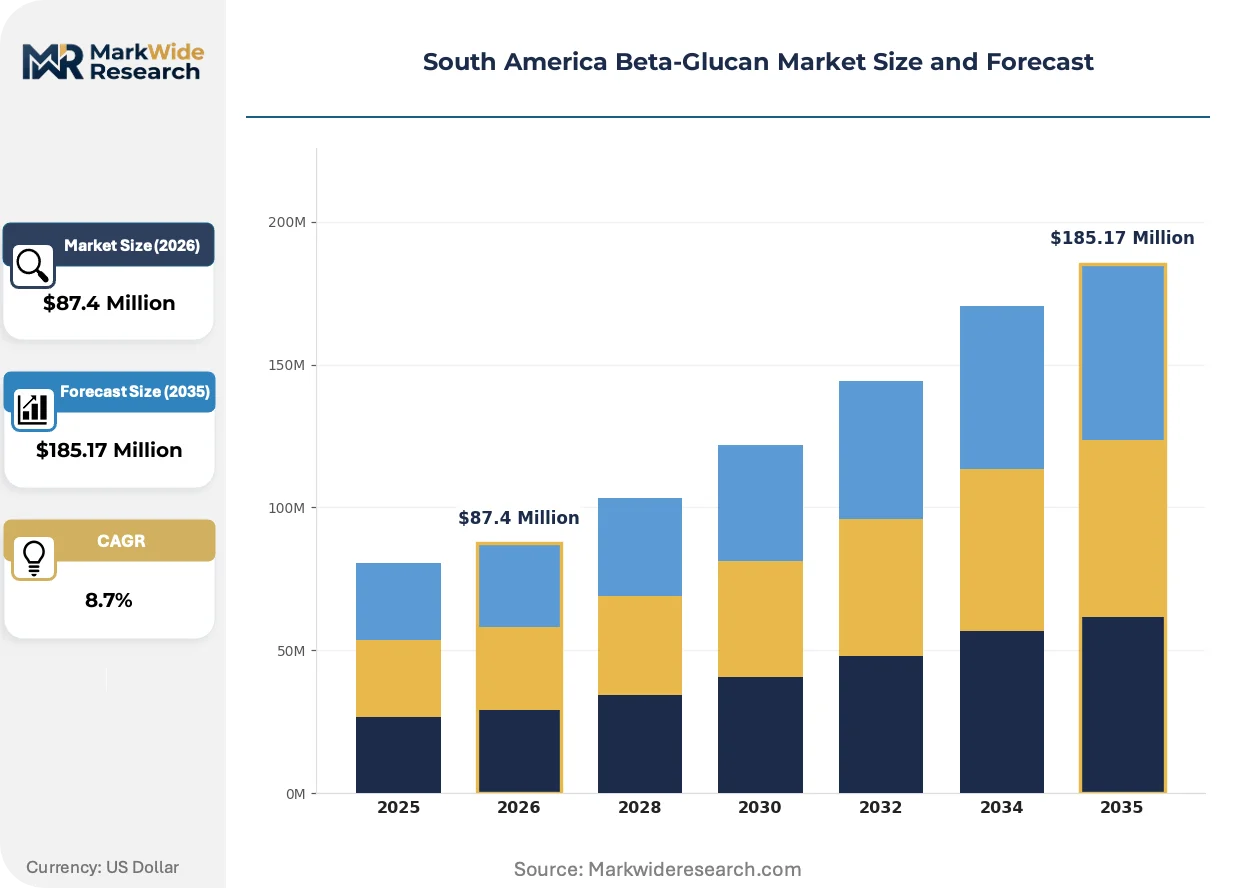
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Veterinary Grade, Cosmetic Grade Application: Functional Foods, Nutraceuticals, Supplements, Personal Care Source: Yeast, Oats, Barley, Mushrooms Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Tate & Lyle PLC, Kerry Group PLC, Biothera Inc., Lesaffre, Koninklijke DSM N.V., Biospringer, Kemin Industries, Garuda International Inc., Ceapro Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Beta-Glucan Market Evolving Landscape
Extraction technology convergence and regulatory harmonization pressures are compressing competitive differentiation in South American beta-glucan supply, favoring suppliers with integrated fermentation-to-formulation capabilities.
Ultrafiltration-based purification is consolidating quality tiers in yeast-derived beta-glucan production. Brazilian pharmaceutical-grade buyers in Sao Paulo's manufacturing corridor are adopting membrane filtration systems at accelerated replacement cycles. This technology compression is eliminating intermediate purity grades and forcing suppliers to choose between commodity food-grade positioning or full pharmaceutical certification investment.
ANVISA's evolving health claim substantiation framework is tightening evidentiary standards for immune-modulatory positioning. Brazilian functional food manufacturers must now submit clinical trial data packages that were previously accepted through literature reviews. Supplement formulators targeting pharmacy channels are responding by partnering with domestic research institutions for localized efficacy studies.
Direct-procurement relationships between nutraceutical brands and extraction facilities are displacing traditional ingredient distributor networks in Mercosur markets. Argentine and Brazilian formulators now negotiate volume-guaranteed multi-year contracts that bypass regional chemical distributors. This channel restructuring is most visible in Sao Paulo's southeastern corridor, where Kerry Group and Ceapro have established captive supply partnerships with breakfast cereal and dairy processors.
South America Beta-Glucan Market Segmentation
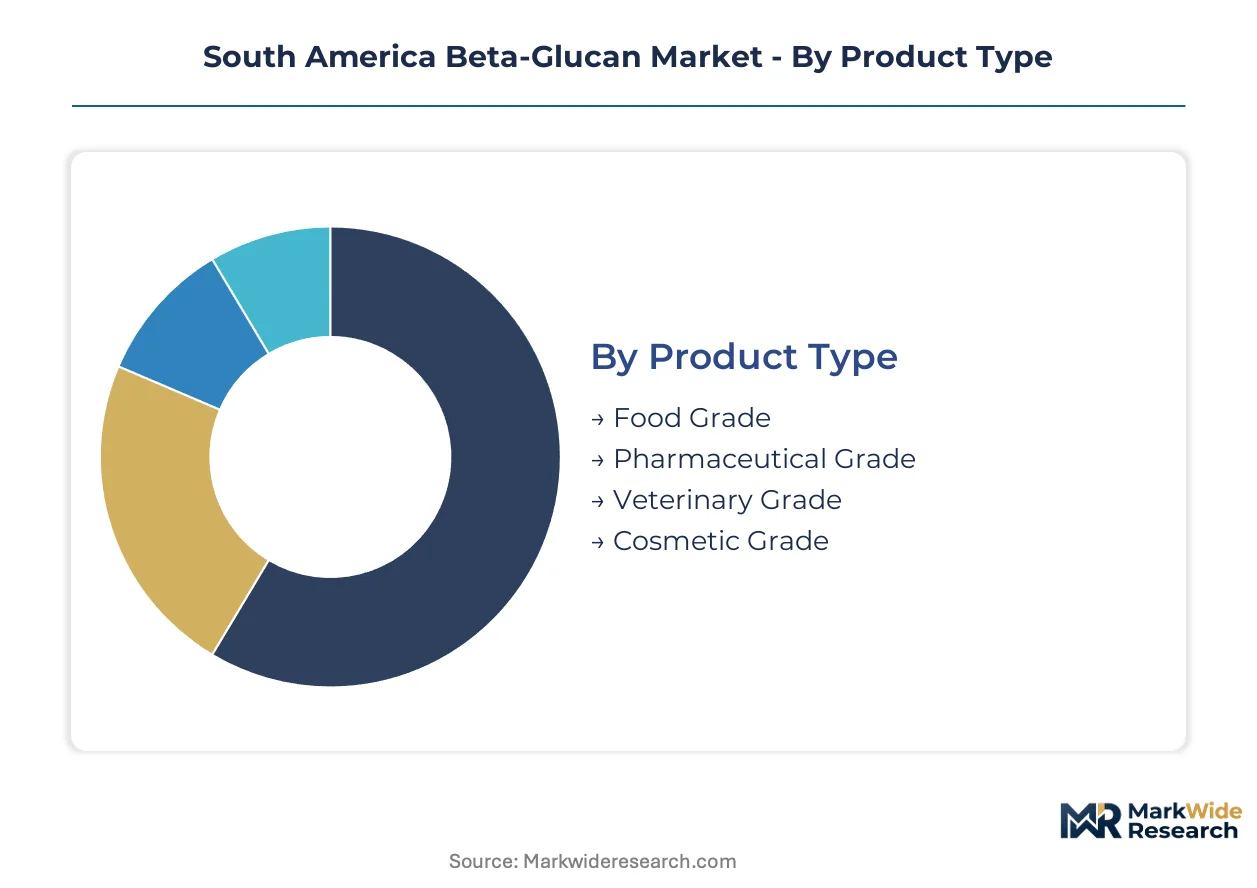
Beta-glucan procurement patterns in South America diverge sharply across purity grades and end-use specifications. ANVISA's tiered registration pathways and Mercosur labeling harmonization pressures are forcing suppliers to align product portfolios with distinct buyer cost thresholds and compliance capacities.
Product Type:
Brazilian and Argentine buyers separate into distinct procurement tiers based on documentation burden tolerance and margin structure.
- Food Grade:Oat and barley-derived polysaccharides with beta-1,3/1,4 linkages dominate breakfast cereal and dairy formulations across Sao Paulo's manufacturing corridor. Sao Paulo-based processors leverage Mercosur distribution scale to compress unit costs for functional food applications where cholesterol management claims require minimal clinical substantiation.
- Pharmaceutical Grade:Yeast-sourced beta-1,3/1,6 glucans with ultrafiltration purification command premium positioning for immune-modulating therapeutics. ANVISA's tightened purity documentation requirements extend validation cycles for Brazilian pharmaceutical manufacturers, concentrating procurement relationships with Ceapro and Kerry Group for certified supply security.
- Veterinary Grade:Mid-purity extracts serve livestock feed additive applications in Argentina's agricultural belt.
- Cosmetic Grade:Low-molecular-weight variants target dermal absorption specifications in Brazilian personal care formulations.
Food Grade leads volumes today; Pharmaceutical Grade is expanding most quickly.
Application:
End-use concentration tracks regulatory pathway complexity and health claim permissibility across Brazil and Argentina.
- Functional Foods:Beta-glucan fortification in breakfast cereals and dairy products concentrates in southeast Brazil's processing cluster. Sao Paulo-based manufacturers exploit ANVISA's compressed novel food timelines to accelerate immune-positioned product launches with literature-based substantiation.
- Nutraceuticals:Yeast-derived immune support formulations dominate pharmacy channel distribution in Brazil and Argentina. Argentine formulators face Mercosur-aligned labeling constraints that limit respiratory health messaging, compressing consumer pull-through versus Brazilian counterparts.
- Supplements:Capsule and tablet formats target direct-to-consumer immune positioning.
- Personal Care:Topical applications leverage beta-glucan's film-forming properties in Brazilian cosmetic formulations.
Functional Foods anchors current revenue; Nutraceuticals shows steepest expansion trajectory.
Source:
Feedstock selection determines molecular architecture, extraction cost structure, and regulatory classification pathways.
- Yeast:Saccharomyces cerevisiae cell walls yield beta-1,3/1,6 glucans with established immunomodulatory mechanisms. Brazilian PLI biotechnology incentives subsidize domestic fermentation capacity expansion, enabling local production cost parity with imported cereal sources.
- Oats:Avena sativa-derived beta-1,3/1,4 glucans command cholesterol reduction positioning in Mercosur functional food regulations. Argentine agricultural output volatility creates margin compression risk for processors dependent on Patagonian feedstock supply.
- Barley:Hordeum vulgare sources compete with oats on viscosity and solubility specifications.
- Mushrooms:Shiitake and reishi-derived variants occupy premium adaptogenic positioning in Brazilian nutraceutical channels.
Yeast dominates procurement volumes; Mushrooms commands highest per-kilogram pricing.
Distribution Channel:
Channel selection reflects buyer sophistication, purchase frequency, and regulatory information requirements.
- Pharmacies:Immune-positioned supplements and pharmaceutical-grade therapeutics concentrate in Brazil's pharmacy channel where ANVISA health claim enforcement is most stringent. Direct procurement relationships between formulators and extraction facilities are displacing traditional distributor networks for volume-guaranteed supply.
- Supermarkets:Mass-market functional foods and breakfast cereals flow through Brazil's southeastern retail corridor. Sao Paulo-based processors negotiate captive supply partnerships that bypass regional chemical distributors for cost efficiency.
- Online:Direct-to-consumer platforms expand reach for specialized mushroom-derived variants.
- Health Stores:Specialty retailers target premium positioning for adaptogenic and organic-certified products.
Supermarkets move the largest unit volumes; Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation technicians and extraction chemists cluster in Brazil's southeastern biotechnology corridor, anchoring regional production capacity for yeast-derived beta-glucan. Argentina's agricultural processing workforce supports cereal-source extraction facilities in the Pampas grain belt. Chile's emerging nutraceutical talent pool is consolidating around Santiago's life sciences research institutions.
Brazil
ANVISA's compressed novel food registration protocols are accelerating product launch timelines for functional food manufacturers. The PLI biotechnology incentive scheme subsidizes fermentation equipment investments, enabling domestic capacity expansion for Saccharomyces cerevisiae-derived production. São Paulo's manufacturing corridor hosts the region's densest concentration of extraction and formulation facilities, with processors commanding captive supply relationships across Mercosur distribution channels.
Argentina
Oat and barley feedstock availability from the Pampas agricultural belt determines input cost structures for cereal-derived beta-glucan processors. The national food regulator enforces Mercosur-aligned labeling standards that constrain unsubstantiated immune benefit messaging on packaging. Buenos Aires province concentrates mid-purity extraction facilities serving both domestic functional food manufacturers and cross-border supply to Brazilian dairy processors.
Chile
Pending harmonization between the national food safety agency and Mercosur technical regulations is creating first-mover positioning opportunities for suppliers establishing Santiago-based distribution. The country's research institutions are generating localized clinical efficacy data packages that meet tightening ANVISA evidentiary standards. Northern metropolitan areas are emerging as import gateways for mushroom-derived adaptogenic formulations targeting premium nutraceutical channels.
Colombia
Andean agricultural diversification programs are expanding barley cultivation for regional beta-glucan feedstock supply. The national health regulator maintains distinct novel food approval pathways that lag Brazilian timelines by 6-8 months. Bogotá's processing cluster serves domestic functional dairy applications while importing pharmaceutical-grade material from Brazilian suppliers.
Peru
Traditional medicine export channels are driving demand for mushroom-sourced beta-glucan variants targeting North American and Asian adaptogenic markets. The country's sanitary regulatory agency coordinates with ANVISA on mutual recognition protocols for ingredient safety documentation. Lima's coastal manufacturing zone concentrates cosmetic-grade extraction for dermal absorption applications in personal care formulations.
South America Beta-Glucan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's beta-glucan supply structure. The market exhibits moderate consolidation, with three to four integrated ingredient platforms commanding disproportionate influence over pharmaceutical-grade procurement relationships. Strategic archetypes include global nutrition conglomerates with regional fermentation assets, specialized extraction technology providers, and agricultural processors with downstream purification capabilities. Competitive dynamics center on multi-year volume guarantee contracts and pre-certification of extraction protocols ahead of ANVISA registration deadlines.
Within the specialized extraction tier, Ceapro Inc. and Biospringer occupy positions anchored by differentiated feedstock capabilities. Ceapro Inc. exemplifies the pharmaceutical-grade purification specialist archetype, while Biospringer represents yeast-derived production scale. Kerry Group PLC sits within the diversified nutrition conglomerate category, leveraging integrated ingredient platforms across the Mercosur corridor. These three entities collectively illustrate the competitive segmentation between purity-grade specialization and broad portfolio breadth that defines regional supply relationships.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group PLC |
| Biothera Inc. |
| Lesaffre |
| Koninklijke DSM N.V. |
| Biospringer |
| Kemin Industries |
| Garuda International Inc. |
| Ceapro Inc. |
| Others |
Value Network & Pricing Analysis
São Paulo-based nutraceutical formulators anchor procurement demand across the Mercosur corridor, concentrating purchasing power that favors contract-based long-term offtake agreements with volume-guaranteed pricing over spot market transactions.
Pricing Analysis
Service bundling separates pharmaceutical-grade supply relationships from commodity food-grade transactions. Three-tier pricing structure across pharmaceutical, food, and feed grades reflects ANVISA certification burden and ultrafiltration investment requirements. Cost compression in food-grade cereal derivatives intensifies because Argentine drought cycles spike oat and barley feedstock costs. Small-scale cosmetic formulators exhibit highest price sensitivity, while immune-therapeutic manufacturers accept premium positioning for documented purity.
Supply Chain Analysis
Brazil's PLI biotechnology incentives reshape sourcing by subsidizing domestic Saccharomyces cerevisiae fermentation capacity, reducing import dependency for yeast-derived inputs. Supply concentrates in Brazil, Argentina, and Chile, with São Paulo's extraction corridor feeding Mercosur distribution. Raw material flows draw from Patagonian grain belts, domestic yeast fermentation tanks, and imported mushroom biomass. Single-source vulnerability concentrates in pharmaceutical-grade ultrafiltration capabilities clustered in southern Brazil. Distribution runs through direct-procurement partnerships displacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers where ANVISA's tightened purity documentation extends validation cycles and protects pricing power for pre-qualified suppliers.
For Market Incumbents: Cement captive supply relationships with São Paulo-based breakfast cereal and dairy processors through multi-year volume guarantees ahead of competitor pre-certification. Deepen backward integration into yeast fermentation capacity utilizing PLI equipment subsidies to offset capital requirements. Defend against Biospringer's aggressive Mercosur pricing by locking pharmaceutical-grade procurement with Ceapro-level purification documentation. For New Entrants and Emerging Players: Enter via Chile's pending Mercosur harmonization window before dosage threshold alignment finalizes, establishing Santiago-based distribution for first-mover positioning. Target mushroom-derived adaptogenic formulations in Brazilian stress-management channels where premium pricing tolerates new entrant cost structures. Pursue direct-procurement partnerships with Argentine nutraceutical formulators facing labeling constraints that limit immune messaging and compress incumbent margins. For Investors and Strategic Acquirers: Diversified nutrition conglomerates with regional fermentation assets represent the most active acquirer category in this space, seeking pharmaceutical-grade purification capabilities to complete integrated portfolios. Long-term viability hinges on ANVISA registration acceleration sustaining faster product launch timelines against regulatory friction risks. Acquisition target archetype: specialized extraction technology providers with certified ultrafiltration infrastructure. Watch ANVISA-Mercosur dosage threshold harmonization progress as inflection indicator for cross-border formulation standardization investments.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Certification Investment | Accelerated novel food registration timelines compress competitive entry windows for immune-positioned products. |
| Yeast Fermentation Capacity Expansion | PLI biotechnology subsidies enable domestic production cost parity with imported cereal beta-glucan sources. |
| Direct-Procurement Partnership Formation | Volume-guaranteed contracts with São Paulo processors displace traditional distributor networks across Mercosur. |
| Pharmaceutical-Grade Ultrafiltration Upgrade | Membrane filtration technology consolidation eliminates intermediate purity tiers and forces certification investment. |
| Mushroom-Derived Adaptogenic Positioning | Shiitake and reishi-sourced variants command premium pricing in Brazilian cognitive function applications. |
Research Methodology
Bottom-up nutraceutical formulation modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with ANVISA regulatory affairs specialists, São Paulo procurement directors, Argentine agricultural processors, and Chilean nutraceutical formulators combined with secondary validation from ANVISA registration databases, Mercosur technical regulation filings, and Brazilian customs trade records. Triangulation between supply-side fermentation capacity surveys and demand-side SKU launch tracking ensures cross-verified outputs.
Input-output matrices segment the market by purity grade, source organism, end-use application, and distribution channel across the projection horizon. CAGRs derive from regression analysis of historical ANVISA approval velocity, PLI subsidy uptake rates, and Mercosur cross-border trade flows. Forecast inputs incorporate oat and barley yield volatility from Argentine agricultural output cycles and yeast fermentation capacity expansion timelines under biotechnology incentive schemes.
Inputs from ANVISA registration databases and Mercosur harmonization working papers were available through the study window; gaps in real-time Chilean dosage threshold negotiations introduce uncertainty bands around cross-border formulation standardization timelines. Forecasts reflect documented assumptions regarding PLI subsidy continuity and ANVISA evidentiary framework stability. Regulatory divergence risk, feedstock price volatility, and extraction technology concentration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Chitosan for Agriculture Market