
 Acetoin Natural Market | 2026-2036
Acetoin Natural Market Size, Share, and Industry Trends Forecast 2026-2036
Acetoin Natural Market Outlook
European biotech fermentation capacity is realigning toward natural flavor precursors as synthetic vanillin substitutes face tightening restrictions. Vigon International leverages its New Jersey flavor ingredient hub to sustain North American supply lines for beverage manufacturers. Axxence Aromatic GmbH anchors German production of high-purity natural aroma chemicals through backward integration into botanical sourcing. Qingdao CEPA Energy Technology Co., Ltd. competes on fermentation scale, positioning its Shandong facilities to serve Asian processed food exporters.
Acetoin natural refers to a biologically derived vicinal diketone (C4H6O2) produced through microbial fermentation of glucose or pyruvate, typically yielding 99% purity grades for food-contact applications. Its primary industrial purpose centers on imparting buttery, creamy flavor notes to confectionery, dairy analogs, and savory formulations without synthetic labeling. Liquid acetoin dominates current volume flows due to ease of incorporation into continuous food processing lines, while powder grades capture premium margin pools in dry-mix flavoring and encapsulated pharmaceutical coatings. The food and beverage application segment leads absolute consumption, though cosmetics-grade specifications are emerging as the fastest-growing demand pocket as clean beauty brands reformulate away from petroleum-derived fragrance fixatives.
EFSA flavoring substance evaluations under Regulation (EC) No 1333/2008 determine which acetoin sources qualify for EU natural labeling, directly shaping market access for fermentation-derived versus chemically identical synthetic variants. REACH registration requirements for bulk importers add compliance layers that favor established European compounders with dedicated regulatory affairs functions. FDA GRAS self-determination pathways in the United States create a bifurcated approval landscape where documentation rigor separates premium suppliers from commodity traders. Stakeholders must monitor evolving distinctions between natural-identical and biologically sourced designations as major retail chains tighten ingredient transparency protocols.
Market Dynamics
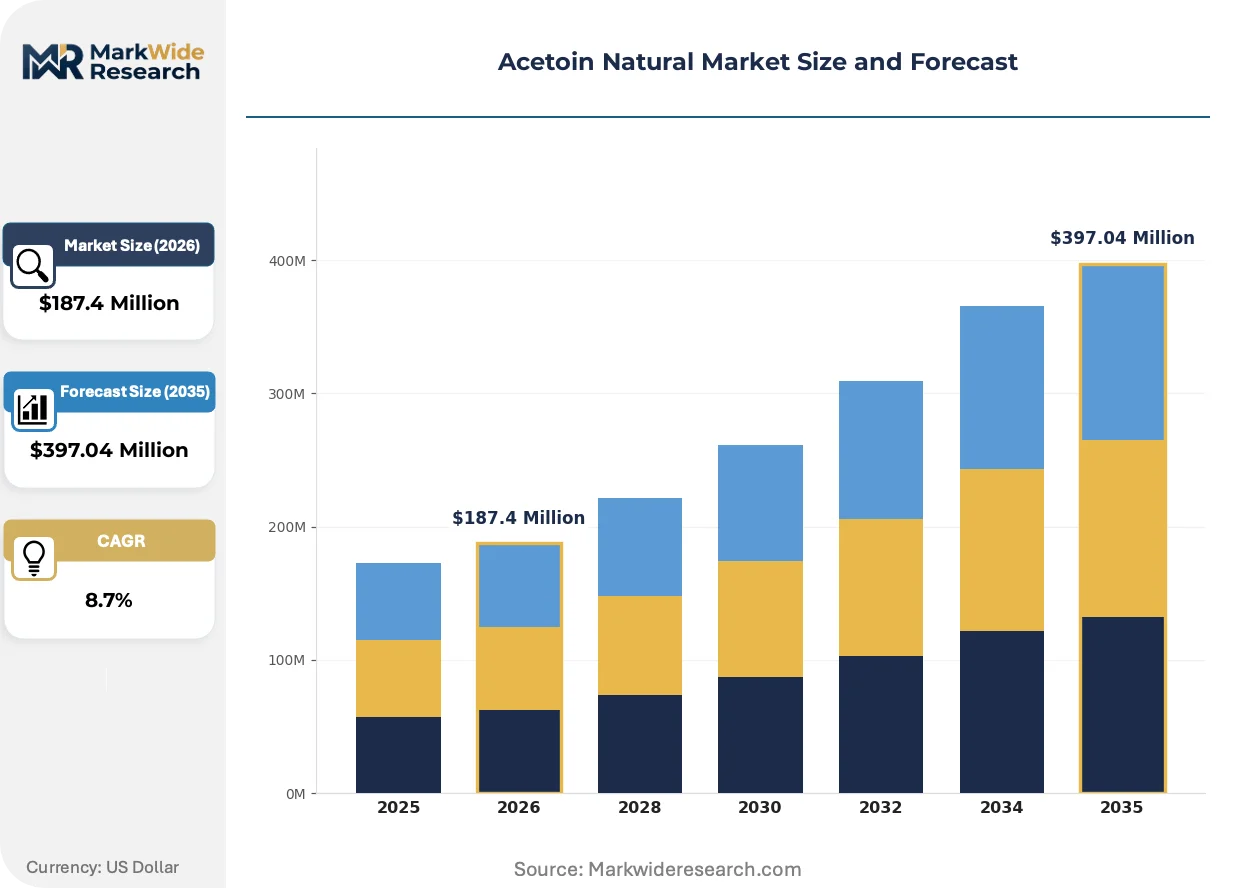
Clean-label mandates from EU REACH and EFSA are forcing dairy and confectionery formulators to source fermentation-derived acetoin, redirecting procurement budgets away from synthetic alternatives and concentrating supply relationships around certified biotech clusters.
Growth Catalysts
- EFSA Flavoring Evaluations:Regulation (EC) No 1333/2008 classifications for natural-origin substances are disqualifying synthetic acetoin from EU natural-labeled products, compelling reformulation toward biologically derived grades.
- Clean-Beauty Fragrance Fixatives:Cosmetics brands are replacing petroleum-derived stabilizers with natural acetoin in perfume and skincare formulations, opening a parallel demand channel beyond food applications.
- Rhine-Ruhr Fermentation Clusters:Germany's concentration of flavor houses and biotech infrastructure around Düsseldorf and Cologne is creating captive supply ecosystems that reduce procurement friction for European formulators.
Market Restraints
- Glucose Feedstock Volatility:Fermentation economics hinge on corn and wheat-derived glucose prices, which fluctuate with agricultural commodity cycles and biofuel policy shifts in major producing regions.
- Single-Source Bioreactor Dependency:Commercial-scale natural acetoin production remains concentrated among a handful of fermentation specialists, creating vulnerability to batch contamination or facility downtime.
- Diacetyl Substitution Pressure:Food manufacturers in cost-sensitive segments continue using synthetic diacetyl for buttery flavor notes, particularly where natural labeling carries no retail price premium.
Strategic Opportunities
- Shandong Export Corridor:Qingdao and Yantai fermentation facilities are scaling capacity to serve Southeast Asian processed food exporters seeking EU-compliant natural flavor documentation.
- Encapsulated Dry-Mix Formats:Powder-grade acetoin for instant beverage and baking premix applications commands margin premiums over liquid grades due to extended shelf stability and handling convenience.
- USDA BioPreferred Program:Federal procurement preferences for biobased products are creating institutional demand anchors for fermentation-derived acetoin in school nutrition and military ration programs.
Industry Challenges
- Fermentation Scale-Up Talent:Industrial microbiology expertise for 100,000-liter-plus bioreactor operations remains scarce, extending commissioning timelines for new production capacity.
- REACH Registration Burden:Bulk importers face documentation and testing costs that favor established European compounders with dedicated regulatory affairs functions over emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetoin Natural Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Concentrate, Emulsion Application: Food & Beverage, Cosmetics, Pharmaceuticals, Flavoring End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | The Good Scents Company, UBM EMEA, Vigon International, Axxence Aromatic GmbH, Qingdao CEPA Energy Technology Co., Ltd., Sunaux, RPX Corporation, Penta Manufacturing Company, Charkit Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetoin Natural Market Strategic Shifts
Continuous fermentation monitoring and precision metabolic engineering are compressing batch-to-batch variability, enabling food-grade acetoin producers to promise tighter specification windows than chemical synthesis alternatives.
Modular skid-mounted bioreactor systems are decentralizing production geography for natural acetoin. Regional dairy cooperatives and mid-sized flavor houses are deploying 5,000-20,000 liter units at customer-adjacent sites, cutting transport costs for temperature-sensitive liquid grades. This distributed model is compressing the historical advantage of centralized Rhine-Ruhr and Shandong production basins.
REACH registration requirements for bulk importers are tightening documentation standards for natural-origin claims. ECHA substance evaluation protocols now demand carbon-14 isotope testing to distinguish fermentation-derived from petrochemical-sourced acetoin. German and Dutch compounders with in-house analytical capabilities are capturing specification-grade business that commodity traders cannot service.
Direct contracting between food manufacturers and fermentation specialists is displacing traditional flavor house intermediaries. Large dairy processors in Germany and bakery conglomerates in France are establishing captive supply relationships with acetoin producers, unbundling flavor compounding from precursor procurement. This pattern is most visible in clean-label private label programs where ingredient transparency requirements exceed standard commercial specifications.
Acetoin Natural Market Segmentation
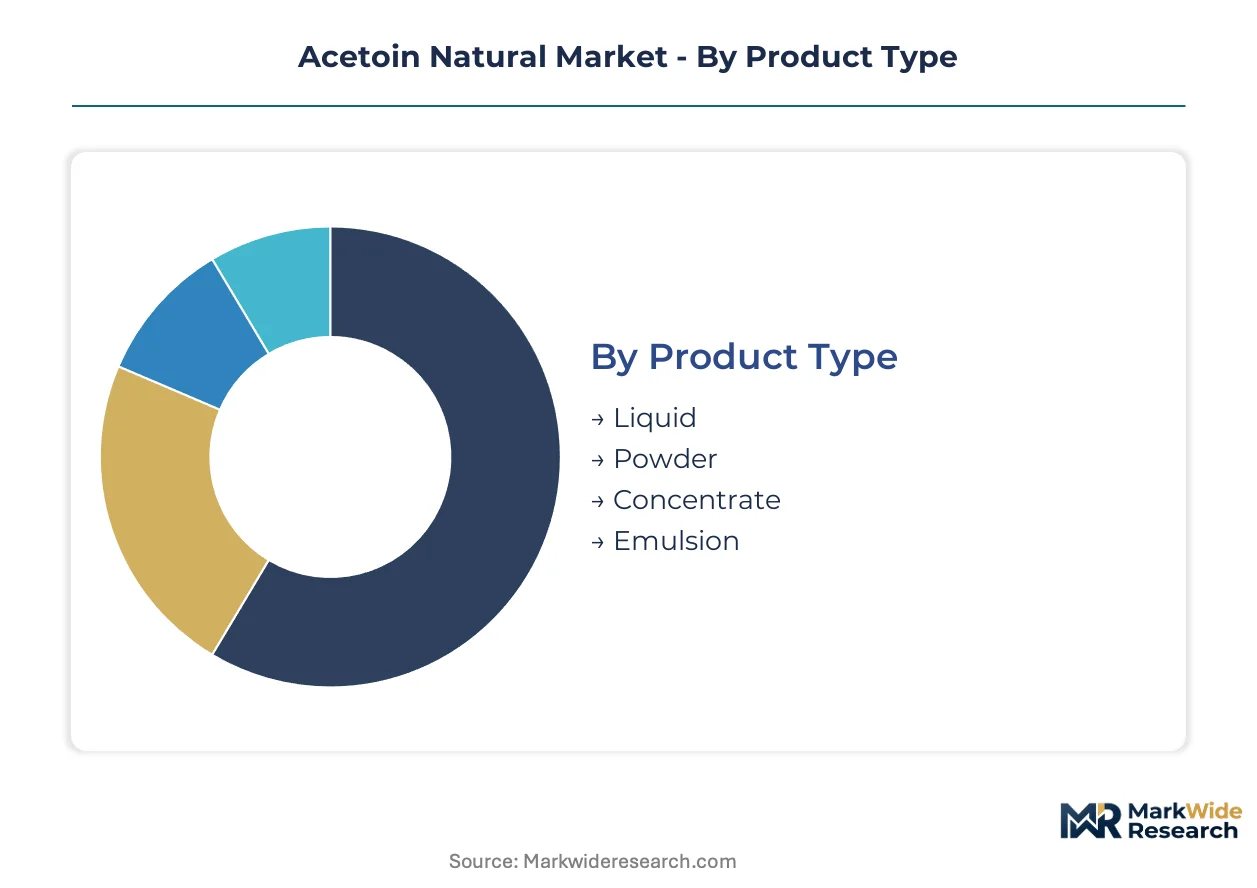
Segmentation in the acetoin natural market reveals how formulation requirements, regulatory documentation burdens, and supply chain temperature sensitivity split demand across distinct procurement channels. Understanding these divides clarifies why liquid grades dominate continuous processing while powder formats capture premium positioning in dry-mix applications.
Product Type:
Standardization dominates at the commodity end of this spectrum, while powder and concentrate grades command customization premiums for specific incorporation challenges.
- Liquid:Standard 99% purity aqueous solutions flow through continuous dairy and beverage processing lines without reconstitution steps. German flavor houses around Düsseldorf and Cologne specify liquid acetoin for clean-label butter flavoring in private label spreads, where EFSA natural-origin documentation must accompany every batch.
- Powder:Spray-dried or encapsulated formats extend shelf stability for instant beverage premixes and baking applications. French bakery conglomerates source powder grades for croissant and pastry mixes exported to Middle Eastern retail chains demanding 18-month ambient stability.
- Concentrate:High-potency reduced-water formulations reduce freight costs for long-distance supply to Southeast Asian processed food exporters.
- Emulsion:Oil-in-water dispersions serve fat-based confectionery applications where homogeneous distribution through cocoa butter matrices is essential.
Most installed capacity flows through liquid fermentation output. Expansion is steepest in powder as dry-mix convenience formats gain shelf space in European and Gulf retail.
Application:
Food-contact volumes anchor production economics, while cosmetics and pharmaceutical specifications pull capacity toward higher-margin certification tiers.
- Food & Beverage:Dairy analogs, confectionery, and savory formulations consume the majority of fermentation-derived acetoin output. Clean-label mandates from EU REACH and EFSA are disqualifying synthetic alternatives from natural-labeled products across German and French retail chains.
- Cosmetics:Fragrance fixatives and skincare emollients represent the steepest expansion trajectory as clean-beauty brands reformulate away from petroleum-derived stabilizers. US-based prestige perfume houses now require carbon-14 isotope documentation to verify biobased origin.
- Pharmaceuticals:Encapsulated coatings for oral dosage forms demand USP-grade specifications with batch-level traceability that only a handful of fermentation specialists can satisfy.
- Flavoring:Standalone flavor precursor sales to independent compounders serve smaller regional dairy processors without captive biotech relationships.
Food and beverage applications absorb the majority of current fermentation output. Cosmetics specifications are climbing fastest as fragrance houses bid capacity away from commodity food grades.
End User:
Direct manufacturer relationships are displacing traditional distributor intermediaries as large processors seek unbundled precursor procurement with full documentation chains.
- Manufacturers:Dairy processors, bakery conglomerates, and flavor houses source acetoin directly from fermentation specialists to satisfy clean-label private label programs. Captive supply relationships are concentrating around Rhine-Ruhr biotech clusters and Shandong export corridors.
- Distributors:Regional compounders and ingredient traders serve mid-sized formulators lacking volume to justify direct fermentation contracts. REACH registration burdens favor established European distributors with dedicated regulatory affairs functions.
- Retailers:Private label specification teams at major European grocery chains increasingly dictate acetoin sourcing requirements to their contract manufacturers.
- Consumers:Negligible direct volume; artisan food producers and experimental cosmetics formulators purchase through specialty channels.
Manufacturer direct procurement is gaining share fastest. Distributor intermediaries retain relevance only where regulatory documentation capabilities exceed buyer in-house resources.
Distribution Channel:
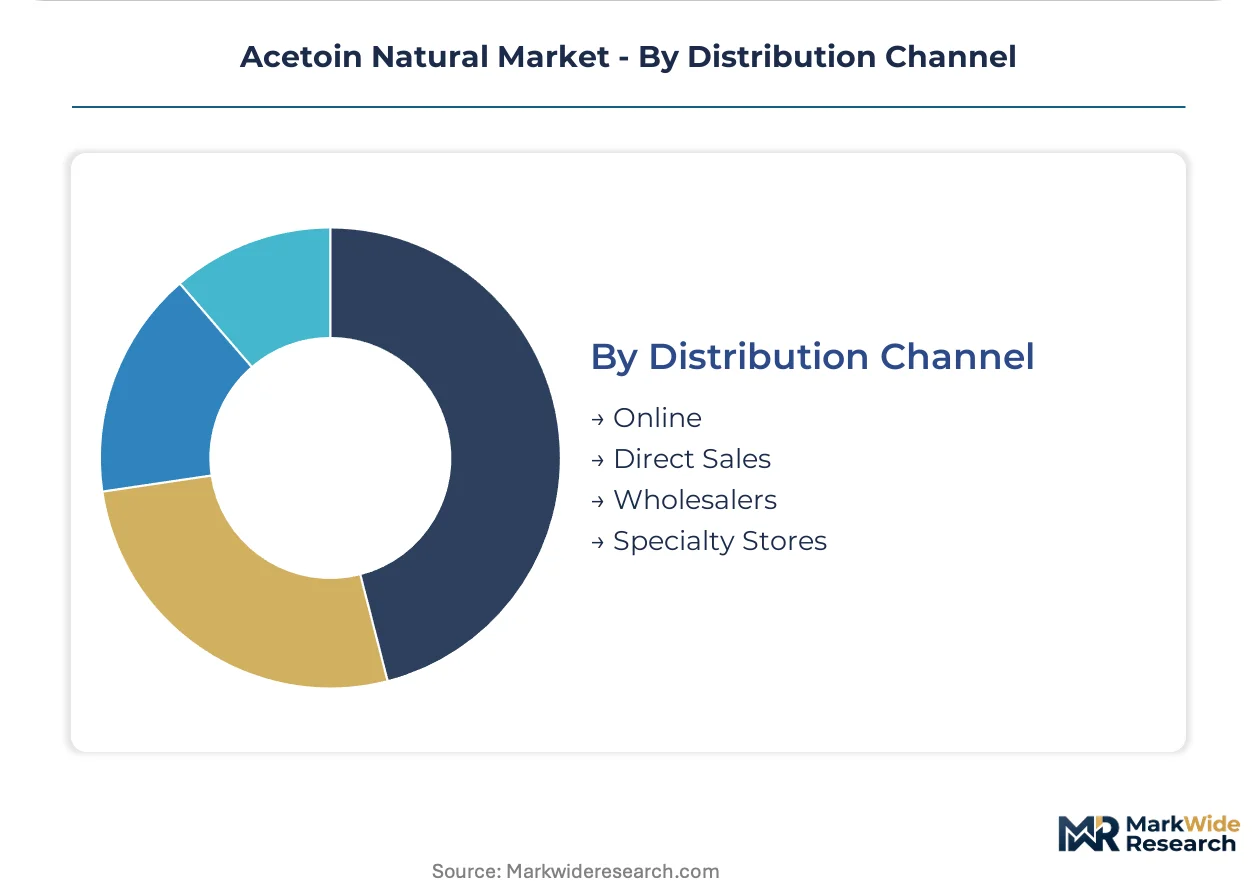
Channel selection tracks customer scale and documentation intensity, with direct sales capturing specification-grade business and online channels serving fragmented artisan demand.
- Direct Sales:Fermentation specialists maintain technical sales teams for large dairy and cosmetics manufacturers requiring batch-level carbon-14 certificates and EFSA compliance dossiers. German and Dutch compounders dominate this channel through in-house analytical capabilities.
- Wholesalers:Regional ingredient distributors aggregate demand from mid-sized European flavor houses and bakery cooperatives. Inventory pooling reduces minimum order quantities for processors below 50,000-liter annual offtake.
- Online:E-commerce platforms serve artisan food producers, experimental cosmetics formulators, and research institutions with sub-tonne quantity requirements. Documentation quality varies widely across sellers.
- Specialty Stores:Physical ingredient supply outlets in industrial zones around Düsseldorf and Cologne cater to local small-batch processors with immediate pickup needs.
Direct sales channels carry the majority of volume value. Online channels are expanding most quickly as distributed bioreactor systems enable smaller fermentation specialists to reach fragmented end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands tighter EFSA compliance documentation than China, where Shandong fermentation clusters compete on export scale for Southeast Asian processed food manufacturers seeking EU natural-label certification.
Germany
Clean-label dairy spreads and confectionery reformulations drive acetoin procurement from Rhine-Ruhr biotech corridors. REACH registration requirements under ECHA enforcement favor established compounders with dedicated regulatory affairs functions. Düsseldorf and Cologne host flavor houses clustering around captive fermentation supply ecosystems.
United States
Beverage manufacturers and clean-beauty fragrance houses source natural acetoin through FDA GRAS self-determination pathways. USDA BioPreferred Program procurement preferences anchor institutional demand in school nutrition and military ration programs. New Jersey flavor ingredient hubs sustain North American supply lines for liquid-grade continuous processing.
China
Shandong Peninsula fermentation facilities scale capacity to serve Asian processed food exporters requiring EU-compliant natural flavor documentation. SAMR food additive standards and dual carbon policy targets redirect capital toward biobased chemical platforms. Qingdao and Yantai bioreactor clusters compete on export volume for Middle Eastern and Southeast Asian dairy analog manufacturers.
France
Bakery conglomerates reformulate croissant and pastry premixes for Gulf retail chains demanding 18-month ambient stability in powder-grade acetoin. ANSM cosmetic ingredient oversight pushes fragrance houses toward carbon-14 isotope verification for biobased origin claims. Paris-region flavor compounders establish direct contracting relationships bypassing traditional distributor intermediaries.
Netherlands
Rotterdam chemical trading infrastructure and Eindhoven biotech research clusters support REACH-registered compounders serving mid-sized European flavor houses. Dutch distributors aggregate demand from bakery cooperatives below 50,000-liter annual offtake thresholds. Randstad regulatory consultants specialize in EFSA flavoring substance evaluation dossiers for natural-origin certification.
Acetoin Natural Market Competitive Environment
Rhine-Ruhr producers anchor the premium documentation tier; Shandong specialists hold scale-driven export positions. Market structure bifurcates between established European compounders with in-house analytical capabilities and emerging Asian fermentation operators competing on capacity expansion. Three archetypes dominate: regulatory-heavy documentation specialists, backward-integrated botanical sourcers, and modular bioreactor deployers. Competitive moves center on direct manufacturer contracting displacing flavor house intermediaries and REACH registration investments excluding commodity traders.
Within the documentation-specialist tier, Axxence Aromatic GmbH and Vigon International exemplify divergent geographic anchoring strategies. Qingdao CEPA Energy Technology Co., Ltd. occupies a position representing Shandong-scale fermentation export capacity. These three names illustrate how competitive positioning splits between EFSA-compliance depth and production volume scalability.
| Leading Market Players |
|---|
| The Good Scents Company |
| UBM EMEA |
| Vigon International |
| Axxence Aromatic GmbH |
| Qingdao CEPA Energy Technology Co., Ltd. |
| Sunaux |
| RPX Corporation |
| Penta Manufacturing Company |
| Charkit Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists in Germany's Rhine-Ruhr corridor maintain disciplined pricing through captive relationships with flavor houses, while sovereign-backed Chinese producers in Shandong compete on scale for export contracts. This ownership split creates divergent pricing behaviors: European compounders capture premium documentation tiers while Asian operators compress margins for volume throughput.
Pricing Analysis
Capacity additions in Shandong are reshaping price floors for standard-grade liquid acetoin as Qingdao CEPA Energy Technology Co., Ltd. and regional competitors expand bioreactor footprints. Three-tier pricing structure across premium documentation, standard food-grade, and economy industrial tiers separates EFSA-certified batches from commodity exports. Price differentiation hinges on carbon-14 isotope verification and REACH registration completeness. Cost compression in the standard tier is intensifying because glucose feedstock volatility and single-source bioreactor dependency squeeze fermentation economics. Small bakery cooperatives and mid-sized flavor houses exhibit highest price sensitivity, while prestige cosmetics brands purchasing USP-grade powder show minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Düsseldorf, and Qingdao anchor hub-and-spoke patterns for temperature-sensitive liquid grades. Supply concentrates in Germany, China, and the United States, with Rhine-Ruhr biotech corridors and Shandong Peninsula fermentation clusters commanding distinct tier positions. Raw material flows draw from corn and wheat-derived glucose, pyruvate feedstocks, and botanical precursors for backward-integrated producers. Single-source bioreactor dependency creates vulnerability to batch contamination or facility downtime. Distribution runs through direct sales channels for large manufacturers and wholesaler aggregators for mid-sized processors below 50,000-liter annual offtake thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetoin natural markets present margin-expansion potential through fermentation yield improvements and premium-tier shifts toward cosmetics-grade specifications with carbon-14 documentation requirements.
For Market Incumbents: Cement EFSA compliance depth through in-house analytical capabilities for carbon-14 isotope testing, insulating specification-grade business from commodity traders. Acquire modular bioreactor specialists to deploy distributed 5,000-20,000 liter units at customer-adjacent sites, compressing transport costs for temperature-sensitive liquid grades. Defend against Shandong-scale competitors by embedding technical sales teams within large dairy and cosmetics manufacturers requiring batch-level documentation chains. For New Entrants and Emerging Players: Begin with encapsulated dry-mix powder formats for instant beverage and baking premix applications, where 18-month ambient stability requirements command margin premiums over liquid grades. Target French bakery conglomerates exporting croissant and pastry mixes to Gulf retail chains seeking EU-compliant natural flavor documentation. Pursue USDA BioPreferred Program certification to anchor institutional demand in school nutrition and military ration programs as a go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European compounders lacking Shandong-scale fermentation capacity but possessing REACH registration infrastructure and EFSA dossier expertise. Long-term viability across the analysis window favors acquisition targets with backward integration into botanical sourcing and captive relationships with clean-label private label programs. Monitor ECHA substance evaluation protocol expansions as the signal to watch for documentation-tier margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Axxence Aromatic GmbH secures captive supply chains for high-purity natural aroma chemicals. |
| Modular Bioreactor Deployment | Regional dairy cooperatives cut transport costs through customer-adjacent 5,000-20,000 liter production units. |
| REACH Registration Investment | German and Dutch compounders exclude commodity traders through ECHA-compliant documentation capabilities. |
| Direct Manufacturer Contracting | Large French bakery conglomerates bypass flavor house intermediaries for unbundled precursor procurement. |
| Carbon-14 Isotope Certification | US prestige perfume houses verify biobased origin claims for clean-beauty fragrance fixative formulations. |
Study Parameters
Coverage spans Germany, the United States, China, France, and the Netherlands, with primary inputs from each market through interviews with fermentation plant managers, procurement leads at dairy and cosmetics manufacturers, distribution channel partners, and regulatory affairs directors at flavor houses. Secondary validation draws from EFSA flavoring substance evaluation databases, REACH registration filings under ECHA, FDA GRAS self-determination notices, and customs trade data for acetoin import flows. Bottom-up volume estimates from bioreactor capacity installations triangulate against top-down demand projections from end-use industry consumption patterns.
Granularity-level modeling tracks liquid, powder, concentrate, and emulsion product types; food and beverage, cosmetics, pharmaceutical, and flavoring applications; and manufacturer, distributor, retailer, and consumer end-user channels. CAGRs derive from segment-level growth rate assumptions applied across the projection horizon, with cross-segment reconciliation ensuring internal consistency. Industry-specific forecast inputs include glucose feedstock price indices, EFSA natural-origin certification approval timelines, and clean-label private label program adoption curves at major European grocery chains.
Several conditions sit outside the modeled scope, including sudden EFSA reclassification of acetoin's natural-origin status, catastrophic bioreactor contamination events at major production facilities, and biofuel policy shifts altering agricultural glucose availability. Forecasts reflect assumptions about regulatory stability, fermentation yield improvements, and documentation standard convergence across geographies. Stakeholders should weight assumptions against their own operating context, particularly regarding REACH registration burden capacity and captive supply relationship durability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market