
 Soil Inoculants Market | 2026-2036
Soil Inoculants Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Inoculants Market Analytics
Aftermarket technical advisory revenue is fragmenting from traditional agrochemical distributors toward specialized biological input consultants. BASF SE leverages its microbial strain library to anchor premium positioning in rhizobial inoculants across Latin American soybean belts. Novozymes A/S sustains leadership through continuous fermentation process optimization that lowers production costs for liquid formulations. Lallemand Inc. specializes in yeast and bacterial consortia for specialty crop segments where growers pay for documented yield improvement.
Soil inoculants comprise live microbial preparations containing defined strains of bacteria, fungi, or mycorrhizae formulated for field application at concentrations typically exceeding 10^8 colony-forming units per gram; these organisms colonize plant root zones to enhance nutrient solubilization, biological nitrogen fixation, or pathogen suppression. Bacterial inoculants dominate commercial volume due to established efficacy in legume symbiosis and lower manufacturing complexity relative to mycorrhizal products requiring host-plant propagation. Mycorrhizal inoculants command premium pricing in horticultural crops and turf applications where phosphorus use efficiency regulations tighten. Liquid formulations lead distribution through direct sales channels serving large-scale agronomic operations, while powder and granular formats retain importance in emerging markets with limited cold-chain infrastructure.
EPA biopesticide registration requirements under FIFRA shape product development timelines and label claims for microbial inoculants entering the US market, while EU REACH and Fertilizing Products Regulation frameworks govern strain safety assessments and market access across European member states. Brazil's national biosafety commission, CTNBio, evaluates transgenic and novel microbial strains for environmental release, creating a distinct regulatory pathway that influences R&D investment priorities for suppliers targeting South American expansion. Stakeholders must monitor evolving strain patent landscapes and biocontrol claim substantiation standards as biological input categories converge with conventional crop protection regulatory architectures.
Market Dynamics
EPA runoff limits on synthetic nitrogen are compressing fertilizer application windows across the US Corn Belt, forcing growers toward biological nitrogen fixation as a compliance pathway rather than a yield supplement.
Growth Catalysts
- EPA Nitrogen Runoff Limits:Tightening discharge thresholds under the Clean Water Act are mandating synthetic fertilizer reduction in Midwestern row crop operations, expanding inoculant adoption as a compliance mechanism.
- Brazilian Import Substitution:Bradyrhizobium inoculant demand accelerates in the Cerrado as currency volatility and supply chain risk drive farmers to reduce fertilizer import dependency through biological fixation.
- No-Till System Expansion:Reduced soil disturbance practices preserve microbial colony integrity, improving inoculant survival rates and field efficacy in South American soybean belts.
Market Restraints
- Cold-Chain Infrastructure Gaps:Liquid formulation viability depends on uninterrupted refrigeration from fermentation facility to field, constraining distribution in emerging markets with unreliable electricity networks.
- Strain Patent Concentration:Premium rhizobial strain intellectual property concentrates among three multinational suppliers, limiting new entrant access to high-efficacy germplasm.
- Synthetic Fertilizer Price Volatility:Urea and diammonium phosphate price collapses during demand shocks temporarily erode the economic case for biological alternatives in price-sensitive procurement cycles.
Strategic Opportunities
- EU Fertilizing Products Regulation:The unified EU-wide strain registration pathway reduces market entry fragmentation, creating first-mover advantage for suppliers achieving CE-marked microbial fertilizer status.
- Specialty Crop Premium Segments:Horticultural producers in protected agriculture systems demonstrate willingness to pay documented yield improvement premiums for mycorrhizal consortia in high-value vegetable production.
- Direct-to-Farm Digital Channels:E-commerce platforms and agronomic advisory apps are disintermediating traditional distributor networks, enabling specialized biological input consultants to capture technical advisory revenue.
Industry Challenges
- CTNBio Strain Approval Timelines:Brazil's national biosafety commission evaluation periods for novel microbial strains extend 18-24 months, compressing product launch windows relative to competitor jurisdictions.
- Biocontrol Claim Substantiation:Convergence between biological input and crop protection regulatory architectures demands expanded field trial investment to support pathogen suppression label claims under evolving EPA biopesticide standards.
- Fermentation Scale-Up Expertise:Liquid formulation manufacturing requires specialized bioprocess engineering talent scarce outside pharmaceutical and enzyme production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Inoculants Market |
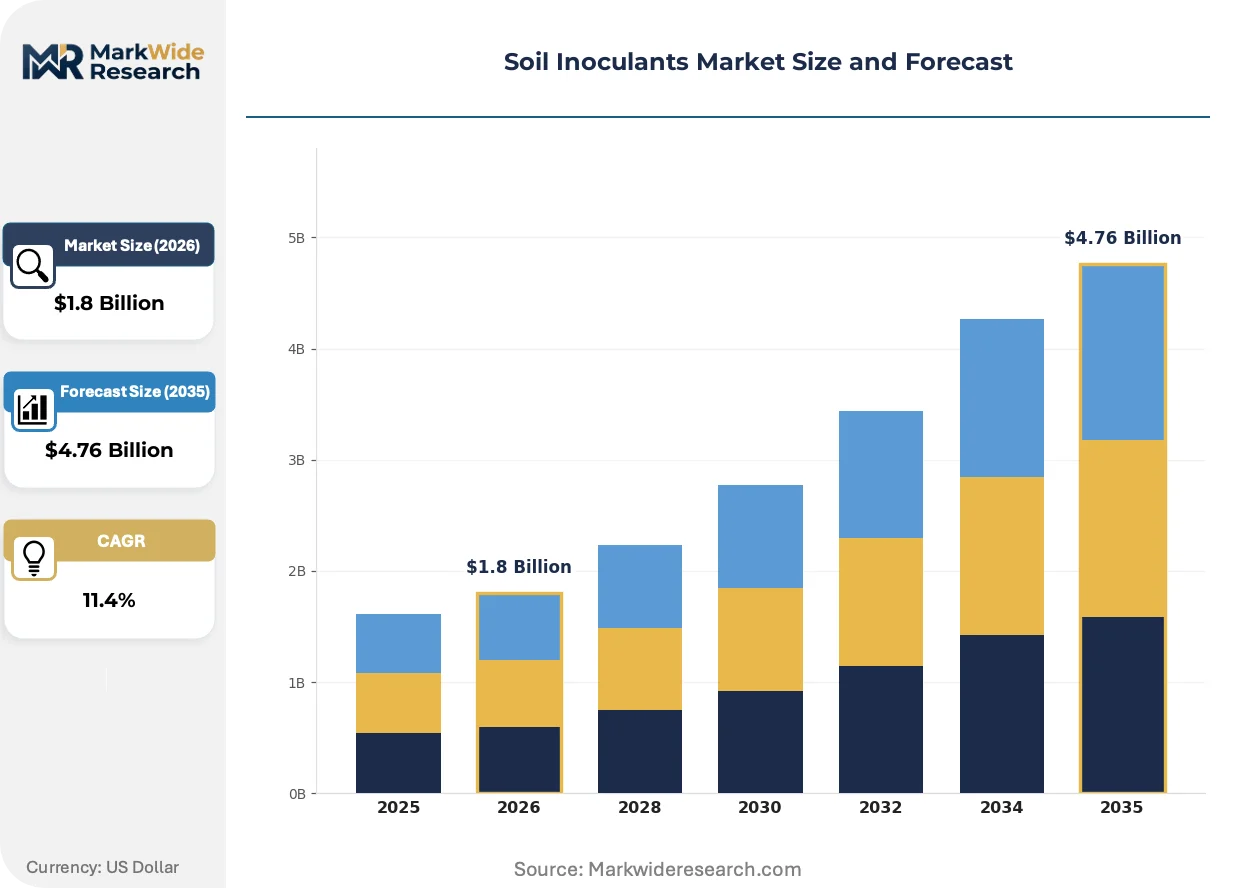
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Inoculants, Mycorrhizal Inoculants, Fungal Inoculants, Composts Application: Agronomic Crops, Horticultural Crops, Turf & Ornamental, Forestry Formulation: Liquid, Powder, Granular, Pelleted Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | BASF SE, Bayer AG, Novozymes A/S, Corteva Agriscience, Syngenta Group Co., Ltd., Verdesian Life Sciences, UPL Limited, Rizobacter Argentina S.A., Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Inoculants Market Evolving Landscape
Formulation chemistry and delivery mechanism advances are eroding the historical performance gap between biological and synthetic nutrient inputs in broadacre agriculture.
Microbial consortia engineering is hybridizing previously discrete functional categories. Multi-strain preparations now combine nitrogen-fixing bacteria with phosphorus-solubilizing fungi and biocontrol agents in single-application products. Large-scale agronomic operations in the US Corn Belt are piloting these integrated formulations at scale. This convergence is hybridizing supplier R&D roadmaps and compressing the addressable market for single-function inoculants.
REACH and the EU Fertilizing Products Regulation are harmonizing strain safety assessment protocols across European member states. Industrial consequence includes reduced duplication of toxicological studies for multi-market entry. Specialty crop segments in the Netherlands and Spain are responding fastest, leveraging streamlined registration to introduce mycorrhizal products ahead of broadacre adoption curves.
Technical advisory services are unbundling from product distribution. Growers increasingly purchase inoculants through direct channels while sourcing application guidance from independent biological input consultants. This bifurcation disrupts traditional agrochemical distributor margin structures. The pattern is most visible in Brazil's Mato Grosso soybean belt, where digital agronomy platforms now intermediate between manufacturers and farm-level decision-makers.
Soil Inoculants Market Segmentation
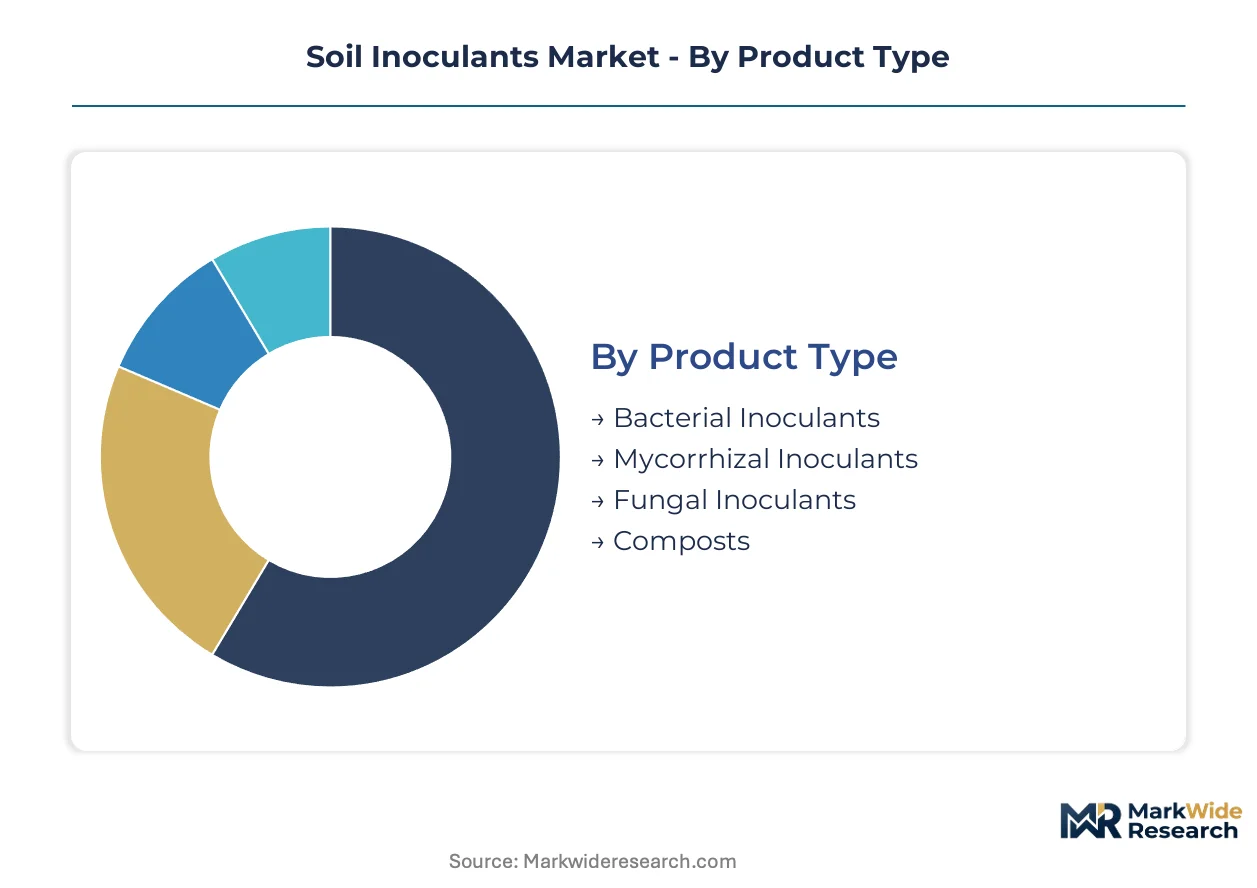
Soil inoculant suppliers navigate distinct technical and commercial requirements across microbial categories, crop systems, and delivery formats. Segmentation reveals where formulation chemistry investments concentrate and which distribution channels are disintermediating traditional supply chains.
Product Type:
Mature bacterial platforms dominate commercial volume while emerging mycorrhizal technologies capture premium positioning in high-value crop segments.
- Bacterial Inoculants:Live preparations of defined rhizobial or plant growth-promoting bacterial strains formulated at concentrations exceeding 10^8 CFU per gram. Demand concentrates in Brazil's Cerrado soybean belt where Bradyrhizobium inoculants displace synthetic nitrogen imports amid currency volatility.
- Mycorrhizal Inoculants:Arbuscular or ectomycorrhizal fungal propagules requiring host-plant propagation during manufacturing, commanding price premiums in horticultural phosphorus efficiency applications. The Netherlands and Spain lead adoption curves as EU Fertilizing Products Regulation streamlines strain registration.
- Fungal Inoculants:Trichoderma and other biocontrol fungal preparations suppressing soil-borne pathogens through competitive colonization.
- Composts:Microbially active organic amendments combining diverse bacterial and fungal consortia with carbon substrates.
Bacterial inoculants retain volume leadership; mycorrhizal inoculants hold the steepest expansion curve.
Application:
Cost tier stratification separates broadacre commodity systems from protected agriculture operations willing to document yield improvement premiums.
- Agronomic Crops:Row crop applications across corn, soybean, and wheat systems where biological nitrogen fixation serves EPA compliance pathways in the US Corn Belt. US Midwestern growers face tightening Clean Water Act discharge thresholds.
- Horticultural Crops:High-value vegetable and fruit production in controlled environment agriculture, with mycorrhizal consortia demonstrating phosphorus use efficiency gains. Spanish greenhouse operators and Dutch glasshouse producers adopt fastest under harmonized EU registration.
- Turf & Ornamental:Golf course and landscape applications with seasonal application windows and aesthetic performance metrics.
- Forestry:Reforestation and plantation establishment programs requiring ectomycorrhizal symbiosis for seedling survival.
Agronomic crops retain volume leadership; horticultural crops gain share fastest through premium pricing acceptance.
Formulation:
Supply concentration in liquid manufacturing reflects fermentation scale-up expertise scarcity outside pharmaceutical production clusters.
- Liquid:Aqueous suspensions of viable microbial cells requiring uninterrupted cold-chain from fermentation facility to field. Direct sales channels serving large-scale Brazilian and US operations favor liquid for precision application compatibility.
- Powder:Lyophilized or desiccated preparations with extended ambient temperature stability, retaining importance in Indian and African markets with unreliable electricity networks.
- Granular:Clay or peat-based carriers enabling mechanical spreading equipment compatibility in broadacre systems.
- Pelleted:Compressed formulations with seed-coating adhesion properties for precision placement at planting.
Liquid formulations retain volume leadership; powder formats climb fastest in emerging market expansion.
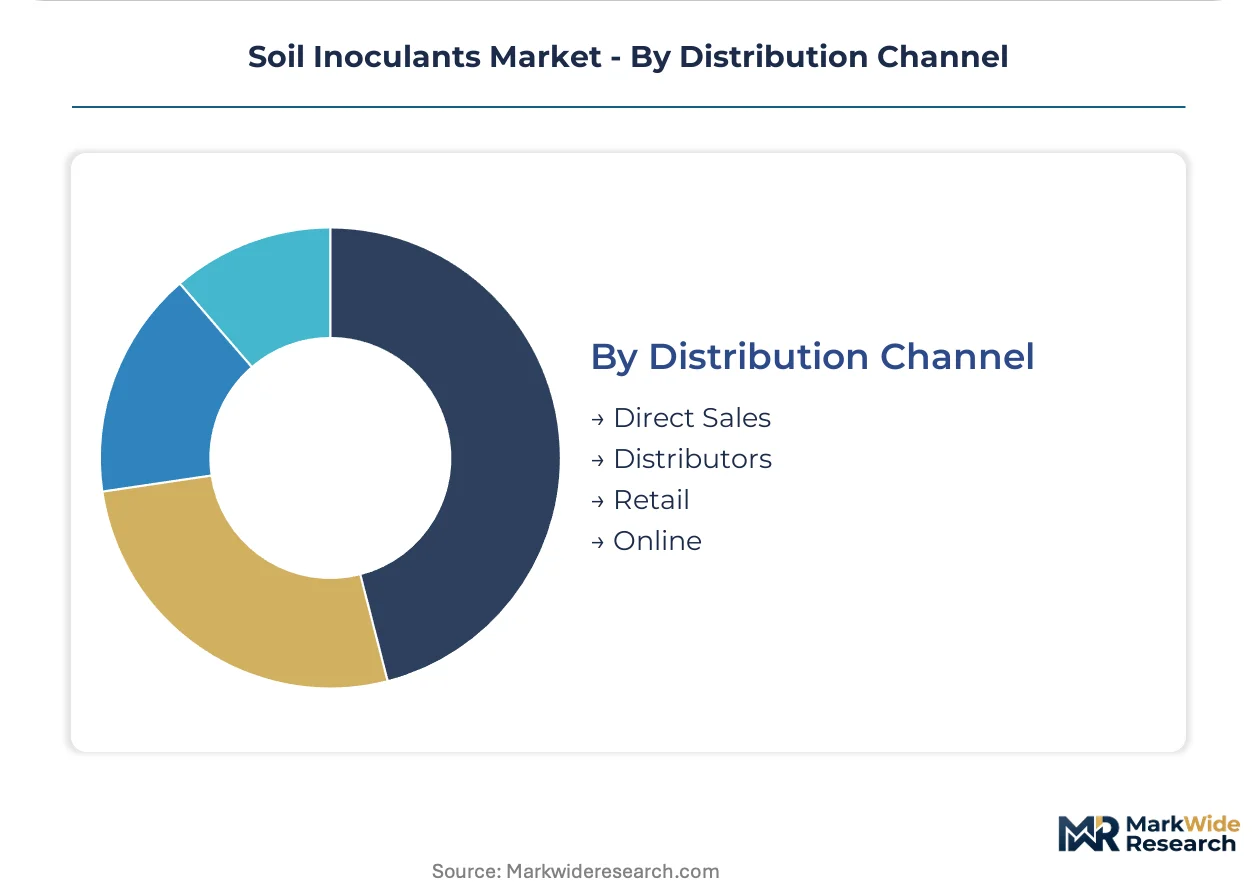
Distribution Channel:
Customer type bifurcation separates procurement behavior of large-scale agronomic operators from specialty crop growers sourcing technical advice independently.
- Direct Sales:Manufacturer-to-farm relationships capturing technical advisory revenue previously retained by agrochemical distributors. Brazil's Mato Grosso soybean belt demonstrates this pattern most visibly.
- Distributors:Traditional agricultural supply cooperatives and input retailers with storage infrastructure and credit relationships.
- Retail:Garden center and farm supply outlets serving hobbyist and small-scale producers.
- Online:E-commerce platforms and agronomic advisory apps disintermediating established networks, enabling specialized biological input consultants to capture advisory margins.
Direct sales retain volume leadership; online channels expand most quickly through digital agronomy platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Brazilian growers deploy inoculants as primary nitrogen sources, while US operators treat them as compliance tools. European horticulturalists pay premiums for phosphorus efficiency, and Indian farmers prioritize shelf-stable formats over live-cell viability.
United States
EPA Clean Water Act discharge thresholds compress synthetic fertilizer application windows across Iowa and Illinois corn operations. The agency's biopesticide registration pathway under FIFRA shapes product development timelines for microbial strains entering commercial distribution. Midwestern agronomic clusters around Des Moines and Peoria pilot multi-strain consortia combining nitrogen fixation with biocontrol functions.
Brazil
Currency volatility and import dependency drive Bradyrhizobium adoption across Mato Grosso and Goiás soybean belts. CTNBio strain approval timelines extend 18-24 months, compressing launch windows for novel microbial preparations. The Cerrado region concentrates demand growth where no-till systems preserve inoculant viability from planting through canopy closure.
Netherlands
EU Fertilizing Products Regulation harmonization enables rapid mycorrhizal product introduction in greenhouse vegetable production. REACH-aligned safety assessments reduce toxicological study duplication across member state markets. Wageningen-area research clusters accelerate phosphorus efficiency trials in tomato and pepper protected agriculture systems.
India
Powder and granular formats dominate procurement in Maharashtra and Gujarat due to cold-chain infrastructure gaps. FSSAI and BIS standards govern microbial fertilizer quality parameters for domestic manufacturing and import. Punjab's wheat-rice rotation systems show rising rhizobial inoculant penetration as urea subsidy rationalization proceeds.
Germany
ECHA registration requirements and EU Green Deal nutrient efficiency targets accelerate biological input R&D investment. Bavarian and North Rhine-Westphalian specialty crop operations adopt mycorrhizal consortia for asparagus and strawberry production. Industrial biotechnology clusters around Munich and Cologne supply fermentation expertise for liquid formulation scale-up.
Soil Inoculants Market Competitive Landscape
Capability concentration sits with microbial strain libraries and fermentation process specialists; scale advantage sits with agrochemical incumbents leveraging distribution infrastructure. The market structures around three archetypes: multinational life science conglomerates with integrated biological portfolios, specialized microbial technology firms with deep strain development expertise, and regional agricultural input suppliers with localized formulation capabilities. Competitive moves center on strategic partnerships bridging strain access with market reach, and backward integration into captive fermentation capacity to secure supply continuity.
Within the multinational tier, BASF SE and Bayer AG exemplify integrated life science positioning spanning crop protection, seeds, and biological inputs. Novozymes A/S occupies a distinct tier as a fermentation technology specialist with process optimization capabilities transferable to agricultural microbial production. These three anchors demonstrate how competitive positioning stratifies between breadth-driven conglomerates and depth-focused technology platforms.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Novozymes A/S |
| Corteva Agriscience |
| Syngenta Group Co., Ltd. |
| Verdesian Life Sciences |
| UPL Limited |
| Rizobacter Argentina S.A. |
| Lallemand Inc. |
| Others |
Value Network & Pricing Analysis
The Port of Santos cold-chain corridor from Brazilian fermentation facilities to Mato Grosso soybean operations concentrates supply-side leverage among three multinational suppliers, translating logistics reliability premiums into price differentiation across liquid formulation tiers while powder alternatives absorb margin compression in electricity-constrained Indian distribution networks.
Pricing Analysis
Long-term offtake contracts dominate Brazilian Bradyrhizobium procurement, locking in volume commitments across multi-season windows that insulate manufacturers from urea price volatility while spot purchases in Indian Maharashtra markets expose buyers to seasonal availability squeezes. Price differentiation rests on strain efficacy certification tiers and cold-chain guarantee levels, with CTNBio-registered premium strains commanding substantial markups over generic alternatives. Pricing pressure stems from synthetic fertilizer price collapses during demand shocks that temporarily erode biological nitrogen fixation economics. Large-scale agronomic operators in the US Corn Belt demonstrate lowest price sensitivity due to EPA compliance pathway requirements, while smallholder wheat-rice rotations in Punjab exhibit highest elasticity to urea subsidy adjustments.
Supply Chain Analysis
Export-control regimes on microbial strain intellectual property limit germplasm flows from German and Danish fermentation technology clusters to emerging market formulation facilities, constraining new entrant access to high-efficacy rhizobial platforms. Manufacturing concentrates in Brazil, the United States, and Germany where specialized bioprocess engineering talent anchors liquid formulation scale-up. Raw material dependencies include molasses feedstocks for fermentation, lyophilization excipients for powder stability, and peat carriers for granular mechanical spreading compatibility. Single-source vulnerability concentrates in cold-chain logistics providers serving Latin American soybean belts. Distribution runs through direct manufacturer-to-farm channels capturing technical advisory revenue, though traditional agricultural cooperatives retain credit-relationship advantages in Midwestern US corn operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil inoculant market fragmentation accelerates as digital agronomy platforms disintermediate traditional distributor networks, creating specialized niches for biological input consultants and regional formulation specialists to capture technical advisory margins previously retained by agrochemical incumbents.
For Market Incumbents: Pre-empt digital platform encroachment by acquiring specialized biological input consultants in Brazil's Mato Grosso and US Corn Belt corridors, securing channel control over technical advisory relationships. Anchor backward integration into captive fermentation capacity in German industrial biotechnology clusters to reduce dependency on external bioprocess engineering talent. Patent cliff pressure on premium rhizobial strains demands accelerated R&D investment in multi-strain consortia combining nitrogen fixation with biocontrol functions.
For New Entrants and Emerging Players: India's powder and granular format penetration offers the most accessible white-space target, leveraging ambient-temperature stability advantages to bypass cold-chain infrastructure gaps constraining multinational liquid formulations. Specialty crop mycorrhizal applications in Dutch and Spanish protected agriculture systems demonstrate willingness to pay documented yield improvement premiums, creating premium positioning opportunities outside commodity soybean markets. Digital-first go-to-market strategies through agronomic advisory apps enable direct farm relationships without distributor network investment.
For Investors and Strategic Acquirers: Fermentation technology specialists with process optimization capabilities represent the priority acquisition archetype, capturing transferable expertise from pharmaceutical and enzyme production clusters into agricultural microbial manufacturing. Long-term viability hinges on regulatory arbitrage positioning across EU Fertilizing Products Regulation harmonization and CTNBio approval pathway differentials. The signal to watch is CTNBio strain approval timeline compression or expansion, which would accelerate or delay Brazilian market entry windows for novel microbial platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Strain Consortia Development | Hybrid nitrogen-fixing and biocontrol functions compress single-function inoculant addressable markets across US Corn Belt pilot programs. |
| Cold-Chain Infrastructure Partnership | Uninterrupted refrigeration networks from fermentation to field unlock liquid formulation viability in Brazilian Cerrado no-till systems. |
| CTNBio Fast-Track Registration | Accelerated Brazilian biosafety approval reduces 18-24 month launch windows relative to competitor jurisdictions. |
| Direct-to-Farm Digital Platform | E-commerce and agronomic advisory apps disintermediate traditional distributor margins in Mato Grosso soybean belts. |
| EU CE-Marked Microbial Fertilizer Status | First-mover advantage captures streamlined strain registration under harmonized Fertilizing Products Regulation across Netherlands and Spain. |
Research Methodology
The analysis maps bacterial, mycorrhizal, fungal inoculant and compost sub-sectors, each validated through fermentation process engineers, agricultural cooperative procurement leads, biological input consultants, and regulatory affairs specialists at strain registration bodies. Primary interviews with plant managers at Brazilian and German fermentation facilities, downstream OEM agronomists at large-scale soybean and corn operations, and distribution channel partners in Indian Maharashtra markets combined with secondary validation through EPA biopesticide registration filings, CTNBio approval databases, EU Fertilizing Products Regulation strain safety assessments, and SEC 10-K disclosures from listed life science conglomerates. Bottom-up strain-level production estimates and top-down agricultural input expenditure patterns underwent triangulation to resolve data gaps.
Assumptions held synthetic fertilizer price volatility within historical bands, EPA nitrogen runoff limit enforcement at current trajectory, and cold-chain infrastructure expansion in emerging markets at observed rates across the analysis window. Segmentation dimensions modeled include microbial category, crop application system, formulation chemistry, and distribution channel structure. CAGRs derived from logistic adoption curve fitting to biological nitrogen fixation penetration data in Brazilian soybean belts and US Corn Belt compliance-driven procurement. Industry-specific forecast inputs incorporated CTNBio approval timeline distributions and EU REACH toxicological study cost burdens.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized microbial technology firms with deep strain libraries would shift outcomes through accelerated multi-strain consortia introduction. Material shifts in EPA biopesticide registration stringency, CTNBio approval timeline compression, or synthetic fertilizer price collapse duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market