
 Global Activated Carbon Canisters Market | 2026-2036
Global Activated Carbon Canisters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Activated Carbon Canisters Market Intelligence
The specialized distribution channel for automotive aftermarket canisters is narrowing as large service chains consolidate purchasing power and source directly from manufacturers. This shift pressures smaller distributors and favors suppliers with scale. Robert Bosch GmbH leverages its vast original equipment service network to maintain its position. Meanwhile, Ingevity specializes in high-performance activated carbon materials, giving it an advantage in technical specifications required by automakers.
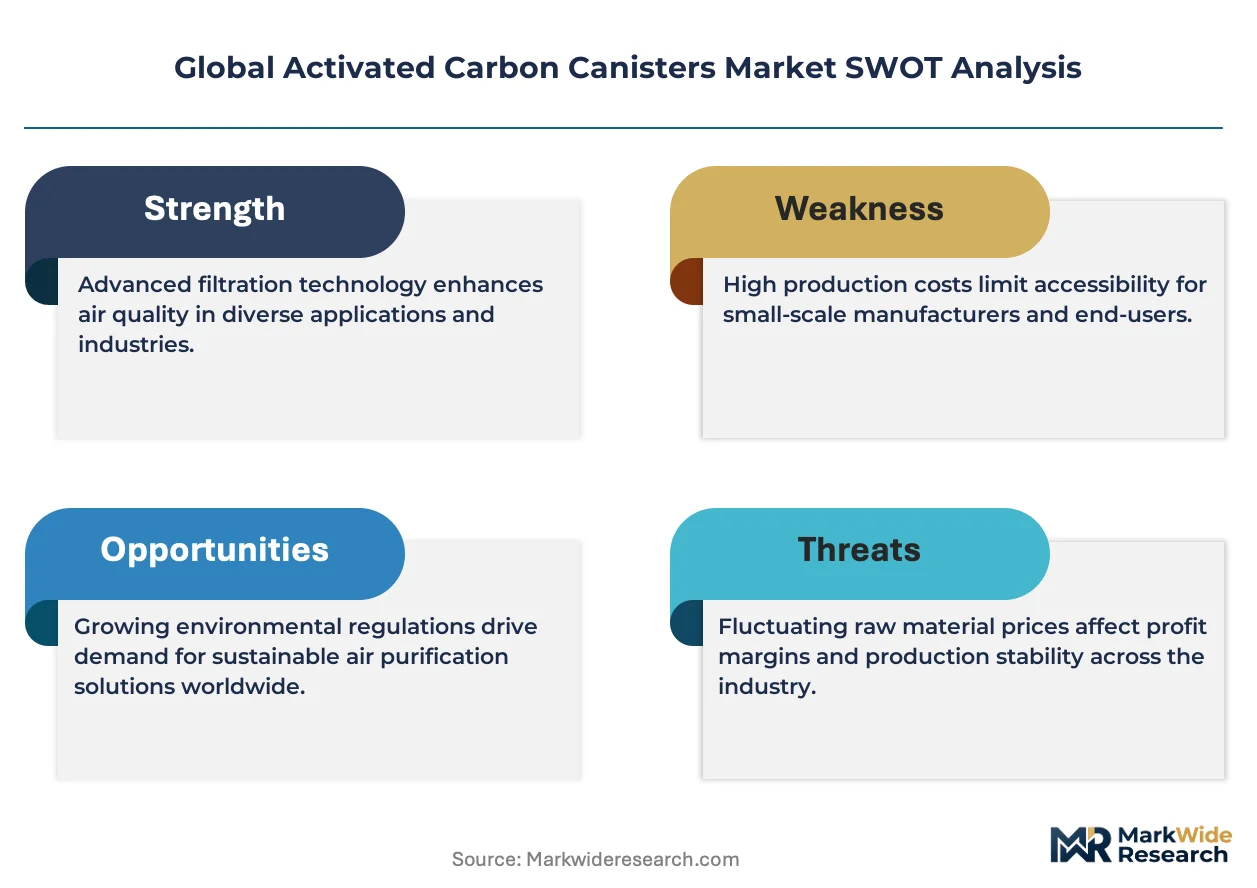
Activated carbon canisters are devices designed to adsorb and contain volatile organic compounds (VOCs) and other gaseous pollutants. They typically contain granular activated carbon (GAC) chosen for its high porosity and surface area, which enables the physical adsorption of vapor molecules. Their primary purpose is capturing fuel vapors in automotive evaporative emission control (EVAP) systems and purifying air streams in industrial settings. While air purification remains the dominant application, demand for water treatment and gas separation is expanding. Granular Activated Carbon and Pellets represent the most common product types.
Regulatory mandates are the primary force shaping product specifications and market access. In the United States, the EPA enforces strict evaporative emission standards under the Clean Air Act, which dictates canister capacity and durability. Similarly, the European Union’s REACH and Euro 7 emission standards impose stringent requirements on materials and performance for vehicles sold in the region. Manufacturers must therefore navigate a complex web of regional standards to ensure compliance and market viability.
Market Dynamics
The activated carbon canister market is fundamentally shaped by the escalating stringency of global environmental regulations. Mandates from bodies like the US EPA and the European Union's ECHA dictate performance specifications, forcing continuous product innovation and creating significant barriers to market entry for non-compliant producers.
Growth Catalysts
- Stringent Emission Standards:The implementation of regulations like the EU’s Euro 7 standards for vehicles and stricter industrial VOC limits in China compels the adoption of higher-performance canisters in automotive and manufacturing sectors.
- Industrialization in Asia:Rapid construction of new chemical processing plants and manufacturing facilities, particularly in India and China, creates sustained demand for activated carbon canisters for industrial air purification and solvent recovery.
- Application Diversification:Expanding use cases beyond automotive EVAP systems into areas such as municipal water treatment for taste and odor control and biogas purification are opening new revenue streams for manufacturers.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations of key raw materials, especially coconut shell charcoal, whose supply is concentrated in specific climate-dependent regions and subject to agricultural variables.
- Finite Adsorption Capacity:Activated carbon has a limited lifespan and requires periodic replacement or complex regeneration, which adds to the total cost of ownership and operational downtime for end-users in industrial settings.
- Threat from Alternative Technologies:In certain high-concentration industrial vapor recovery applications, alternative technologies such as cryogenic condensation and membrane separation systems present a viable substitution threat to activated carbon canisters.
Strategic Opportunities
- Emerging Energy Applications:Development of specialized canisters for the purification of biogas and the storage of hydrogen represents a significant opportunity, aligning with the global transition toward cleaner energy sources.
- Aftermarket Penetration in Developing Economies:Targeting the automotive aftermarket in Southeast Asian and Latin American countries with aging vehicle fleets offers a substantial growth vector as emissions regulations are gradually tightened in these regions.
- Advanced Material Development:Creating carbon composites or using novel impregnation agents to enhance the selective adsorption of specific pollutants like formaldehyde or benzene allows for product differentiation and access to premium-priced segments.
Industry Challenges
- Complex Global Compliance:Manufacturers face significant administrative and testing costs to secure and maintain certifications across multiple jurisdictions, such as simultaneously meeting US EPA durability requirements and European REACH material standards.
- Raw Material Sourcing Logistics:The supply chain for high-grade activated carbon precursors is geographically concentrated, exposing producers to logistical disruptions, quality inconsistencies, and geopolitical risks in sourcing regions.
- Diagnostic System Integration:Integrating advanced canisters with sophisticated onboard diagnostic (OBD) systems in modern vehicles requires deep collaboration with automotive electronics suppliers to ensure flawless error detection and reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Activated Carbon Canisters Market |
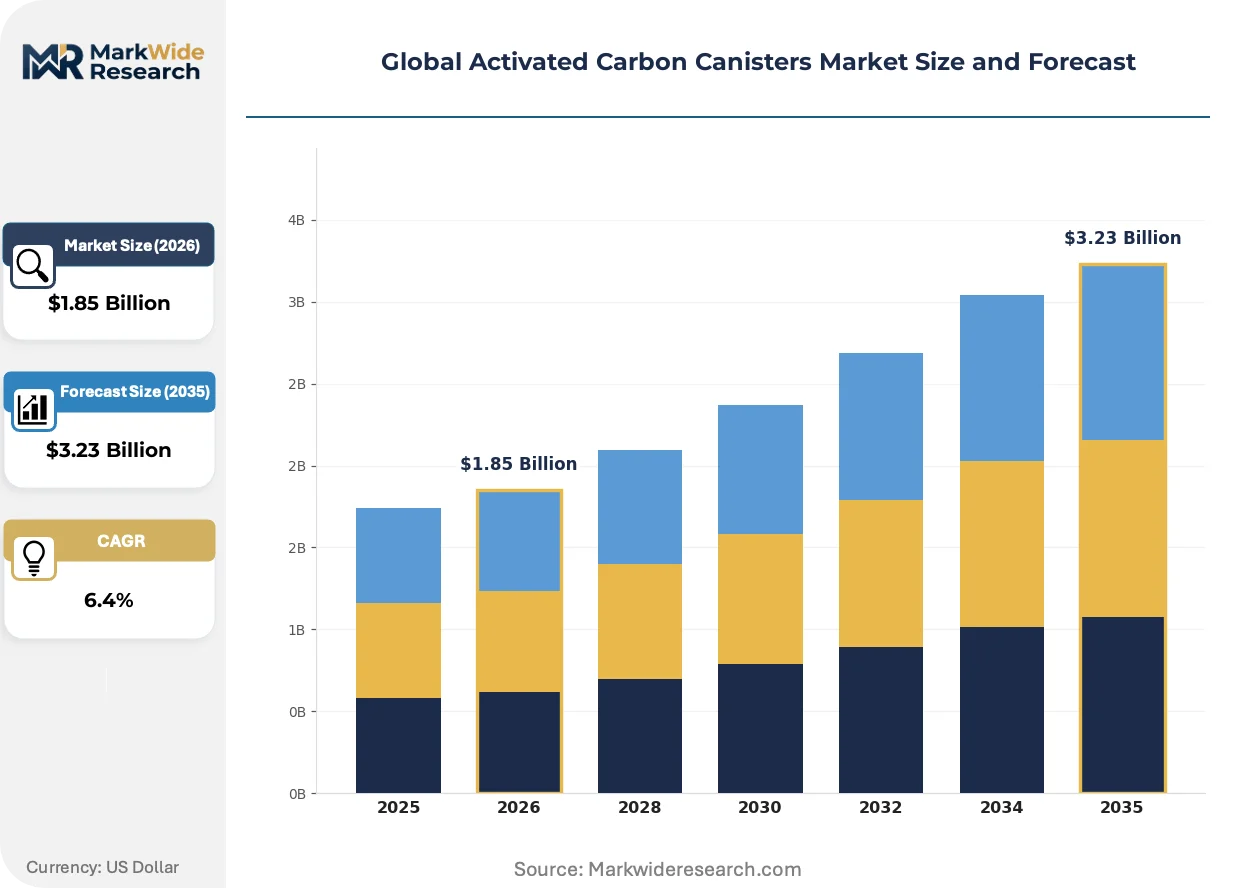
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Activated Carbon, Powdered Activated Carbon, Extruded Activated Carbon, Impregnated Carbon, Pellets Application: Air Purification, Water Treatment, Chemical Processing, Gas Separation, Food & Beverage Processing End User Industry: Pharmaceuticals, Petrochemicals, Electronics Manufacturing, Municipal Utilities, Food Packaging Packaging Type: Bags, Drums, Totes, Bulk Containers, Cylinders |
| Companies Covered | Robert Bosch GmbH, Continental AG, HELLA GmbH & Co., Ingevity, Stant Corporation, Delphi Automotive PLC, Calgon Carbon Corporation, Cabot Corporation, Kuraray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Activated Carbon Canisters Market Strategic Shifts & Innovations
Product development is increasingly a function of material science advancements meeting precise regulatory performance targets. This dynamic pushes innovation toward higher-capacity adsorbents and more durable canister designs capable of withstanding harsh operating conditions over longer service lifetimes across automotive and industrial applications.
Advanced computational fluid dynamics and adsorption modeling software are becoming central to canister design. These tools allow engineers to simulate vapor flow, carbon bed saturation, and purge efficiency under a wide range of operational scenarios. Automotive OEMs and their Tier 1 suppliers are the primary adopters, using this software to shorten development timelines. This technology is virtualizing the historically iterative process of physical prototyping and testing, enabling faster compliance with new emissions standards.
China's MEE is aggressively implementing its GB standards for industrial VOC emissions as a core component of the nation's "dual carbon" policy. This regulatory push mandates that facilities in sectors like petrochemicals, printing, and furniture manufacturing install or upgrade air pollution control equipment. The industrial canister segment in China is most affected, with demand shifting decisively toward high-performance systems that guarantee long-term compliance with tightening local and national environmental laws.
Consolidation within the automotive aftermarket distribution channel is altering procurement patterns for replacement canisters. Large, multi-regional auto parts retailers and e-commerce giants are increasingly bypassing traditional tiered distributors to source products directly from manufacturers. This disintermediation pressures smaller, specialized distributors while favoring canister producers who possess the scale and logistical capabilities to manage direct-to-retail supply chains, a trend most visible in North America.
Global Activated Carbon Canisters Market Segmentation
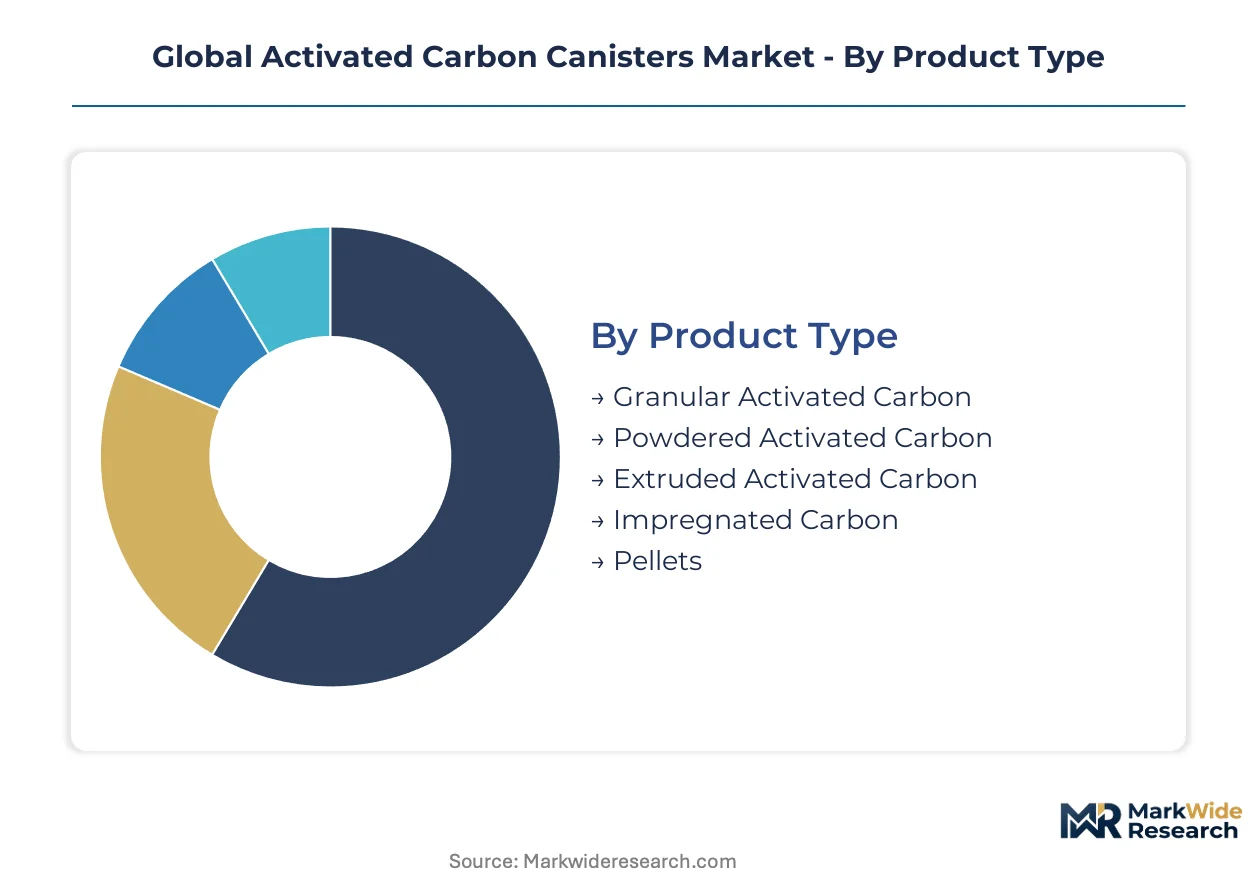
The global activated carbon canisters market is precisely segmented to reflect the diverse material compositions, application requirements, end-user specifications, and logistical considerations influencing procurement. This detailed breakdown allows manufacturers to align product development with specific industry needs and regulatory compliance across various global regions.
Product Type:
The turnover rate for different product types varies significantly, with some requiring more frequent replacement due to adsorption capacity limits, while others offer extended service lifetimes.
- Granular Activated Carbon:This product type consists of irregular-shaped particles with high surface area and porosity, making it highly effective for vapor adsorption in automotive evaporative control systems. Demand for GAC is particularly strong in North America due to strict US EPA regulations for vehicle emissions.
- Pellets:Cylindrical activated carbon pellets offer low dust content and high mechanical strength, making them suitable for applications requiring low-pressure drop and robust performance. Automakers in Europe increasingly specify pelletized carbon for Euro 7 compliant canister designs.
- Powdered Activated Carbon:Fine powder forms of activated carbon are typically used in batch processes for water treatment and industrial air purification, where rapid adsorption kinetics are beneficial.
- Extruded Activated Carbon:These carbons are formed into uniform cylindrical shapes, offering high mechanical strength and low dust, often employed in industrial gas phase applications.
- Impregnated Carbon:Activated carbon chemically treated with specific impregnants enhances its ability to adsorb particular pollutants like hydrogen sulfide or ammonia, serving specialized industrial needs.
Granular Activated Carbon dominates the installed base for automotive applications. Pellets are where expansion concentrates for next-generation vehicle platforms.
Application:
Application segments are differentiated by the volume of pollutants processed and the specific purification challenges addressed by activated carbon canisters.
- Air Purification:This segment involves removing volatile organic compounds (VOCs), odors, and other airborne contaminants from industrial exhausts and indoor environments. Industrial facilities in China are driving significant demand for air purification systems under the MEE's GB standards.
- Water Treatment:Activated carbon canisters are employed to remove taste, odor, chlorine, and organic pollutants from municipal drinking water supplies and industrial wastewater streams. Municipal utilities in India are expanding their use of these systems for public health initiatives.
- Chemical Processing:Canisters are used for solvent recovery, catalyst support, and purification of process gases within chemical manufacturing plants.
- Gas Separation:This application utilizes activated carbon's selective adsorption properties to separate gas mixtures, such as in biogas purification or hydrogen storage systems.
- Food & Beverage Processing:Activated carbon purifies ingredients, decolorize liquids, and remove off-flavors in various food and beverage production processes.
Air Purification applications command the largest market share. Water Treatment applications exhibit the steepest expansion trajectory.
End User Industry:
The market segments by end-user industry reflect varied purchasing cycles and specific regulatory requirements for air and water quality.
- Petrochemicals:This industry uses activated carbon canisters for emission control, solvent recovery, and purification of various chemical streams in large-scale operations. Petrochemical complexes in the Middle East are significant consumers due to stringent environmental permits.
- Municipal Utilities:Public water and wastewater treatment facilities utilize canisters for ensuring potable water quality and meeting discharge standards. European municipal utilities are adopting advanced systems to comply with ECHA regulations.
- Pharmaceuticals:Canisters are critical for maintaining cleanroom air quality, solvent recovery, and purifying process water in pharmaceutical manufacturing.
- Electronics Manufacturing:Activated carbon removes airborne molecular contaminants and purifies process chemicals to prevent defects in sensitive electronic components.
- Food Packaging:Canisters are integrated into packaging to absorb unwanted odors or ethylene, extending the shelf life of perishable food products.
Regulatory mandates from the US EPA and European ECHA significantly influence product specifications and procurement in the Petrochemicals and Municipal Utilities sectors.
Packaging Type:
The cost structure for activated carbon canisters is directly influenced by the packaging type, which impacts shipping efficiency and handling costs for end-users.
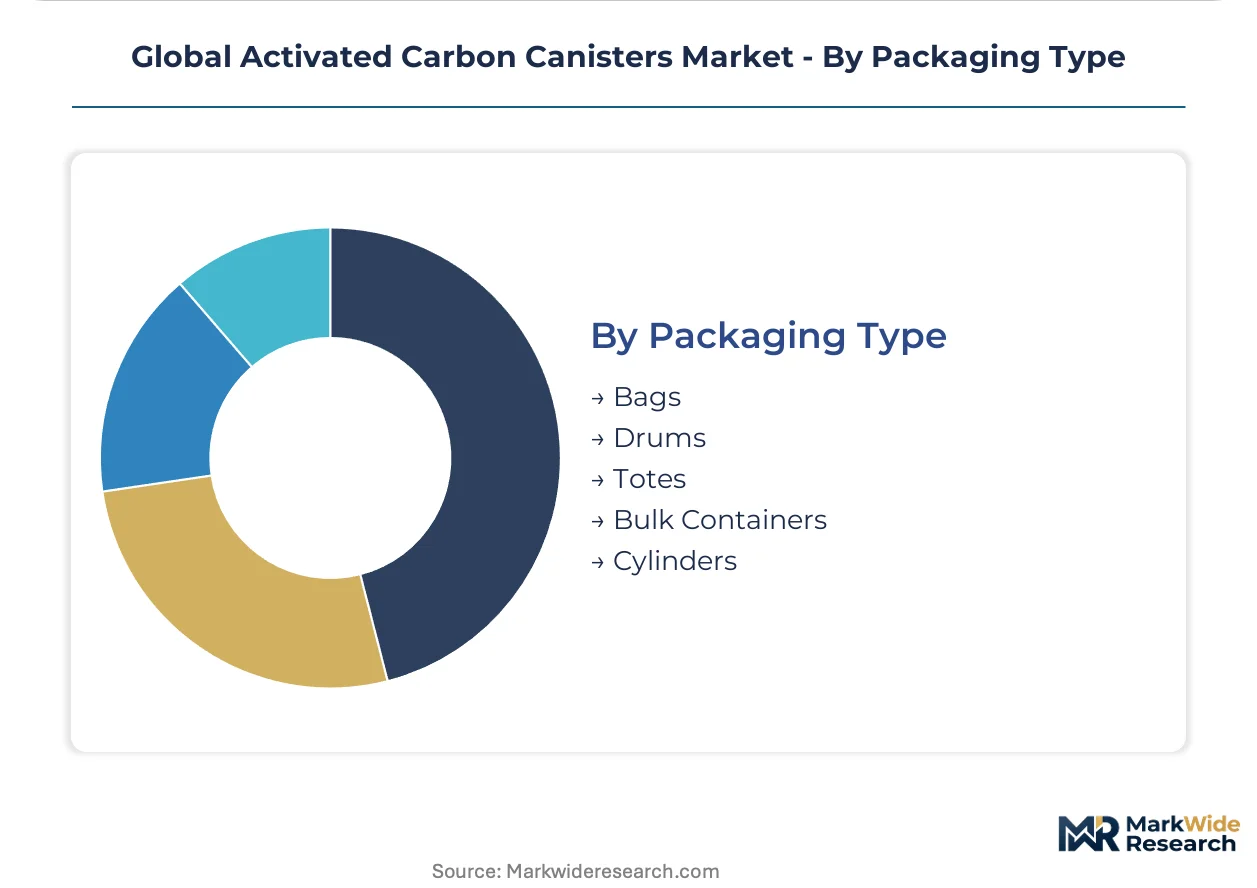
- Bulk Containers:Large containers, such as super sacks or railcars, are used for high-volume industrial customers requiring substantial quantities of activated carbon. These offer the lowest per-unit cost for large-scale operations.
- Drums:Steel or fiber drums provide a robust packaging solution for medium-to-large industrial users, balancing protection with handling convenience. Drums are commonly used for activated carbon shipments to manufacturing facilities in Southeast Asia.
- Bags:Smaller quantities of activated carbon are packaged in bags, suitable for smaller-scale applications or specialized uses where precise dosing is required.
- Totes:Intermediate bulk containers (IBCs) or totes offer a reusable and efficient option for transporting activated carbon, particularly for customers with regular, moderate volume needs.
- Cylinders:Specialized gas cylinders are employed for high-pressure or specific gas separation applications, ensuring the integrity and purity of the activated carbon.
Bulk Containers offer the most cost-effective solution for large-scale industrial procurement. Drums provide a balanced logistical solution for many commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for activated carbon canisters exhibits asymmetry, with European premium segments commanding higher value compared to the more cost-sensitive markets in Southeast Asia. This disparity influences manufacturing strategies and distribution networks across global regions. Demand drivers vary significantly by local economic and regulatory landscapes.
United States
Strict automotive evaporative emissions control and industrial air purification drive demand for activated carbon canisters in the United States. The US EPA's stringent Clean Air Act mandates specific canister capacities and durability for vehicle systems. Automotive manufacturing hubs in Michigan are integrating advanced EVAP systems to comply with federal standards.
Germany
European automakers in Germany drive demand for high-performance activated carbon pellets for Euro 7 compliance in new vehicle platforms. ECHA regulations on chemical substances also shape material specifications for industrial applications. The Ruhr region's chemical industry requires specialized canisters for process gas purification and solvent recovery.
China
Industrialization in China fuels substantial demand for canisters in new chemical processing facilities and for industrial air purification. The MEE's GB standards for industrial VOC emissions compel widespread adoption of advanced control equipment. Manufacturing clusters in the Yangtze River Delta are upgrading air pollution control systems to meet tightening local environmental laws.
India
Municipal water treatment and chemical processing expansion in India generate significant new demand for activated carbon canisters. BIS standards are increasingly influencing product quality and performance requirements for water purification systems. Industrial zones around Gujarat are installing new air purification and solvent recovery units for environmental compliance.
Japan
Automotive OEMs in Japan prioritize advanced EVAP systems for domestic and export markets, seeking durable, high-capacity canisters. JIS standards for industrial air quality and material safety guide product development for local manufacturers. The Kanto region's electronics and automotive sectors are adopting sophisticated gas separation technologies.
Global Activated Carbon Canisters Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the activated carbon canister market. This market structure is tiered, featuring large automotive Tier 1 suppliers alongside specialized material science companies. Two strategic archetypes emerge: diversified industrial conglomerates and focused high-performance material producers. Companies pursue strategic partnerships to integrate diagnostic systems and engage in capacity expansion to meet regulatory demand.
Within the diversified industrial conglomerate archetype, Robert Bosch GmbH leverages its vast original equipment service network, maintaining a strong market position across automotive applications. Ingevity, a specialized material science company, occupies a position focused on high-performance activated carbon materials, meeting the stringent technical specifications required by automakers for advanced evaporative systems. Calgon Carbon Corporation represents a significant player in the broader activated carbon market, with its offerings spanning multiple applications including water treatment and industrial air purification. Such companies exemplify the material producer segment, providing foundational components across various end-user industries.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| HELLA GmbH & Co. |
| Ingevity |
| Stant Corporation |
| Delphi Automotive PLC |
| Calgon Carbon Corporation |
| Cabot Corporation |
| Kuraray Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Regional undercapacity for specialized activated carbon canisters in Europe drives premium pricing and incentivizes strategic capacity expansion. This utilization dynamic influences supplier investment decisions and market entry strategies across global regions.
Pricing Analysis
Configured-to-order pricing for specialized automotive EVAP systems commands a premium over standard industrial-grade canisters. The market operates on a hybrid model, combining long-term contracts for automotive OEMs and transactional pricing for aftermarket and smaller industrial buyers. Price differentiation stems from technical specifications like adsorption capacity and durability, alongside certification level for Euro 7 or US EPA compliance. Pricing softness runs through the standard industrial segment due to increased competition from Asia. Automotive OEMs prioritize performance and compliance over cost, while small industrial buyers are highly price-sensitive.
Supply Chain Analysis
Coconut shell charcoal, a primary feedstock for activated carbon, originates predominantly from Southeast Asia, particularly Indonesia and the Philippines. The supply chain for activated carbon canisters relies heavily on these geographically concentrated raw material sources and petroleum coke derivatives. Commodity price volatility, influenced by agricultural variables in sourcing regions, represents a significant structural risk for manufacturers. Large-scale industrial distribution runs through bulk containers and drums to end-users in sectors like petrochemicals. Procurement patterns are shifting towards direct sourcing from manufacturers by large automotive aftermarket chains in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The activated carbon canister market presents a fragmentation opportunity as expanding application diversification, particularly in biogas purification, creates specialized niches.
For Market Incumbents: Build regulatory compliance moats by investing heavily in R&D for Euro 7 and US EPA-compliant materials, ensuring long-term market access against emerging entrants. Deepen collaboration with automotive OEMs on advanced diagnostic system integration to counter the threat from alternative technologies like cryogenic condensation. Acquire specialized material science firms to control key intellectual property for next-generation adsorbents, strengthening market position.
For New Entrants and Emerging Players: Establish a beachhead in the growing industrial air purification segment in Southeast Asia by offering cost-effective, regionally compliant canisters. Target municipal water treatment in India and biogas purification in Europe as white-space opportunities. Aftermarket penetration in Latin American countries with aging vehicle fleets offers a penetrable segment. Leverage e-commerce platforms for direct-to-consumer sales of smaller industrial and automotive aftermarket units.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science companies possessing proprietary impregnation technologies for selective pollutant adsorption. Long-term viability (5-10 year window) hinges on continuous innovation addressing increasingly complex environmental mandates. Target mid-sized firms with strong intellectual property in advanced carbon composites or novel adsorbent manufacturing processes. The signal to watch is the accelerated adoption of hydrogen storage applications, indicating broader clean energy integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Addresses industrialization-driven demand in China and India, securing market share for activated carbon canisters. |
| Advanced Material R&D | Develops higher-capacity adsorbents for Euro 7 and US EPA compliance, meeting stringent automotive performance targets. |
| Aftermarket Channel Development | Captures growth in Southeast Asian and Latin American automotive markets with aging vehicle fleets. |
| Biogas Purification Specialization | Positions manufacturers in emerging energy applications, aligning with global cleaner energy transitions. |
| Onboard Diagnostic System Integration | Ensures flawless error detection in modern vehicles, crucial for automotive electronics suppliers and OEMs. |
Research Approach
Desk research of regulatory filings, patent databases, and industry association reports preceded structured interviews with automotive OEM engineers, chemical plant managers, and activated carbon material scientists. This approach facilitated bottom-up and top-down triangulation to validate market sizing and forecast assumptions. Secondary data sources included government environmental agency reports and trade statistics to ensure comprehensive data coverage.
Market forecasts held macroeconomic stability and current regulatory trajectories fixed while varying adoption rates for new EVAP technologies and industrial VOC emission limits. The analytical framework modeled market dynamics across the analysis window. Product type, application, end-user industry, regional regulatory compliance, and raw material input were key dimensions. Compound annual growth rates were derived from historical data, projected demand, and technology diffusion curves. Automotive production volumes in key regions and industrial facility construction rates informed projections.
Stress conditions across raw material supply disruptions and unforeseen shifts in environmental policy were modeled; outcomes outside those bands fall beyond the analytical envelope. These forecasts reflect documented assumptions, and cross-checking against regional economic indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Global Neopentyl Glycol Market