
 Textile Printing Ink Market | 2026-2036
Textile Printing Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Printing Ink Market Analytics
The gap between premium digital ink formulations and commodity screen-printing supplies is recalibrating how suppliers allocate R&D budgets and manufacturing capacity. Kornit Digital Ltd. leverages its integrated pigment chemistry and print-engine architecture to capture value in on-demand fashion workflows. Sun Chemical anchors its position through backward integration into pigment synthesis and dispersion technology. Mimaki Engineering Co., Ltd. competes by specializing in reactive dye inks for cotton-rich substrates favored by Japanese and European textile houses.
Textile printing ink comprises pigment or dye particles dispersed in liquid carriers, formulated with binders, surfactants, and rheology modifiers to achieve defined viscosity ranges and color fastness ratings on woven, knitted, or non-woven substrates. Its primary purpose is to impart durable, precise coloration for decorative, functional, or branding applications across fabric manufacturing. Water-based formulations lead volume in fashion apparel due to regulatory pressure on volatile organic compound emissions, while UV-curable inks command margin premiums in industrial fabrics where instant curing and chemical resistance justify higher unit economics. Digital printing technology represents the fastest-expanding technology dimension as printhead reliability and ink-substrate compatibility widen addressable substrate scope.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, compelling domestic converters to reformulate away from solvent-heavy systems. REACH and the EU Green Deal in Europe impose substance restrictions and carbon footprint disclosure requirements that reshape supplier qualification criteria for brands selling into EU markets. China's MEE enforces emission standards on printing facilities in the Yangtze and Pearl River deltas, accelerating local adoption of compliant ink systems. Stakeholders must monitor how divergent regional compliance timelines affect cross-border sourcing strategies and capital allocation for formulation assets.
Market Dynamics
Digital printhead reliability is compressing minimum order quantities from thousands to single units, forcing ink suppliers to reformulate for viscosity stability across intermittent production cycles rather than continuous industrial runs.
Growth Catalysts
- REACH substance restrictions:European brands now require full chemical disclosure from ink suppliers, creating qualification advantages for formulators with pre-certified water-based portfolios.
- Sportswear on-demand manufacturing:Athletic apparel brands are migrating to digital workflows for seasonal color refreshes, pulling pigment ink volumes away from rotary screen operations.
- Reactive dye chemistry:Japanese textile houses favor cotton-rich substrates with reactive ink systems for superior wash fastness, sustaining premium formulation demand despite higher processing costs.
Market Restraints
- Pigment dispersion input costs:Specialized surface-modified pigment concentrates face supply concentration among German and Japanese chemical specialists, exposing formulators to raw material volatility.
- UV oligomer supply geography:Cationic photoinitiator and acrylate oligomer production clusters in East Asia, creating tariff and logistics exposure for Western ink blenders serving industrial fabric printers.
- Substrate pretreatment complexity:Digital inks require corona or plasma surface activation for synthetic fibers, adding process steps that rotary screen printing avoids entirely.
Strategic Opportunities
- India export garment hubs:Tirupur and Surat clusters lack captive ink formulation, presenting toll-manufacturing partnerships for compliant water-based systems serving EU and US-bound apparel.
- EU Green Deal carbon disclosure:Scope 3 reporting mandates for fashion brands create first-mover advantage for ink suppliers with lifecycle-assessed product lines and verified low-VOC credentials.
- UV-LED and ink convergence:Narrow-wavelength curing systems paired with matched photoinitiator packages enable heat-sensitive substrate printing, opening technical textiles and medical fabrics to digital decoration.
Industry Challenges
- Colorimetric calibration expertise:Digital textile production requires spectrophotometric profiling skills scarce among traditional screen-printing technicians, constraining workforce scalability.
- Batch-to-batch viscosity control:Water-based ink rheology drifts with humidity and temperature, demanding real-time monitoring infrastructure that legacy screen operations rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Printing Ink Market |
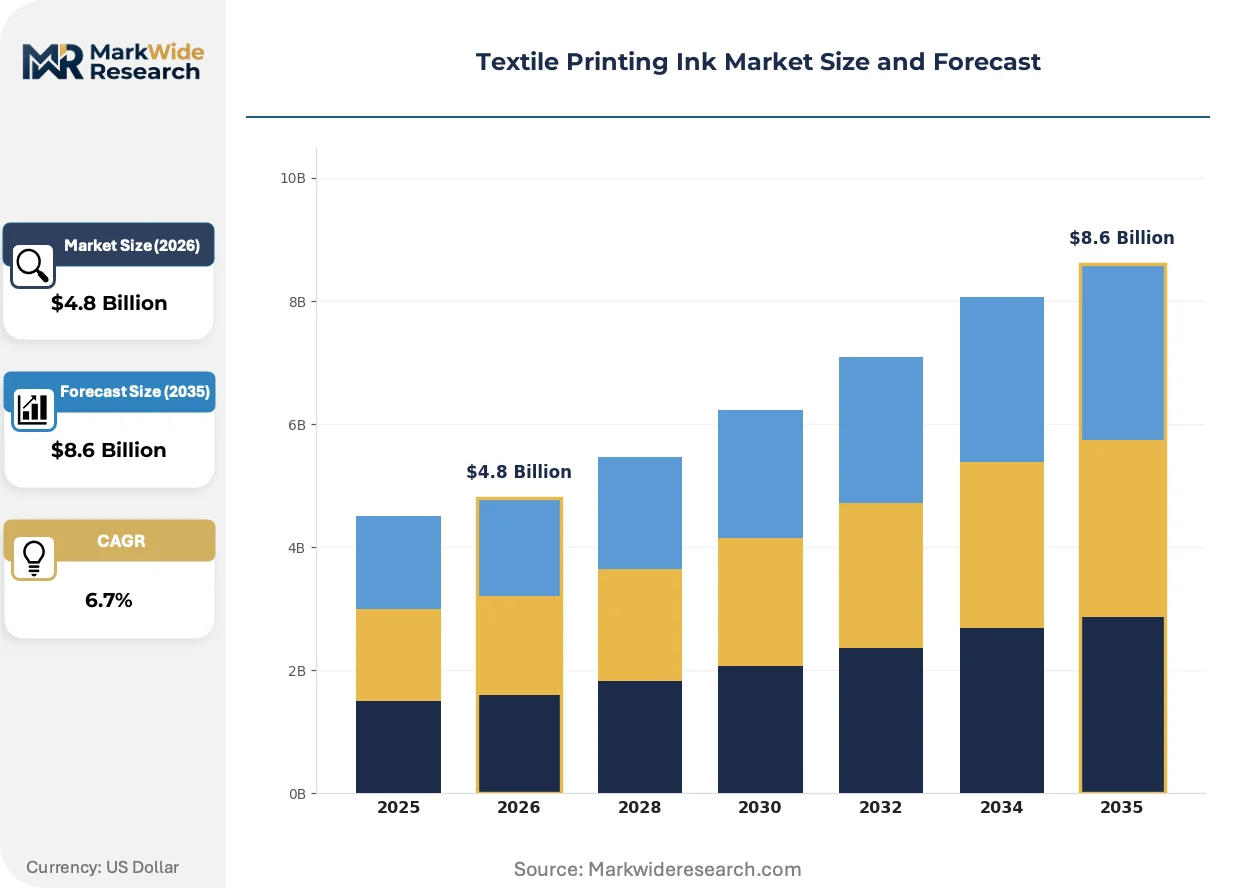
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Water-Based, Solvent-Based, UV-Curable, Plastisol Technology: Digital Printing, Screen Printing, Rotary Printing, Block Printing End User: Fashion Apparel, Home Textiles, Industrial Fabrics, Sportswear Form: Liquid, Powder, Gel, Paste |
| Companies Covered | Mimaki Engineering Co., Ltd., Kornit Digital Ltd., Sun Chemical, Electronics for Imaging, Inc., Durst Group AG, Flint Group, Ricoh Company, Ltd., Konica Minolta, Inc., Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Printing Ink Market Evolving Landscape
Pigment ink chemistry is absorbing the operational burden of substrate diversity as printhead manufacturers widen droplet placement tolerances, enabling single-pass printing on uncoated fabrics previously reserved for dye-based systems.
Nano-pigment dispersion technology is absorbing the technical constraints of fine-filament synthetics. Sportswear manufacturers in Vietnam and Indonesia are adopting these systems for polyester-elastane blends at accelerating rates. The technology is absorbing market share from sublimation transfer methods by eliminating paper waste and reducing color matching steps.
China's MEE emission standards for the Yangtze River Delta are forcing printing facilities to retire solvent-heavy coating lines. Facilities must install vapor recovery or switch to water-based or UV-curable alternatives. Bangladeshi and Pakistani export-oriented garment printers are now pre-qualifying ink suppliers against these Chinese facility standards to maintain access to EU brand sourcing offices.
Short-run procurement patterns are fragmenting buyer power across fashion micro-brands and direct-to-consumer labels. Traditional distributor networks serving volume screen printers are losing share to direct technical sales teams offering color management support. This behavioral shift is most visible in Los Angeles and London, where on-demand fulfillment centers source ink in drum quantities with weekly rather than monthly replenishment cycles.
Textile Printing Ink Market Segmentation
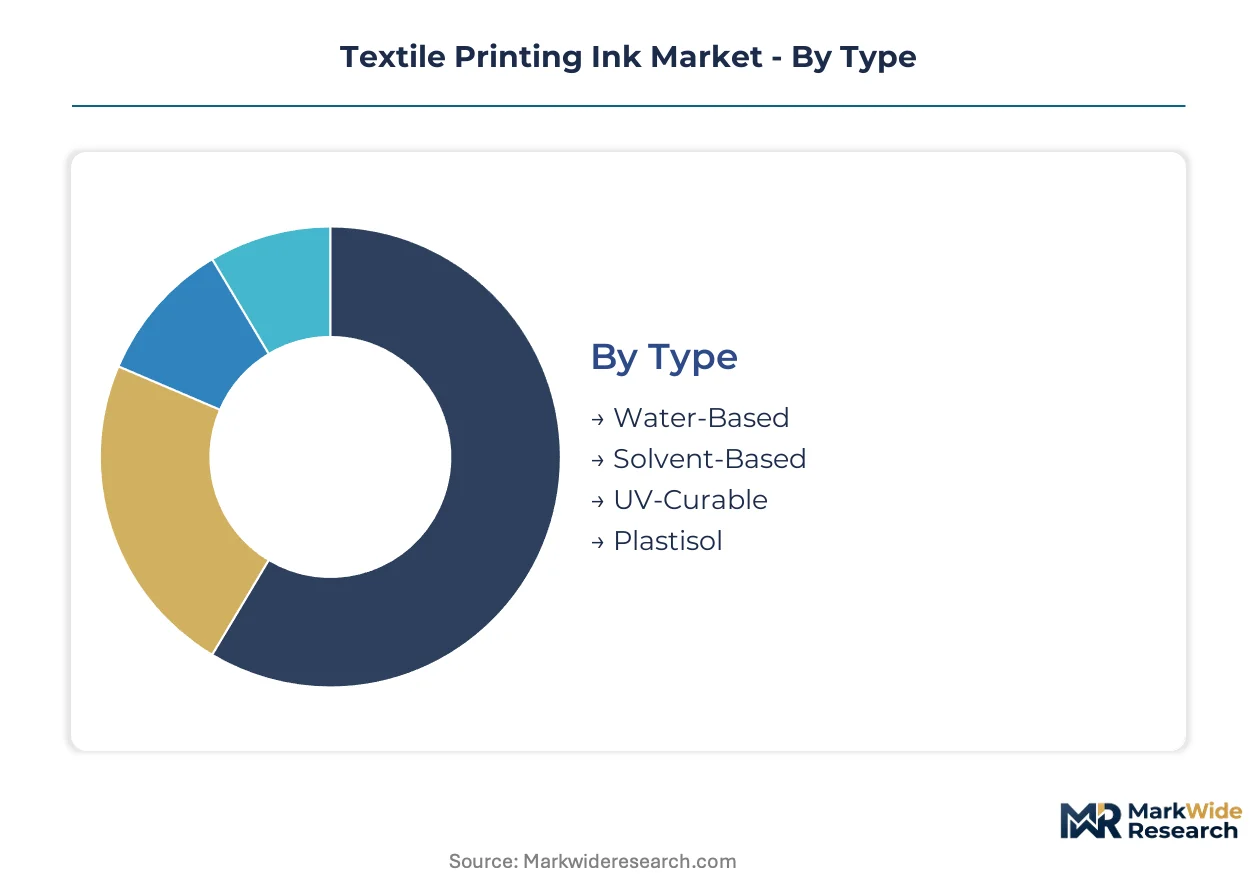
Formulation chemistry and print-engine compatibility determine supplier margins and customer switching costs across textile printing ink categories. Segmentation reveals where technical differentiation commands price premiums versus where commodity competition erodes returns.
Type:
Supply concentration in pigment dispersion technology tilts competitive advantage toward formulators with captive or exclusive sourcing relationships.
- Water-Based:Acrylic and polyurethane resin dispersions carrying pigment or dye loads, formulated with humectants and defoamers for viscosity stability. REACH and EPA emission limits in Germany and the United States pull fashion apparel converters toward these systems despite slower drying rates. Water-based formulations absorb the bulk of installed capacity; UV-curable alternatives are expanding most quickly.
- Solvent-Based:Hydrocarbon or glycol ether carriers with high solids content for rapid substrate penetration on synthetic fabrics. China's MEE enforcement in the Yangtze River Delta is forcing facility retrofits or line retirements, compressing domestic demand while export-oriented printers in Bangladesh pre-qualify compliant alternatives.
- UV-Curable:Acrylate oligomer and monomer bases with photoinitiator packages for instant polymerization under UV-LED arrays.
- Plastisol:PVC resin dispersed in plasticizer carriers, gelled through heat activation for thick-film deposits on cotton and blends.
Water-based systems dominate volume throughput in garment hubs; UV-curable chemistries gain share in industrial fabric decoration.
Technology:
Printhead reliability curves and substrate compatibility matrices determine which technology tiers absorb capital expenditure from converters.
- Digital Printing:Piezoelectric drop-on-demand deposition of ink through fixed or scanning printhead arrays. Sportswear manufacturers in Vietnam and Indonesia adopt these workflows for single-unit production runs and rapid color turnaround. Digital printing is climbing the fastest; rotary printing retains the deepest installed base.
- Screen Printing:Mesh stencil systems forcing ink through open areas via squeegee action, suited for thick-film effects and high-opacity deposits.
- Rotary Printing:Cylindrical screen drums rotating against blanket-backed fabric webs for continuous high-speed output.
- Block Printing:Hand-carved wooden or linoleum blocks stamped with manual pressure, persisting in artisanal and heritage textile production.
Rotary systems maintain throughput leadership in high-volume fashion cycles; digital platforms capture marginal growth from on-demand and micro-brand segments.
End User:
Color fastness specifications and production lot sizing diverge sharply across end-use applications, fragmenting supplier qualification requirements.
- Fashion Apparel:Seasonal color palettes and rapid style turnover demand ink systems compatible with both digital and screen workflows. European brands impose full chemical disclosure requirements, favoring formulators with pre-certified water-based portfolios. Fashion apparel commands the largest formulation volumes; sportswear is gaining share fastest.
- Home Textiles:Curtains, upholstery, and bedding applications requiring wash fastness ratings and lightfastness under domestic laundering conditions.
- Industrial Fabrics:Technical textiles for automotive, filtration, and geotextile end-uses where chemical resistance and mechanical durability justify premium UV-curable formulations.
- Sportswear:Polyester-elastane and nylon substrates for athletic performance wear, driving nano-pigment dispersion adoption for sublimation-free coloration.
Fashion apparel absorbs the majority of pigment and reactive dye volumes; sportswear applications show the steepest expansion trajectory.
Form:
Rheology control and storage stability requirements vary by form factor, affecting manufacturing equipment and distribution logistics.
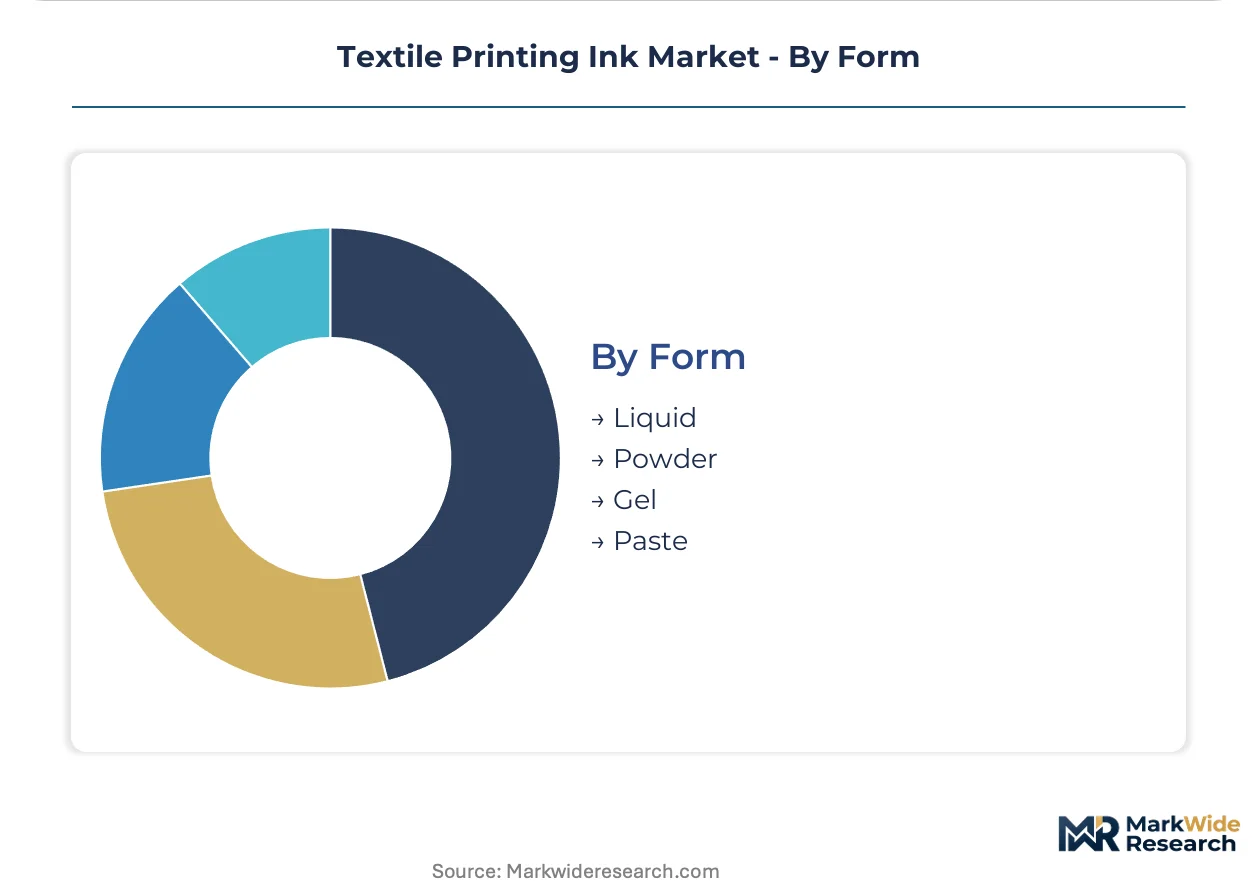
- Liquid:Pumpable dispersions with defined viscosity ranges for jetting or doctor blade application, dominating digital and screen printing supply chains. Liquid preparations hold the greatest production capacity; gel formulations are expanding most quickly.
- Powder:Solid pigment concentrates and binder systems requiring on-site dispersion, prevalent in regional blending operations serving price-sensitive markets.
- Gel:Thixotropic preparations with yield stress behavior for controlled deposit on textured or pile fabrics without wicking or bleeding.
- Paste:High-solids compositions for thick-film screen printing and resist-dye applications in traditional craft and specialty industrial segments.
Liquid formulations retain the broadest equipment compatibility; gel systems are penetrating technical textile applications requiring precise deposit control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tirupur anchors South Asia's textile printing ink demand, with the Tamil Nadu cluster processing export orders for European and North American fashion brands. The city's rotary and digital printing facilities consume water-based pigment formulations at accelerating rates.
United States
Los Angeles garment district micro-brands drive drum-quantity ink procurement with weekly replenishment cycles. EPA hazardous air pollutant regulations compel California and North Carolina converters to abandon solvent-heavy systems. Digital fulfillment centers in Brooklyn and Austin now specify pre-certified low-VOC portfolios for on-demand sportswear production.
Germany
REACH substance restrictions and EU Green Deal carbon disclosure mandates reshape supplier qualification criteria for brands selling into European markets. The country's national chemical regulator enforces full chemical disclosure requirements. Ink formulators in Baden-Württemberg and North Rhine-Westphalia maintain captive pigment synthesis operations to secure raw material stability.
China
MEE emission standards for the Yangtze River Delta force printing facilities to retire solvent-heavy coating lines or install vapor recovery systems. The Pearl River Delta garment printing corridor accelerates adoption of water-based and UV-curable alternatives. Shenzhen and Guangzhou export-oriented printers now pre-qualify ink suppliers against these facility standards.
India
Surat's synthetic fabric processing cluster lacks captive ink formulation, creating toll-manufacturing opportunities for compliant water-based systems. BIS standards and DGFT export incentives support local blending operations serving EU-bound apparel. Mumbai and Ahmedabad technical sales teams displace traditional distributor networks with direct color management support.
Bangladesh
Dhaka and Chittagong export garment hubs pre-qualify ink suppliers against Chinese MEE facility standards to maintain access to EU brand sourcing offices. The country's national environmental regulator tightens wastewater discharge limits for textile wet processing. Local rotary printing operations absorb the majority of reactive dye volumes for cotton-rich substrates.
Textile Printing Ink Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and print-engine architecture. The market structures around three tiers: integrated pigment chemists with captive dispersion technology, regional blenders serving price-sensitive rotary printers, and digital-native specialists bundling ink with printhead warranties. Strategic moves concentrate on backward integration into pigment synthesis and geographic expansion through toll-manufacturing partnerships in South Asian garment hubs.
Among Japan-based precision equipment manufacturers, Mimaki Engineering Co., Ltd. and Ricoh Company, Ltd. occupy positions emphasizing reactive dye specialization and piezoelectric deposition systems respectively. Seiko Epson Corporation anchors the consumer-to-industrial transition segment. Kornit Digital Ltd. exemplifies the vertically integrated archetype combining pigment chemistry with print-engine architecture. Sun Chemical represents the chemical conglomerate model with upstream control over dispersion technology. These five entities illustrate how competitive positioning diverges across equipment-ink bundling, raw material captivity, and regional service density.
| Leading Market Players |
|---|
| Mimaki Engineering Co., Ltd. |
| Kornit Digital Ltd. |
| Sun Chemical |
| Electronics for Imaging, Inc. |
| Durst Group AG |
| Flint Group |
| Ricoh Company, Ltd. |
| Konica Minolta, Inc. |
| Seiko Epson Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon disclosure mandates now gate qualified supply access and premium-tier pricing power, compelling ink suppliers to invest in lifecycle-assessed product lines before brands will award volume contracts. REACH substance restrictions and EPA hazardous air pollutant rules simultaneously compress commodity margins while expanding certified formulation premiums across European and North American markets.
Pricing Analysis
Value-based pricing anchored to printhead uptime guarantees and color yield consistency dominates digital textile workflows, separating premium pigment chemistry from commodity dye alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with fashion micro-brands in Los Angeles and London showing highest price sensitivity due to drum-quantity procurement patterns. Cost compression in water-based formulations is intensifying because raw material volatility in German and Japanese pigment concentrates feeds through to blender margins. Industrial fabric converters purchasing UV-curable systems demonstrate least price sensitivity, accepting premium positioning for instant curing and chemical resistance.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg and North Rhine-Westphalia pigment synthesis operations limit capacity expansion for surface-modified concentrates serving digital ink formulators. Supply concentrates in Germany, Japan, and China for specialized pigment dispersions, cationic photoinitiators, and acrylate oligomers, creating geographic dependencies that expose Western blenders to tariff and logistics volatility. Distribution runs through technical sales teams displacing traditional distributor networks in on-demand garment hubs, with direct color management support now required for drum-quantity buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
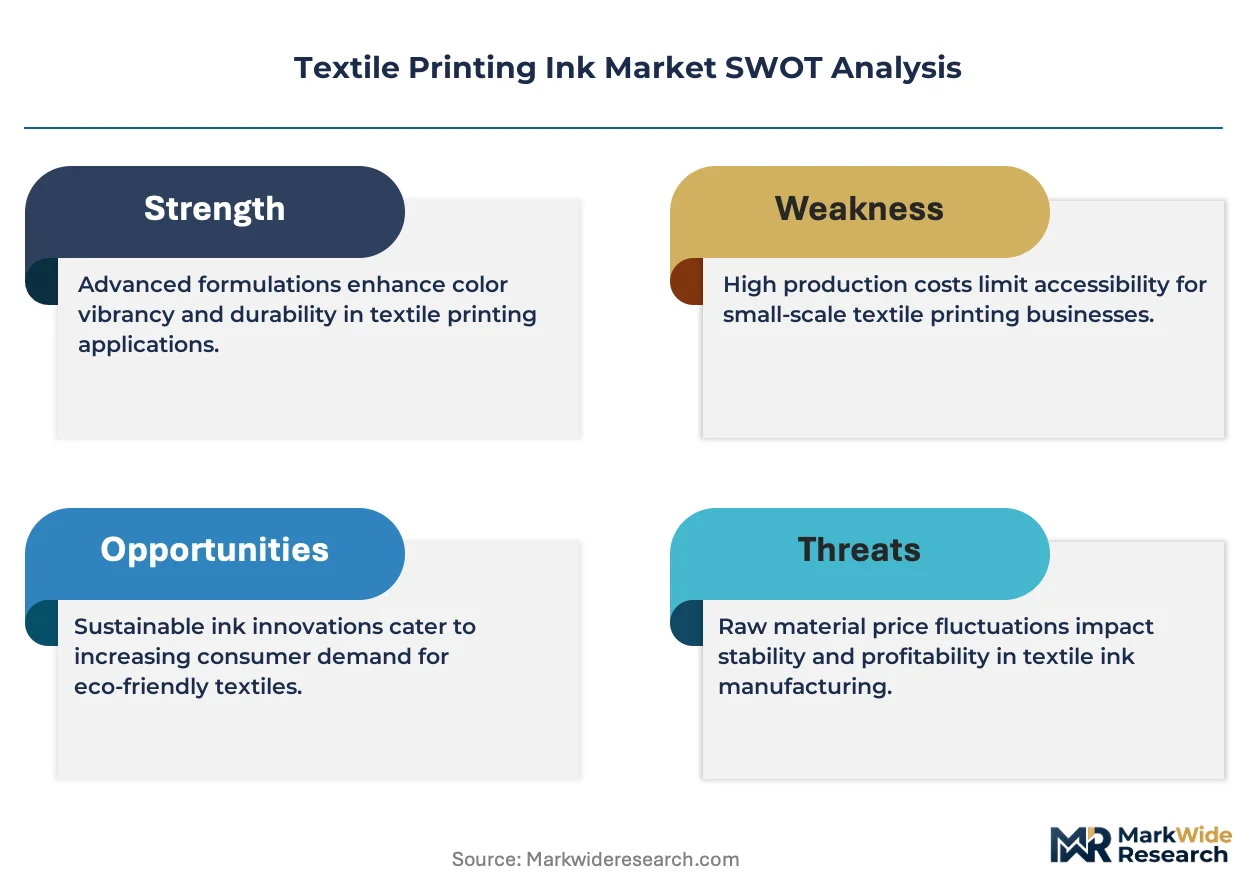
This market reads as a cost-of-compliance story where REACH substance restrictions and EU Green Deal mandates erect barrier-to-entry moats favoring formulators with pre-certified water-based portfolios and captive dispersion technology.
For Market Incumbents: Extend backward integration into pigment synthesis to secure raw material stability against German and Japanese chemical specialist concentration. Deepen technical sales presence in Tirupur and Surat through toll-manufacturing partnerships, defending share against regional blenders serving price-sensitive rotary printers. For New Entrants and Emerging Players: Enter via toll-manufacturing arrangements in Bangladeshi export garment hubs pre-qualifying suppliers against Chinese MEE facility standards. Target sportswear on-demand workflows in Vietnam and Indonesia with nano-pigment dispersion systems, leveraging sublimation-free coloration as the primary go-to-market angle. For Investors and Strategic Acquirers: EU brand sourcing offices mandating full chemical disclosure is the leading indicator that captive dispersion technology commands durable premium multiples. Acquire formulators with in-house pigment synthesis and verified low-VOC credentials, watching for MEE enforcement intensity in the Yangtze River Delta as the signal for accelerated compliant ink adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive supply of surface-modified concentrates reduces exposure to German and Japanese chemical specialist pricing volatility. |
| Toll-Manufacturing Partnership in South Asia | Tirupur and Surat clusters lack captive formulation, enabling compliant water-based supply to EU-bound apparel exporters. |
| UV-LED Curing System Convergence | Narrow-wavelength systems paired with matched photoinitiators open heat-sensitive medical fabrics to digital decoration. |
| Direct Technical Sales Team Deployment | Color management support displaces distributor networks for drum-quantity buyers in Los Angeles and London. |
| Lifecycle-Assessed Product Line Development | Verified low-VOC credentials satisfy EU Green Deal Scope 3 reporting mandates for fashion brands. |
Research Methodology
Trade databases, chemical industry association filings, and customs records formed the secondary backbone, cross-referenced with primary interviews involving ink formulation chemists, rotary printing facility managers, and sportswear brand procurement leads. Bottom-up and top-down triangulation validated volume estimates across formulation chemistry, print-engine technology, and end-use application segments.
Bottom-up modeling built from individual country-level production capacity and import-export flows, while top-down approaches anchored total addressable market sizing to garment sector output in Bangladesh, Vietnam, and Indonesia. Segmentation dimensions included formulation type, print technology, end-use vertical, and regional regulatory cluster, with CAGRs derived from trend extrapolation of digital adoption curves and compliance-driven formulation shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance list expansion or MEE enforcement intensity variations. Assumptions regarding digital printhead reliability improvement and nano-pigment dispersion cost curves underpin the projection framework. A small set of named triggers—EU carbon border adjustment implementation, Chinese dual carbon policy acceleration, and sportswear brand on-demand manufacturing penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Ink Resins Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Food Grade Inks Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Functional Printing Market
Printing Inks
Printing Inks Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Screen Printing Mesh Market