
 Northern Europe Calcium Sulphate Market | 2026-2036
Northern Europe Calcium Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Northern Europe Calcium Sulphate Market Analytics
Calcium sulphate dihydrate is expanding its share in interior wallboard formulations as magnesium oxide boards retreat on cost grounds. Saint-Gobain leverages integrated quarry-to-retail operations across Scandinavia to sustain margin stability. Knauf Group anchors its Nordic position through specialized plasterboard lines tuned to cold-climate construction codes. Etex Group competes via regional manufacturing scale that reduces logistics exposure for Swedish and Finnish distributors.
Calcium sulphate is a mineral compound with the formula CaSO₄, occurring naturally as gypsum (dihydrate) or anhydrite (anhydrous form), typically processed through calcination to produce hemihydrate plaster with controlled setting times between three and thirty minutes depending on retarder addition. The construction end-use industry dominates volume consumption, with gypsum plasterboard representing the mature revenue base while soil conditioning applications in agriculture show faster growth trajectory. Direct sales channels capture the largest margin pools through long-term supply contracts with cement producers and large-scale contractors.
REACH registration requirements and the EU Green Deal carbon accounting rules shape product formulation standards across Northern Europe. ECHA chemical safety assessments and national building codes in Sweden, Finland, and Denmark mandate fire-resistance ratings that favor gypsum-based assemblies. Stakeholders must monitor evolving embodied-carbon thresholds in public procurement frameworks to anticipate specification shifts in commercial and residential projects.
Market Dynamics
The Northern Europe calcium sulphate market is being reshaped by REACH compliance costs and EU Green Deal carbon accounting rules that force reformulation of gypsum-based building materials across Sweden, Finland, and Denmark.
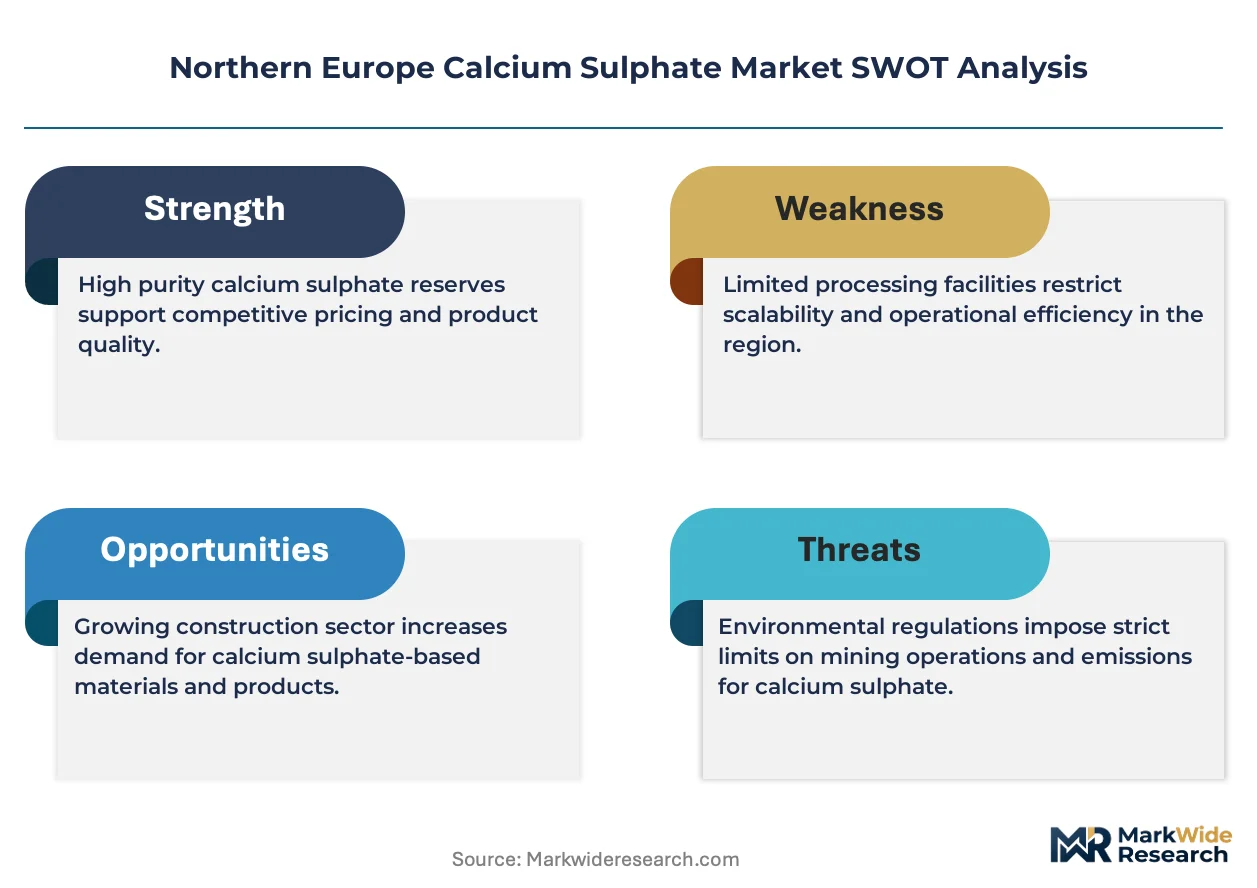
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Public procurement frameworks in Sweden and Denmark now mandate lower-carbon drywall systems, directing specification toward recycled-content gypsum plasterboard in wood-frame residential construction.
- Cold-climate construction codes:Fire-resistance ratings in Finnish and Swedish national building codes favor gypsum-based assemblies over magnesium oxide alternatives for interior wall systems.
- Sweden's wood-frame residential cluster:Concentrated demand from Stockholm and Gothenburg housing developments sustains volume pull for standard and moisture-resistant plasterboard lines.
Market Restraints
- Natural gas price volatility:Calcination energy costs for hemihydrate plaster production fluctuate with Nordic electricity and gas markets, compressing margins for calcined gypsum processors.
- Quarry concentration in southern Sweden:High-purity gypsum reserves cluster near Gotland and Skåne, creating logistics exposure for Finnish and northern Swedish distribution networks.
- Magnesium oxide board cost retreat:MgO panel pricing has compressed the premium gap with gypsum drywall in non-rated applications, threatening share in utility and secondary spaces.
Strategic Opportunities
- Finnish soil conditioning underpenetration:Agricultural CaSO₄ application for sodic soil remediation remains below Swedish penetration rates, offering white space for distributor education programs.
- CSRD supply-chain disclosure mandates:Corporate Sustainability Reporting Directive rules create service revenue pools for carbon-accounted gypsum sourcing and EPD certification support.
- Direct-to-contractor digital channels:Specialized plasterboard configurators bypass traditional merchant distribution for large Swedish and Danish commercial drywall contractors.
Industry Challenges
- Retarder chemistry expertise gap:Formulation chemists capable of tuning hemihydrate setting times for automated taping tools remain scarce across Nordic building materials labs.
- EPD certification timeline compression:Third-party environmental product declaration validation for EU Green Deal compliance now requires 8-14 months, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Northern Europe Calcium Sulphate Market |
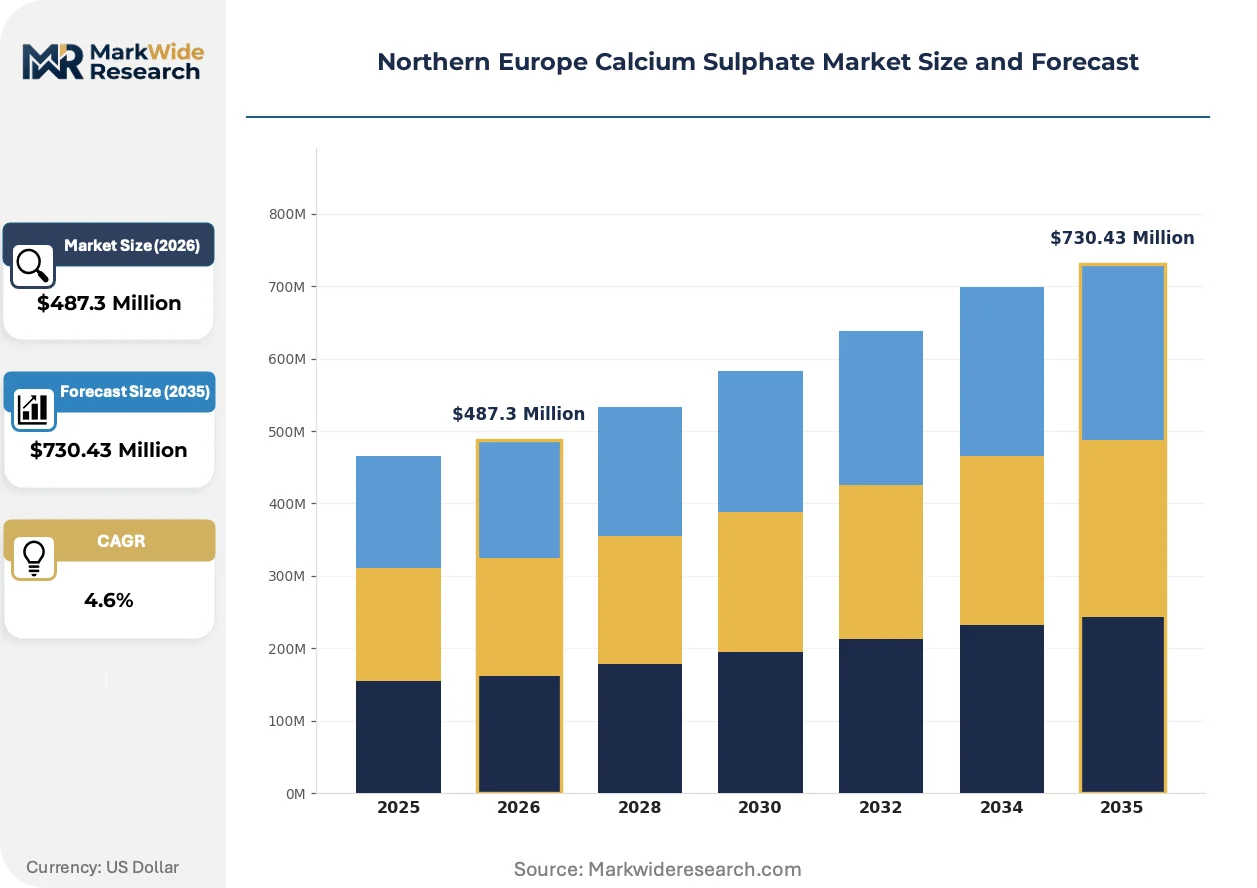
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum, Anhydrite, Calcium Sulphate Dihydrate, Plaster End Use Industry: Construction, Agriculture, Chemical Processing, Food Industry Application: Soil Conditioning, Cement Production, Food Additive, Water Treatment Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | Saint-Gobain, Knauf Group, LafargeHolcim, British Gypsum, Solvay SA, BASF SE, Etex Group, USG Corporation, AKO KASEI CO., LTD, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Northern Europe Calcium Sulphate Market Evolving Landscape
Product formulation and procurement models across Northern Europe are converging around carbon transparency and cold-climate performance specifications that reward integrated supply chain control.
Recycled-content gypsum plasterboard is absorbing specification share from virgin-mineral alternatives as Stockholm and Copenhagen developers face tightening embodied-carbon budgets in commercial and multi-family residential projects. Contractors in Sweden's wood-frame cluster now specify 30-50% recycled core content as standard, compressing the addressable market for conventional gypsum lines and rewarding processors with captive recycling streams.
REACH registration requirements and ECHA chemical safety assessments are tightening purity standards for synthetic gypsum byproduct streams used in Nordic wallboard manufacturing. Industrial processors must now document trace contaminant profiles for flue-gas desulfurization gypsum, raising compliance costs for secondary material sourcing. Finnish and Danish distributors are responding by consolidating supplier relationships toward integrated quarry-to-board producers with established dossier compliance.
Swedish and Finnish drywall contractors are consolidating procurement through long-term supply agreements that bundle material, logistics, and installation support, displacing spot purchasing through traditional builders' merchants. Large commercial contractors in Gothenburg and Helsinki now negotiate 24-36 month frame contracts with volume commitments and fixed price corridors. This concentration is most visible in Sweden's residential construction vertical, where national housebuilders have reduced active plasterboard suppliers from 4-5 to 2-3 per region.
Northern Europe Calcium Sulphate Market Segmentation
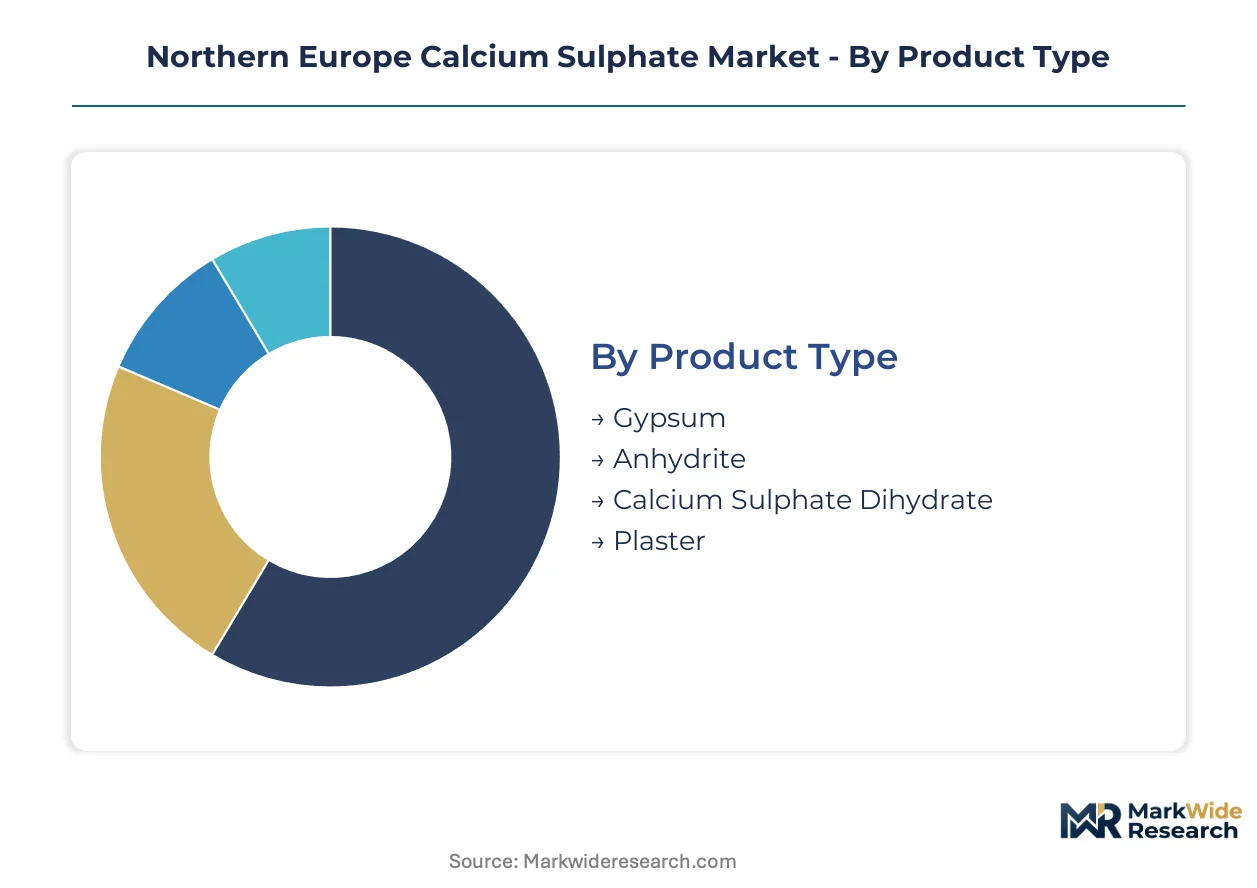
Segmentation in Northern Europe's calcium sulphate market reveals how product specifications, end-use requirements, and procurement channels create distinct competitive arenas. Buyers prioritize setting-time control for construction applications, purity grades for food and chemical uses, and logistics reliability for agricultural distribution.
Product Type:
Cost tier and application criticality determine buyer selection across the four product categories.
- Plaster:Hemihydrate plaster produced through controlled calcination delivers setting times between three and thirty minutes depending on retarder chemistry. Swedish drywall contractors specify this for automated taping tools in Stockholm's wood-frame residential cluster, where speed and finish quality drive procurement.
- Gypsum:Natural calcium sulphate dihydrate serves as the feedstock for calcined products and direct soil conditioning applications. Finnish agricultural distributors source this for sodic soil remediation programs in the Ostrobothnia region, where calcium deficiency limits crop yields.
- Calcium Sulphate Dihydrate:High-purity crystalline form meeting REACH registration standards for food-grade and pharmaceutical applications. Danish food processors utilize this as a firming agent in tofu production and brewing applications.
- Anhydrite:Anhydrous calcium sulphate with slower dissolution kinetics preferred for long-release soil conditioning and specialized cement formulations. Norwegian cement producers blend this for sulfate-resisting concrete in coastal infrastructure.
Volume sits with Plaster; growth tilts toward Calcium Sulphate Dihydrate.
End Use Industry:
Application maturity and regulatory exposure separate the four industrial demand pools.
- Construction:Dominates value consumption through gypsum plasterboard for interior wall systems, fire-rated assemblies, and moisture-resistant applications. Swedish national building codes mandate gypsum-based fire barriers in multi-family residential projects, sustaining specification pull.
- Agriculture:Expanding most quickly as Finnish and Swedish farmers adopt calcium sulphate for sodic soil remediation and nutrient management. EU Green Deal agricultural subsidies accelerate adoption in regions with clay-heavy soils.
- Chemical Processing:Industrial buyers source synthetic gypsum byproduct streams and high-purity grades for specialty chemical manufacturing. ECHA chemical safety assessments tighten purity documentation requirements for secondary material sourcing.
- Food Industry:Regulated applications include firming agents, yeast nutrients, and processing aids requiring food-grade certification. Danish and Swedish food safety authorities enforce strict contaminant thresholds on imported dihydrate.
Construction commands current volume; agriculture offers the steepest expansion trajectory.
Application:
Performance specifications and buyer sophistication vary sharply across the four use cases.
- Cement Production:Gypsum and anhydrite serve as set-retarders controlling Portland cement hardening rates. Norwegian and Swedish cement plants specify precise grind sizes and sulfate content for consistent performance in precast concrete manufacturing.
- Soil Conditioning:Agricultural CaSO₄ application addresses sodicity, aluminum toxicity, and calcium deficiency in Nordic soils. Finnish extension services promote this practice in southwestern clay plains where traditional lime amendments prove insufficient.
- Food Additive:E-number E516 applications require batch certification for heavy metals and microbial contamination. Swedish and Danish food manufacturers audit supplier dossiers against EFSA safety evaluations.
- Water Treatment:Limited use in flue-gas desulfurization and specialized industrial effluent processing. Danish power utilities generate synthetic gypsum as a byproduct, creating circular supply potential.
Cement Production anchors volume; Soil Conditioning is gaining share fastest.
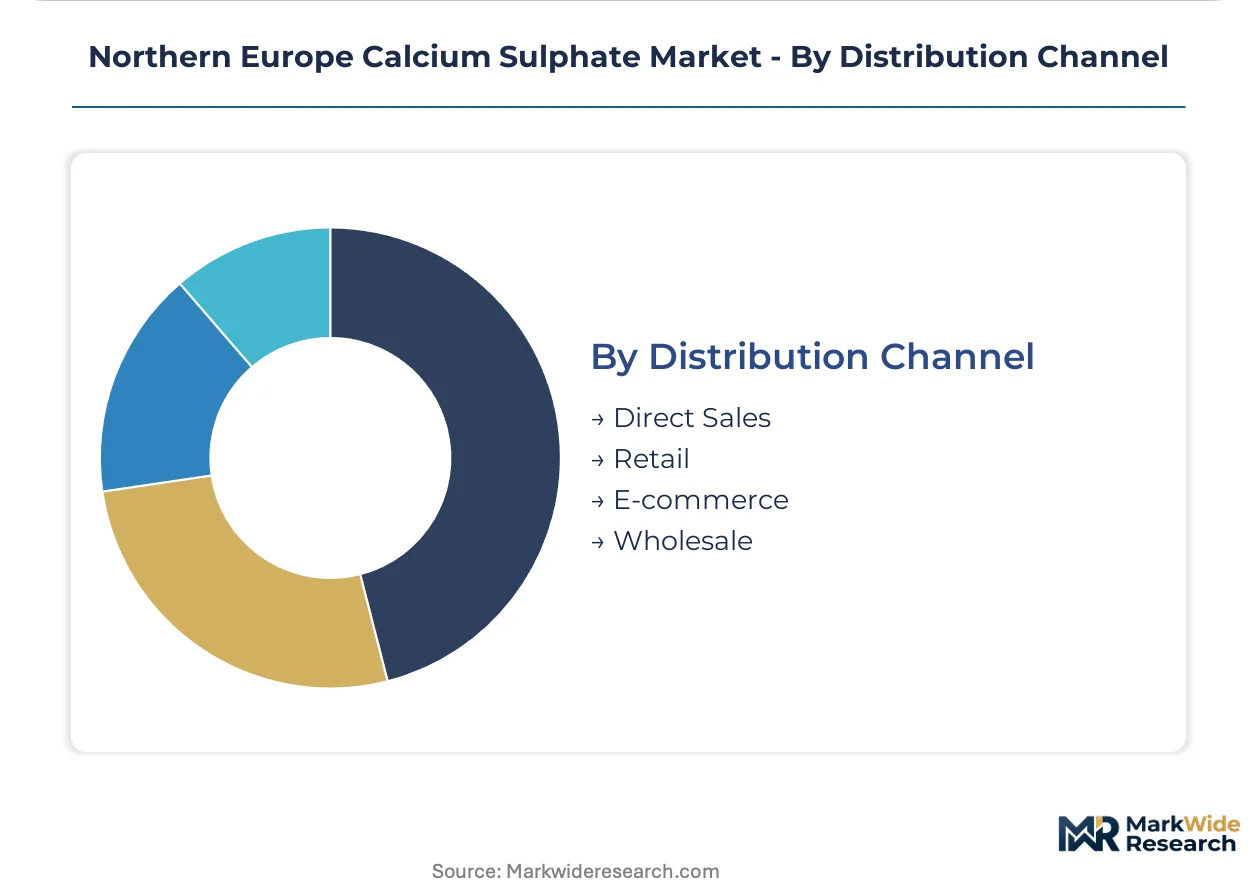
Distribution Channel:
Customer scale and service requirements fragment procurement pathways across four channel types.
- Direct Sales:Long-term supply contracts with cement producers, national housebuilders, and large-scale agricultural cooperatives capture premium margin pools. Swedish commercial drywall contractors negotiate 24-36 month frame agreements bundling material, logistics, and technical support.
- Wholesale:Regional distributors serve mid-tier construction firms and agricultural retailers across Sweden, Finland, and Denmark. Gotland and Skåne quarry proximity advantages concentrate wholesale gravity in southern Sweden.
- Retail:Builders' merchants and agricultural supply stores handle spot purchases for small contractors and independent farmers. This channel faces compression as procurement consolidates toward direct and digital pathways.
- E-commerce:Emerging digital configurators for specialized plasterboard lines and agricultural amendments bypass traditional distribution. Large Swedish contractors pilot direct-to-site ordering platforms with real-time inventory visibility.
Direct Sales holds volume concentration; E-commerce shows the most rapid development slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden concentrates regional demand through its wood-frame residential construction cluster, while Finland, Denmark, and Norway each present distinct regulatory and industrial drivers that shape calcium sulphate consumption patterns.
Sweden
Stockholm and Gothenburg housing developments sustain volume pull for standard and moisture-resistant plasterboard lines. Swedish national building codes mandate gypsum-based fire barriers in multi-family residential projects under Boverket regulations. The Gotland and Skåne quarry belt anchors high-purity gypsum extraction, creating logistics concentration for Nordic distribution networks.
Finland
Agricultural CaSO₄ application for sodic soil remediation remains below Swedish penetration rates, offering white space for distributor education programs in the Ostrobothnia region. Finnish extension services promote calcium sulphate amendments in southwestern clay plains where EU Green Deal agricultural subsidies accelerate adoption. Helsinki-based commercial drywall contractors now negotiate 24-36 month frame contracts with volume commitments.
Denmark
Copenhagen developers face tightening embodied-carbon budgets that direct specification toward recycled-content gypsum plasterboard. Danish food processors utilize high-purity calcium sulphate dihydrate as a firming agent in tofu production under EFSA safety evaluations. The country's power utilities generate synthetic gypsum as a flue-gas desulfurization byproduct, creating circular supply potential for wallboard manufacturing.
Norway
Norwegian cement producers blend anhydrite for sulfate-resisting concrete in coastal infrastructure projects. The country's cold-climate construction codes favor gypsum-based assemblies for interior wall systems in multi-family residential developments. Stavanger and Bergen construction clusters drive demand for fire-rated drywall systems in commercial and residential verticals.
Denmark
Danish national procurement frameworks now mandate lower-carbon drywall systems in public construction projects under EU Green Deal implementation. ECHA chemical safety assessments tighten purity documentation requirements for secondary material sourcing across industrial processors. Aarhus and Odense housing developments consolidate supplier relationships toward integrated quarry-to-board producers with established REACH dossier compliance.
Northern Europe Calcium Sulphate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with construction end-use favoring integrated producers while agricultural and chemical applications accommodate more fragmented supply. The Northern Europe calcium sulphate market presents a tiered structure where quarry-to-retail operators compete against regional processors dependent on merchant gypsum sourcing. Three archetypes dominate: Scandinavian-integrated producers with captive mineral reserves, German-Belgian industrial conglomerates with diversified chemical portfolios, and specialty distributors focused on agricultural amendment channels. Competitive dynamics center on backward integration into quarry assets and carbon-accounted product certification rather than price-based rivalry.
Within the integrated producer tier, Saint-Gobain and Knauf Group exemplify archetypes of quarry-captive operators with Nordic manufacturing footprints. Etex Group occupies a position representing regional manufacturing scale that reduces logistics exposure for Swedish and Finnish distributors. These three companies anchor the competitive core, with their strategic positioning shaped by mineral reserve access and cold-climate product formulation capabilities rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Saint-Gobain |
| Knauf Group |
| LafargeHolcim |
| British Gypsum |
| Solvay SA |
| BASF SE |
| Etex Group |
| USG Corporation |
| AKO KASEI CO., LTD |
| Others |
Value Network & Pricing Analysis
Swedish national housebuilders and large commercial drywall contractors concentrate procurement through 24-36 month frame contracts, compressing spot-market liquidity and anchoring pricing power with integrated quarry-to-board producers. This buyer consolidation rewards backward integration into captive gypsum reserves while squeezing margin pools for merchant-dependent processors.
Pricing Analysis
Volume concentrates in standard-grade plasterboard lines where per-unit margins compress under natural gas price volatility, while premium tiers for moisture-resistant and fire-rated assemblies retain pricing power through certification-linked differentiation. Price differentiation hinges on REACH dossier completeness and EPD certification status, with uncertified imports facing procurement exclusion from Copenhagen and Stockholm developers. Cost compression in calcined gypsum runs through Nordic electricity market exposure, tightening fastest for processors without captive quarry supply. Small contractors and independent farmers remain most price-sensitive, while national housebuilders prioritize supply security over unit cost.
Supply Chain Analysis
Gypsum feedstock supply rests on high-purity reserves concentrated in Gotland and Skåne, with Finnish and Danish processors drawing from Swedish quarry belts or synthetic FGD gypsum streams. Key inputs include natural gas for calcination energy, retarder chemistry for setting-time control, and recycled paper facing for plasterboard manufacturing. Single-source vulnerability concentrates in southern Sweden quarry access, where logistics exposure lengthens for northern distribution networks. Distribution runs through direct long-term contracts for large contractors, wholesale channels for regional construction firms, and emerging digital configurators bypassing traditional merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where quarry access and carbon-accounted product certification determine competitive survival. Players are pursuing upstream control over high-purity gypsum reserves to defend margin stability against input cost volatility.
For Market Incumbents: Anchor Nordic market position through captive recycling stream development for 30-50% recycled-content plasterboard lines demanded by Stockholm and Copenhagen developers facing EU Green Deal embodied-carbon thresholds. Invest in EPD certification infrastructure to compress third-party validation timelines from 14 months toward competitive benchmarks. Defend against magnesium oxide board cost retreat by bundling fire-rated system warranties with cold-climate construction code expertise.
For New Entrants and Emerging Players: Enter via Finnish agricultural soil conditioning distribution, where sodic soil remediation penetration trails Swedish levels and EU Green Deal subsidies accelerate farmer education needs. Target white space in carbon-accounted gypsum sourcing services under CSRD supply-chain disclosure mandates, where established producers lack dedicated service arms. Build go-to-market through direct digital channels for large Swedish commercial contractors consolidating procurement away from traditional builders' merchants.
For Investors and Strategic Acquirers: The window for entry favors quarry-captive mid-cap specialists with established REACH dossiers and cold-climate product formulation capabilities. Long-term viability hinges on mineral reserve tenure and recycling infrastructure rather than manufacturing scale alone. Watch for inflection in Swedish public procurement frameworks tightening embodied-carbon thresholds, which would accelerate specification shifts toward integrated producers with verified circular supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive gypsum reserves from Gotland and Skåne insulate margin stability against Nordic energy price volatility. |
| Recycled-Content Plasterboard Scale-Up | 30-50% recycled core content meets Stockholm developer specifications under tightening EU Green Deal carbon budgets. |
| EPD Certification Infrastructure Investment | Compressed third-party validation timelines accelerate product launch velocity for Copenhagen and Helsinki contractors. |
| Direct-to-Contractor Digital Channel Development | Real-time inventory configurators bypass traditional merchant distribution for large Swedish commercial drywall contractors. |
| Finnish Agricultural Distribution Partnership | Distributor education programs capture sodic soil remediation white space in Ostrobothnia clay plains under EU subsidy acceleration. |
Research Methodology
Document review covered customs and trade data from Nordic statistical agencies, SEC filings and annual reports from construction materials conglomerates, ECHA REACH registration databases, and EU Green Deal implementation guidance, complemented by interviews with plant managers at calcined gypsum processors, procurement leads at Swedish national housebuilders, distribution channel partners across Finland and Denmark, and technical R&D directors specializing in retarder chemistry formulation. Bottom-up volume modeling triangulated against top-down construction sector spending analysis.
Historical production and consumption patterns cross-referenced against panel input from industry stakeholders informed the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry vertical, application performance specification, and distribution channel structure. CAGRs derived from regression analysis against construction sector output indices, agricultural subsidy program trajectories, and regulatory compliance cost evolution. Forecast inputs incorporated natural gas price scenario modeling and embodied-carbon threshold policy development timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme Nordic electricity market volatility or accelerated magnesium oxide board cost compression. Assumptions reflect documented regulatory trajectories for REACH compliance and EU Green Deal implementation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Mass Transfer Trays Market