
 Carbon Composites Market | 2026-2036
Carbon Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Composites Market Analysis
AS9100 certification is reorganizing supplier hierarchies in the carbon composites sector, forcing tier-two material providers to upgrade quality systems or exit aerospace qualification pipelines. Toray Industries sustains the broadest PAN-based carbon fiber portfolio across Japan, Europe, and the United States. Hexcel Corporation dominates thermoset prepreg supply to Boeing and Airbus tier-one aerostructures fabricators. SGL Carbon specializes in automotive-grade chopped fiber and molded compounds for BMW's electric vehicle architectures.
Carbon composites are fiber-reinforced materials combining carbon fibers with thermoset or thermoplastic resin matrices, typically achieving specific tensile strengths exceeding 1,500 MPa while maintaining densities below 1.6 g/cm³, engineered primarily for structural load-bearing applications where stiffness-to-weight ratios determine performance. Carbon fiber reinforced polymer formulations anchor the highest value segment due to entrenched aerospace qualification cycles and multi-year OEM lock-in contracts. Continuous fiber composites represent the fastest-growing product category as automated fiber placement and resin transfer molding reduce labor content in wind turbine blade and pressure vessel production. Carbon nanotube-enhanced variants remain nascent, constrained by dispersion uniformity challenges and limited batch-scale manufacturing consistency.
FAA airworthiness directives and EASA certification standards govern material allowables and damage tolerance testing protocols for structural composite applications in commercial aviation. REACH substance restrictions and EU Green Deal embodied carbon reporting requirements are reshaping resin chemistry selection and recycling pathway investments across European supply chains. China's GB standards and MIIT industrial policy directives accelerate domestic carbon fiber capacity expansion while limiting import dependency for defense-aerospace grades. Stakeholders must monitor qualification timeline compression as OEMs dual-source critical aerostructures and regulators harmonize damage tolerance standards across jurisdictions.
Market Dynamics
AS9100 certification requirements are reorganizing supplier hierarchies in carbon composites, forcing tier-two material providers to upgrade quality systems or exit aerospace qualification pipelines entirely.
Growth Catalysts
- Automated fiber placement:Wind turbine blade manufacturers in Denmark and Germany are adopting robotic layup systems to compress production cycles and reduce labor content in 80-meter-plus blade architectures.
- FAA damage tolerance protocols:Harmonized airworthiness standards across US and European jurisdictions are accelerating multi-source qualification timelines for structural aerostructures.
- EU Green Deal embodied carbon reporting:Mandatory lifecycle disclosure requirements are redirecting resin chemistry investments toward bio-based and recyclable thermoplastic matrices in French and German supply chains.
Market Restraints
- Acrylonitrile price volatility:Feedstock cost swings for PAN precursor production compress margin stability for carbon fiber manufacturers dependent on petrochemical supply chains.
- Japanese and Korean supply concentration:Oligopolistic control over aerospace-grade tow capacity creates single-source vulnerability for Western tier-one aerostructures fabricators.
- Aluminum-lithium substitution:Arconic and Constellium alloys in wing skins and fuselage stringers retain cost advantage for single-aisle aircraft programs with moderate performance requirements.
Strategic Opportunities
- India defense-aerospace localization:PLI scheme incentives and DGFT import substitution mandates are opening qualification pathways for domestic carbon fiber prepreg manufacturing.
- Hydrogen pressure vessel adoption:Type IV composite tanks for heavy-duty fuel cell trucks represent uncontracted demand from Hyundai, Nikola, and Daimler engineering programs.
- CE marking harmonization with ISO standards:Converged composite testing protocols are reducing redundant certification costs for European suppliers exporting to Middle Eastern and Southeast Asian markets.
Industry Challenges
- Non-destructive inspection technician scarcity:Ultrasonic and thermography specialists qualified to ASNT standards command premium wages, constraining throughput at tier-two fabrication facilities.
- Autoclave capacity bottlenecks:Out-of-autoclave curing technologies remain unproven for primary aerostructures, locking capital-intensive oven investments into 15-year depreciation cycles.
- REACH substance restriction compliance:Bisphenol A and formaldehyde reclassifications are forcing resin formulators to requalify entire product lines under ECHA substance evaluation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Composites Market |
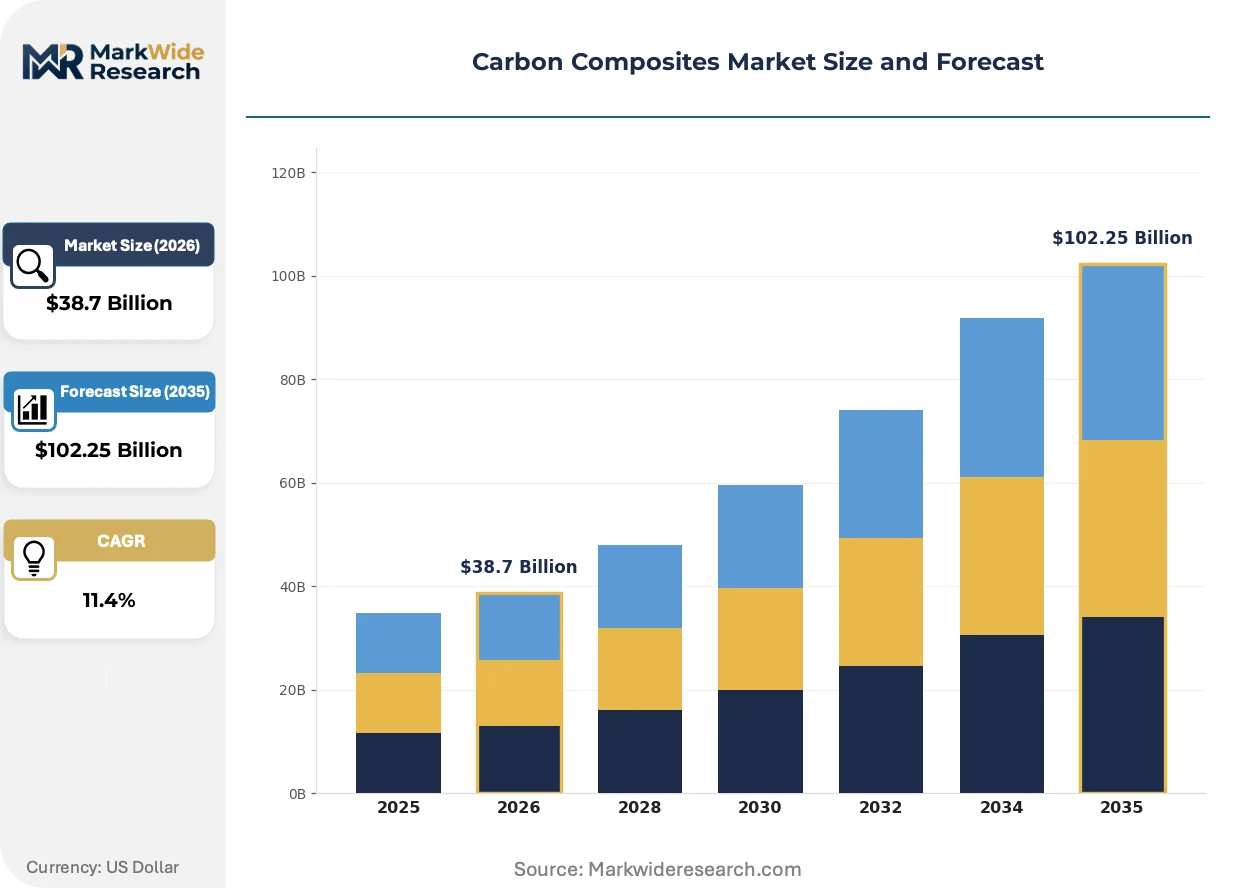
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber Reinforced Polypropylene, Carbon Nanotubes, Carbon Fiber Reinforced Polymer, Continuous Fiber Composites Application: Aerospace Components, Automotive Parts, Electronics Enclosures, Construction Materials End User: Aerospace Industry, Automotive Manufacturers, Electronics Sector, Construction Firms Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Mitsubishi Chemical Holdings Corporation, Zoltek, Toray Industries, Inc., DowAksa Advanced Composites LLC, Solvay, Teijin Limited, SGL Carbon, Formosa Plastics Corporation, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Composites Market Emerging Trajectories
Thermoplastic resin systems are capturing engineering attention as out-of-autoclave processing matures, while regulatory pressure on embodied carbon intensifies material selection criteria across transport sectors.
PEEK and PPS matrix composites are displacing epoxy thermosets in aircraft interior brackets and engine nacelle components where fire-smoke-toxicity regulations have tightened. Bombardier and Gulfstream business jet programs are qualifying these materials for secondary structures to eliminate autoclave bottlenecks. This displacement is compressing cure cycle times from hours to minutes while reducing scrap rates in automated production cells.
REACH substance restrictions and EU Green Deal carbon border adjustment mechanisms are reshaping resin chemistry portfolios across German and French supply chains. ECHA evaluations of styrene and isocyanates are accelerating bio-epoxy and furan-based alternative development. Small wind turbine and rail interior segments are absorbing first-generation sustainable matrices despite 15-20% cost premiums.
OEM technical specification unbundling is fragmenting traditional long-term supply agreements in commercial aviation. Boeing and Airbus procurement teams are segmenting material allowables by component criticality, enabling dual-source strategies for non-primary structures. This pattern is most visible in US Southwest and Southeast manufacturing clusters where Spirit AeroSystems and GKN Aerospace operate competing qualification pipelines.
Carbon Composites Market Segmentation
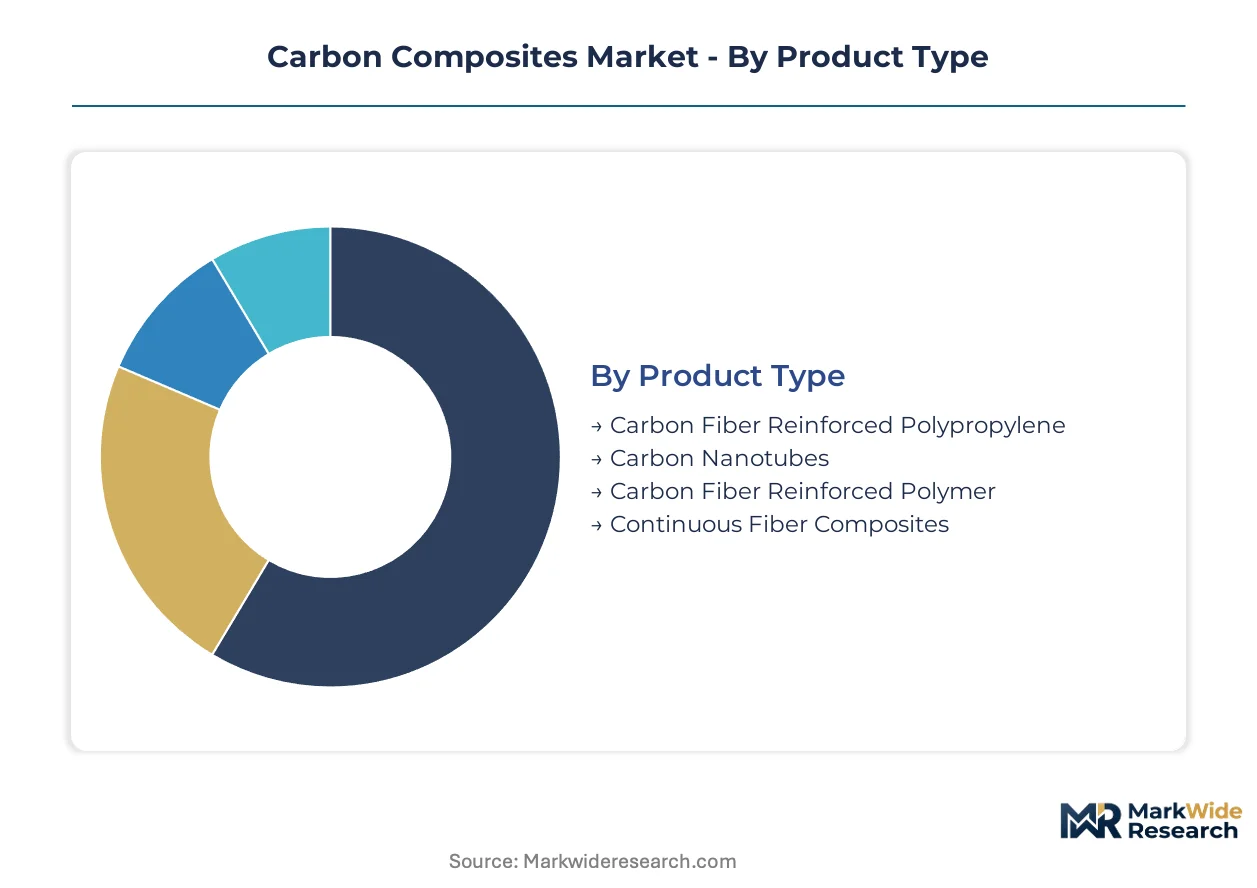
Carbon composites segmentation reveals how material specifications, certification requirements, and procurement channels fragment value capture across aerospace, automotive, and industrial verticals. Understanding these divisions exposes where margin pools concentrate and which qualification barriers protect incumbent positions.
Product Type:
Margin pools concentrate in aerospace-qualified formulations where multi-year OEM lock-in contracts and damage tolerance testing investments create defensive moats.
- Carbon Fiber Reinforced Polymer:Thermoset matrix systems combining epoxy or bismaleimide resins with PAN-based carbon fiber tows achieve specific tensile strengths exceeding 1,500 MPa. Boeing and Airbus tier-one fabricators in Washington State and Toulouse anchor demand through AS9100-qualified supply agreements spanning five-to-seven-year procurement windows. FAA airworthiness directives and EASA certification standards govern material allowables, compressing qualification timelines for secondary suppliers.
- Continuous Fiber Composites:Unidirectional or woven fiber architectures processed through automated fiber placement and resin transfer molding enable 80-meter-plus wind turbine blade production. Vestas and Siemens Gamesa operations in Denmark and Germany are compressing labor content through robotic layup systems while Denmark's labor pool constraints accelerate automation capex cycles.
- Carbon Fiber Reinforced Polypropylene:Thermoplastic matrix formulations targeting automotive interior and under-hood applications where cost sensitivity exceeds performance thresholds. BMW electric vehicle architectures in Leipzig and Munich absorb molded compounds for battery enclosures and structural seat frames.
- Carbon Nanotubes:Nano-scale carbon structures enhancing matrix mechanical and electrical properties, constrained by dispersion uniformity challenges and limited batch-scale manufacturing consistency. Laboratory-scale applications in EMI shielding and conductive coatings dominate current offtake.
The dominant share belongs to Carbon Fiber Reinforced Polymer, while Continuous Fiber Composites is closing the gap fastest.
Application:
Volume concentration tracks OEM platform cycles, with commercial aviation and electric vehicle programs driving the steepest capacity absorption.
- Aerospace Components:Primary and secondary aerostructures including wing skins, fuselage sections, and control surfaces where stiffness-to-weight ratios determine fuel efficiency. Spirit AeroSystems in Wichita and GKN Aerospace in Bristol operate competing qualification pipelines for Boeing and Airbus programs.
- Automotive Parts:Body-in-white panels, chassis components, and battery enclosures where crashworthiness and mass reduction balance against aluminum-lithium substitution economics. BMW i-series production in Dingolfing and Leipzig specifies carbon fiber roof panels and structural reinforcements.
- Electronics Enclosures:Lightweight housings for aerospace avionics, satellite structures, and high-performance computing hardware where electromagnetic interference shielding adds functional value. Satellite constellation programs in California and Texas absorb specialized prepregs.
- Construction Materials:Bridge strengthening laminates, seismic retrofit systems, and architectural facade elements where corrosion resistance extends infrastructure lifecycles. German federal highway programs and Japanese rail operators specify carbon fiber reinforced polymer sheets for concrete reinforcement.
Aerospace Components commands the largest revenue pool, though Automotive Parts is expanding most quickly as electric vehicle architectures multiply attachment points.
End User:
Procurement sophistication varies sharply, with aerospace primes enforcing AS9100 quality systems while construction contractors prioritize landed cost over technical documentation.
- Aerospace Industry:Tier-one aerostructures fabricators and engine manufacturers qualifying materials through FAA and EASA damage tolerance protocols. Boeing Commercial Airplanes in Everett and Airbus in Hamburg anchor multi-billion-dollar composite demand through long-term supply agreements.
- Automotive Manufacturers:OEMs and tier-one suppliers balancing performance specifications against high-volume cost targets. BMW Group, Porsche, and Lamborghini programs in Germany and Italy specify carbon fiber for roof structures and performance chassis components.
- Electronics Sector:Satellite manufacturers, defense contractors, and semiconductor equipment builders requiring dimensional stability and thermal management. Northrop Grumman and Lockheed Martin space divisions in California absorb specialized low-outgassing prepregs.
- Construction Firms:Civil engineering contractors and infrastructure specialists applying externally bonded reinforcement systems. German Autobahn maintenance programs and Japanese railway operators specify pultruded laminates for bridge deck strengthening.
The Aerospace Industry retains the deepest margin capture, while Automotive Manufacturers are scaling fastest as electric vehicle production multiplies platform volumes.
Distribution Channel:
Channel economics reflect certification intensity, with aerospace-grade materials flowing through qualified distributor networks while commodity thermoplastics migrate toward direct mill relationships.
- Direct Sales:Mill-direct relationships for high-volume automotive and wind energy customers where technical service teams co-locate at OEM engineering centers. Toray Industries and Hexcel Corporation maintain direct account teams at Boeing, Airbus, and Vestas facilities.
- Distributors:Specialized composite distributors holding AS9100 certification and material traceability documentation for aerospace tier-two and tier-three fabricators. Composites One and Park Aerospace Technologies operate North American distribution networks with freezer storage capabilities.
- Wholesalers:Regional stocking points for construction-grade and industrial composites where batch sizes are smaller and technical support requirements are lower. German and French building materials wholesalers carry standard pultruded profiles and repair kits.
- Online Retail:E-commerce platforms serving hobbyist, prototype, and small-batch manufacturing demand for raw fiber, fabric, and basic resin systems. Fiber Glast and Easy Composites operate UK and US-based web storefronts with global shipping.
Direct Sales captures the highest value per kilogram, though Distributors are gaining share fastest as dual-source qualification strategies multiply approved vendor lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and defense localization mandates are redirecting carbon fiber capacity investments across major manufacturing economies. National industrial policies in Germany, the United States, China, Japan, and India are accelerating qualification pipelines for aerospace-grade and automotive-grade composite materials.
United States
Boeing's 787 and 777X production programs in Everett anchor aerospace composite demand through tier-one fabricator networks. FAA damage tolerance protocols and airworthiness directives govern material allowables for primary aerostructures. The Pacific Northwest manufacturing cluster around Seattle and Wichita hosts Spirit AeroSystems and competing qualification pipelines for commercial aviation programs.
Germany
BMW i-series electric vehicle architectures and Airbus A350 production in Hamburg absorb substantial carbon fiber volumes across automotive and aerospace segments. REACH substance restrictions and EU Green Deal embodied carbon reporting requirements are reshaping resin chemistry investments. The Bavarian and Baden-Württemberg industrial corridors concentrate thermoplastic composite development for next-generation mobility platforms.
China
MIIT industrial policy directives and GB standards accelerate domestic carbon fiber capacity expansion while reducing import dependency for defense-aerospace grades. Commercial Aircraft Corporation of China (COMAC) C919 qualification programs are absorbing locally produced prepregs. The Yangtze River Delta and Shandong Peninsula host emerging tow production facilities targeting wind turbine blade and pressure vessel applications.
Japan
Toray Industries and Teijin Limited anchor global PAN-based carbon fiber supply from domestic precursor production bases. METI technology roadmaps support next-generation thermoplastic matrix development and recycling pathway investments. The Chubu region around Nagoya maintains aerospace-qualified fiber placement and autoclave curing infrastructure for Boeing and Airbus tier-one contracts.
India
PLI scheme incentives and DGFT import substitution mandates open qualification pathways for domestic carbon fiber prepreg manufacturing. Hindustan Aeronautics Limited and Defense Research and Development Organisation programs are localizing composite aerostructures for fighter aircraft and unmanned systems. The Karnataka and Telangana aerospace clusters in Bangalore and Hyderabad host emerging fabrication facilities targeting defense procurement pipelines.
Carbon Composites Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with backward control over precursor supply chains. Market structure concentrates around Japanese and European fiber producers holding aerospace qualification lock-ins, while Korean and Chinese entrants expand wind energy and industrial-grade capacity. Strategic archetypes include PAN precursor-to-fiber integrators, thermoset prepreg specialists, and automotive-grade thermoplastic compounders. Dominant competitive moves encompass capacity expansion in low-cost geographies and strategic partnerships with OEM engineering teams for co-development programs.
Among Japanese chemical conglomerates, Toray Industries, Inc., Teijin Limited, and Mitsubishi Chemical Holdings Corporation occupy positions exemplifying integrated precursor-to-composite supply chain control. Toray represents the archetype of global aerospace-qualified fiber production with multi-continental manufacturing footprints. Teijin Limited exemplifies diversification across carbon fiber and aramid fiber portfolios serving overlapping defense and industrial segments. Mitsubishi Chemical Holdings Corporation anchors a position spanning petrochemical feedstocks through advanced materials, representing conglomerate-scale vertical integration strategies. These three entities collectively illustrate how Japanese industrial policy support and long-term OEM relationship investments have consolidated aerospace-grade supply positions.
| Leading Market Players |
|---|
| Mitsubishi Chemical Holdings Corporation |
| Zoltek |
| Toray Industries, Inc. |
| DowAksa Advanced Composites LLC |
| Solvay |
| Teijin Limited |
| SGL Carbon |
| Formosa Plastics Corporation |
| Hexcel Corporation |
| Others |
Supply Flow & Price Mechanics
Economies of scale in PAN precursor production concentrate pricing power among Japanese and Korean fiber manufacturers, compressing margin capture for tier-two prepreg formulators while establishing floor prices for aerospace-qualified grades. Capacity utilization rates above 85% at Toray and Teijin facilities translate directly into oligopolistic pricing leverage over Western tier-one aerostructures fabricators.
Pricing Analysis
Certification level (AS9100 aerospace-grade versus industrial-grade) creates the primary spread, with FAA-qualified prepregs commanding three-to-five-fold premiums over wind turbine commodity tows. Price differentiation rests on damage tolerance testing investments and multi-year OEM lock-in contracts, while cost compression in automotive-grade thermoplastics is intensifying because BMW and Volkswagen procurement teams are squeezing molded compound suppliers. Tier-one aerostructures fabricators exhibit lowest price sensitivity due to airworthiness liability exposure, whereas construction contractors and industrial distributors absorb highest sensitivity with minimal technical documentation requirements.
Supply Chain Analysis
Japan and South Korea anchor aerospace-grade tow production, while China expands wind energy and industrial-grade capacity through MIIT-supported domestic precursor investments. Raw material dependencies center on acrylonitrile feedstocks from petrochemical complexes, epoxy resin formulations from German and US chemical producers, and specialized sizing agents for fiber-matrix adhesion. Single-source vulnerability concentrates in 24K and higher tow counts for primary aerostructures, where Toray, Teijin, and Mitsubishi Chemical control qualified supply. Distribution runs through AS9100-certified specialized distributors for aerospace tiers, with direct mill relationships dominating high-volume automotive and wind energy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to commercial aviation production rate restarts at Boeing and Airbus, with composite content per platform expanding across next-generation narrowbody and widebody programs.
For Market Incumbents: Shield aerospace qualification lock-ins by accelerating backward integration into precursor production and expanding autoclave capacity in low-cost manufacturing clusters. Aluminum-lithium substitution threats from Arconic and Constellium in wing skin applications demand defensive positioning through co-development contracts with Spirit AeroSystems and GKN Aerospace engineering teams.
For New Entrants and Emerging Players: Thermoplastic recycling service gaps where incumbents under-serve offer the most penetrable white-space, particularly in European markets facing EU Green Deal embodied carbon mandates. Target automotive under-hood applications and hydrogen pressure vessel manufacturing in India and Southeast Asia, where PLI scheme incentives and DGFT localization requirements lower qualification barriers. A go-to-market angle through out-of-autoclave processing partnerships with tier-two fabricators bypasses capital-intensive curing infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thermoplastic compounders serving automotive platform cycles with multi-year supply agreements. Long-term viability favors acquisition targets with backward integration into PAN precursor production and established OEM co-development pipelines. The signal to watch is FAA-EASA damage tolerance standard harmonization, which accelerates multi-source qualification timelines and fragments incumbent supply positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Captive acrylonitrile supply insulates Toray and Mitsubishi from petrochemical price volatility. |
| Out-of-Autoclave Processing Scale-Up | Bombardier and Gulfstream qualification of PEEK matrix systems eliminates curing bottlenecks. |
| Thermoplastic Recycling Pathway Investment | ECHA substance restrictions and EU Green Deal mandates reshape German resin chemistry portfolios. |
| Defense-Aerospace Localization Partnership | HAL and DRDO programs in Bangalore absorb domestic prepreg capacity for fighter platforms. |
| Hydrogen Pressure Vessel Qualification | Hyundai and Nikola engineering programs generate uncontracted demand for Type IV composite tanks. |
Methodological Framework
Operator-level perspectives from composite manufacturing engineers, tier-one aerostructures procurement leads, resin formulation R&D directors, and AS9100 quality system auditors anchored the qualitative base. Primary interviews across Boeing, Airbus, BMW, and Vestas supply chains combined with secondary validation from FAA airworthiness directives, EASA certification standards, MIIT industrial policy filings, and SEC 10-K disclosures from Hexcel and Toray. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested forecast robustness against acrylonitrile price volatility scenarios, commercial aviation production rate assumptions, and electric vehicle platform penetration curves. Segmentation dimensions modeled include matrix chemistry (thermoset versus thermoplastic), fiber architecture (continuous versus chopped), end-use vertical (aerospace, automotive, wind energy), and geographic regulatory cluster (FAA-governed, EASA-governed, MIIT-directed). CAGRs derived from production capacity absorption rates, OEM procurement pipeline visibility, and qualification timeline compression patterns.
Underlying assumptions cover sustained commercial aviation recovery, REACH substance restriction implementation timelines, and Chinese domestic capacity substitution rates, with deviation risk concentrated in acrylonitrile feedstock cost swings and aluminum-lithium alloy substitution economics. Recalibration cycles align with material shifts in FAA-EASA regulatory harmonization and OEM dual-source strategy announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Epoxy Composite Market
Composite Materials
Composite Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Biocomposites Market
Composite Materials
Tow Prepreg Market
Composite Materials
Medical Composite Material Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Global Composite Resin Market
Composite Materials
Green Composites Market