
 Anti-Corrosive Agents Market | 2026-2036
Anti-Corrosive Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Corrosive Agents Market Analytics
Aftermarket service revenue is rewriting profitability expectations across the anti-corrosive agents value chain. BASF SE leverages its Ludwigshafen integrated site to captive-produce key resin intermediates for protective coatings. The Dow Chemical Company anchors its position through water-borne acrylic technology leadership in marine applications. Cortec Corporation specializes in vapor-phase corrosion inhibitor films for electronics packaging, a niche where few multinationals compete.
Anti-corrosive agents are chemical formulations—typically comprising organic inhibitors, inorganic passivators, or polymer-based barrier systems—engineered to prevent electrochemical degradation of ferrous and non-ferrous substrates in corrosive environments. Their primary purpose is extending asset life in infrastructure, transportation, and process equipment exposed to moisture, salt, or industrial chemicals. Solvent-based coatings still command the largest value share in marine and heavy industrial settings where film integrity under extreme conditions justifies higher material costs and stricter handling protocols. Water-based formulations are gaining fastest in automotive OEM lines where VOC regulations and paint-shop energy efficiency targets reshape procurement specifications.
REACH in Europe and EPA rules in the United States are restricting chromate-based inhibitors, redirecting R&D spending toward rare-earth and organic alternatives that meet both performance and toxicity thresholds. China's MEE enforces GB standards on heavy-metal content in industrial coatings, creating compliance costs for exporters while opening local supply advantages for domestic producers. Stakeholders must monitor how tightening chemical hazard classifications in multiple jurisdictions affect registration timelines and reformulation costs for legacy product portfolios.
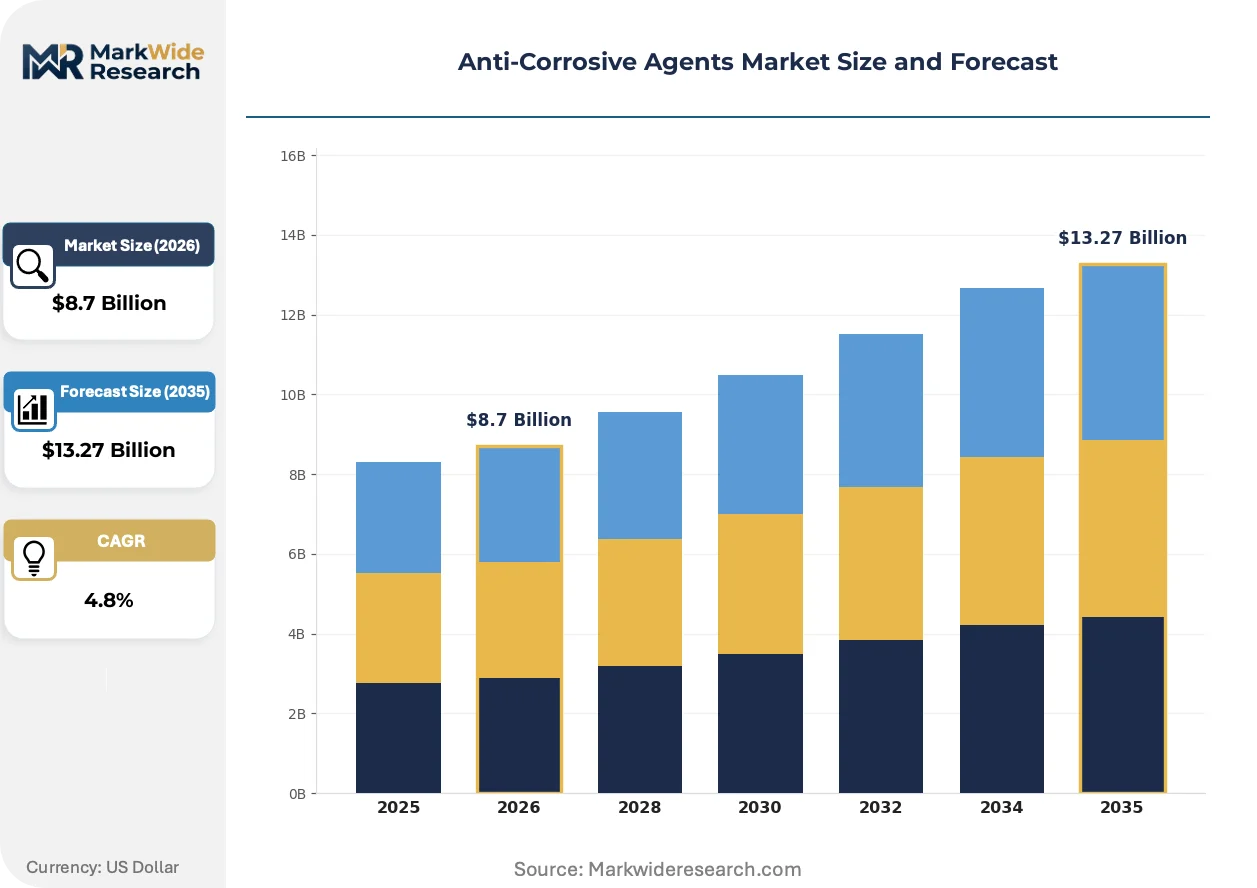
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation of chromate-based inhibitor portfolios, compressing R&D timelines while opening first-mover advantages for rare-earth and organic alternatives that satisfy both performance and toxicity thresholds.
Growth Catalysts
- Offshore wind buildout:North Sea turbine foundations and substation platforms require high-performance coating systems rated for splash-zone exposure, driving specification upgrades across marine-grade epoxy and polyurethane formulations.
- EPA chromate restrictions:The United States Environmental Protection Agency's tightening limits on hexavalent chromium in industrial coatings redirect procurement toward compliant inhibitor chemistries in aerospace and defense supply chains.
- Water-borne acrylic substitution:Automotive OEM paint shops in Germany and the United States accelerate conversion from solvent-borne systems to reduce VOC emissions and cut energy-intensive flash-off stages.
Market Restraints
- Raw material concentration:Strontium and cerium supply chains concentrate in Chinese processing facilities, exposing formulators to export quota volatility and price spikes for rare-earth corrosion inhibitors.
- Performance gaps in extreme service:Organic inhibitor packages still fail to match chromate passivation on aluminum alloys in salt-spray testing beyond 3,000 hours, limiting full substitution in military and aviation applications.
- REACH registration costs:European Chemicals Agency data requirements for new substance notifications impose six-figure compliance burdens on mid-scale specialty chemical producers, consolidating competitive position among larger registrants.
Strategic Opportunities
- Electronics vapor-phase protection:Cortec Corporation's VpCI film technology for semiconductor and circuit board packaging remains underexploited outside North American distribution, creating white space for channel expansion into Asian electronics manufacturing clusters.
- India industrial corridor buildout:The country's Production-Linked Incentive scheme for specialty chemicals supports domestic manufacturing of corrosion inhibitors for refinery and pipeline infrastructure along the Gujarat-Maharashtra belt.
- Marine biofouling convergence:Integration of silicone foul-release topcoats with anti-corrosive epoxy primers enables single-specification procurement for vessel operators facing both International Maritime Organization emissions rules and hull performance mandates.
Industry Challenges
- Formulation chemist scarcity:Expertise in electrochemical inhibitor mechanisms and polymer-coating compatibility has concentrated among retiring specialists, constraining product development velocity at mid-tier producers.
- Qualification timeline compression:Offshore wind project developers demand coating system warranties exceeding 25 years, forcing accelerated field-testing protocols that strain laboratory and pilot-scale validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Corrosive Agents Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Coatings, Inhibitors, Additives End User: Marine, Automotive, Industrial, Construction Formulation: Water-Based, Solvent-Based, Powder, Paste Application: Protective Coatings, Metal Treatment, Surface Preparation, Maintenance |
| Companies Covered | BASF SE, The Dow Chemical Company, Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Cortec Corporation, Nouryon, Ecolab, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Corrosive Agents Market Evolving Landscape
Coating system intelligence is migrating from passive barrier performance to active condition-monitoring integration, rewiring how asset owners specify protection packages and how suppliers structure service revenue.
Embedded sensor networks within protective coating systems is digitizing corrosion monitoring for offshore platforms and subsea pipelines. Oil majors operating North Sea assets now pilot real-time pH and chloride detection layers that transmit degradation signals to shore-based maintenance systems. This convergence of materials science and IoT infrastructure is compressing inspection intervals while enabling predictive recoating schedules that reduce unplanned downtime.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon propellants in spray-applied coating systems, forcing aerosol formulators toward compressed gas and mechanical pump alternatives. Industrial maintenance contractors in Germany and the Netherlands report 15-20% equipment replacement costs for compliant application gear. The restriction most affects touch-up and field repair segments where portable aerosol formats previously dominated accessibility.
Asset owners now unbundle coating specification from installation procurement, separating material supply from applicator selection to drive competitive bidding on labor while locking in certified product performance. This disintermediation concentrates purchasing power among EPC firms and major facility operators with in-house engineering competence. The pattern is most visible in German chemical processing and US Gulf Coast refining, where owner-operators maintain approved manufacturer lists independent of contractor relationships.
Anti-Corrosive Agents Market Segmentation
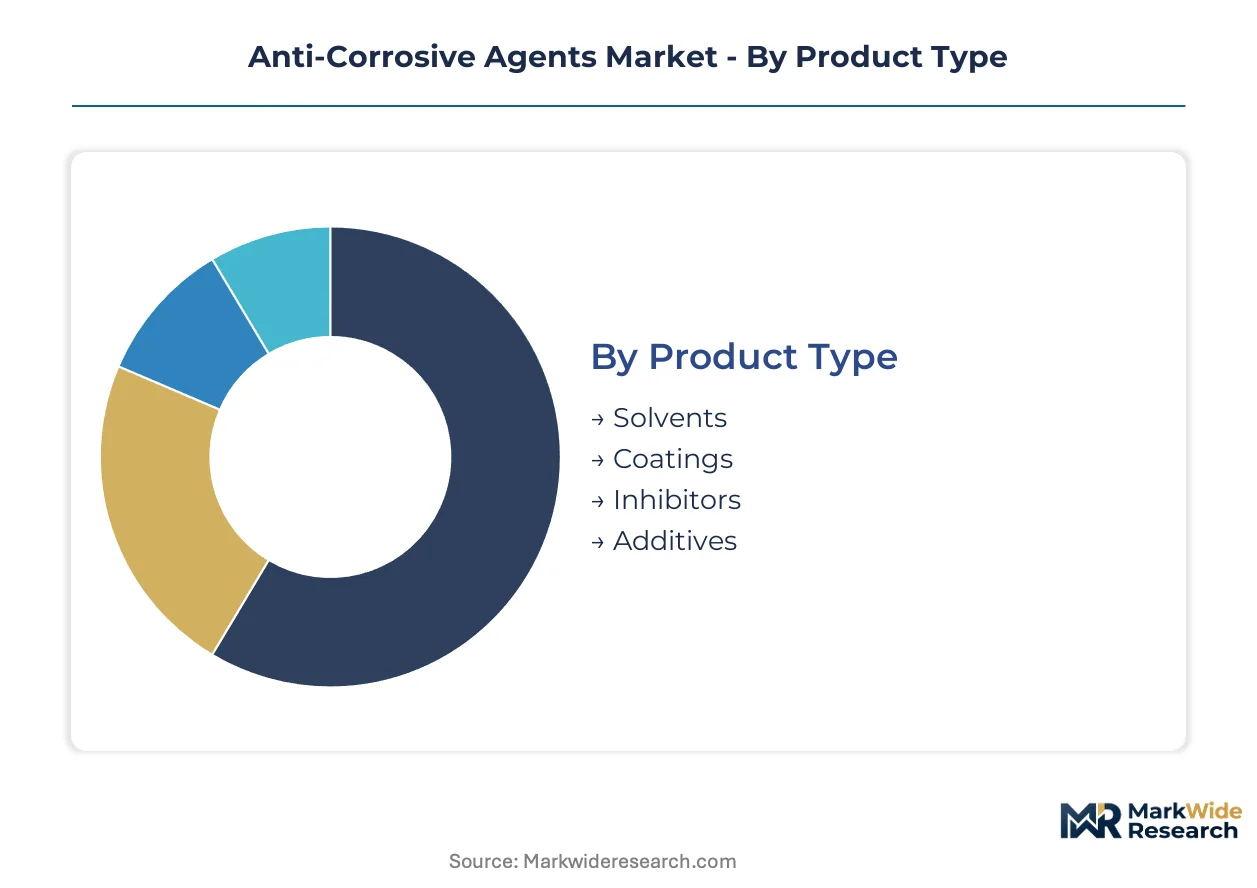
Anti-corrosive agents serve radically different duty cycles across product categories. Marine coating systems demand 25-year warranties while automotive pretreatment chemicals turn over with model-year procurement rhythms. Understanding these velocity differentials shapes inventory positioning and technical service allocation.
Product Type:
Coatings turn inventory slowest due to specification lock-in on major infrastructure projects, whereas additives and inhibitors rotate fastest through continuous process consumption in metalworking and chemical processing.
- Solvents:Hydrocarbon and oxygenated carrier fluids dissolve resin binders and control application viscosity in industrial maintenance coatings. Demand clusters in German chemical processing corridors where high-solids formulations reduce solvent loading per coat.
- Coatings:Epoxy, polyurethane, and zinc-rich film-forming systems create electrochemical barriers on steel substrates. Offshore wind foundations in the North Sea specify marine-grade epoxies rated for splash-zone exposure, driving premium formulation requirements.
- Inhibitors:Organic azoles and inorganic phosphates interrupt corrosion cell formation at the metal-electrolyte interface. Cooling water treatment in US Gulf Coast refineries consumes bulk volumes of molybdate and nitrite packages.
- Additives:Rheology modifiers, defoamers, and adhesion promoters optimize coating application properties. Automotive OEM paint shops specify low-VOC wetting agents to meet EPA emission thresholds without sacrificing edge coverage.
Coatings anchors the volume base while additives gains share at the steepest rate.
End User:
Cost tier differentiation separates project-based marine procurement from continuous automotive consumption patterns.
- Marine:Shipyard newbuild and repair specifications demand IMO-compliant coating systems with extended dry-dock intervals. Container lines and tanker operators concentrate procurement through approved manufacturer lists vetted by classification societies.
- Automotive:OEM assembly plants and tier supplier pretreatment lines consume phosphate conversion coatings and electrocoat primers in high-throughput immersion systems. German and US facilities lead water-borne technology conversion.
- Industrial:Refinery, pipeline, and power generation maintenance drives specification of high-temperature silicone and thermal-spray aluminum systems. Owner-operators unbundle material supply from contractor selection to compress total project cost.
- Construction:Bridge deck and rebar corrosion protection specifications vary by environmental exposure category. Infrastructure stimulus programs in India accelerate domestic inhibitor production for concrete admixture applications.
Industrial commands the largest revenue pool while automotive demonstrates the steepest technology substitution trajectory.
Formulation:
Supply concentration in water-borne resin intermediates is accelerating regional self-sufficiency programs.
- Water-Based:Acrylic and epoxy dispersions eliminate flammable solvent handling while reducing paint shop energy demand. German automotive OEMs specify these systems to meet TA Luft emission standards and cut flash-off stage duration.
- Solvent-Based:High-solids alkyds and two-component epoxies maintain film integrity under extreme chemical exposure. Marine and heavy industrial settings tolerate higher material costs and stricter handling protocols for superior barrier performance.
- Powder:Thermoset epoxy and polyester coatings eliminate liquid carrier entirely, achieving zero-VOC application on architectural metal and appliance components. Electrostatic spray lines in European manufacturing clusters drive specification.
- Paste:High-build, trowel-applied compounds fill weld seams and repair damaged coating systems in field maintenance. Offshore platform operators stock these materials for splash-zone touch-up between scheduled dry-dock periods.
Solvent-Based retains the widest installed base while Water-Based climbs the fastest.
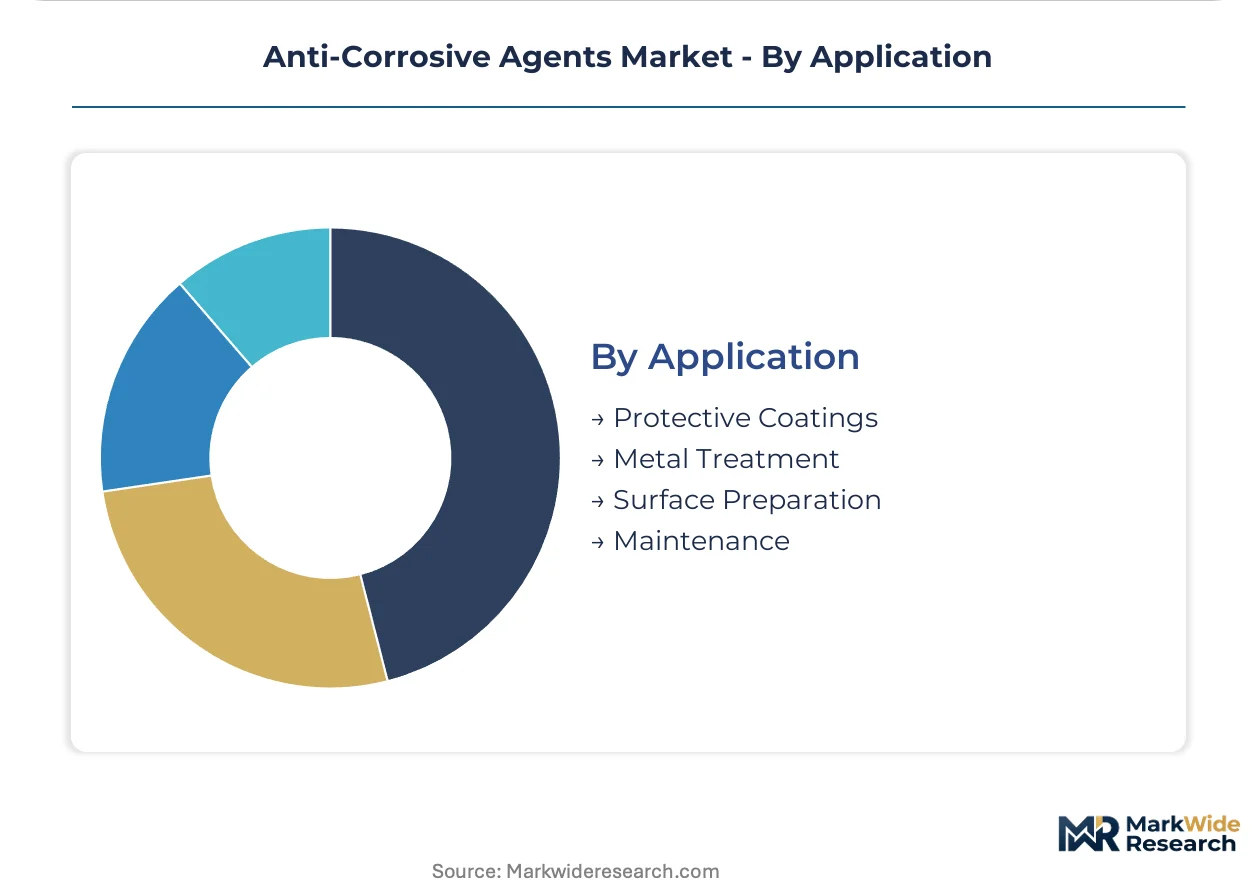
Application:
Customer type separation distinguishes asset owner specifications from contractor procurement behavior.
- Protective Coatings:Multi-layer systems combining zinc-rich primers, epoxy intermediates, and polyurethane topcoats defend structural steel in aggressive environments. North Sea offshore wind developers demand 25-year warranties on these specifications.
- Metal Treatment:Phosphate conversion, passivation, and anodizing processes prepare aluminum and steel substrates for subsequent coating adhesion. Aerospace supply chains specify these treatments to replace chromate technologies under EPA restrictions.
- Surface Preparation:Abrasive blasting, chemical degreasing, and profile-creation steps determine coating adhesion and service life. German industrial maintenance contractors absorb 15-20% equipment replacement costs to meet F-Gas Regulation compliance.
- Maintenance:Touch-up and repair materials extend asset life between full recoat cycles. Cortec Corporation's vapor-phase inhibitor films serve electronics packaging applications with minimal multinational competition.
Protective Coatings dominates current procurement volumes while Maintenance expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth processing capacity concentrates in Chinese refineries, exposing formulators elsewhere to export quota volatility. European REACH compliance and US EPA chromate restrictions are redirecting procurement toward compliant inhibitor chemistries. Industrial clusters in Germany, the US Gulf Coast, and India's western corridor anchor regional demand concentrations.
United States
Offshore wind lease auctions in the Atlantic and Gulf of Mexico drive specification of marine-grade coating systems for turbine foundations. EPA restrictions on hexavalent chromium redirect aerospace and defense supply chains toward rare-earth and organic inhibitor alternatives. Houston-area refineries and chemical plants consume bulk volumes of high-temperature silicone and thermal-spray aluminum systems for process equipment maintenance.
Germany
Automotive OEM paint shops in Stuttgart and Munich accelerate conversion from solvent-borne to water-borne acrylic systems to meet TA Luft emission standards. The F-Gas Regulation phases down hydrofluorocarbon propellants, forcing industrial maintenance contractors to absorb equipment replacement costs for compliant application gear. The Düsseldorf-Ruhr industrial corridor concentrates demand for protective coatings in chemical processing infrastructure.
China
GB standards enforced by the MEE restrict heavy-metal content in industrial coatings, creating compliance costs for exporters while opening local supply advantages for domestic producers. Strontium and cerium supply chains concentrate in Chinese processing facilities, exposing international formulators to price spikes for rare-earth corrosion inhibitors. Yangtze River Delta shipyards specify IMO-compliant coating systems with extended dry-dock intervals for container and tanker newbuilds.
India
The Production-Linked Incentive scheme for specialty chemicals supports domestic manufacturing of corrosion inhibitors for refinery and pipeline infrastructure. Infrastructure stimulus programs accelerate domestic inhibitor production for concrete admixture applications in bridge deck and rebar corrosion protection. The Gujarat-Maharashtra industrial belt concentrates demand from petrochemical complexes and port facilities requiring splash-zone coating systems.
United Kingdom
North Sea offshore platform operators pilot embedded sensor networks within protective coating systems for real-time corrosion monitoring. Decommissioning schedules for aging oil and gas assets drive maintenance chemical consumption through extended field life programs. Aberdeen and Scottish coastal clusters anchor specification expertise for subsea pipeline protection and splash-zone coating warranties exceeding 25 years.
Anti-Corrosive Agents Market Competitive Landscape
Integrated chemical conglomerates and specialized coating formulators split the market along technology sophistication and service intensity vectors. The vendor base concentrates among multinational resin producers with captive intermediate supply, mid-scale regional formulators with applicator relationships, and niche technology specialists with proprietary inhibitor mechanisms. Scale-driven players leverage backward integration into key raw materials, while specialists defend position through formulation expertise and qualified product lists. Geographic expansion and portfolio diversification toward water-borne and compliant chemistries represent dominant competitive moves.
Within the integrated chemical tier, BASF SE and The Dow Chemical Company exemplify archetypes combining resin intermediate production with downstream formulation capabilities. Cortec Corporation occupies a position among vapor-phase corrosion inhibitor specialists where few multinationals compete. These three entities represent the strategic spectrum from scale-driven integrated supply to technology-specialized niche protection.
| Leading Market Players |
|---|
| BASF SE |
| The Dow Chemical Company |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Cortec Corporation |
| Nouryon |
| Ecolab |
| Ashland |
| Others |
Value Network & Pricing Analysis
Chinese strontium and cerium processing concentration anchors upstream pricing power for rare-earth corrosion inhibitors, shifting margin capture toward formulators with captive mineral sourcing or long-term offtake agreements with Yangtze River Delta refineries.
Pricing Analysis
Aftermarket service contracts and extended warranty packages now drive lifetime value capture for coating system suppliers. Three-tier pricing structure across certified marine-grade, industrial-standard, and economy maintenance tiers reflects performance warranty duration and applicator certification level. Cost compression in economy-grade solvent-based formulations is intensifying because of feedstock volatility in epoxy resin intermediates. Automotive OEMs demonstrate the highest price sensitivity due to paint-shop energy efficiency mandates, while offshore wind developers accept premium positioning for 25-year warranted splash-zone systems.
Supply Chain Analysis
Tariff exposure between China and Western coating formulators dominates supply chain risk planning for rare-earth inhibitor sourcing. Manufacturing concentration clusters in China, Germany, and the United States, with formulation depending on strontium carbonate, cerium oxide, and water-borne acrylic resin intermediates. Single-source vulnerability persists for vapor-phase corrosion inhibitor film substrates sourced through limited North American specialty polymer channels. Distribution runs through authorized applicator networks and direct EPC contractor procurement rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against rare-earth and organic inhibitor technologies displacing legacy chromate passivation in aerospace and defense specifications.
For Market Incumbents:Pre-empt chromate substitution by accelerating rare-earth inhibitor qualification with Airbus and Boeing supply chains before EPA restrictions harden. Backward integration into cerium oxide processing through joint ventures with Chinese refineries secures feedstock margin control against export quota volatility.
For New Entrants and Emerging Players:Establish a beachhead in vapor-phase corrosion inhibitor films for Asian electronics manufacturing clusters where Cortec's distribution remains underdeveloped. India's Production-Linked Incentive scheme for specialty chemicals offers the most penetrable entry point, with domestic refinery infrastructure buildout creating qualified supplier list vacancies for compliant inhibitor formulators.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across water-borne resin intermediate production as European F-Gas Regulation compliance forces equipment replacement cycles. Acquisition targets should prioritize mid-scale German formulators with TA Luft-certified water-borne technology and existing automotive OEM approved manufacturer status. The signal to watch is REACH registration cost burden consolidation forcing smaller European specialty chemical producers toward distressed sale scenarios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive cerium oxide supply from Chinese refineries insulates margin against export quota volatility. |
| Water-Borne Technology Conversion | Automotive OEM paint shops in Germany specify these systems to meet TA Luft emission standards. |
| Vapor-Phase Inhibitor Channel Expansion | Asian electronics manufacturing clusters remain underexploited by existing North American distribution. |
| Embedded Sensor Network Integration | North Sea offshore operators pilot real-time pH detection layers for predictive maintenance contracts. |
| REACH-Compliant Formulation Portfolio | ECHA data requirements consolidate competitive position among larger registrants with six-figure compliance capacity. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA registration databases preceded structured interviews with coating formulator R&D directors, automotive OEM paint shop engineers, offshore wind EPC procurement leads, and industrial maintenance contractor operations managers. Primary fieldwork captured specification behavior across marine, automotive, and industrial end-use segments. Secondary validation drew from ACC and Cefic industry reports, customs export data for rare-earth oxide categories, and bottom-up triangulation against top-down market sizing from resin intermediate consumption trends.
Assumptions around REACH compliance timeline enforcement and EPA chromate restriction implementation were held fixed, while offshore wind capacity buildout pace and rare-earth export quota volatility were stress-tested across sensitivity bands. The analytical framework modeled volume and value across formulation type, end-use industry, and regional production hub throughout the forecast period. CAGRs were derived from segment-level elasticity modeling against industrial capital expenditure cycles and coating system specification renewal rates. Forecast inputs included marine newbuild orderbook data, automotive OEM paint shop conversion timelines, and refinery maintenance turnaround schedules.
Stress conditions across strontium and cerium price volatility, REACH registration cost inflation, and offshore wind project development delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers centered on regulatory enforcement acceleration or rare-earth processing capacity expansion outside China. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
South America Starch Derivatives Market