
 Process Chromatography Market | 2026-2036
Process Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Process Chromatography Market Outlook
Equipment leasing and performance-based service contracts are narrowing the capital barrier for mid-tier biotechnology firms entering commercial manufacturing. Danaher Corporation leverages its Pall Life Sciences integration to sustain integrated filtration-chromatography workflows. Thermo Fisher Scientific anchors its position through captive resin production and global distribution infrastructure. Sartorius AG competes with single-use chromatography skids that reduce facility footprint and cleaning validation burden.
Process chromatography employs stationary-phase media packed into columns to separate biomolecules by differential affinity, with typical resin particle sizes ranging from 20 to 100 micrometers and operating pressures up to 10 bar in preparative protein purification. Liquid chromatography dominates installed base value due to its indispensability in monoclonal antibody polishing steps, while affinity chromatography commands premium pricing through Protein A resin consumables that constitute the largest recurring spend category. Biopharmaceutical applications absorb the majority of resin and system demand as contract development and manufacturing organizations scale multi-product facilities.
FDA guidance on process validation and ICH Q5A-Q5D standards dictate viral clearance demonstration requirements that directly determine chromatography train design and resin selection for mammalian cell-derived products. EMA's Annex 1 revisions on sterile manufacturing and China's NMPA alignment with PIC/S GMP standards are elevating documentation and qualification burdens for chromatography system suppliers. Stakeholders must evaluate resin lifetime claims against actual cycling data under variable feedstream conditions before committing to multi-year supply agreements.
Market Dynamics
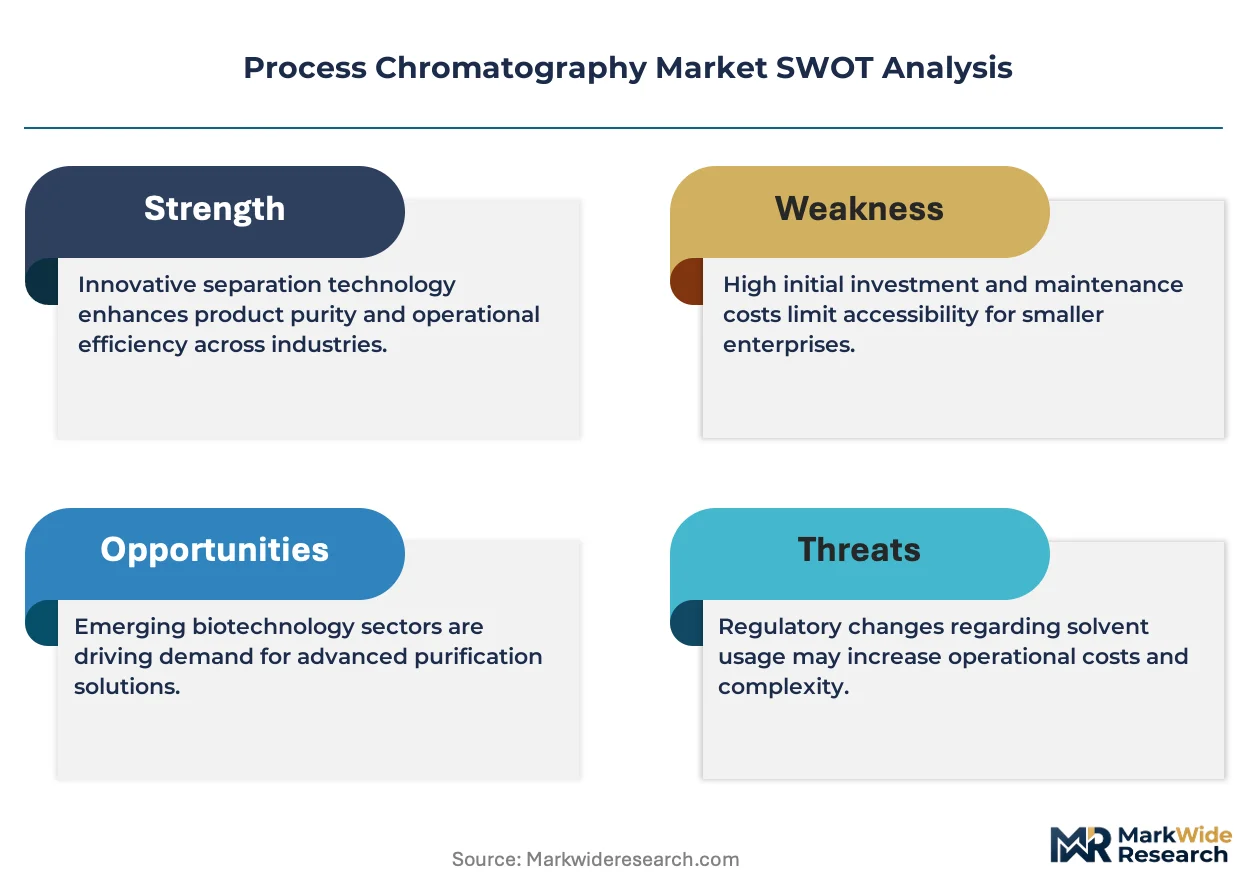
Single-use chromatography systems are compressing facility qualification timelines and displacing stainless-steel infrastructure across mammalian cell culture facilities, while continuous processing architectures reframe resin utilization economics for multi-product biomanufacturing.
Growth Catalysts
- Monoclonal antibody pipeline expansion:Therapeutic protein developers in the United States, Germany, and China are commissioning additional purification trains to accommodate Phase III and commercial launch volumes.
- FDA process validation guidance:The agency's lifecycle approach to process validation mandates documented viral clearance studies that embed chromatography steps as critical control points.
- Protein A resin cycling advances:Improved alkaline-stable ligand chemistries extend resin functional lifetime, reducing consumable cost per gram of purified antibody.
Market Restraints
- Agarose base matrix supply concentration:Three suppliers control high-purity cross-linked agarose production, creating input vulnerability for affinity resin manufacturers.
- EMA Annex 1 sterile manufacturing revisions:The updated guidance imposes closed-system requirements that retrofit costs onto legacy batch chromatography installations.
- Membrane chromatography substitution:Flow-through polishing membranes capture selected impurity classes with lower buffer consumption than packed-bed alternatives.
Strategic Opportunities
- Gene therapy vector purification:AAV and lentivirus manufacturing lacks standardized chromatography platforms, opening white space for resin and membrane developers.
- India's PLI scheme for biopharmaceuticals:Production-linked incentives attract CDMO investment that requires imported chromatography systems and resins.
- Continuous chromatography-mass spectrometry integration:Real-time product quality attribute monitoring enables dynamic process control and reduced hold times.
Industry Challenges
- Process analytical technology implementation:Biomanufacturers struggle to validate chromatographic peak identification algorithms for real-time release testing under FDA scrutiny.
- Resin lot-to-lot variability management:Ligand density fluctuations across manufacturing campaigns force extended requalification protocols that compress effective production windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Chromatography Market |
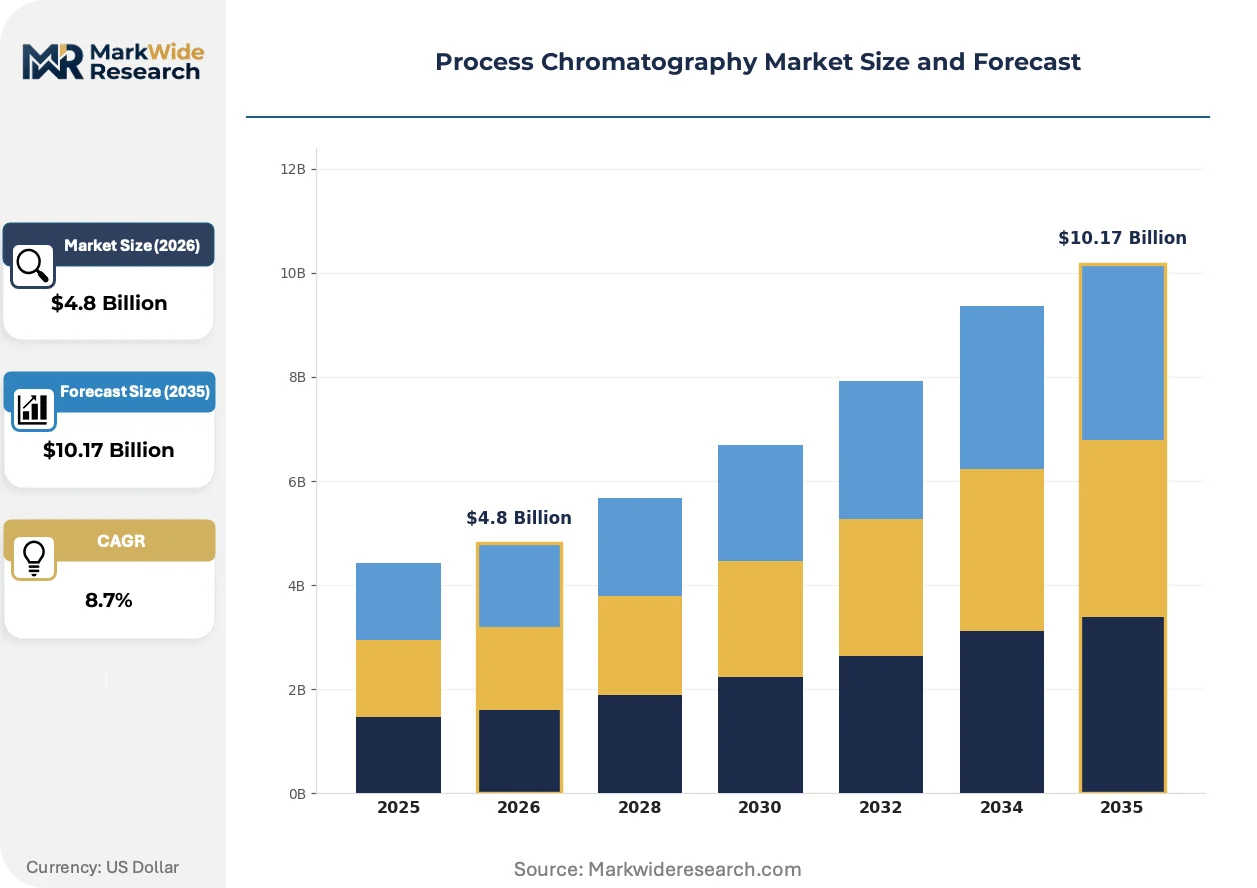
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chromatography, Gas Chromatography, Flash Chromatography, Supercritical Fluid Chromatography Application: Biopharmaceuticals, Food & Beverage, Environmental Testing, Chemical Synthesis End User: Pharmaceutical Companies, Academic Research Institutions, Biotechnology Firms, Quality Control Labs Technology: High-Performance Liquid Chromatography, Ion Chromatography, Preparative Chromatography, Affinity Chromatography |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Bio-Rad Laboratories Inc., Agilent Technologies, Danaher Corporation, Waters Corporation, GE Healthcare, Shimadzu Corporation, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Chromatography Market Strategic Shifts
Process chromatography is fragmenting across three simultaneous vectors: hardware disposability, control system digitization, and service model unbundling. These shifts compress capital deployment cycles while elevating consumable and software attach rates.
Multicolumn countercurrent chromatography is migrating from pilot-scale demonstration to commercial GMP deployment. Contract manufacturers with high-volume monoclonal antibody portfolios are installing periodic counter-current systems that reduce resin inventory by sixty percent versus batch capture. This hardware transition is compressing cost structures for biosimilar producers competing on COGS.
EMA's Annex 1 sterile manufacturing revisions are mandating closed-system architecture for aseptic processing steps. Chromatography skid suppliers are integrating disposable flow paths and sealed column housings to eliminate open manipulations. European biomanufacturers are prioritizing these configurations for new facility builds, while retrofitting legacy stainless-steel trains to meet compliance deadlines.
CDMOs are unbundling equipment ownership from operational expertise. Performance-based service contracts now cover resin lifetime optimization, column packing validation, and regulatory documentation support. This procurement model shift is concentrating vendor relationships among mid-tier biotechnology firms in the United States and Germany that lack in-house purification development capabilities.
Process Chromatography Market Segmentation
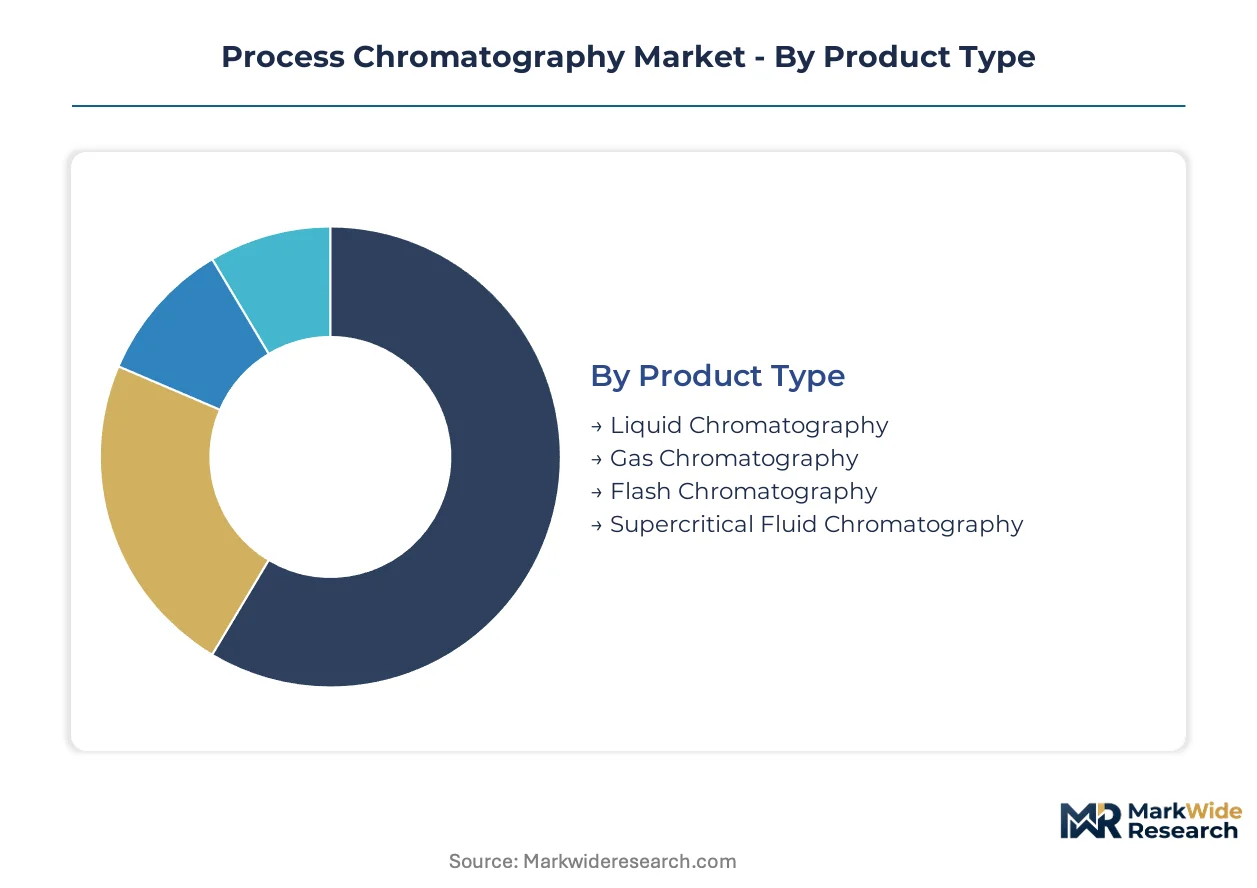
Chromatography system selection cascades through facility design, consumable economics, and regulatory compliance pathways. Segmentation reveals how purification modality, application intensity, and end-user scale determine vendor engagement models and technology roadmaps.
Product Type:
Liquid systems dominate therapeutic protein manufacturing, while gas and specialized modalities serve analytical and preparative niches across the value chain.
- Liquid Chromatography:Stationary-phase media packed into columns separate biomolecules by differential affinity, with resin particle sizes from 20 to 100 micrometers and operating pressures up to 10 bar. Monoclonal antibody polishing steps in United States and German GMP facilities absorb the majority of installed base value, driven by FDA and EMA viral clearance mandates that embed liquid chromatography as a critical control point.
- Gas Chromatography:Volatile compound separation employs capillary or packed columns with thermal conductivity or flame ionization detection. Environmental testing laboratories in China deploy these systems for residual solvent analysis under NMPA-aligned PIC/S GMP standards, with demand concentrating in industrial quality control applications.
- Flash Chromatography:Rapid preparative purification for synthetic chemistry intermediates.
- Supercritical Fluid Chromatography:Carbon dioxide-based mobile phase systems for chiral separations.
The dominant share belongs to Liquid Chromatography, while Affinity Chromatography (within technology segmentation) is closing the gap fastest through Protein A resin premiumization.
Application:
Application intensity correlates directly with regulatory burden and consumable throughput, creating divergent margin profiles across customer segments.
- Biopharmaceuticals:Therapeutic protein developers commission multi-column purification trains for Phase III and commercial launch volumes. United States manufacturers face FDA lifecycle process validation requirements that document viral clearance studies, while German facilities navigate EMA Annex 1 sterile manufacturing revisions mandating closed-system architectures.
- Food & Beverage:Contaminant detection and nutritional profiling for safety compliance.
- Environmental Testing:Pollutant quantification and regulatory monitoring applications.
- Chemical Synthesis:Reaction monitoring and impurity isolation for pharmaceutical intermediates.
Biopharmaceuticals commands the largest revenue pool, with Environmental Testing expanding most quickly under tightening emissions and water quality frameworks.
End User:
End-user scale determines procurement modality, from capital equipment purchases to performance-based service contracts.
- Pharmaceutical Companies:Integrated manufacturing organizations with captive purification development capabilities.
- Academic Research Institutions:Method development and fundamental separation science funding.
- Biotechnology Firms:Mid-tier developers in the United States and Germany are narrowing capital barriers through equipment leasing and resin lifetime optimization contracts. These firms lack in-house purification expertise, concentrating vendor relationships among CDMOs offering regulatory documentation support.
- Quality Control Labs:Release testing and stability monitoring for commercial product batches.
Pharmaceutical Companies retain the dominant installed base, though Biotechnology Firms are gaining share fastest via unbundled procurement models.
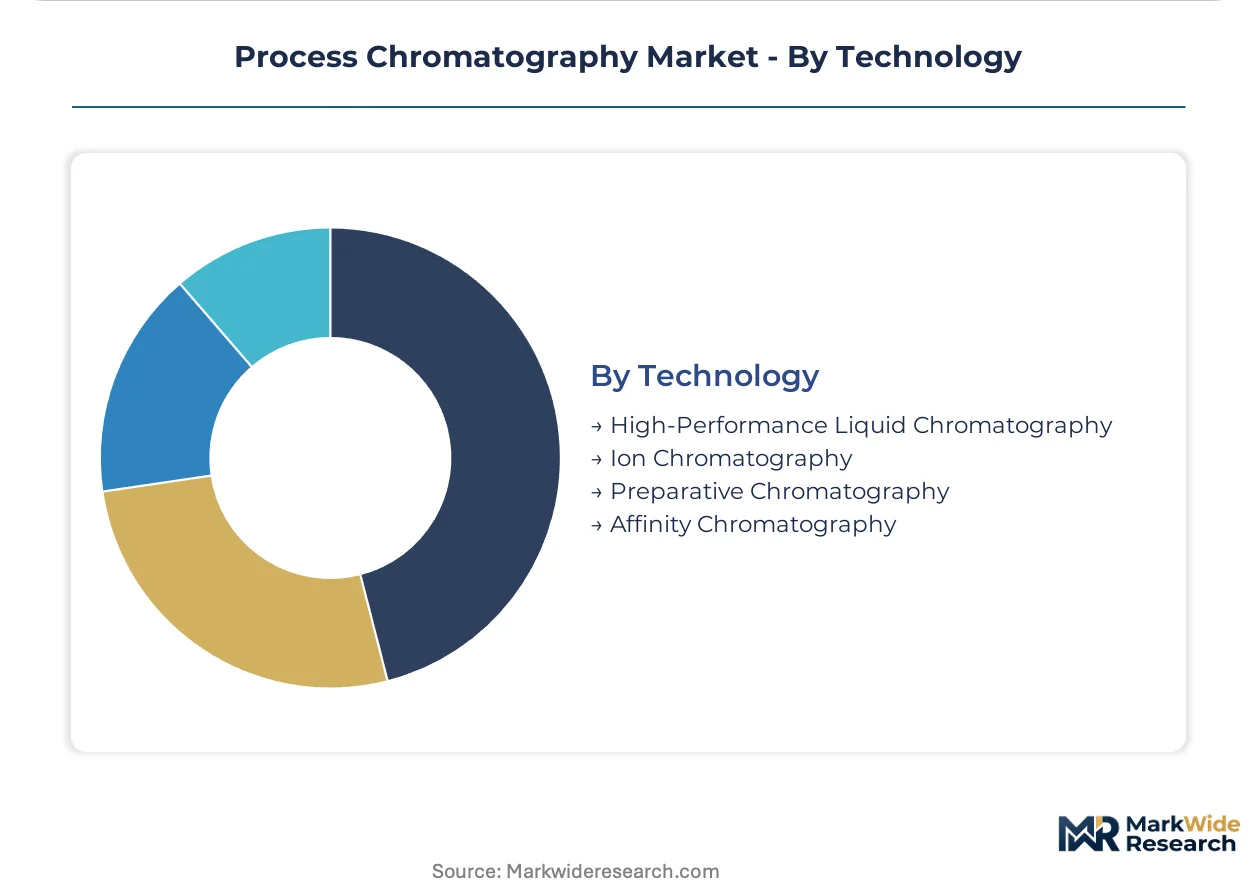
Technology:
Technology selection frames resin utilization economics and real-time process control capabilities.
- High-Performance Liquid Chromatography:Analytical and preparative separations with pressure-rated hardware.
- Ion Chromatography:Charged species analysis for inorganic and organic ion detection.
- Preparative Chromatography:Large-scale purification with multicolumn countercurrent architectures. CDMOs with high-volume monoclonal antibody portfolios in China are installing periodic counter-current systems that reduce resin inventory versus batch capture, compressing cost structures for biosimilar producers.
- Affinity Chromatography:Biospecific ligand-protein interactions, with Protein A resins constituting the largest recurring spend category. Improved alkaline-stable ligand chemistries extend functional lifetime, reducing consumable cost per gram of purified antibody in mammalian cell culture facilities.
Affinity Chromatography captures the premium pricing tier, while Preparative Chromatography climbs the fastest through continuous processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-purity agarose base matrices concentrates supply risk in three manufacturing clusters. Export flows of Protein A resins and single-use chromatography systems track biopharmaceutical production capacity expansion in regulated markets.
United States
Monoclonal antibody pipeline expansion drives purification train commissioning for Phase III and commercial volumes. FDA lifecycle process validation guidance mandates documented viral clearance studies that embed chromatography as critical control points. The Greater Boston and San Francisco Bay Area clusters host CDMOs scaling multi-product facilities with integrated filtration-chromatography workflows.
Germany
EMA Annex 1 sterile manufacturing revisions mandate closed-system architectures for aseptic processing steps. Heidelberg and Munich industrial zones concentrate CDMO investment in single-use chromatography skids that reduce facility footprint and cleaning validation burden. German biomanufacturers prioritize disposable flow paths for new facility builds while retrofitting legacy stainless-steel trains.
China
Biosimilar producers compete on COGS through periodic counter-current system installations that reduce resin inventory versus batch capture. NMPA alignment with PIC/S GMP standards elevates documentation and qualification burdens for chromatography system suppliers. The Yangtze River Delta biomanufacturing corridor absorbs the majority of imported preparative chromatography systems for mammalian cell culture facilities.
India
Production-linked incentive schemes for biopharmaceuticals attract CDMO investment requiring imported chromatography systems and resins. The country's national pharmaceutical regulator enforces viral clearance demonstration requirements for therapeutic protein separations. Hyderabad and Bengaluru biotechnology clusters concentrate mid-tier developers entering commercial manufacturing through equipment leasing contracts.
Switzerland
Swissmedic oversight of therapeutic protein manufacturing elevates resin lifetime validation requirements under variable feedstream conditions. Basel and Zurich host contract manufacturers with high-volume monoclonal antibody portfolios installing multicolumn countercurrent chromatography at commercial GMP scale. Swiss facilities lead European adoption of continuous chromatography-mass spectrometry integration for real-time product quality attribute monitoring.
Process Chromatography Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and membrane supply. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with captive filtration-chromatography workflows, pure-play chromatography system specialists emphasizing single-use architectures, and consumables-focused suppliers controlling agarose matrix production. Competitive moves concentrate on backward integration into resin manufacturing and geographic expansion through regional distribution infrastructure.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific exemplify platform integration strategies. Sartorius AG occupies a position among European specialists advancing single-use chromatography skids. These three anchors represent distinct approaches to narrowing capital barriers for mid-tier biotechnology firms through unbundled procurement models spanning equipment leasing, resin lifetime optimization, and regulatory documentation support.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Bio-Rad Laboratories Inc. |
| Agilent Technologies |
| Danaher Corporation |
| Waters Corporation |
| GE Healthcare |
| Shimadzu Corporation |
| Sartorius AG |
| Others |
Value Chain & Pricing Dynamics
Heidelberg's industrial zone concentrates single-use chromatography skid manufacturing capacity, with three German suppliers controlling proprietary agarose base matrix production that feeds downstream Protein A resin pricing power across European and North American biopharmaceutical markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in resin volume commitments across multi-year supply agreements. Price differentiation rests on GMP certification tier and after-sales service bundling, with FDA-validated resins commanding substantial premiums over research-grade alternatives. Cost compression in biosimilar manufacturing is intensifying because Chinese producers deploy periodic counter-current systems that slash resin inventory requirements. Biotechnology firms with leased equipment arrangements exhibit highest price sensitivity, while integrated pharmaceutical manufacturers with captive purification capabilities demonstrate lowest sensitivity due to volume scale.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for chromatography system importers navigating NMPA alignment requirements. High-purity cross-linked agarose production concentrates in Sweden, Germany, and Japan, with downstream Protein A ligand chemistry development drawing from specialized biotechnology inputs in Switzerland and the United States. Single-source vulnerability pervades agarose base matrix supply, where three manufacturers control critical input availability for affinity resin producers. Distribution runs through authorized distributor networks serving CDMO clusters in the Greater Boston, San Francisco Bay Area, and Yangtze River Delta biomanufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane chromatography substitution threatens incumbent packed-bed resin economics, compelling traditional suppliers to defend value through integrated workflow offerings and continuous processing architectures that preserve consumable attach rates.
For Market Incumbents: Build regulatory documentation moats by embedding viral clearance validation support into resin lifetime service contracts, defending against emerging membrane chromatography entrants capturing flow-through polishing applications. Backward integration into agarose base matrix production secures input cost control against Swedish and German supply concentration. Capacity addition in China's Yangtze River Delta biomanufacturing corridor captures biosimilar producer demand for periodic counter-current system deployments. For New Entrants and Emerging Players: Establish a beachhead in gene therapy vector purification, where AAV and lentivirus manufacturing lacks standardized chromatography platforms and incumbent Protein A resin portfolios hold minimal relevance. India's PLI scheme for biopharmaceuticals attracts CDMO investment requiring imported systems and resins, presenting the most penetrable geography for equipment leasing models. A go-to-market angle emphasizing performance-based service contracts with resin lifetime optimization narrows capital barriers for mid-tier biotechnology firms lacking in-house purification expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumables-focused suppliers controlling agarose matrix production and Protein A ligand chemistries, with service contract attach rates providing visibility across the projection horizon. Acquisition targets should display captive resin manufacturing capabilities and established relationships with CDMOs scaling multi-product facilities. The signal to watch is EMA Annex 1 compliance deadline acceleration, which forces European biomanufacturers into retrofit or replacement cycles for legacy stainless-steel chromatography trains.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Lifetime Optimization Service Contracts | CDMOs in Germany and the United States outsource purification expertise through unbundled procurement models. |
| Continuous Chromatography Platform Deployment | Periodic counter-current systems reduce resin inventory by sixty percent versus batch capture in Chinese biosimilar facilities. |
| Backward Integration into Agarose Matrix Production | Captive supply of high-purity cross-linked agarose mitigates input vulnerability from Swedish and German concentration. |
| Gene Therapy Vector Purification Platform Development | AAV and lentivirus manufacturing lacks standardized chromatography platforms, opening white space for specialized resin developers. |
| EMA Annex 1 Closed-System Architecture Certification | European biomanufacturers prioritize disposable flow paths and sealed column housings for new facility builds and retrofits. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with biopharmaceutical process development executives, regulatory affairs leads at CDMOs, resin procurement managers, and chromatography system engineering directors; and secondary validation through FDA guidance documents, EMA Annex 1 revisions, NMPA PIC/S GMP alignment notices, and SEC 10-K filings from diversified life science conglomerates. Bottom-up triangulation against resin cycling data under variable feedstream conditions and top-down cross-checks against biopharmaceutical purification capacity expansion announcements ensured analytical consistency.
Forecast inputs considered technology segmentation across affinity, ion exchange, and preparative modalities; application intensity spanning monoclonal antibody, gene therapy vector, and biosimilar manufacturing; and end-user scale from integrated pharmaceutical companies to mid-tier biotechnology firms leasing equipment. CAGRs were derived through regression analysis of historical resin consumption patterns and projected biopharmaceutical pipeline advancement across the analysis window. Industry-specific inputs included Protein A resin functional lifetime improvements from alkaline-stable ligand chemistries and continuous processing adoption rates in contract manufacturing organizations.
Stress conditions across agarose base matrix supply disruption, EMA Annex 1 compliance timeline acceleration, and membrane chromatography substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory documentation burden stability and CDMO multi-product facility commissioning rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Hydrogenated Bisphenol a Market