
 Drum Melters Market | 2026-2036
Drum Melters Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Melters Market Foresight
Buyer concentration among industrial manufacturers is restructuring as mid-tier packaging firms consolidate procurement while specialty chemical processors fragment across regional hubs. Nordson Corporation leverages its adhesive dispensing integration to sustain technology leadership in precision temperature control systems. Graco Inc. anchors North American manufacturing scale through extensive distributor networks and field service infrastructure. Illinois Tool Works competes across multiple end-use verticals through ITW Dynatec's specialized hot melt equipment division.
Drum melters are industrial heating vessels designed to liquefy solid or semi-solid materials—typically hot melt adhesives, sealants, or coatings—through controlled thermal transfer, operating at precise temperature ranges with insulated drum jackets and pumped discharge systems. Electric drum melters dominate installed base volumes due to cleaner emissions profiles and tighter temperature uniformity, while hybrid configurations gain traction in facilities pursuing dual-fuel redundancy. Large capacity units command margin concentration in chemical plant and recycling process applications where batch throughput directly determines operational economics.
EPA emissions standards and OSHA thermal hazard protocols shape equipment design mandates, forcing manufacturers to integrate redundant temperature limiters and exhaust capture systems. CE marking under EU machinery directives and REACH chemical compliance requirements govern European market access for drum melters processing solvent-bearing formulations. Stakeholders must monitor evolving carbon border adjustments and regional energy price spreads when configuring electric versus gas-powered portfolios.
Market Dynamics
EPA emissions guidelines and OSHA thermal safety rules are forcing drum melter manufacturers to redesign heating systems around redundant temperature limiters and exhaust capture integration, compressing equipment replacement cycles among packaging automation clusters.
Growth Catalysts
- REACH chemical compliance:European adhesive formulators are upgrading to sealed-system drum melters to meet solvent-handling mandates, accelerating equipment turnover in Germany's R&D centers.
- Packaging automation clusters:Mid-tier packaging firms in industrial manufacturing hubs are consolidating procurement around precision temperature control systems to reduce batch variability.
- Hot melt adhesive specifications:Tighter viscosity tolerances in automotive and electronics assembly are pulling demand toward pumped discharge systems with insulated drum jackets.
Market Restraints
- Stainless steel input volatility:Drum jacket fabrication depends on nickel-alloy sheet metal, exposing manufacturers to commodity price swings that compress margin predictability.
- Electric heating element supply concentration:Ceramic and mica-wound resistor sourcing concentrates in East Asian component suppliers, creating single-source vulnerability for Western equipment builders.
- Gas-powered redundancy limitations:Hybrid configurations face permitting friction under local air quality districts, restricting deployment flexibility in California and Northeast US manufacturing zones.
Strategic Opportunities
- Chemical recycling feedstock preparation:Drum melters configured for post-industrial adhesive recovery are penetrating plastics reprocessing facilities seeking batch liquefaction of contaminated polymer streams.
- India's PLI scheme for packaging machinery:Domestic adhesive equipment subsidies are opening localized production pathways for mid-capacity electric units serving South Asian contract manufacturers.
- IoT-enabled predictive maintenance:Convergence of temperature telemetry with cloud-based asset management is creating subscription revenue streams alongside hardware sales.
Industry Challenges
- Thermal systems engineering talent scarcity:Qualified technicians for heat transfer optimization and control loop tuning are concentrated among aging specialist workforces in Midwest US and Rhineland industrial regions.
- CE marking timeline compression:EU machinery directive certification for solvent-bearing configurations requires extended third-party validation cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Melters Market |
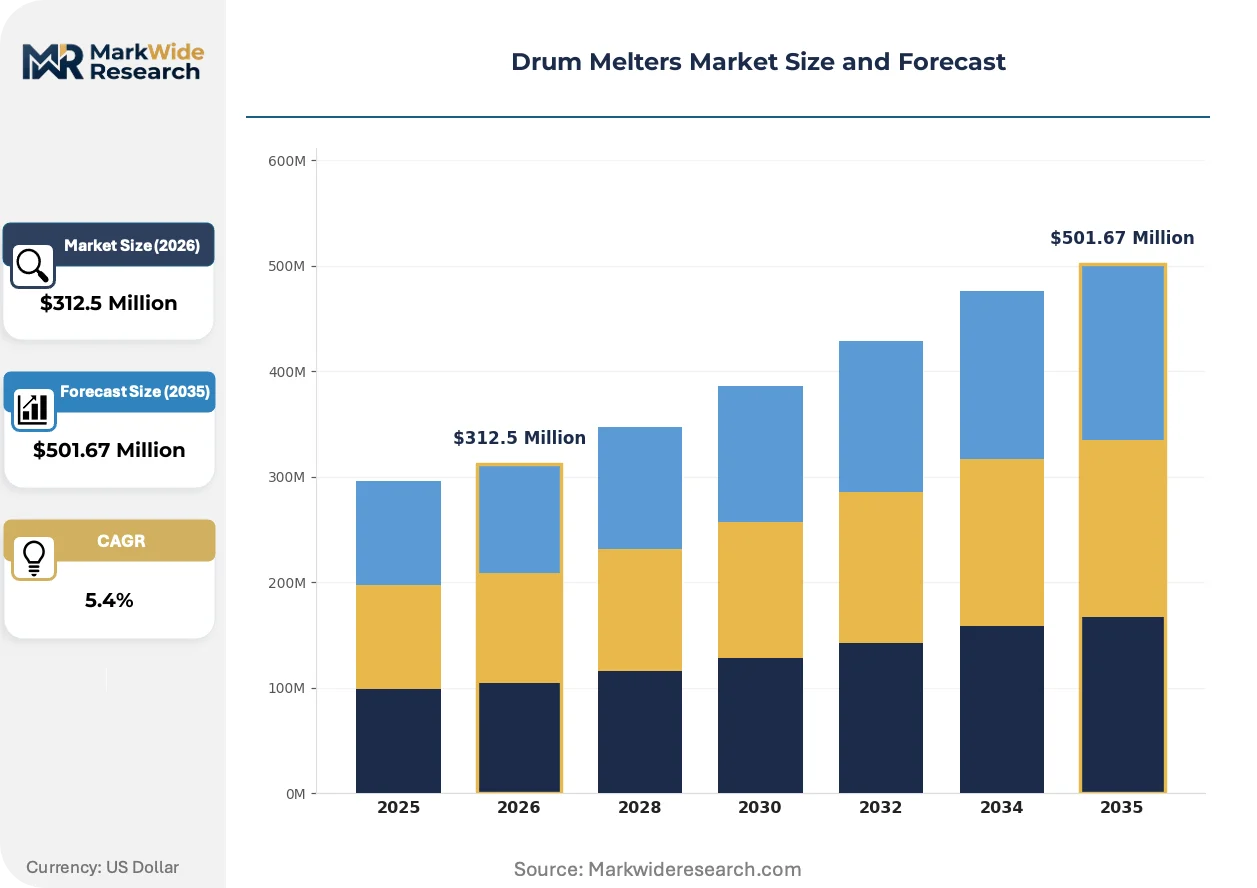
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Drum Melters, Gas-Powered Drum Melters, Hybrid Drum Melters, Manual Drum Melters End User: Industrial Manufacturers, Food Processing, Chemical Plants, Construction Industry Capacity: Small Capacity, Medium Capacity, Large Capacity, Extra-Large Capacity Application: Hot Melt Adhesives, Coatings, Sealants, Recycling Processes |
| Companies Covered | Nordson Corporation, Graco Inc., Illinois Tool Works, Valco Melton, BÜHNEN GmbH & Co. KG, Meler, ITW Dynatec, Robatech, SM Klebetechnik Vertriebs-GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Melters Market Shifts & Advancements
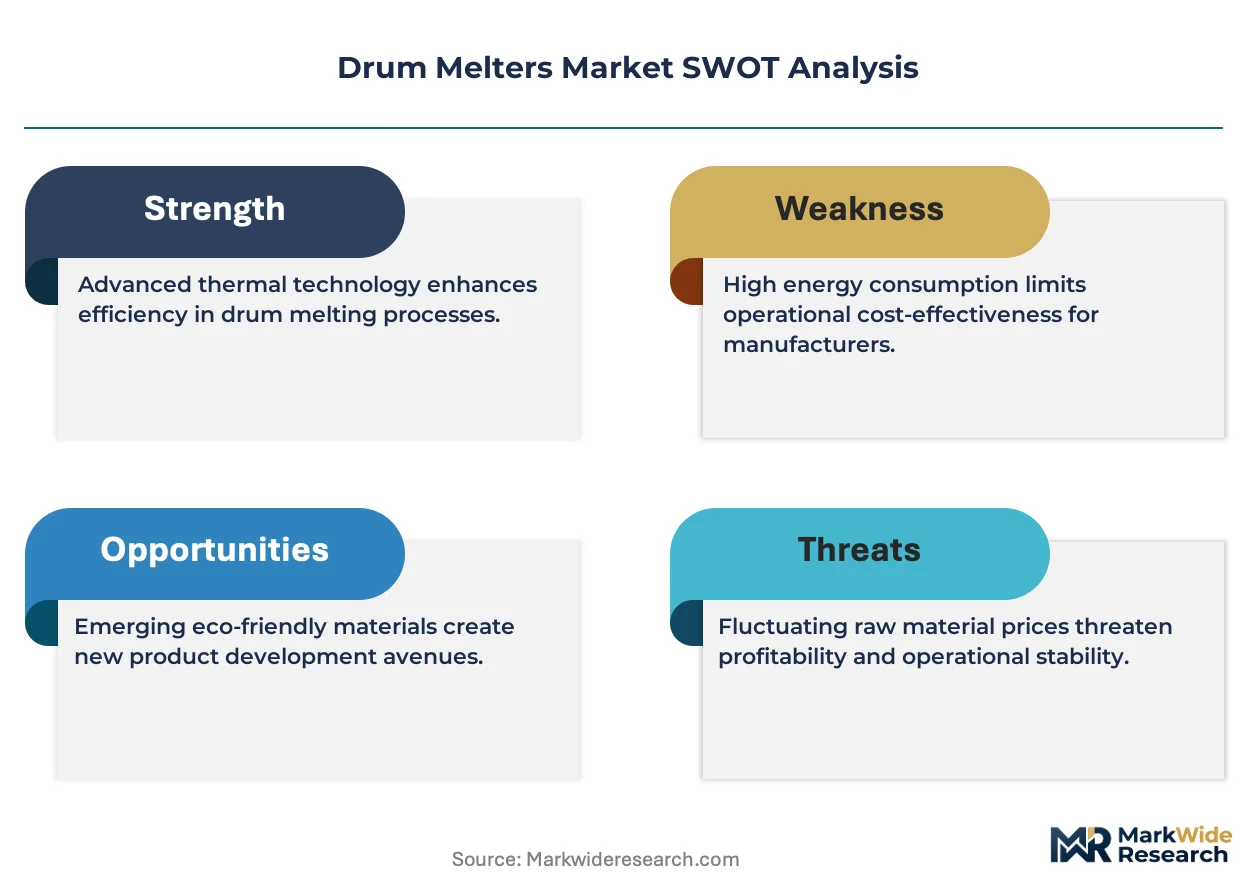
Precision temperature control architectures are displacing conventional on-off heating cycles, while regulatory pressure on thermal emissions accelerates sealed-system redesigns across adhesive processing equipment.
Induction heating elements are integrating into drum melter base designs to replace resistive coil systems, delivering faster thermal ramp rates and improved energy efficiency. Automotive tier-one adhesive applicators in Stuttgart and Detroit are piloting these units for just-in-time sealant preparation. The technology is integrating temperature uniformity specifications that exceed traditional jacketed systems, compressing competitive differentiation around heating method rather than capacity rating.
OSHA's updated thermal hazard protocols are mandating redundant high-limit cutouts and insulated surface temperature caps on all new industrial heating vessel installations. Equipment manufacturers must now engineer dual-sensor architectures and external guard panels that add material cost and assembly complexity. North American packaging lines and German chemical processing facilities are absorbing these compliance costs fastest, driving premium positioning for safety-certified configurations.
Buyer consolidation among mid-tier packaging firms is compressing vendor negotiation leverage and unbundling after-sales service from equipment purchase contracts. Distributor networks that previously bundled installation and maintenance are losing ground to direct manufacturer service agreements priced separately from hardware. This pattern concentrates most visibly in US Midwest industrial corridors where private-equity-backed packaging rollups are standardizing procurement across multi-site operations.
Drum Melters Market Segmentation
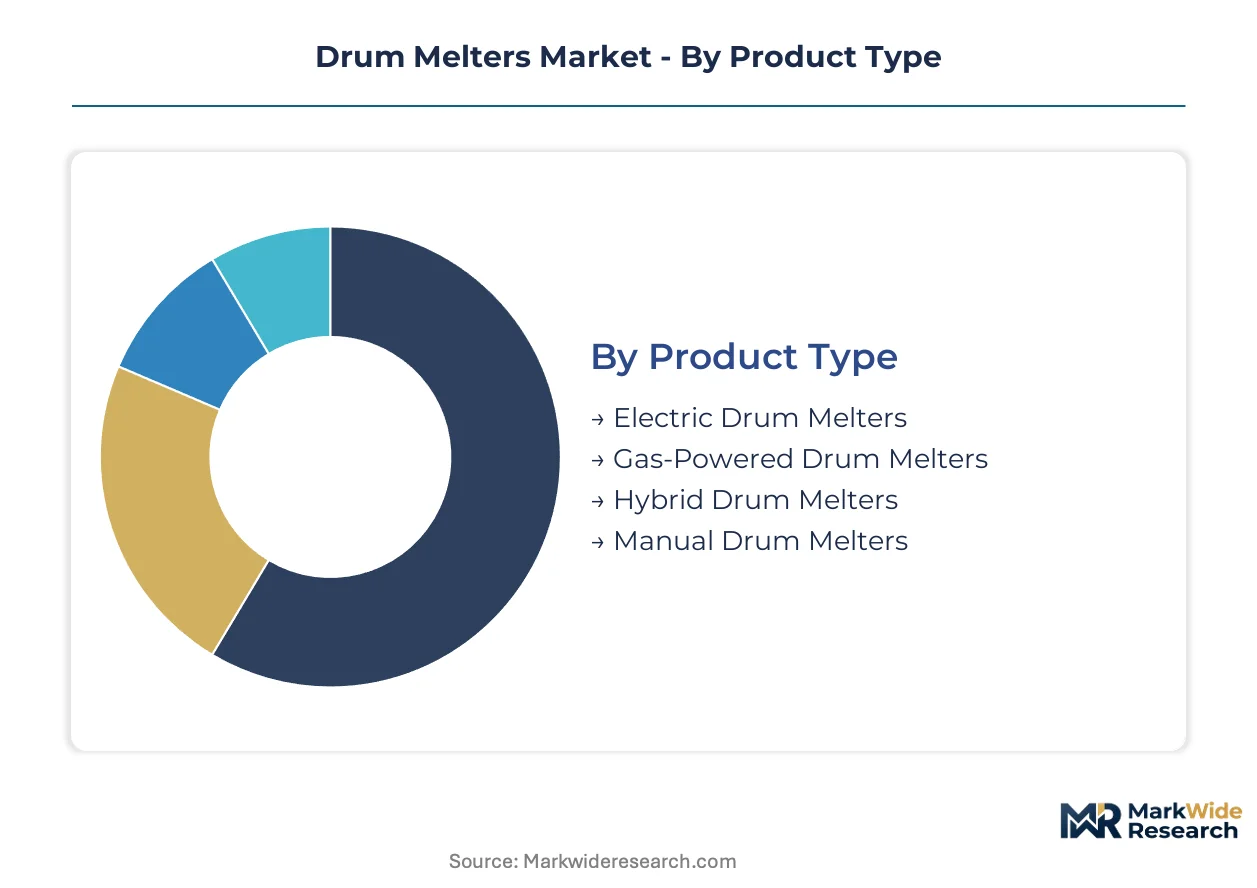
Equipment replacement cycles across drum melter categories track divergent regulatory pressures and energy cost spreads. Buyers configure portfolios across product type, capacity tier, and end-use application to match batch throughput requirements with site-specific emissions constraints.
Product Type:
Upgrade cycles accelerate where EPA emissions guidelines and OSHA thermal safety rules force heating system redesigns around redundant temperature limiters and exhaust capture integration.
- Electric Drum Melters:Resistive coil and induction-based systems deliver cleaner emissions profiles and tighter temperature uniformity for adhesive dispensing lines. Packaging automation clusters in Germany and the US Midwest favor these units for EPA compliance and precision viscosity control.
- Gas-Powered Drum Melters:Direct-fired burner configurations persist in chemical plants and recycling facilities with high batch throughput demands and lower electricity cost structures. Permitting friction under California and Northeast US air quality districts constrains new deployments.
- Hybrid Drum Melters:Dual-fuel redundancy appeals to facilities pursuing operational continuity amid energy price volatility, though dual-sensor safety architectures add material cost.
- Manual Drum Melters:Basic jacketed vessels without pumped discharge serve small-batch operations and maintenance shops with minimal automation requirements.
Electric configurations sit at the top of the volume ranking, with hybrid systems climbing the fastest as facilities hedge fuel source risk.
End User:
Procurement consolidation patterns vary sharply across customer types, with industrial manufacturers bundling multi-site contracts while specialty processors fragment across regional hubs.
- Industrial Manufacturers:Automotive tier-one suppliers and electronics assemblers drive specifications for pumped discharge systems with insulated drum jackets. Stuttgart and Detroit adhesive applicators pilot induction heating for just-in-time sealant preparation.
- Food Processing:Sanitary-design drum melters with stainless steel construction and clean-in-place capability serve edible coating and packaging adhesive applications. FDA food contact compliance dictates surface finish and material certification requirements.
- Chemical Plants:Large capacity units command margin concentration where batch throughput determines operational economics. REACH solvent-handling mandates push European facilities toward sealed-system configurations.
- Construction Industry:Field-deployable melters for roofing membranes and waterproofing sealants prioritize portability and rapid thermal ramp over precision control.
Industrial manufacturers anchor absolute demand volumes, with food processing expanding most quickly behind clean-label packaging adhesive specifications.
Capacity:
Facility scale and batch frequency determine capacity selection, with chemical recycling feedstock preparation creating new demand at the upper tier.
- Small Capacity:Laboratory and pilot-line units for adhesive formulation R&D centers in Germany support recipe development before production scale-up.
- Medium Capacity:Mid-tier packaging firms consolidate procurement around standardized units serving multiple SKUs with changeover flexibility.
- Large Capacity:Chemical plant and plastics reprocessing facilities seeking batch liquefaction of contaminated polymer streams configure these for throughput economics.
- Extra-Large Capacity:Continuous-duty installations at adhesive manufacturing sites integrate with bulk storage and automated feed systems.
Medium capacity holds the largest installed base, with extra-large units gaining share fastest behind chemical recycling penetration.
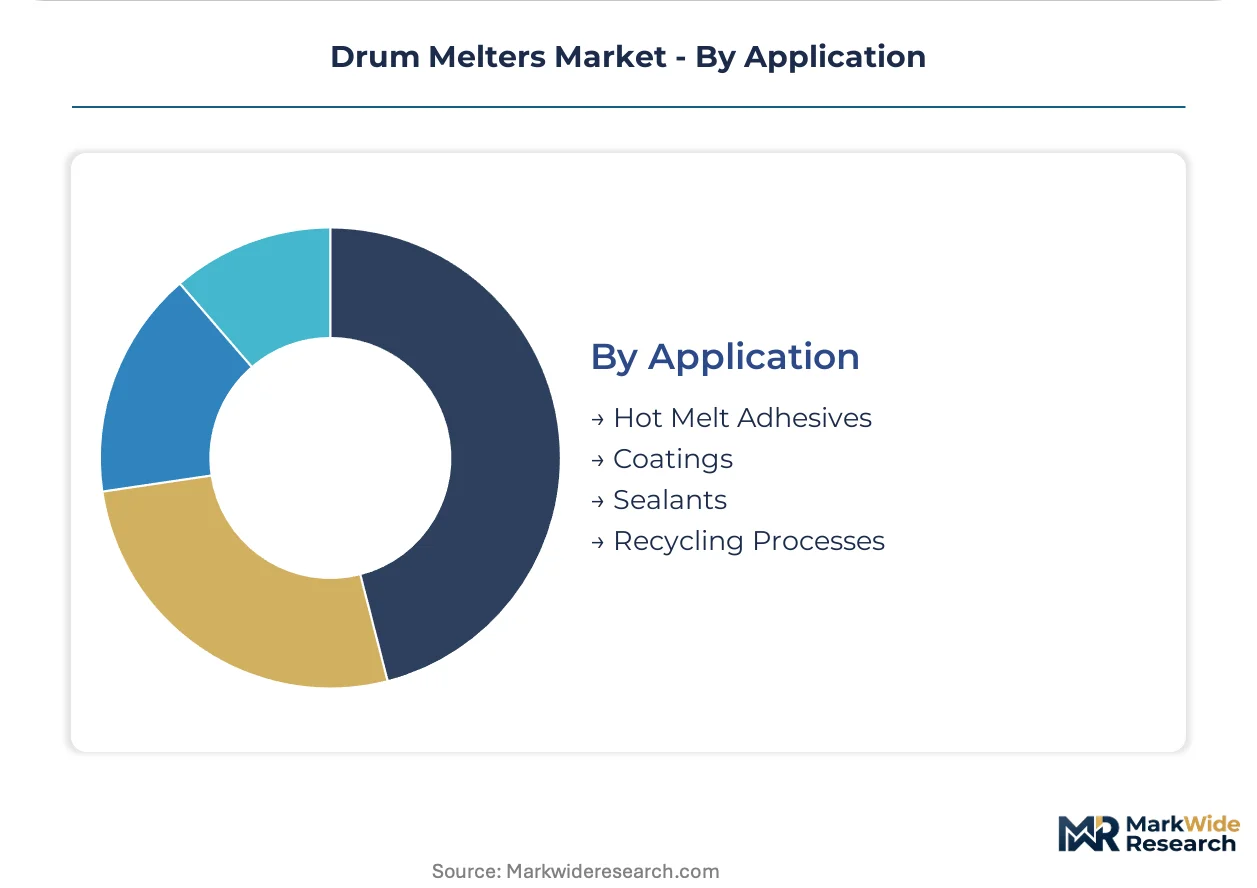
Application:
Application-specific viscosity and temperature requirements shape heating method selection and control architecture sophistication.
- Hot Melt Adhesives:The dominant application demands precise temperature maintenance across EVA, polyamide, and metallocene formulations to prevent thermal degradation and char formation.
- Coatings:Powder coating and liquid protective coating preparation requires controlled melt rates and filtration integration for contamination removal.
- Sealants:Polyurethane and silicone sealant processing in automotive and construction end-uses emphasizes degassing capability and moisture exclusion.
- Recycling Processes:Post-industrial adhesive recovery and contaminated polymer stream liquefaction represents an emerging configuration segment for plastics reprocessing facilities.
Hot melt adhesives dominate current deployment, with recycling processes showing the steepest expansion trajectory as circular economy mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's packaging automation clusters outpace US Midwest procurement consolidation in drum melter replacement velocity, while India's PLI scheme opens localized production pathways that challenge East Asian component sourcing patterns.
United States
OSHA thermal hazard protocols and EPA emissions guidelines compress equipment replacement cycles across automotive tier-one adhesive applicators in Detroit. Private-equity-backed packaging rollups in the Midwest industrial corridor standardize procurement across multi-site operations, unbundling distributor service agreements. California air quality districts impose permitting friction on hybrid configurations, redirecting demand toward electric units.
Germany
REACH chemical compliance mandates accelerate sealed-system drum melter turnover among adhesive formulation R&D centers. CE marking under EU machinery directives extends third-party validation timelines for solvent-bearing configurations. Stuttgart automotive clusters pilot induction heating elements for just-in-time sealant preparation, compressing competitive differentiation around thermal ramp rates.
China
Dual carbon goals and MIIT industrial efficiency standards reshape heating method selection toward electric and induction-based systems. Yangtze River Delta packaging machinery manufacturers absorb ceramic and mica-wound resistor supply concentration from domestic component suppliers. GB standards compliance creates technical barriers for Western equipment builders seeking market access.
India
PLI scheme subsidies for packaging machinery open localized production pathways for mid-capacity electric units serving South Asian contract manufacturers. BIS certification requirements and FSSAI food contact compliance dictate sanitary-design specifications for edible coating applications. Maharashtra and Gujarat industrial corridors concentrate demand from mid-tier packaging firms consolidating procurement.
Japan
METI energy efficiency regulations and JIS standards precision push automotive electronics assemblers toward pumped discharge systems with insulated drum jackets. Kanto region adhesive applicators emphasize degassing capability and moisture exclusion for polyurethane sealant processing. Aging specialist workforces for thermal systems engineering concentrate in Nagoya and Osaka industrial zones.
Drum Melters Market Competitive Landscape
North American producers anchor one tier; German and Swiss specialists hold premium positioning through precision temperature control integration. The vendor base stratifies across three tiers: diversified industrial conglomerates with adhesive dispensing divisions, dedicated thermal equipment fabricators with regional service networks, and emerging Asia-Pacific manufacturers competing on component cost. Consolidation pressures concentrate among mid-tier packaging procurement rollups, while technology licensing agreements proliferate around IoT-enabled predictive maintenance architectures.
Within the diversified industrial tier, Nordson Corporation and Illinois Tool Works exemplify integrated adhesive dispensing strategies that bundle drum melters with precision application systems. Graco Inc. anchors North American manufacturing scale through extensive distributor infrastructure. Among European specialists, BÜHNEN GmbH & Co. KG and Meler occupy positions emphasizing CE-marked configurations for REACH-compliant solvent handling, while Robatech represents Swiss precision engineering in temperature uniformity specifications.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| Illinois Tool Works |
| Valco Melton |
| BÜHNEN GmbH & Co. KG |
| Meler |
| ITW Dynatec |
| Robatech |
| SM Klebetechnik Vertriebs-GmbH |
| Others |
Supply & Pricing Matrix
Backward integration into ceramic heating element production anchors supply security for Western equipment builders while insulating premium-tier pricing from East Asian component volatility. This captive sourcing strategy simultaneously defends margin concentration in large-capacity chemical plant configurations and compresses cost pass-through to mid-tier packaging buyers consolidating procurement.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electric drum melter configurations, pressuring legacy resistive coil suppliers. Pricing stratifies across premium induction-based systems, standard electric jacketed units, and economy manual configurations, with differentiation driven by CE marking tier and after-sales service bundling. Cost compression in the economy tier intensifies because of ceramic resistor oversupply, while automotive tier-one buyers in Stuttgart and Detroit show lowest price sensitivity due to just-in-time thermal uniformity requirements.
Supply Chain Analysis
CE marking and OSHA thermal hazard certification gating concentrates qualified supplier pools among established German and North American fabricators with third-party validation capabilities. Component sourcing draws from China for ceramic heating elements, Germany for precision temperature controllers, and Japan for mica-wound resistors. Single-source vulnerability in East Asian resistor supply creates exposure for Western equipment builders. Distribution runs through manufacturer-direct service agreements replacing traditional distributor networks in US Midwest packaging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in drum melters rests on the shift from commodity electric units toward premium induction configurations with IoT-enabled predictive maintenance subscriptions. Stainless steel input hedging and captive heating element production compress cost volatility for integrated manufacturers.
For Market Incumbents: To counter procurement consolidation among private-equity-backed packaging rollups, deepen direct service agreements that unbundle installation from hardware sales and capture recurring revenue streams. Invest in dual-sensor safety architectures ahead of OSHA thermal hazard protocol updates to preempt certification delays that disadvantage smaller competitors.
For New Entrants and Emerging Players: Begin with India's PLI-subsidized packaging machinery corridor, where BIS certification requirements create technical barriers that favor localized assembly partnerships over direct import. Target mid-capacity electric units for South Asian contract manufacturers, leveraging domestic stainless steel fabrication to undercut landed costs from established European suppliers.
For Investors and Strategic Acquirers: Roll-up economics work for regional thermal equipment fabricators with CE-marked solvent-handling capabilities because REACH compliance mandates are accelerating sealed-system replacement cycles beyond organic capacity expansion timelines. Watch for inflection when carbon border adjustments in Europe redirect demand toward electric configurations with documented Scope 3 emissions profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive ceramic resistor production insulates margin from East Asian supply concentration and price volatility. |
| Induction Technology Licensing | Temperature uniformity specifications exceeding jacketed systems command premium positioning in automotive adhesive applicators. |
| IoT Predictive Maintenance Platform | Cloud-based asset management converts one-time hardware sales into recurring subscription revenue streams. |
| CE Marking Pre-Certification Investment | Third-party validation capabilities compress product launch timelines for solvent-bearing configurations by 8-14 months. |
| India PLI Localization Partnership | Domestic mid-capacity assembly secures BIS certification pathways and defends against carbon-adjusted import competition. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, aftermarket service heads, and thermal systems engineering specialists; secondary validation through customs trade data, SEC equipment manufacturer filings, and EU machinery directive certification databases; plus regional energy price spreads and stainless steel commodity indices — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Segment-level outputs across product type, capacity tier, end-use application, and heating method were projected across the analysis window using replacement cycle modeling tied to regulatory compliance deadlines and facility automation investment patterns. CAGRs were derived from equipment shipment correlations with adhesive formulation R&D center expansion and packaging automation cluster formation.
Several conditions sit outside the modeled scope, including tariff rate revisions on heating element imports, abrupt OSHA thermal hazard protocol amendments, and energy price shock scenarios exceeding historical volatility bands. A model refresh is warranted upon material change in carbon border adjustment implementation timelines or REACH solvent-handling mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Tallow Fatty Acid Market