
 Pelletized Activated Carbon Market | 2026-2036
Pelletized Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
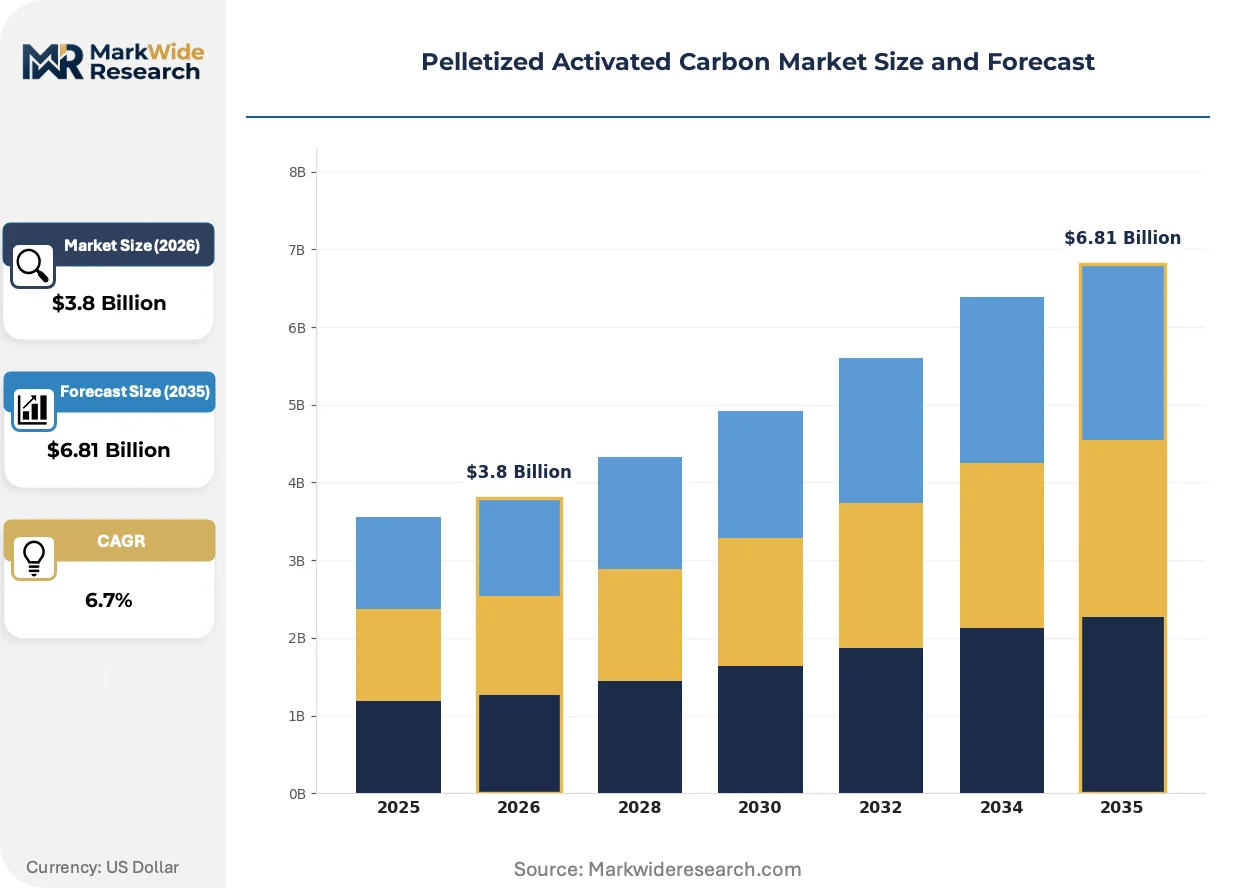
Pelletized Activated Carbon Market Outlook
REACH is decoupling European market access from legacy coal-based production methods, forcing reformulation investments that favor coconut shell and wood-based pelletized grades. Calgon Carbon Corporation leverages its captive reactivation infrastructure across the Rhine-Ruhr corridor to sustain margin structures competitors cannot replicate. Kuraray Co. Ltd. anchors Asia-Pacific supply security through backward integration into coconut char supply chains in Indonesia and the Philippines.
Pelletized activated carbon consists of cylindrical extrudates, typically 0.8–4.0 mm in diameter, manufactured by mixing powdered activated carbon with binders and passing the blend through a die under high pressure before thermal activation; this geometry delivers low pressure drop and uniform packed-bed performance critical to continuous-flow gas and liquid treatment systems. Extruded carbon dominates municipal water treatment contracts where hydraulic performance specifications are non-negotiable, while coconut shell carbon commands premium positioning in food processing and pharmaceutical applications demanding ultra-low ash content and minimal leachable metals. Wood-based carbon occupies a narrowing mid-market niche as utilities in North America and Europe pivot toward renewable feedstock credentials.
EPA Maximum Contaminant Level enforcement for PFAS compounds is accelerating demand for reactivated pelletized carbon in US municipal water systems, while ECHA authorization requirements under REACH constrain coal-based product placement in EU industrial air treatment. Japan's Ministry of Economy, Trade and Industry (METI) has tightened volatile organic compound emission thresholds that favor pelletized formats in solvent recovery applications. Stakeholders must weigh feedstock transition timelines against reactivation network density when allocating capital between greenfield capacity and service-model expansion.
Market Dynamics
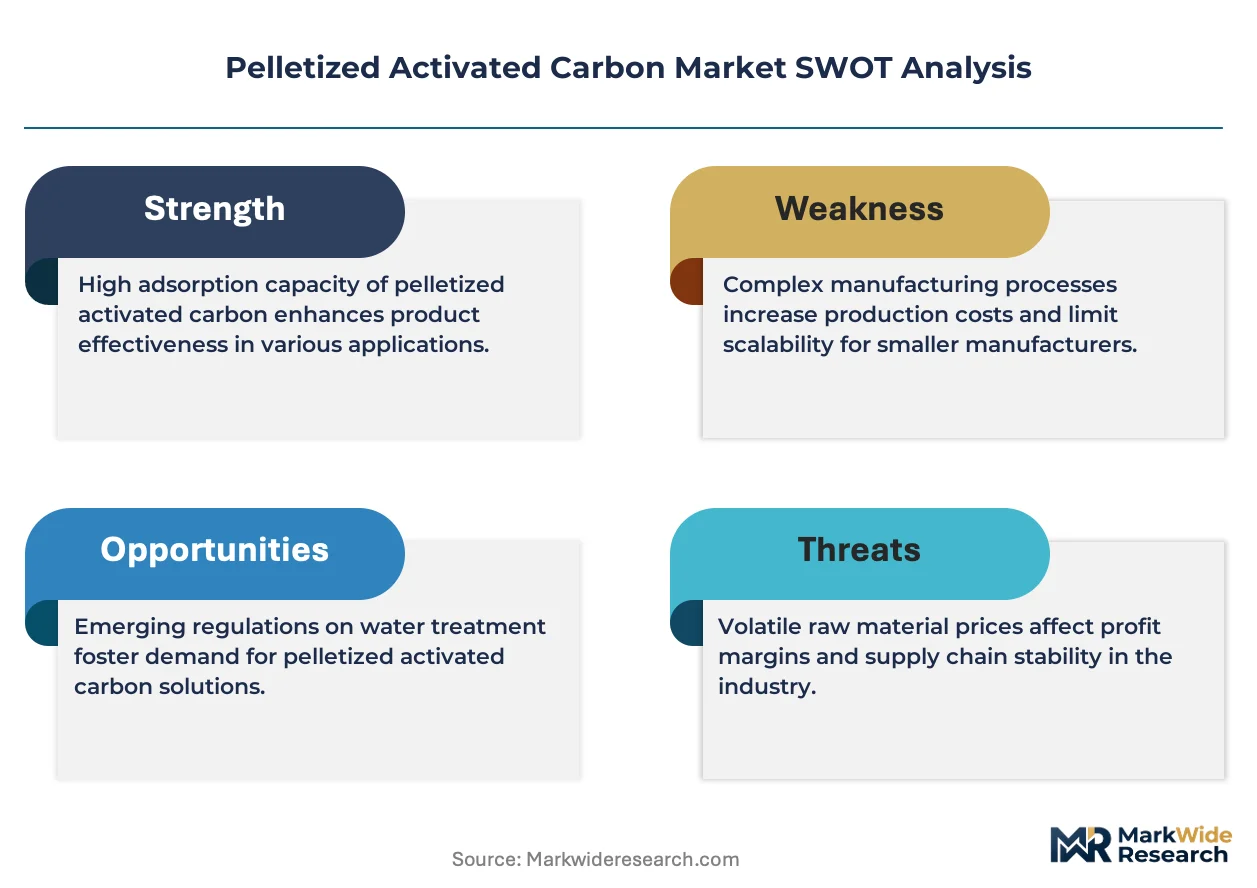
Coal-to-biomass feedstock transitions are forcing extruded carbon manufacturers to rebuild supply chains around coconut shell and wood-based precursors, compressing legacy coal-based capacity economics while opening premium positioning for renewable-sourced grades.
Growth Catalysts
- EPA PFAS enforcement:Maximum Contaminant Level rules for per- and polyfluoroalkyl substances are mandating granular activated carbon replacement cycles in US municipal water systems.
- Food-grade purity specifications:Ultra-low ash coconut shell pelletized carbon is displacing powdered formats in beverage decolorization and pharmaceutical solvent recovery.
- Reactivation infrastructure density:Captive thermal reactivation facilities along industrial corridors in Germany and the Netherlands are shortening carbon service loops for air treatment utilities.
Market Restraints
- Coconut shell feedstock volatility:Typhoon frequency in the Philippines and Indonesia disrupts char supply continuity, exposing manufacturers to raw material cost spikes.
- REACH authorization friction:ECHA substance authorization requirements for coal-tar derived carbons block legacy product placement in EU industrial air treatment markets.
- Pressure-swing adsorption substitution:Zeolite molecular sieves are capturing solvent recovery applications where hydrocarbon specificity outweighs activated carbon's broad-spectrum capacity.
Strategic Opportunities
- India municipal water infrastructure:Jal Jeevan Mission rural piped water schemes are creating first-time demand for continuous-flow carbon treatment systems.
- Hydrogen purification applications:Pressure-swing adsorption pre-treatment using pelletized carbon is consolidating as a standard step in electrolyzer-fed hydrogen production trains.
- EU Green Deal procurement criteria:Renewable feedstock mandates in public tender specifications are tilting contract awards toward coconut shell and wood-based carbon suppliers.
Industry Challenges
- Reactivation technician scarcity:Thermal regeneration furnace operations require specialized combustion engineering expertise that outpaces vocational training pipeline output.
- Legacy system integration complexity:Fixed-bed carbon contactors in aging US water treatment plants constrain retrofit options for higher-performance extruded carbon geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelletized Activated Carbon Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Carbon, Granular Carbon, Coconut Shell Carbon, Wood-Based Carbon Application: Water Purification, Air Treatment, Industrial Applications, Food Processing End User: Municipal, Industrial, Residential, Commercial Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | CarboTech AC GmbH, Donau Carbon GmbH, Calgon Carbon Corporation, Ingevity Corporation, Kuraray Co. Ltd., Cabot Corporation, Carbon Activated Corporation, Activated Carbon Technologies Pty Ltd, Jacobi Carbons AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelletized Activated Carbon Market Strategic Shifts
Extruded carbon manufacturing is pivoting toward precision geometry control and feedstock traceability systems that satisfy simultaneously tightening performance specifications and sustainability audit requirements.
Steam-activation process optimization is consolidating competitive advantage for manufacturers with captive boiler infrastructure. US municipal water utilities specify 4.0 mm diameter extrudates for minimum pressure drop across deep-bed contactors, while food processors demand 0.8–1.4 mm formats for maximum surface area density. The technology is consolidating supply around integrated producers who control both carbonization and activation stages.
REACH substance authorization timelines are compressing coal-based carbon placement windows in European industrial markets. ECHA's restriction roadmap for polycyclic aromatic hydrocarbons in consumer applications is forcing reformulation investments toward biomass-derived precursors. German automotive paint shops and chemical processors are accelerating qualification programs for coconut shell pelletized grades ahead of anticipated 2026 authorization deadlines.
Service-model contracting is displacing traditional carbon procurement in North American water utilities. Municipal buyers now specify guaranteed contaminant removal performance rather than carbon tonnage, transferring reactivation logistics and spent carbon liability to equipment suppliers. This shift concentrates contract awards among vendors with dense thermal reactivation networks in the Ohio River Valley and Gulf Coast corridors.
Pelletized Activated Carbon Market Segmentation
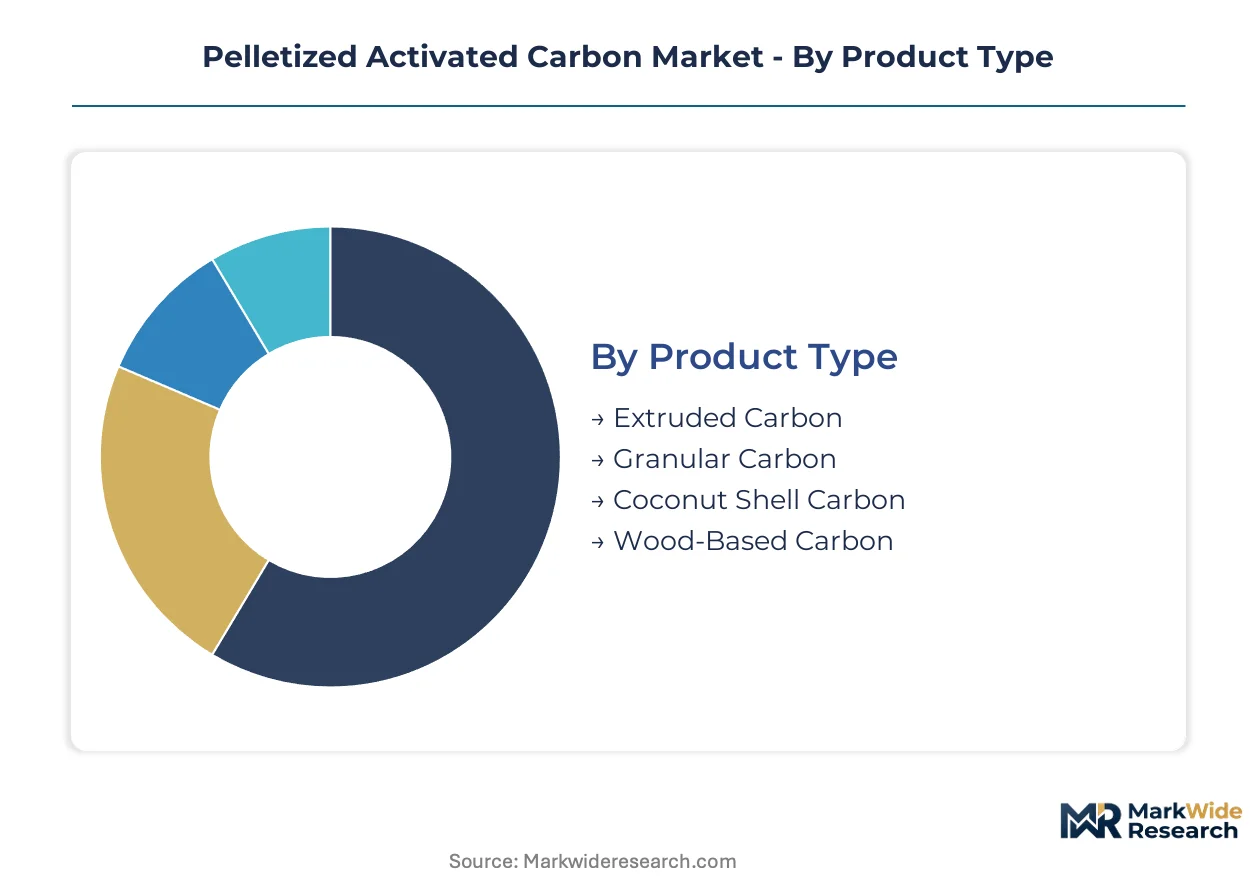
Pelletized activated carbon procurement patterns diverge sharply across geometry specifications, purity grades, and reactivation service bundling. Feedstock traceability requirements and hydraulic performance standards now govern segment selection more than unit price alone.
Product Type:
Supply concentration tilts toward integrated manufacturers controlling both carbonization and activation stages, with captive reactivation infrastructure determining competitive positioning in extruded formats.
- Extruded Carbon:Cylindrical extrudates manufactured by mixing powdered activated carbon with binders and passing through a die under high pressure before thermal activation. Municipal water treatment contracts in Germany and the United States specify 4.0 mm diameter formats for minimum pressure drop across deep-bed contactors, with EPA PFAS enforcement accelerating replacement cycles.
- Coconut Shell Carbon:Ultra-low ash content and minimal leachable metals characterize this premium grade derived from pyrolyzed coconut husks. Food processors and pharmaceutical solvent recovery operations in Japan and the European Union pay premiums for biomass-derived certification ahead of REACH authorization deadlines for coal-tar alternatives.
- Granular Carbon:Irregular particle geometry suited to batch processing applications where packed-bed uniformity matters less than adsorption capacity.
- Wood-Based Carbon:Renewable feedstock credentials support mid-market positioning as North American and European utilities pivot from coal-based precursors.
Today's leader: Extruded Carbon. Tomorrow's challenger: Coconut Shell Carbon.
Application:
Cost tier differentiation separates continuous-flow municipal systems requiring guaranteed contaminant removal performance from intermittent industrial batch processes optimizing for capital efficiency.
- Water Purification:Continuous-flow treatment systems dominate municipal procurement, with service-model contracts transferring spent carbon liability to vendors with dense reactivation networks. The Jal Jeevan Mission in India is creating first-time demand for extruded carbon in rural piped water schemes.
- Air Treatment:Solvent recovery and volatile organic compound abatement in automotive paint shops and chemical processing facilities. METI thresholds in Japan favor pelletized formats, while ECHA authorization requirements under REACH constrain coal-based placement in European industrial markets.
- Industrial Applications:Hydrogen purification pre-treatment using pelletized carbon is consolidating as standard in electrolyzer-fed production trains.
- Food Processing:Beverage decolorization and pharmaceutical applications demand ultra-low ash specifications that coconut shell grades uniquely satisfy.
Water Purification commands current contract volume. Hydrogen purification applications within Industrial Applications are gaining share fastest.
End User:
Customer type determines procurement modality, with municipal buyers specifying outcome-based performance guarantees while industrial purchasers optimize for total cost of ownership across reactivation cycles.
- Municipal:Public water utilities specify guaranteed contaminant removal rather than carbon tonnage, concentrating awards among vendors with thermal reactivation infrastructure in the Ohio River Valley and Gulf Coast corridors.
- Industrial:Chemical processors, automotive manufacturers, and hydrogen producers balance feedstock certification requirements against reactivation network density when sourcing.
- Residential:Point-of-use filtration systems represent fragmented demand with limited pelletized carbon penetration.
- Commercial:Food service and hospitality operations generate moderate volume for coconut shell grades in beverage applications.
Municipal procurement anchors contract value. Industrial end users are expanding most quickly on hydrogen economy buildout.
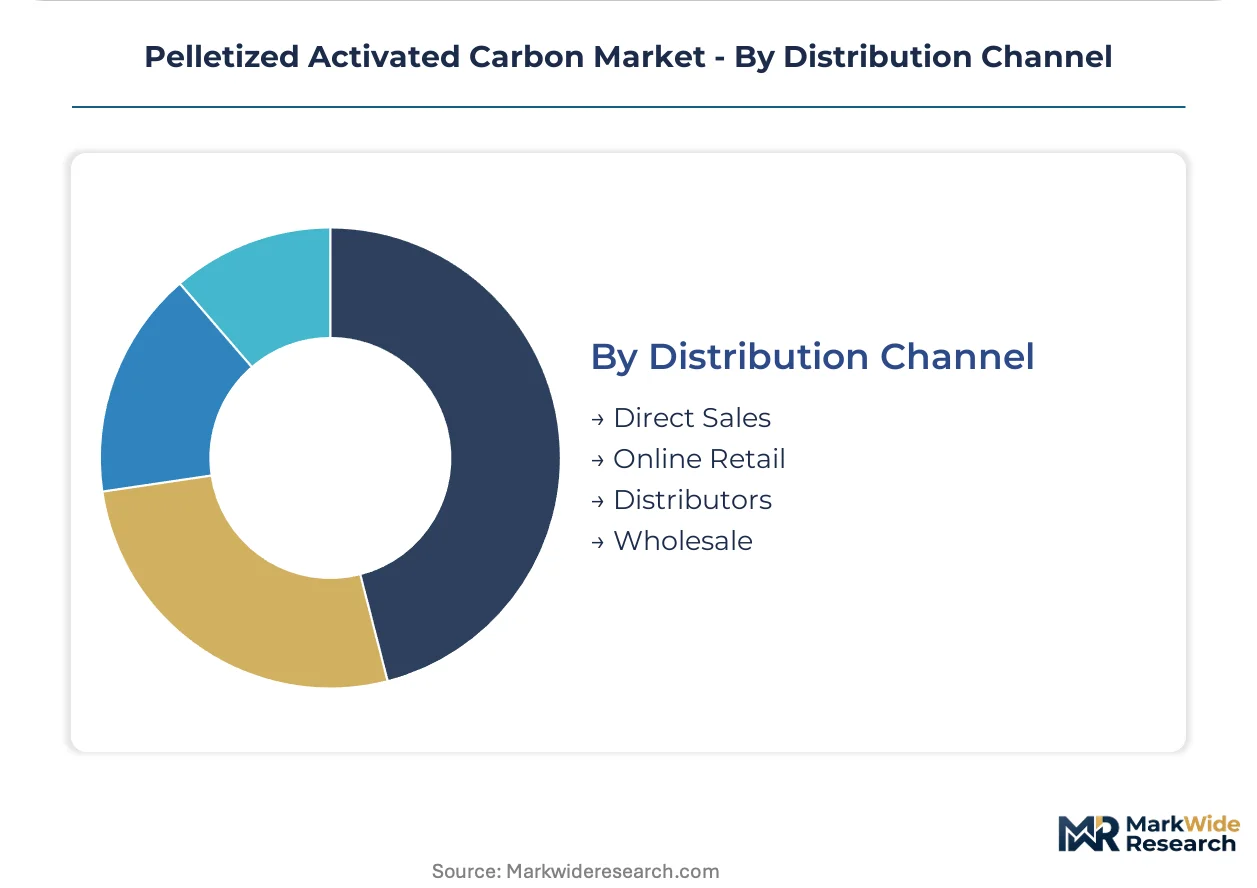
Distribution Channel:
Volume concentration favors direct relationships for large municipal and industrial accounts, while distributor networks capture fragmented commercial and residential demand.
- Direct Sales:Large municipal water utilities and industrial air treatment operators negotiate service-model contracts directly with manufacturers possessing captive reactivation capacity.
- Distributors:Regional stocking distributors serve mid-sized industrial accounts and commercial food processors requiring technical specification support.
- Wholesale:Bulk procurement channels aggregate demand from smaller water treatment contractors and equipment OEMs.
- Online Retail:Minimal penetration given technical specification requirements and reactivation service bundling in core applications.
Direct Sales dominates value capture. Distributors are consolidating position in mid-market industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reactivation technicians concentrate along Germany's Rhine-Ruhr corridor and the US Ohio River Valley, anchoring service-model contract awards in municipal water treatment. Their geographic clustering shapes where carbon manufacturers locate captive regeneration infrastructure.
United States
EPA Maximum Contaminant Level enforcement for PFAS compounds accelerates granular activated carbon replacement cycles in municipal water systems. The agency's drinking water standards mandate continuous-flow treatment upgrades across the Great Lakes and Gulf Coast states. Chicago and Houston anchor dense reactivation networks where vendors bundle spent carbon liability transfer into performance contracts.
Germany
ECHA authorization requirements under REACH constrain coal-tar derived carbon placement in industrial air treatment markets. The EU Drinking Water Directive tightens per- and polyfluoroalkyl substances removal standards, forcing utilities toward coconut shell grades. The Rhine-Ruhr corridor hosts Calgon Carbon Corporation's captive reactivation infrastructure that sustains margin structures competitors cannot replicate.
India
Jal Jeevan Mission rural piped water schemes create first-time demand for extruded carbon in continuous-flow treatment systems. BIS certification requirements for drinking water contact materials shape procurement specifications for domestic manufacturers. Gujarat and Maharashtra industrial clusters witness coal-to-coconut shell feedstock transitions that reshape raw material sourcing economics.
Japan
METI volatile organic compound emission thresholds favor pelletized formats in solvent recovery applications across automotive paint shops. The Ministry of Economy, Trade and Industry standards displace batch processing systems with packed-bed configurations. Osaka and Nagoya chemical processing corridors drive specification demand for ultra-low ash carbon grades.
Indonesia
Coconut char supply chains anchor Asia-Pacific supply security for manufacturers backward integrated into precursor production. Typhoon frequency disrupts harvest cycles and exposes producers to raw material cost volatility. Sulawesi and Sumatra processing clusters concentrate pyrolysis capacity that feeds extruded carbon production lines.
Pelletized Activated Carbon Market Competitive Environment
The competitive structure tilts toward integrated manufacturers with captive reactivation infrastructure and backward-linked feedstock control. Tiered positioning separates premium coconut shell specialists from coal-based legacy operators facing regulatory displacement. Three archetypes dominate: integrated reactivation network operators, biomass feedstock-anchored producers, and regional extrusion specialists serving municipal contract markets. Capacity expansion and service-model contracting represent the dominant competitive moves, with vendors acquiring thermal regeneration assets to shorten carbon service loops.
Among Germany-based operators, CarboTech AC GmbH and Donau Carbon GmbH exemplify the integrated reactivation archetype, while Kuraray Co. Ltd. anchors Asia-Pacific positioning through upstream control over coconut char supply chains in Indonesia and the Philippines.
| Leading Market Players |
|---|
| CarboTech AC GmbH |
| Donau Carbon GmbH |
| Calgon Carbon Corporation |
| Ingevity Corporation |
| Kuraray Co. Ltd. |
| Cabot Corporation |
| Carbon Activated Corporation |
| Activated Carbon Technologies Pty Ltd |
| Jacobi Carbons AB |
| Others |
Value Chain & Pricing Dynamics
Coal-to-coconut shell feedstock transitions in India and Southeast Asia are compressing legacy coal-based capacity economics while concentrating supply power among manufacturers with captive pyrolysis infrastructure. This production-method shift simultaneously raises renewable-grade price floors and fragments bargaining power across buyer archetypes.
Pricing Analysis
Bundled service contracts that transfer spent carbon liability and reactivation logistics to vendors now command 15-25 percent premiums over unbundled tonnage procurement in US municipal water markets. Price differentiation hinges on feedstock certification grade and captive reactivation network density, with coconut shell biomass-derived grades sustaining premium positioning against coal-tar alternatives. Cost compression in standard-grade extruded carbon is intensifying because REACH authorization timelines are shortening placement windows for legacy coal-based products. Municipal utilities exhibit lowest price sensitivity due to outcome-based performance guarantees, while mid-sized industrial air treatment operators face acute budget constraints.
Supply Chain Analysis
Specialized reactivation technician scarcity in Germany's Rhine-Ruhr corridor and the US Ohio River Valley is constraining furnace throughput expansion and lengthening carbon service loops for air treatment utilities. Manufacturing gravity centers on Indonesia, the Philippines, and India, with coconut char pyrolysis capacity concentrated in Sulawesi and Sumatra processing clusters. Raw material sourcing draws from coconut husk harvests, coal-tar pitch precursors, and hardwood biomass feedstocks. Single-source vulnerability in Philippine and Indonesian char supply exposes producers to typhoon-driven harvest disruptions. Distribution runs through direct manufacturer relationships for large municipal accounts and regional stocking distributors for fragmented commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs and Asian feedstock proximity create divergent margin structures across manufacturing locations.
For Market Incumbents: Anticipate zeolite molecular sieve substitution in solvent recovery applications by accelerating coconut shell grade qualification programs ahead of ECHA authorization deadlines. Defend margin structures through captive reactivation capacity additions in the Ohio River Valley and Gulf Coast corridors where municipal service-model contracts concentrate. Prioritize backward integration into Indonesian coconut char supply chains to insulate against typhoon-driven raw material volatility. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium coconut shell grades and economy coal-based extruded carbon creates white-space opportunity in wood-based carbon mid-market positioning. Target India's Jal Jeevan Mission rural piped water schemes where first-time demand for continuous-flow treatment systems outpaces established vendor presence. Pursue BIS certification pathways for domestic manufacturing partnerships as the fastest route to procurement qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion specialists lacking captive reactivation infrastructure but holding municipal contract relationships in fragmented US water treatment markets. Five-to-ten year viability favors integrated manufacturers with upstream feedstock control and dense thermal regeneration networks. Watch EPA enforcement velocity on PFAS Maximum Contaminant Level rules as the primary inflection signal for reactivation service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Char | Calgon Carbon Corporation's Indonesian supply chain anchors Asia-Pacific raw material security against typhoon disruption. |
| Captive Reactivation Capacity Expansion | Rhine-Ruhr corridor furnace investments sustain margin structures competitors cannot replicate under REACH compliance costs. |
| Biomass Feedstock Certification Investment | ECHA authorization timelines force reformulation spending that coconut shell specialists amortize across EU Green Deal procurement criteria. |
| Service-Model Contracting Transition | US municipal utilities now specify guaranteed contaminant removal performance rather than carbon tonnage procurement. |
| Hydrogen Purification Application Development | Pelletized carbon pre-treatment is consolidating as standard in electrolyzer-fed hydrogen production trains across industrial corridors. |
Study Parameters
Direct dialogue with thermal regeneration furnace operators, municipal water utility procurement directors, coconut char pyrolysis plant managers, and REACH compliance consultants grounded qualitative assessment in operational reality. Secondary validation drew from EPA enforcement disclosures, ECHA substance authorization databases, BIS certification registries, and customs trade data tracking coconut shell carbon flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level outputs reflect disaggregation by feedstock type, geometry specification, application end-use, and regional regulatory cluster throughout the forecast period. CAGRs derived from installed base replacement cycle modeling, PFAS enforcement velocity assumptions, and hydrogen economy buildout penetration curves. Forecast inputs incorporated Jal Jeevan Mission implementation pace, METI solvent recovery threshold adoption, and EU Green Deal procurement mandate rollout.
Caveats apply where EPA PFAS enforcement delays, typhoon frequency escalation in Southeast Asia, or zeolite molecular sieve cost breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions on reactivation network expansion timelines and feedstock transition economics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Chemical Process Mixers Market