
 Philippines Commercial Vehicles Lubricants Market | 2026-2036
Philippines Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Commercial Vehicles Lubricants Market Analytics
Service station networks in the Philippines is tilting toward fleet-direct contracts and integrated maintenance packages. Petron Corporation leverages its nationwide refinery infrastructure to secure bulk supply agreements with provincial bus cooperatives. Shell plc anchors its position through lubricant blending facilities in Batangas that reduce import dependency for heavy-duty engine oils. Phoenix Petroleum Philippines competes aggressively on credit terms for fleet card programs that bundle fuel and lubricant purchases.
Commercial vehicles lubricants are formulated base oil and additive packages designed to reduce friction, dissipate heat, and prevent wear in diesel and gasoline engines operating under high load cycles, with viscosity grades typically spanning SAE 15W-40 to SAE 10W-30 for tropical climates. These products serve the primary commercial purpose of extending engine overhaul intervals and maintaining powertrain efficiency in vehicles that accumulate kilometers rapidly across archipelagic routes. Engine oil commands the dominant share of product type revenue given the large displacement diesel engines prevalent in Philippine trucking and bus fleets. Heavy-duty trucks represent the most intensive application segment due to continuous operation on the Pan-Philippine Highway and steep gradients in the Cordillera region. Online retail channels for lubricants are growing fastest among distribution channels as fleet managers adopt e-procurement platforms for bulk ordering and delivery scheduling.
The Department of Energy's Philippine Energy Standards and Labeling Program shapes lubricant formulation requirements by mandating minimum energy efficiency indices for commercial vehicle fluids. BIS certification requirements for imported lubricant products create compliance barriers that favor domestic blenders with established testing protocols. The Department of Environment and Natural Resources enforces waste oil handling regulations that increase operational costs for service providers while creating aftermarket opportunities for re-refined base oil products. Stakeholders must monitor how proposed amendments to fuel economy standards will cascade into OEM-specified oil drain intervals and viscosity grade requirements.
Market Dynamics
Fleet operators throughout Luzon are consolidating lubricant procurement under preventive maintenance programs as the Department of Energy tightens fuel economy enforcement across commercial vehicle categories.
Growth Catalysts
- Pan-Philippine Highway freight expansion:Heavy-duty truck operators are extending oil drain intervals to reduce downtime on the archipelago's primary logistics artery connecting Manila to Mindanao.
- BIS certification alignment:Domestic blenders with established testing protocols capture share from importers facing compliance delays at Philippine ports.
- Re-refined base oil adoption:Waste oil handling regulations from the Department of Environment and Natural Resources create circular economy revenue streams for service providers with collection infrastructure.
Market Restraints
- API Group II/III base oil import dependency:Philippine blenders source the majority of high-quality base stocks from Singapore and South Korean refiners, exposing margins to freight rate volatility and currency fluctuation.
- Extended drain interval technology:Synthetic formulations enabling 50,000-kilometer service cycles compress lubricant volume demand per vehicle despite fleet expansion.
- Used lubricant black market diversion:Informal collectors operating outside DENR waste oil regulations undercut licensed re-refiners on feedstock acquisition costs.
Strategic Opportunities
- Visayas-Mindanao corridor penetration:Logistics growth in Cebu and Davao lags Metro Manila's lubricant service density, creating whitespace for depot-based bulk delivery models.
- E-procurement platform integration:Fleet management software vendors are embedding lubricant ordering modules that bypass traditional jobber networks.
- Dual-fuel engine lubricant development:Natural gas-diesel hybrid powertrains entering Philippine bus fleets require specialized additive packages with distinct soot-handling properties.
Industry Challenges
- Certification timeline compression:BIS testing protocols for new viscosity grades extend product launch cycles by eight to twelve months versus regional benchmark markets.
- Skills gap in tribology diagnostics:Service stations lack technicians trained to interpret used oil analysis data for predictive maintenance recommendations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Commercial Vehicles Lubricants Market |
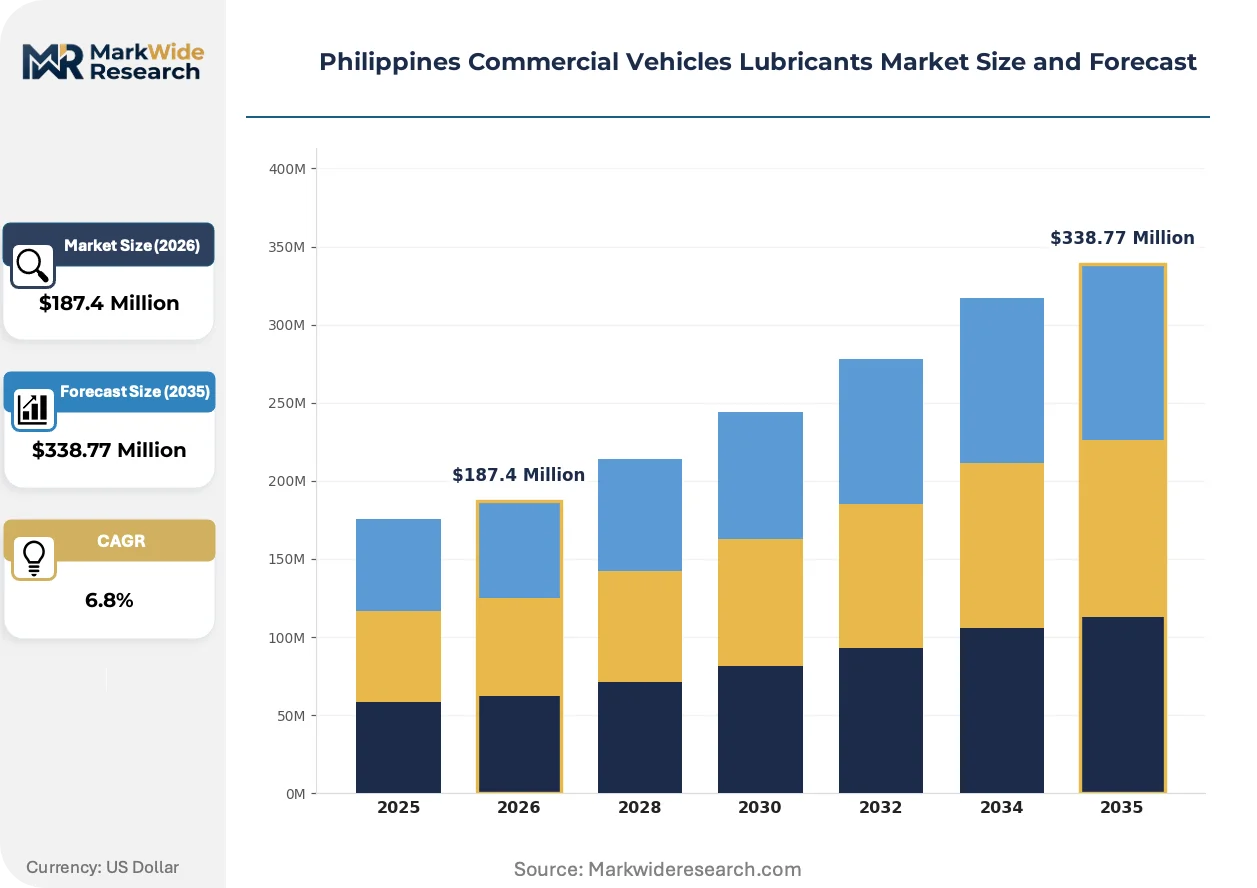
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil Application: Heavy-Duty Trucks, Buses, Vans, Delivery Vehicles Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Wholesale Vehicle Type: Commercial Trucks, Light Commercial Vehicles, Fleets, Specialized Vehicles |
| Companies Covered | Petron Corporation, Shell plc, Chevron Corporation, BP Plc (Castrol), TotalEnergies SE, Phoenix Petroleum Philippines, Inc., SEAOIL Philippines, Inc., ExxonMobil Corporation, PTT Public Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Commercial Vehicles Lubricants Market Evolving Landscape
Lubricant formulation and distribution in the Philippines are pivoting toward data-enabled asset management as fleet operators treat engine oil as a monitored consumable rather than a scheduled commodity.
IoT-enabled oil condition sensors are digitizing maintenance scheduling for provincial bus cooperatives operating across the Cordillera region's steep gradients. Real-time viscosity and oxidation monitoring allows operators to extend drain intervals by 15-30 percent while reducing catastrophic engine failure risk on mountain routes. This telemetry infrastructure is compressing the role of traditional service interval recommendations in favor of actual condition-based replacement triggers.
The Department of Energy's Philippine Energy Standards and Labeling Program is mandating minimum energy efficiency indices for commercial vehicle lubricants sold in domestic channels. Formulators must now document fuel economy improvement percentages versus reference oils to qualify for program certification. Heavy-duty diesel engine oils face the steepest compliance burden, with OEMs specifying drain intervals and viscosity grades that align with proposed fuel economy standard amendments.
Fleet managers in Metro Manila's last-mile delivery sector are unbundling lubricant procurement from fuel purchasing through standalone e-procurement platforms. Digital tendering systems aggregate volume across multiple depots to negotiate direct contracts with blenders, displacing traditional jobber intermediaries. This behavioral shift concentrates purchasing power among the largest logistics operators while fragmenting service provider relationships at smaller fleet scales.
Philippines Commercial Vehicles Lubricants Market Segmentation
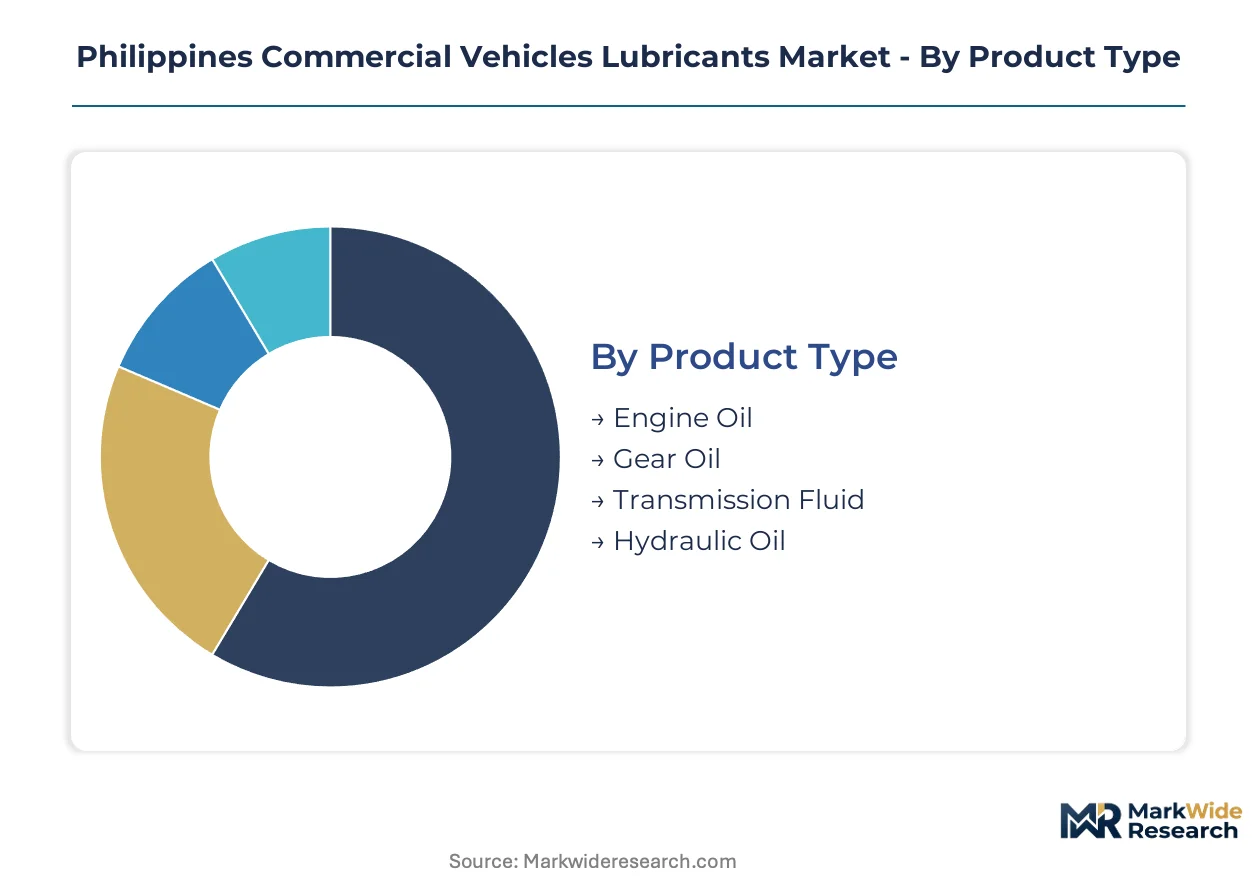
Lubricant purchasing in the Philippines fragments across product specifications, vehicle duty cycles, and procurement channels. Fleet operators weight total cost of ownership differently than owner-operators, creating distinct margin pools within each segment boundary.
Product Type:
Cost tier stratification separates commodity formulations from synthetic premium grades with extended drain claims.
- Engine Oil:Formulations span mineral-based SAE 15W-40 for provincial bus fleets to full-synthetic SAE 5W-30 meeting Euro IV emission hardware requirements. Demand concentrates in Metro Manila's logistics corridors where last-mile operators face high-frequency change intervals on stop-start routes. The Department of Energy's fuel economy labeling program favors lower-viscosity grades that reduce parasitic losses in tropical ambient temperatures.
- Gear Oil:Hypoid gear lubricants for differential and final drive applications carry extreme pressure additives to handle torque spikes on Cordillera mountain gradients. Fleet maintenance contracts in Luzon specify 80W-90 multigrade stocks for year-round serviceability across elevation changes.
- Transmission Fluid:Automated manual transmissions in modern truck platforms require dedicated fluid chemistries distinct from legacy manual gearbox oils.
- Hydraulic Oil:Anti-wear formulations serve dump truck and concrete mixer ancillary systems with high-pressure pump protection requirements.
Engine oil holds installed capacity. Synthetic grades are rotating up the share rankings.
Application:
Application segmentation tracks duty cycle severity and annual kilometer accumulation across vehicle classes.
- Heavy-Duty Trucks:Tractor-trailers operating the Pan-Philippine Highway accumulate 150,000+ kilometers annually with continuous high-load engine operation. Oil analysis programs from Petron Corporation and Shell plc anchor fleet-direct contracts targeting 30,000-kilometer drain intervals. Steep gradients in the Cordillera region accelerate soot loading and thermal degradation versus flat terrain operations.
- Buses:Provincial cooperatives running fixed routes between Luzon cities operate on tighter maintenance windows with depot-based bulk lubricant storage. Natural gas-diesel hybrid powertrains entering the segment require specialized additive packages with distinct soot-handling properties.
- Vans:Light commercial units in urban delivery service shorter duty cycles with more frequent cold starts.
- Delivery Vehicles:Last-mile fleets in Metro Manila prioritize rapid service bay throughput over extended drain technology.
Heavy-duty trucks anchor volume throughput. Buses are expanding fastest on route privatization.
Distribution Channel:
Channel structure reflects procurement centralization trends and credit term competition among suppliers.
- Online Retail:E-procurement platforms aggregate volume across multiple depots for direct blender contracting, bypassing traditional jobber networks. Fleet management software vendors embed lubricant ordering modules that digitize delivery scheduling. Metro Manila's largest logistics operators concentrate purchasing power through standalone tendering systems.
- Service Stations:Petron Corporation and Phoenix Petroleum Philippines leverage fuel-lubricant bundling through fleet card programs with extended payment terms.
- Auto Parts Stores:Independent retailers serve owner-operators and small fleets outside major logistics corridors.
- Wholesale:Bulk supply agreements with provincial bus cooperatives flow through dedicated depot delivery infrastructure.
Service stations hold legacy penetration. Online retail is climbing the fastest on fleet digitization.
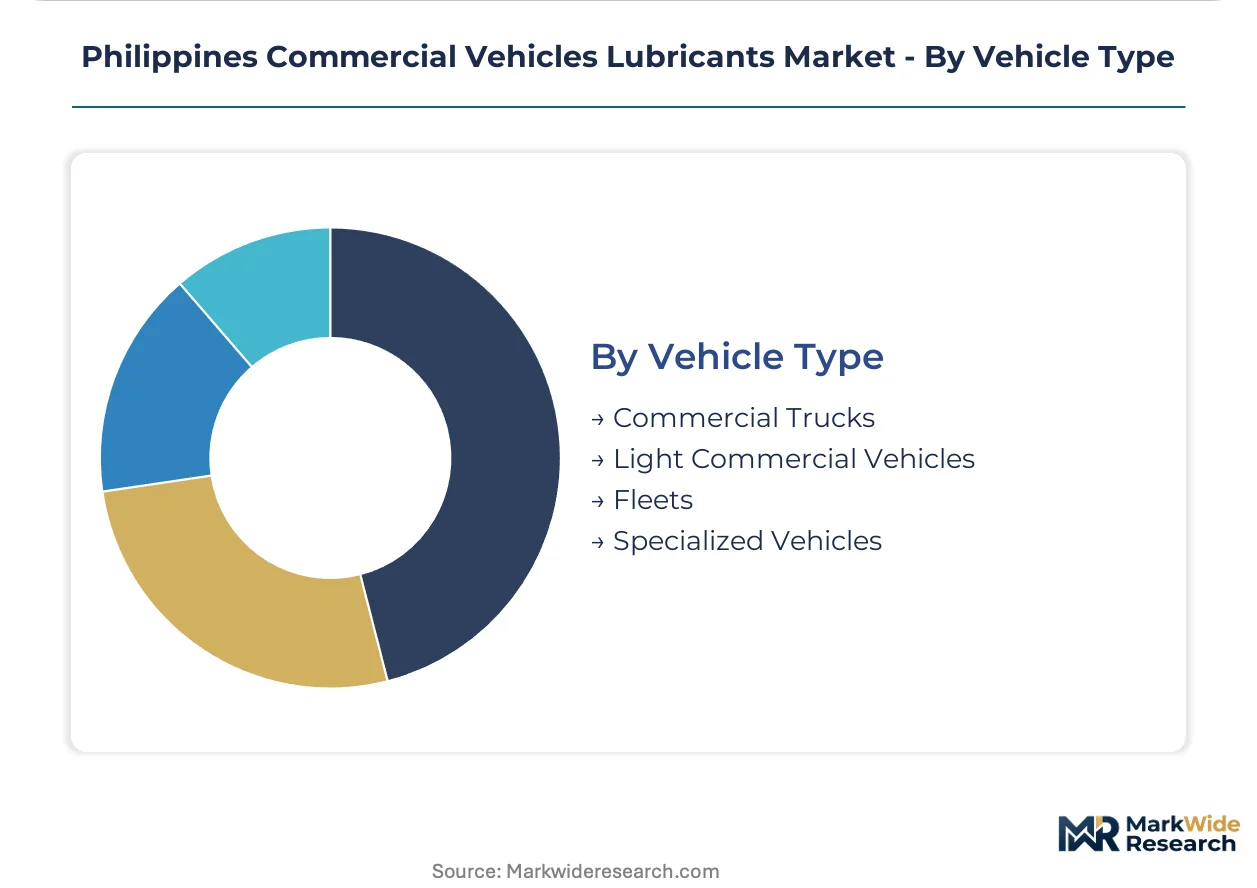
Vehicle Type:
Vehicle classification separates high-mileage highway units from intermittent-use specialized equipment.
- Commercial Trucks:Category spans rigid trucks and tractor-trailers with the most intensive lubricant consumption per vehicle. The Department of Energy's proposed fuel economy standard amendments cascade into OEM-specified oil drain intervals and viscosity grade requirements for this segment.
- Fleets:Consolidated operators with centralized maintenance programs negotiate direct contracts with domestic blenders holding BIS certification.
- Light Commercial Vehicles:Pickup trucks and small vans in provincial distribution serve lower annual kilometer accumulation.
- Specialized Vehicles:Concrete mixers, tankers, and refrigerated trucks require application-specific hydraulic and compressor lubricants alongside engine oils.
Commercial trucks dominate consumption scale. Fleet procurement is gaining share fastest on operator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Energy anchors lubricant demand patterns across Philippine sub-regions through fuel economy enforcement and standards labeling programs. Fleet operator consolidation varies sharply between the northern island cluster and southern growth corridors.
Metro Manila and Calabarzon
Last-mile delivery fleets in the capital region accumulate the highest lubricant change frequency due to stop-start urban duty cycles. The Department of Energy's Philippine Energy Standards and Labeling Program mandates minimum energy efficiency indices for all commercial vehicle fluids sold through domestic channels. Logistics depots in Quezon City and Calamba cluster bulk storage infrastructure serving consolidated procurement contracts.
Central Luzon
Subic Bay Freeport Zone and Clark Special Economic Zone host trans-shipment fleets with intensive highway lubricant consumption. BIS certification requirements for imported products create compliance barriers that favor domestic blenders with established testing protocols. Fleet maintenance facilities in Angeles City and Olongapo anchor preventive maintenance programs for regional distribution operators.
Bicol Region
Provincial bus cooperatives along the Pan-Philippine Highway extension maintain depot-based bulk lubricant storage for fixed-route operations. The Department of Environment and Natural Resources enforces waste oil handling regulations that increase operational costs for service providers. Legazpi City and Naga serve as maintenance hubs for mountain-route fleets facing accelerated thermal degradation on steep gradients.
Visayas
Cebu City's logistics growth lags Metro Manila's lubricant service density, creating whitespace for depot-based bulk delivery models. Proposed amendments to fuel economy standards will cascade into OEM-specified oil drain intervals for regional commercial vehicle categories. Mandaue and Lapu-Lapu industrial zones concentrate fleet operator consolidation among construction and distribution segments.
Mindanao
Davao City's emerging logistics corridor attracts blender investment in dedicated distribution infrastructure. Online retail channels for lubricants penetrate fastest here as fleet managers adopt e-procurement platforms for bulk ordering. Cagayan de Oro and General Santos serve as secondary hubs for agricultural and mining vehicle lubricant demand.
Philippines Commercial Vehicles Lubricants Market Competitive Landscape
Integrated energy majors and independent petroleum distributors split the market through divergent channel strategies. Domestic blenders with BIS certification capture share from importers facing compliance delays at Philippine ports. National oil companies and multinational lubricant specialists constitute the primary strategic archetypes. Competitive moves concentrate on fleet-direct contracting and backward integration into base oil supply.
Among integrated energy majors, Petron Corporation and Shell plc exemplify divergent approaches to market position. Petron leverages nationwide refinery infrastructure to secure bulk supply agreements with provincial bus cooperatives. Shell anchors its position through lubricant blending facilities in Batangas that reduce import dependency for heavy-duty engine oils. Phoenix Petroleum Philippines occupies a position within the independent distributor tier, competing aggressively on credit terms for fleet card programs that bundle fuel and lubricant purchases.
| Leading Market Players |
|---|
| Petron Corporation |
| Shell plc |
| Chevron Corporation |
| BP Plc (Castrol) |
| TotalEnergies SE |
| Phoenix Petroleum Philippines, Inc. |
| SEAOIL Philippines, Inc. |
| ExxonMobil Corporation |
| PTT Public Company Limited |
| Others |
Value Network & Pricing Analysis
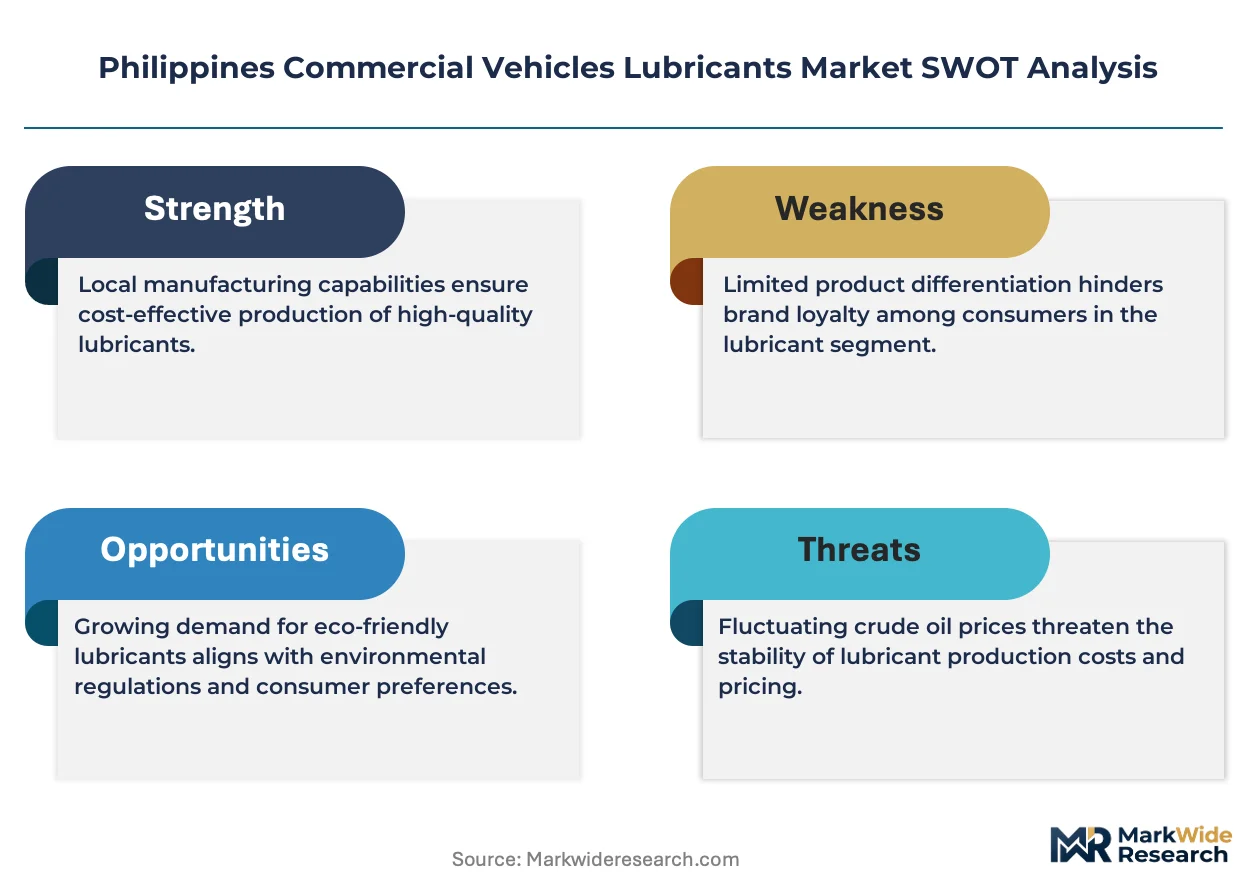
API Group II/III base oil import dependency from Singapore and South Korean refiners exposes Philippine blenders to freight rate volatility and currency fluctuation, compressing margins on premium synthetic grades while forcing economy-tier suppliers toward lower-specification domestic alternatives. This input-cost asymmetry stratifies the market into three distinct pricing tiers that track supply chain reliability rather than formulation complexity alone.
Pricing Analysis
The customization-premium spread separates fleet-direct contracts with configured drain intervals and oil analysis services from standard offtake pricing through jobber networks. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification status, volume commitment scale, and bundled technical support. Cost compression in the economy tier is intensifying because informal collectors undercut licensed re-refiners on waste oil feedstock acquisition. Fleet operators with consolidated procurement exhibit lowest price sensitivity, while owner-operators purchasing through auto parts stores face highest cost pressure per liter.
Supply Chain Analysis
Contract-manufacturing concentration resides with integrated energy majors operating captive blending facilities in Batangas and Limay rather than independent toll blenders. Geographic supply concentration centers on Singapore, South Korea, and Japan for API Group II/III base stocks, with additive packages sourced from US and European specialty chemical suppliers. Raw material dependencies include Group II base oil, zinc dialkyldithiophosphate anti-wear additives, and viscosity index improvers. Single-source vulnerability runs through Singapore Strait logistics chokepoints for seaborne base stock deliveries. Distribution runs through depot-based bulk delivery for fleet-direct accounts and service station networks for fragmented retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine commercial vehicle lubricants function as a service-attach opportunity where predictive maintenance contracts and used oil analysis programs expand faster than standalone product sales. Fleet operators increasingly treat lubricant procurement as an integrated component of total cost of ownership optimization rather than a commodity purchase.
For Market Incumbents: Entrench position through backward integration into re-refined base oil production that captures circular economy value streams under DENR waste oil regulations. Expand Batangas blending capacity to reduce Singapore import exposure. Defend against e-procurement platform disintermediation by embedding lubricant ordering modules directly into fleet management software partnerships. For New Entrants and Emerging Players: Establish a beachhead in Visayas-Mindanao corridor depot-based bulk delivery where service density lags Metro Manila. Target provincial bus cooperatives in Bicol and Central Luzon with credit-competitive fleet card programs. Penetrate through natural gas-diesel dual-fuel engine lubricant specialization that incumbent formulators have underdeveloped. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors domestic blenders with BIS certification infrastructure and established waste oil collection networks. Long-term viability hinges on regulatory compliance capabilities rather than scale alone. Monitor proposed Department of Energy fuel economy standard amendments as the critical inflection signal for OEM-specified oil drain interval compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refining | Captures DENR-mandated waste oil value streams while reducing base stock import exposure. |
| Fleet Management Software Partnership | Embeds lubricant procurement into e-procurement platforms before jobber displacement accelerates. |
| Dual-fuel Engine Lubricant Development | Addresses specialized soot-handling requirements of natural gas-diesel hybrid bus powertrains entering Philippine fleets. |
| Visayas-Mindanao Distribution Buildout | Establishes depot-based bulk delivery infrastructure in whitespace corridors lagging Metro Manila service density. |
| BIS Certification Acceleration | Compresses product launch cycles versus importers facing compliance delays at Philippine ports. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department of Energy regulatory filings, BIS certification databases, and customs import records for base oil and additive trade flows. Primary interviews engaged fleet maintenance managers at provincial bus cooperatives, lubricant procurement leads at logistics operators, technical directors at domestic blending facilities, and aftermarket service heads at integrated energy majors. Secondary validation drew from DENR waste oil handling compliance reports, Philippine Ports Authority cargo manifests, and industry association technical bulletins. Bottom-up volume estimates from depot-level consumption patterns triangulate against top-down market sizing from refinery output and import statistics.
Forecast inputs incorporate vehicle parc growth projections, kilometer accumulation rates by duty cycle class, and OEM-specified drain interval evolution across the analysis window. Segmentation dimensions modeled include product viscosity grade, application severity tier, distribution channel structure, and vehicle fleet consolidation status. CAGRs derive from elasticity-adjusted volume projections against pricing tier trajectories. Industry-specific inputs include Pan-Philippine Highway freight expansion rates and BIS certification timeline compression effects on product launch velocity.
Sensitivities concentrate around Department of Energy fuel economy standard amendments, Singapore-South Korea base oil supply disruptions, and DENR waste oil regulation enforcement intensity. Forecasts embed assumptions regarding fleet operator consolidation trajectories and e-procurement platform penetration rates that material variance could revise. Quarterly review of BIS certification queue lengths, Singapore Strait freight indices, and provincial bus cooperative procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Forestry Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Food Grade Lubricant Market
Lubricants
Norway Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
ASEAN Lubricants Market