
 Global Acrylic Esters Market | 2026-2036
Global Acrylic Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Esters Market Intelligence
The market for acrylic esters is decoupling as specialty, high-purity grades for advanced applications like medical devices diverge from commodity-grade materials. Large-scale producers like Dow Inc. leverage extensive global supply chains to compete on cost for bulk-volume products. In contrast, Arkema S.A. specializes in performance-driven formulations for niche segments such as high-performance adhesives and textiles. BASF SE sustains its market position through significant R&D investment in novel polymer chemistries and sustainable feedstocks.
Acrylic esters are a family of chemicals derived from the esterification of acrylic acid with an alcohol. These reactive monomers, including key types like butyl acrylate and methyl acrylate, function as building blocks in polymerization processes to form various polymers and copolymers. Butyl acrylate represents a significant volume share due to its extensive use in water-based paints and coatings. The adhesives application segment, however, offers higher margin potential, particularly for specialized formulations used within the automotive and electronics industries.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH dictate permissible monomer content and safe handling protocols. In China, the Ministry of Ecology and Environment (MEE) enforces stringent standards on volatile organic compound (VOC) emissions, directly impacting the paints and coatings sector. Future profitability for producers hinges on their ability to develop and scale polymer platforms that comply with these divergent and evolving regional environmental mandates.
Market Dynamics
The acrylic esters market is defined by a structural bifurcation between high-volume, commodity-grade materials and high-purity, specialized grades. This divergence is driven by tightening environmental regulations and the performance demands of advanced applications like medical devices and electronics.
Growth Catalysts
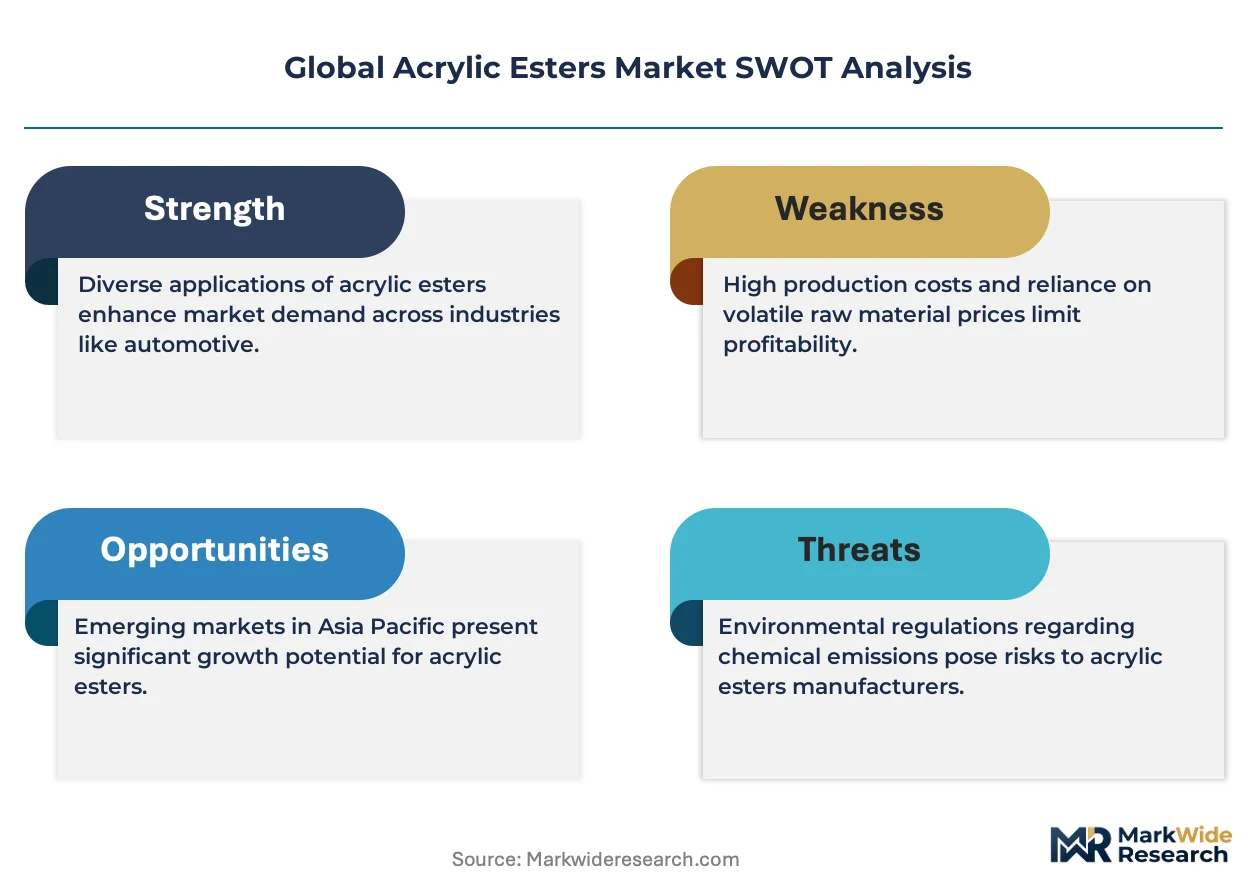
- Low-VOC Regulations:Strict limits on volatile organic compounds in paints from regulators like China's MEE are increasing demand for water-based acrylic ester formulations.
- Automotive Lightweighting:The automotive sector's use of lightweight composites and plastics necessitates acrylic ester adhesives for bonding, boosting consumption in assembly operations.
- Bio-Based Feedstocks:Development of bio-derived acrylic acid creates sustainable polymers that align with frameworks like the EU Green Deal and corporate ESG goals.
Market Restraints
- Feedstock Volatility:Price instability of propylene, the primary feedstock for acrylic acid, directly impacts production costs and creates margin uncertainty for manufacturers.
- Supply Chain Concentration:Heavy concentration of production capacity in China exposes global consumers to geopolitical risks and potential logistical bottlenecks.
- Regulatory Burden:The high cost and complexity of substance registration under Europe's REACH framework acts as a significant barrier to market entry.
Strategic Opportunities
- Medical-Grade Polymers:Developing high-purity acrylic esters for medical devices and diagnostic disposables offers access to a high-value application segment.
- Performance Textiles:Formulating specialized acrylic binders for non-woven textiles improves material durability and water resistance for industrial and consumer goods.
- Indian Construction Sector:India's expanding construction industry is a major target for water-based acrylic coatings, displacing traditional solvent-based paints.
Industry Challenges
- Specialized Talent Scarcity:A lack of polymer scientists and chemical engineers with expertise in developing novel, compliant chemistries constrains R&D and innovation pipelines.
- High Capital Expenditure:The construction of new, world-scale acrylic acid and ester production facilities requires immense capital investment, limiting capacity expansion to large incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Esters Market |
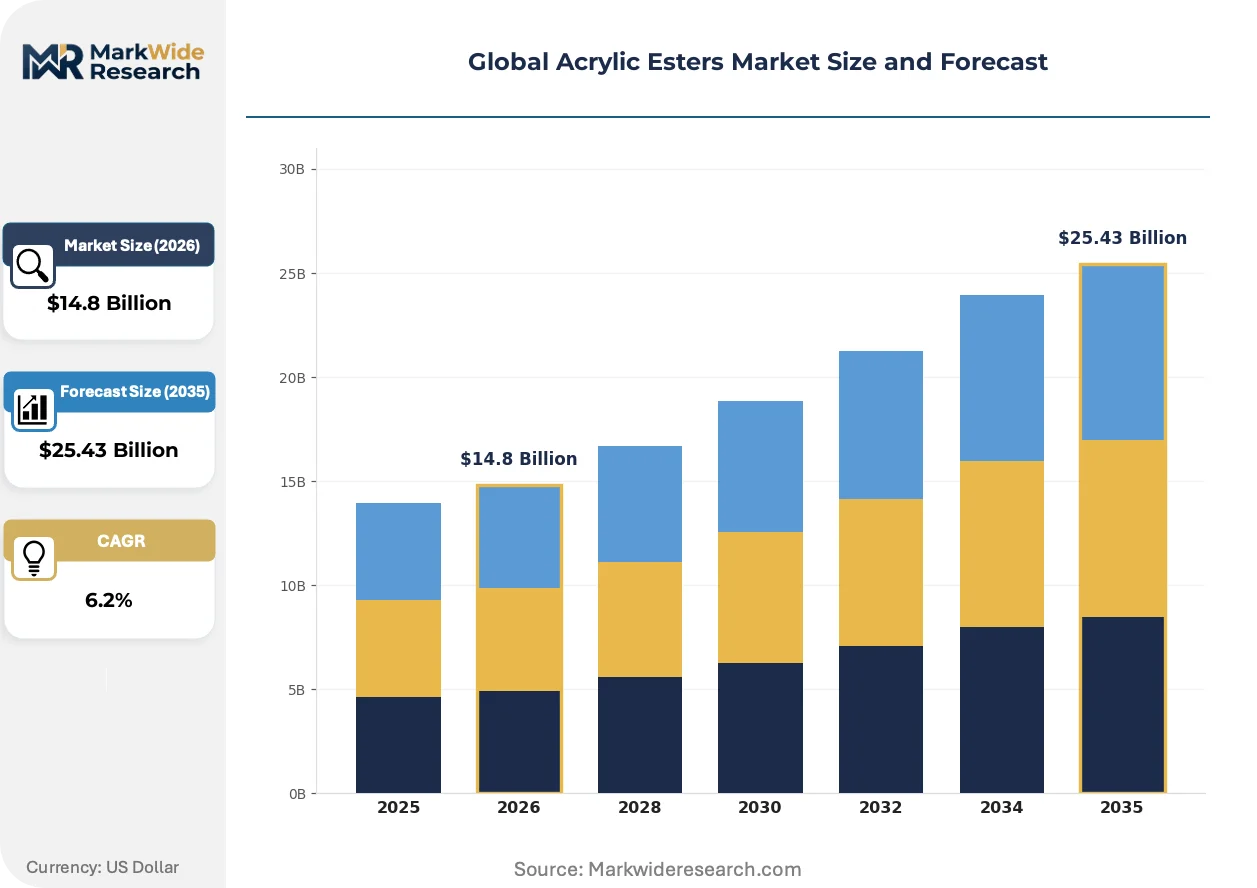
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Acrylate, Ethyl Acrylate, Methyl Acrylate, 2-Ethylhexyl Acrylate, Hydroxyethyl Acrylate Application: Adhesives, Paints & Coatings, Textile Finishing, Sealants, Printing Inks End User Industry: Construction, Packaging, Automotive OEMs, Consumer Goods, Electronics Packaging Type: Drums, Bulk Containers, IBC Totes, Flexible Bags, Bottles |
| Companies Covered | BASF SE, Dow Inc., Arkema S.A., Mitsubishi Chemical Corporation, Evonik Industries, LG Chem Ltd., Nippon Shokubai Co. Ltd., Formosa Plastics Corporation, Sasol Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Esters Market Strategic Shifts & Innovations
The acrylic esters market is evolving under dual pressures for enhanced performance and greater sustainability. This dynamic forces innovation in chemical synthesis, formulation science, and compliance with increasingly complex global environmental standards across all major producing regions.
High-throughput screening (HTS) platforms function as a critical tool in modern polymer discovery, allowing for rapid testing of numerous chemical combinations. Major chemical producers are now widely adopting HTS to shorten their R&D timelines for new materials. This advanced technology is automating the process of identifying novel monomer formulations that satisfy both stringent performance requirements and evolving regulatory standards.
Mandates such as the European Union’s Corporate Sustainability Reporting Directive (CSRD) represent a significant policy shift. This regulation compels producers to provide extensive disclosures on the environmental impact of their entire value chain, from feedstock sourcing to end-of-life. Chemical manufacturers in the EU are most affected, now integrating detailed life-cycle assessment data into their product documentation to prove compliance.
A notable shift in buyer behavior is the demand for application-specific formulation support over simple bulk chemical sales. This trend disrupts the traditional distributor-led model, favoring suppliers who provide deep technical collaboration and co-development services. This change is most prominent within the electronics adhesives sector, where material properties must be precisely tuned for advanced manufacturing processes.
Global Acrylic Esters Market Segmentation
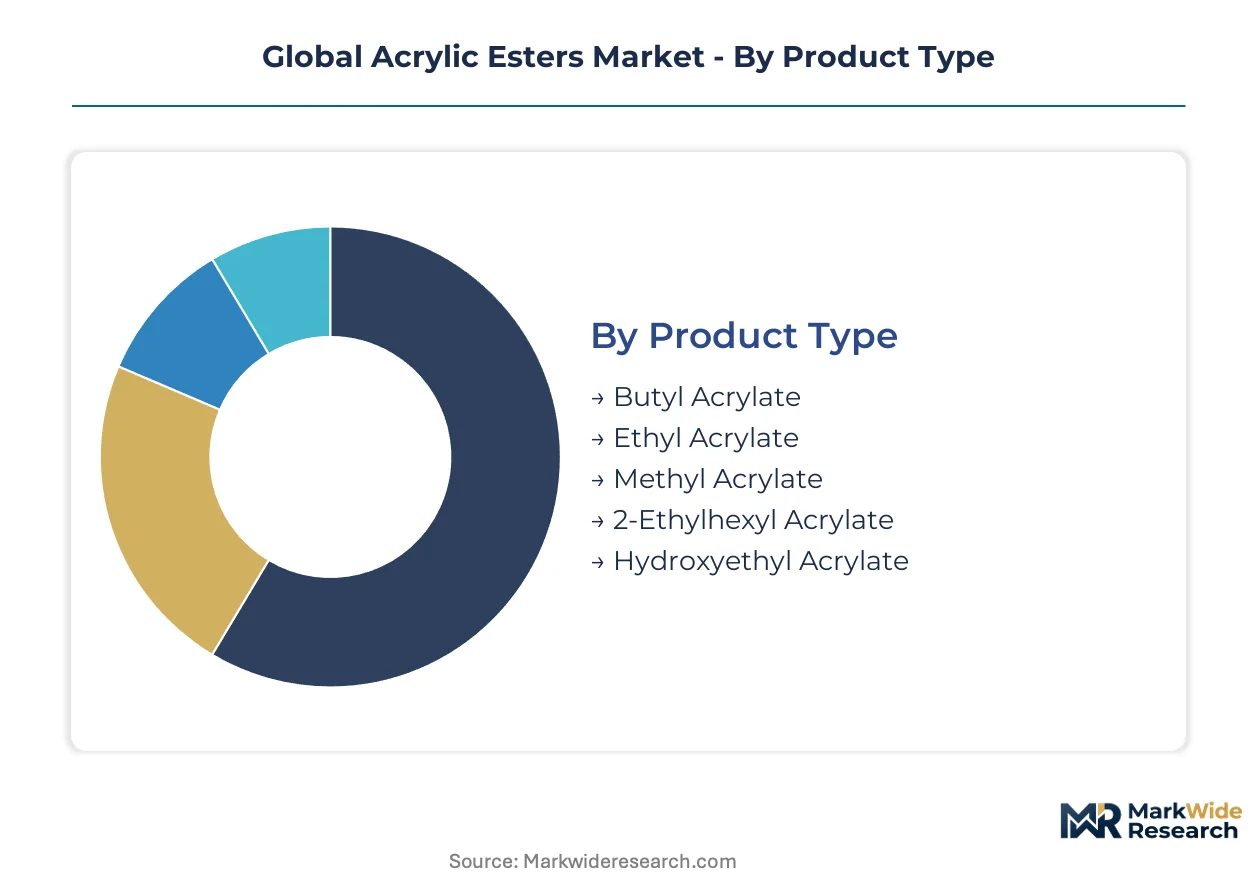
The acrylic esters market exhibits a nuanced structure, reflecting the diverse chemical properties and end-use requirements of these versatile monomers. Understanding this segmentation is critical for producers to align product development with specific application demands and regulatory compliance across various industries.
Product Type:
The customization-versus-standardization spectrum defines the product type segmentation, with some esters serving high-volume applications while others target specialized performance needs.
- Butyl Acrylate:This monomer is critical for manufacturing polymers used in water-based paints and coatings, offering flexibility and weather resistance. Demand is concentrating in China due to its extensive construction activities and the push for lower volatile organic compound formulations enforced by the MEE.
- 2-Ethylhexyl Acrylate:Known for imparting softness and flexibility to polymers, this ester finds use in pressure-sensitive adhesives and sealants. Its demand is increasing in medical device manufacturing within Europe, driven by stringent biocompatibility requirements from the EMA.
- Ethyl Acrylate:Used in textile finishing and paper coatings, this ester provides good adhesion and durability.
- Methyl Acrylate:A reactive monomer, it is employed in the production of polymers for plastics and synthetic fibers.
- Hydroxyethyl Acrylate:This specialty monomer enhances hydrophilicity and adhesion in various polymer systems, including contact lenses.
Most installed capacity flows through Butyl Acrylate. Expansion is steepest in 2-Ethylhexyl Acrylate.
Application:
Application segments for acrylic esters vary significantly in their margin potential and technical requirements, from high-volume commodity uses to niche, performance-driven formulations.
- Paints & Coatings:This segment represents the largest volume consumption for acrylic esters, particularly in architectural and industrial coatings. Strict environmental mandates from the US EPA and Europe's ECHA, focusing on low-VOC content, propel demand for water-based acrylic formulations.
- Adhesives:Acrylic esters provide strong bonding properties and weather resistance for various adhesive types, including pressure-sensitive and structural adhesives. This application offers higher margin potential, especially for specialized formulations required by the automotive and electronics industries.
- Textile Finishing:Acrylic esters enhance the durability, feel, and water resistance of fabrics for industrial and consumer textiles.
- Sealants:These compounds utilize acrylic esters for their flexibility, adhesion, and resistance to environmental factors in construction and automotive applications.
- Printing Inks:Acrylic esters contribute to the fast-drying properties and gloss of inks used in packaging and graphic arts.
The largest volume of acrylic esters is consumed by Paints & Coatings. Specialized acrylic formulations for Adhesives are gaining share fastest.
End User Industry:
Volume concentration across end-user industries dictates the scale and technical specifications for acrylic ester producers, influencing investment in production capacity.
- Construction:This industry is a primary consumer of acrylic esters, primarily for paints, coatings, and sealants used in residential and commercial buildings. Infrastructure development in India and Southeast Asia drives substantial demand for water-based acrylic coatings.
- Automotive OEMs:Acrylic esters are integral to adhesives and coatings for vehicle assembly, supporting lightweighting initiatives and improving durability. Manufacturers in Germany and Japan increasingly specify advanced acrylic adhesive systems for bonding composite materials.
- Packaging:Acrylic esters are used in coatings and adhesives for flexible and rigid packaging solutions, enhancing barrier properties and printability.
- Consumer Goods:This segment includes applications in household products, personal care items, and consumer electronics, where acrylic polymers provide various functional benefits.
- Electronics:Specialty acrylic adhesives and coatings protect sensitive electronic components and enable advanced manufacturing processes.
Construction remains the most established end-user industry. Demand from Electronics is exhibiting strong growth due to advanced material requirements.
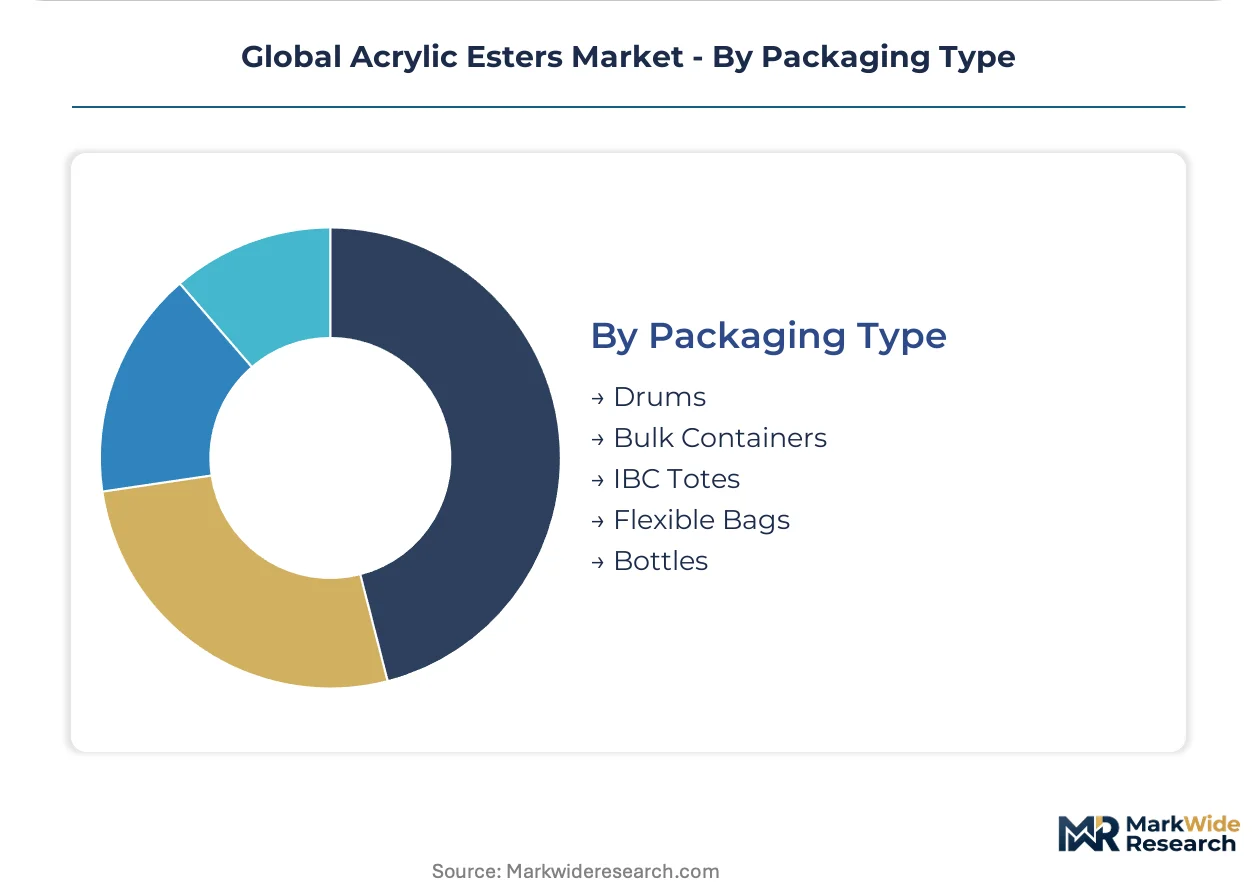
Packaging Type:
The efficiency of the supply chain significantly influences packaging choices, balancing transportation costs with product integrity and handling safety for acrylic esters.
- Bulk Containers:These large-volume containers, including ISO tanks and railcars, facilitate cost-effective transportation of acrylic esters for major industrial customers. Their use is prevalent for high-volume commodity grades shipped globally from production hubs in China.
- Drums:Standard 200-liter drums are widely used for intermediate quantities, offering flexibility for distribution to a broader range of industrial end-users. This packaging type is common for both commodity and some specialized grades across Europe.
- IBC Totes:Intermediate bulk containers provide a convenient solution for quantities larger than drums but smaller than full bulk shipments.
- Flexible Bags:Typically used for solid or powdered acrylic polymers, these bags offer lightweight and efficient storage.
- Bottles:Smaller bottles are reserved for highly specialized or laboratory-grade acrylic esters, where precision and purity are paramount.
Logistical efficiency favors Bulk Containers for large-scale shipments. Drums provide essential flexibility for regional distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A specialized talent concentration in polymer science and chemical engineering anchors significant innovation across key geographies. These regions drive both production capacity and demand for advanced acrylic ester formulations. Regulatory environments also profoundly shape regional market dynamics, particularly for low-VOC products.
China
Extensive construction activities and robust automotive manufacturing drive substantial demand for acrylic esters in China. The Ministry of Ecology and Environment (MEE) enforces stringent standards on volatile organic compound (VOC) emissions, propelling the shift to water-based coatings. Production capacity heavily concentrates in the Yangtze River Delta and Shandong Peninsula, supplying both domestic and international markets.
Germany
Germany's advanced manufacturing sector, particularly in automotive and specialty chemicals, fuels demand for high-performance acrylic ester formulations. The European Chemicals Agency (ECHA) under REACH dictates rigorous substance registration and safe handling protocols for chemical producers. Research and development hubs in North Rhine-Westphalia and Bavaria focus on novel polymer chemistries and sustainable feedstocks.
United States
The United States market sees demand from diverse applications, including paints, coatings, and adhesives for construction and industrial uses. The US Environmental Protection Agency (EPA) mandates strict limits on VOCs, accelerating the adoption of water-based acrylic solutions. Major chemical production facilities along the Gulf Coast and in the Ohio Valley serve as key supply centers.
India
India's expanding construction industry represents a significant target for water-based acrylic coatings, displacing traditional solvent-based paints. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for chemical products, influencing market entry and product formulation. Infrastructure development in Maharashtra and Gujarat creates substantial opportunities for acrylic ester consumption.
Japan
Japan's electronics and automotive sectors require high-purity acrylic esters for advanced adhesives and specialized coatings. The Ministry of Economy, Trade and Industry (METI) promotes innovation in sustainable materials and advanced manufacturing processes. Industrial clusters in the Kanto and Kansai regions focus on developing high-performance formulations for niche applications.
Global Acrylic Esters Market Key Industry Players
Top-tier vendors anchor the global acrylic esters market, while a diverse array of mid-sized and specialized producers serve niche segments. The market structure exhibits a tiered consolidation, with large incumbents leveraging economies of scale for commodity grades. Strategic archetypes include integrated chemical giants, specialty chemical providers, and regional manufacturers. Dominant competitive moves involve significant R&D investment in novel polymer chemistries and strategic partnerships for supply chain resilience.
Within the integrated chemical giant tier, BASF SE and Dow Inc. represent global leaders with extensive portfolios and manufacturing footprints. Arkema S.A. exemplifies a specialty chemical provider, focusing on performance-driven formulations for high-performance adhesives and textiles. These companies navigate complex regulatory frameworks and volatile feedstock markets, continuously adapting their product offerings to meet evolving application demands and sustainability goals.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema S.A. |
| Mitsubishi Chemical Corporation |
| Evonik Industries |
| LG Chem Ltd. |
| Nippon Shokubai Co. Ltd. |
| Formosa Plastics Corporation |
| Sasol Ltd. |
| Others |
Cost & Logistics Intelligence
High-throughput screening platforms are reshaping acrylic ester cost economics by accelerating novel monomer discovery and influencing production scale-up. This technological shift also impacts supply concentration through specialized formulation development.
Pricing Analysis
The bundled-versus-unbundled service split defines acrylic ester pricing, with specialized formulations often including extensive technical support alongside contract-based long-term off-take for commodity grades. Price differentiation stems from purity grade and after-sales formulation support. Pricing softness in commodity butyl acrylate reflects overcapacity in China. Electronics manufacturers are least price-sensitive for high-purity adhesives, while bulk paint producers are most sensitive.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by buyers for critical acrylic ester grades, especially in Europe and Japan. Geographic supply concentrates heavily in China, with significant production also in the US and Germany. The market relies on propylene as a primary feedstock for acrylic acid, creating a structural risk due to its commodity price volatility. Distribution runs through a mix of direct sales to large industrial customers and regional distributors for smaller volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic esters market presents a clear margin-expansion story, driven by the increasing demand for high-purity, specialized grades in advanced applications. This shift towards performance-driven formulations offers significant upside for producers.
For Market Incumbents: Anchor existing market share by investing in sustainable bio-based feedstocks to mitigate regulatory shifts like the EU Green Deal. Consolidate production capacity in strategic regions to counter emerging entrant archetypes. Deepen vertical integration into acrylic acid production to stabilize feedstock costs. Expand R&D into novel polymer chemistries for high-margin medical device applications.
For New Entrants and Emerging Players: Specialized distributors offer a pathway to penetrate niche segments like high-performance adhesives for electronics. Target the Indian construction sector with water-based acrylic coatings, which is the most penetrable application due to infrastructure development. Focus go-to-market efforts on offering application-specific formulation support, differentiating from bulk commodity suppliers. Develop high-purity 2-ethylhexyl acrylate for medical device manufacturing.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional commodity producers with older production assets. The long-term viability of acrylic esters remains robust over a 5-10 year window, driven by advanced material demand. Target specialty chemical providers with strong R&D pipelines in bio-based chemistries. A signal to watch is the increasing adoption rate of high-purity grades in medical devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing production facilities in China supports growing demand from the paints and coatings sector. |
| Green Manufacturing Transition | Adopting bio-based feedstocks aligns with EU Green Deal objectives and corporate ESG goals. |
| Joint Venture | Partnering for advanced R&D accelerates novel polymer chemistry development for niche applications. |
| Long-term Supply Agreement | Securing propylene feedstock contracts mitigates price volatility for acrylic acid producers. |
| Certification Investment | Achieving stringent biocompatibility standards opens access to the high-value medical device market. |
Research Approach
Direct dialogue with plant managers, procurement leads at OEM companies, distribution channel partners, and R&D directors provided primary insights. This was validated through secondary sources including customs data, ACC/Cefic reports, and SEC 10-K filings from major chemical producers. A bottom-up approach to market sizing was triangulated with top-down analyses.
A bottom-up analytical framework projected market volumes and values across the analysis window, validated by top-down market sizing. Segmentation dimensions modeled include product type, end-use industry, packaging format, and regional production hubs. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected demand drivers. Propylene price forecasts and construction spending projections served as key inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Deviation in global economic growth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Global Silica Flour Market