
 Nonene (Propylene Trimer) and Tetramer Market | 2026-2036
Nonene (Propylene Trimer) and Tetramer Market Size, Share, and Industry Trends Forecast 2026-2036
Nonene (Propylene Trimer) and Tetramer Market Intelligence
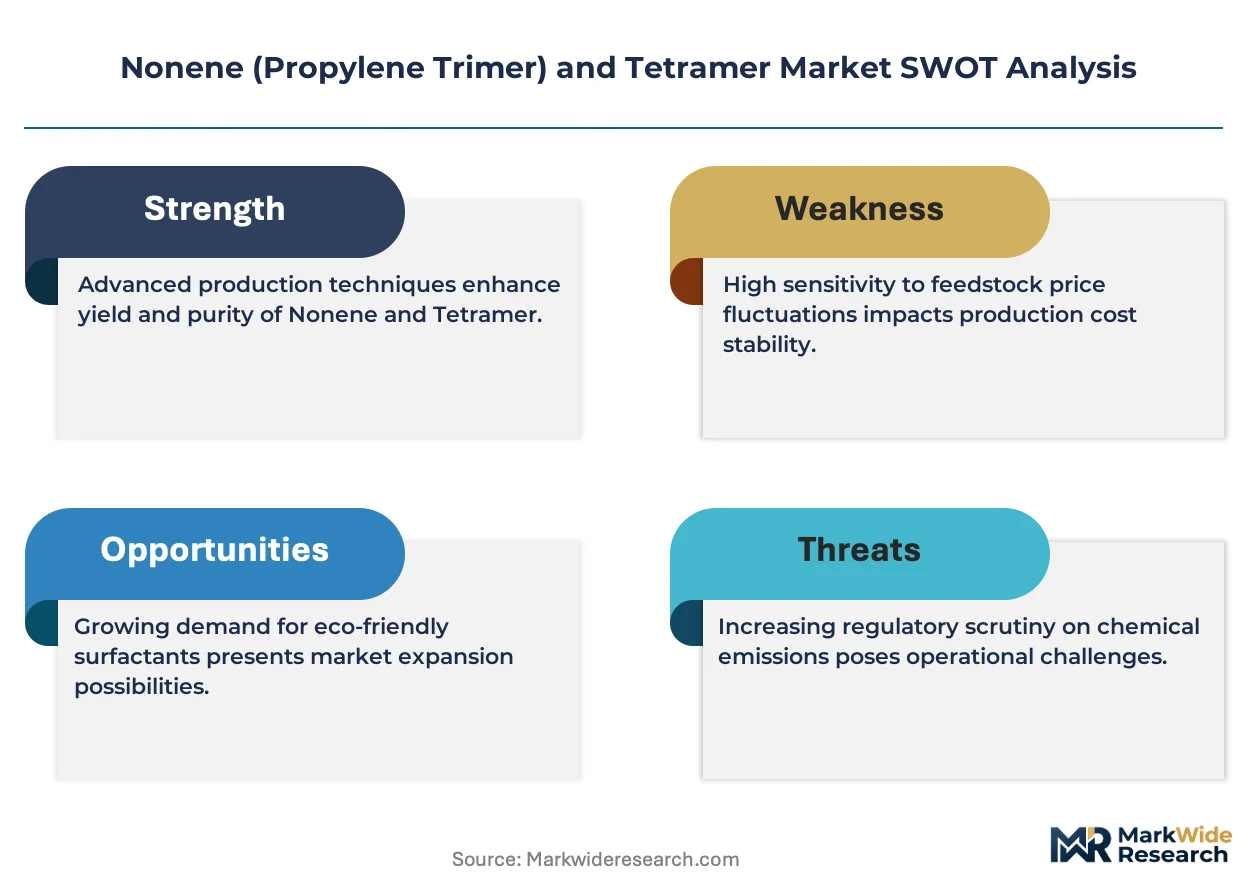
The phase-out of nonylphenol ethoxylates (NPEs) in favor of linear alkylbenzene sulfonates (LAS) and alcohol ethoxylates in industrial detergents is rebalancing the demand structure for propylene oligomers. ExxonMobil Corporation leverages its integrated petrochemical operations to manage feedstock volatility for nonene production. SABIC competes on a global scale through its extensive manufacturing footprint in the Middle East and Asia. Dow Chemical Company differentiates through its focus on specialty chemical derivatives for high-margin applications.
Nonene (propylene trimer) and tetramer (propylene tetramer) are branched olefins produced through the catalytic oligomerization of propylene. These C9 and C12 hydrocarbon streams serve as critical intermediates for synthesizing products like plasticizer alcohols, surfactants, and antioxidants. The lubricants application segment is expanding due to the need for high-performance synthetic oils in the automotive industry. In contrast, demand from the surfactants application is maturing in developed economies while growing in emerging markets.
Chemical safety regulations enforced by the EPA in the United States and ECHA in Europe govern the production and handling of propylene oligomers. In China, the Ministry of Ecology and Environment (MEE) imposes stringent standards on wastewater discharge from chemical plants, impacting operational costs. Future investment decisions will hinge on navigating feedstock price volatility and regional differences in environmental compliance mandates.
Market Dynamics
The market's central dynamic is the tension between volatile propylene feedstock costs and diverging environmental regulations. Stringent rules from the EPA in the US and ECHA in Europe create compliance costs that differ from standards in other manufacturing hubs, influencing investment and trade flows.
Growth Catalysts
- High-Performance Lubricants:The automotive industry requires advanced synthetic oils, driving demand for nonene and tetramer as essential additive precursors.
- NPE Replacement:Regulations phasing out nonylphenol ethoxylates in detergents create a direct substitution opportunity for nonene-derived surfactants.
- Feedstock Access:Expanded propylene capacity in China and the Middle East improves feedstock security and lowers production costs for oligomers.
Market Restraints
- Propylene Price Volatility:Propylene feedstock prices are linked to volatile crude oil markets, creating significant cost instability and margin pressure for producers.
- Alternative Surfactants:Linear alkylbenzene (LAB) is a mature, lower-cost alternative, constraining growth for nonene-based surfactants in price-sensitive detergent markets.
- Compliance Costs:Strict environmental rules, such as China's MEE wastewater limits, increase capital and operational expenditures for chemical manufacturing plants.
Strategic Opportunities
- Bio-based Feedstocks:Developing bio-based propylene sources offers a path to producing renewable nonene, appealing to customers with sustainability mandates.
- Growth in India:India's expanding automotive sector represents a significant growth opportunity for high-performance lubricants and specialty chemical additives derived from nonene.
- Advanced Catalysis:Catalyst innovation can enhance propylene oligomerization selectivity, increasing the yield of high-value nonene and improving overall process efficiency.
Industry Challenges
- High Capital Expenditure:The construction of new, world-scale propylene oligomerization plants demands significant capital investment, acting as a major barrier to market entry.
- Hazardous Material Logistics:Managing the complex supply chain for flammable liquids like nonene requires specialized transportation, storage infrastructure, and strict safety compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonene (Propylene Trimer) and Tetramer Market |
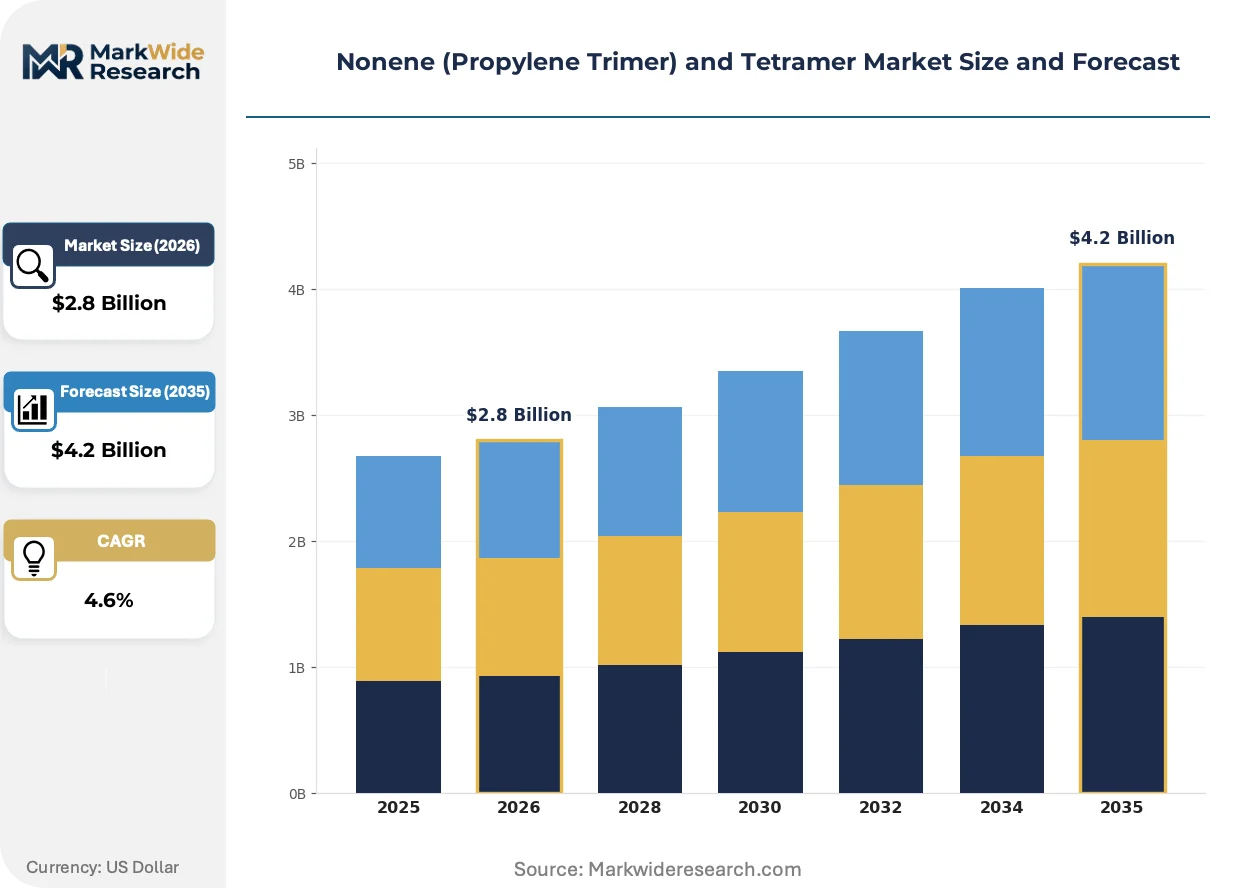
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonene-1, Nonene-2, Nonene-3, Nonene-4 Application: Surfactants, Plasticizers, Polymers, Lubricants End User: Automotive, Cosmetics, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Distributors, Online Retail, Trade Shows |
| Companies Covered | Braskem, PJSC Nizhnekamskneftekhim, ExxonMobil Corporation, LyondellBasell Industries, Dow Chemical Company, Shell, TPC Group, SABIC, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonene (Propylene Trimer) and Tetramer Market Strategic Shifts & Innovations
Process optimization and the pursuit of higher-value applications define the current market trajectory. Producers are moving beyond commodity streams, focusing on innovations that improve yield, meet stringent regulatory demands, and capture margin from specialized derivatives.
Advanced catalyst systems, including novel zeolites and improved solid phosphoric acid (SPA) catalysts, are enhancing propylene oligomerization. Petrochemical producers adopt these technologies to achieve higher selectivity towards desired C9 and C12 isomers. This focus on efficiency is consolidating the production landscape around operators who leverage superior catalyst technology to maximize yield and minimize byproducts.
The European Union's REACH regulation continues to impact the market through ongoing substance evaluation and registration. This framework mandates comprehensive safety data for chemicals like nonene, increasing compliance costs for producers and importers. Consequently, the European market emphasizes supply chain transparency and documented chemical safety, affecting all participants operating within the bloc.
A notable shift in purchasing is moving from cost-per-ton procurement to performance-based specifications, especially in the lubricants sector. End-users now demand nonene grades that deliver specific attributes like improved thermal stability in synthetic oils. This trend is most prominent in North American and European automotive industries where performance outweighs raw material cost.
Nonene (Propylene Trimer) and Tetramer Market Segmentation
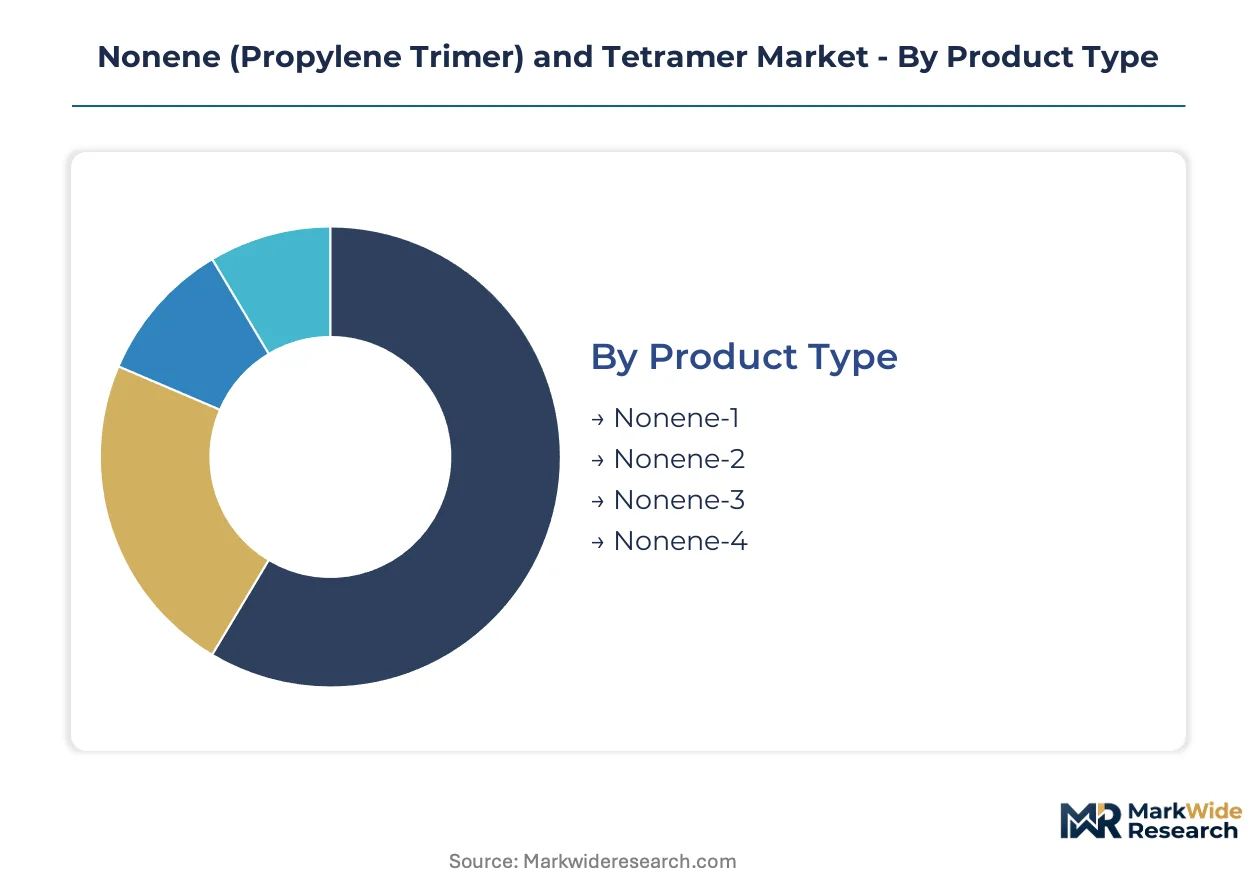
Understanding the distinct segments within the nonene and tetramer market allows producers to align product offerings with specific customer needs and regulatory requirements. This segmentation highlights the diverse applications and end-user demands driving innovation and production strategies for these critical chemical intermediates. Analyzing these categories provides a clearer picture of market dynamics and future growth trajectories.
Product Type:
The upgrade and replacement cycles in downstream chemical manufacturing drive the differentiation across various nonene product types.
- Nonene-1:This highly branched isomer is a key intermediate for certain plasticizer alcohols, contributing to the flexibility of PVC products. Demand for Nonene-1 is influenced by stringent EU REACH regulations on phthalate plasticizers, pushing for alternative formulations.
- Nonene-2:As a branched C9 olefin, Nonene-2 serves as a precursor for specific nonionic surfactants used in industrial detergents. The phase-out of nonylphenol ethoxylates in the United States and Europe directly increases demand for nonene-derived alternatives.
- Nonene-3:This isomer finds utility in specialty chemical synthesis, particularly for certain antioxidant formulations that protect polymers from degradation.
- Nonene-4:Nonene-4 is used in niche applications requiring specific branching structures, including some lubricant additives for high-performance engines.
Nonene-2 sits at the top of the volume ranking, with Nonene-1 climbing the fastest.
Application:
The cost-benefit analysis for end-product formulation influences the adoption across diverse applications for propylene oligomers.
- Lubricants:Nonene and tetramer are crucial for synthesizing high-performance synthetic base oils and additives, enhancing engine efficiency and longevity. The automotive industry's push for fuel economy and extended drain intervals in Germany and Japan drives significant demand.
- Surfactants:These oligomers form the backbone of various nonionic and anionic surfactants, essential for detergents, emulsifiers, and wetting agents. Emerging markets in India and China show robust demand as industrial and consumer cleaning sectors expand.
- Plasticizers:Nonene-derived alcohols are used to produce plasticizers that impart flexibility and durability to polymers, particularly in PVC products.
- Polymers:Nonene and tetramer can act as co-monomers or modifiers, improving specific performance characteristics of certain polymer formulations.
Lubricants applications exhibit significant growth, while surfactants maintain a broad market presence.
End User:
Customer-specific performance requirements dictate the tailored use of nonene and tetramer across various end-user industries.
- Automotive:This sector utilizes nonene and tetramer derivatives in engine lubricants, transmission fluids, and other functional fluids for vehicle performance. The transition to electric vehicles still requires specialized lubricants for gearboxes and thermal management systems.
- Agriculture:Nonene-based surfactants function as adjuvants and emulsifiers in agricultural formulations, improving the efficacy of pesticides and herbicides. Crop protection chemical producers in Brazil and Argentina depend on these intermediates.
- Cosmetics:Nonene derivatives are incorporated into personal care products as emollients, emulsifiers, and conditioning agents.
- Pharmaceuticals:The pharmaceutical industry uses these oligomers in specific excipients and intermediates for drug synthesis and formulation stability.
The automotive sector demonstrates robust consumption, with agriculture showing strong expansion in demand.
Distribution Channel:
The supply chain efficiency and regional market access shape the effectiveness of various distribution channels for nonene and tetramer.
- Direct Sales:Large-volume buyers, particularly integrated chemical manufacturers and major industrial end-users, procure nonene and tetramer directly from producers. This channel ensures consistent supply and tailored contractual agreements for companies like ExxonMobil.
- Distributors:Regional distributors play a vital role in reaching smaller and medium-sized enterprises, offering localized inventory, technical support, and logistical services. Companies in Southeast Asia often rely on distributors for chemical procurement.
- Online Retail:Niche chemical suppliers and researchers may source smaller quantities of specialized nonene grades through online platforms.
- Trade Shows:Industry trade shows facilitate business development, new product introductions, and networking opportunities between producers and potential buyers.
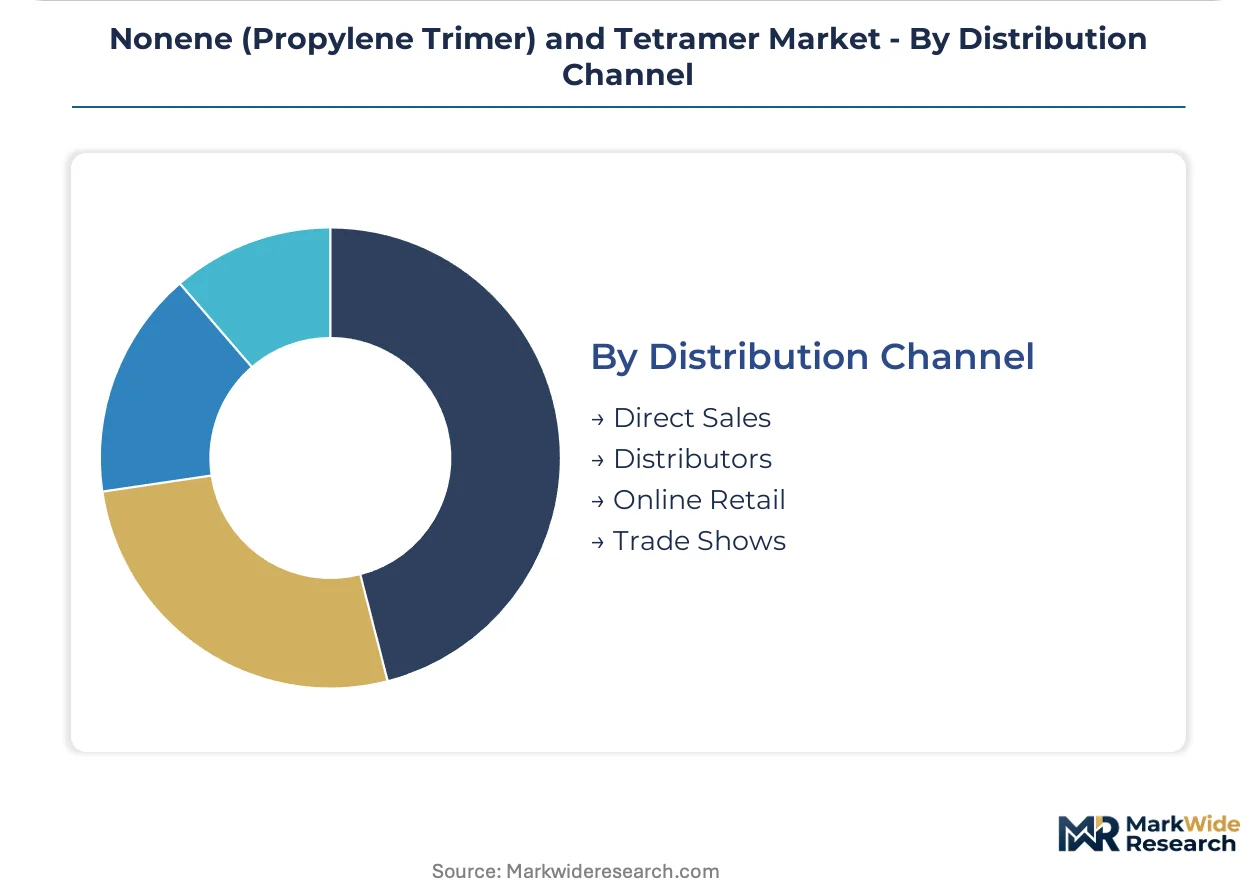
Direct sales channels handle the majority of bulk volumes, while distributors ensure widespread market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's key industrial clusters drive significant nonene and tetramer demand. The need for advanced synthetic base oils and surfactants fuels market expansion. Regulatory frameworks influence production costs and investment strategies across these regions.
United States
The United States experiences strong demand for high-performance lubricants within its automotive sector. EPA chemical safety rules necessitate compliant production processes for oligomers. The Gulf Coast petrochemical complex remains a central hub for nonene and tetramer manufacturing.
China
China's expanding industrial and consumer cleaning sectors contribute substantially to surfactant demand. The Ministry of Ecology and Environment (MEE) imposes stringent wastewater discharge standards on chemical plants. Chemical production in the Yangtze River Delta region drives significant domestic consumption.
Germany
Germany's automotive industry drives demand for nonene and tetramer as precursors for fuel-efficient lubricants. ECHA's REACH framework mandates comprehensive substance evaluation for market access. The Rhine-Ruhr industrial region concentrates chemical manufacturing and innovation.
India
India's automotive sector represents a significant growth opportunity for high-performance lubricants. BIS standards guide the quality and safety of chemical products in the country. Gujarat's chemical manufacturing zone is expanding its capacity for various chemical intermediates.
Saudi Arabia
Saudi Arabia benefits from secure propylene feedstock access, supporting large-scale oligomer production. Local industrial development policies encourage diversification into downstream chemical derivatives. Jubail Industrial City serves as a major export-oriented petrochemical hub.
Nonene (Propylene Trimer) and Tetramer Market Key Industry Players
Global majors compete with regional champions across feedstock integration and market reach. The market structure exhibits a tiered consolidation, from integrated petrochemical giants to specialized chemical manufacturers. Companies pursue capacity expansion, strategic partnerships, and portfolio diversification to secure market position.
Integrated petrochemical giants like ExxonMobil Corporation represent a global integrated player with extensive feedstock control. SABIC exemplifies a Middle Eastern chemical powerhouse through its extensive manufacturing footprint. LyondellBasell Industries occupies a position as a major polyolefin producer, leveraging its global operational scale.
| Leading Market Players |
|---|
| Braskem |
| PJSC Nizhnekamskneftekhim |
| ExxonMobil Corporation |
| LyondellBasell Industries |
| Dow Chemical Company |
| Shell |
| TPC Group |
| SABIC |
| Chevron Phillips Chemical Company |
| Others |
Cost & Logistics Intelligence
The automotive industry's demand for high-performance lubricants drives supply chain adjustments for nonene and tetramer, influencing pricing strategies. This pressure necessitates suppliers to ensure consistent quality and delivery, impacting overall market costs and competitive dynamics.
Pricing Analysis
Volatile propylene feedstock costs are directly passed through to nonene and tetramer pricing. The dominant pricing model is contract-based long-term offtake, ensuring supply stability for large buyers. Price differentiation stems from product purity grade and specialized geographic delivery costs. Pricing pressure stems from the availability of lower-cost alternative surfactants. The automotive sector demonstrates lower price sensitivity compared to price-sensitive detergent markets.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns manage the complex logistics of hazardous liquid chemicals like nonene. Supply concentration is prominent in China, the United States, and Saudi Arabia. The supply chain relies on propylene as its primary raw material. A structural risk is commodity price volatility in crude oil markets, impacting feedstock costs. Downstream distribution runs through direct sales channels for bulk volumes and regional distributors for smaller and medium-sized enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonene and tetramer market is a regulatory compounder, with the global phase-out of nonylphenol ethoxylates driving demand for compliant alternatives.
For Market Incumbents: Deploy integrated petrochemical operations to manage feedstock volatility and optimize production costs. Invest in advanced catalyst systems to enhance selectivity towards high-value nonene isomers. Counter the threat from alternative surfactants by emphasizing performance benefits in specialty applications. Expand capacity in regions with secure feedstock access, such as the Middle East, to mitigate supply chain risks.
For New Entrants and Emerging Players: Enter via bio-based propylene sources to appeal to customers with sustainability mandates. Target India's expanding automotive sector, which represents a highly penetrable segment for high-performance lubricants. Focus on niche specialty chemical derivatives for high-margin applications as a go-to-market angle. Leverage advanced catalysis to achieve process efficiency and product differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized chemical manufacturers focused on advanced catalysis and sustainable production methods. Long-term viability depends on navigating evolving environmental regulations and securing feedstock access over the next 5-10 years. Target companies with strong intellectual property in catalyst innovation or bio-based chemical processes. Watch for increased regulatory mandates on chemical sustainability as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases supply to meet growing demand from emerging markets and leverages regional feedstock availability. |
| Advanced Catalysis Investment | Enhances process efficiency and improves selectivity for high-value nonene and tetramer isomers. |
| Bio-based Feedstock Integration | Addresses sustainability mandates from end-users and diversifies raw material sourcing. |
| Strategic Partnerships in Lubricants | Secures long-term offtake agreements with major automotive and industrial lubricant producers. |
| Regulatory Compliance Upgrade | Ensures market access in stringent regions like Europe and the United States, mitigating operational risks. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each key industrial cluster. Interviews were conducted with plant managers, procurement leads at downstream OEMs, and technical R&D directors. Secondary data from trade associations, government reports, and company filings validated insights. Bottom-up and top-down triangulation ensured data integrity across all segments.
Market volume and value were modeled across product type, application, end-user, and distribution channel. The analytical framework projected compound annual growth rates throughout the forecast period, reflecting historical trends and anticipated shifts. Key forecast inputs included propylene capacity expansions in the Middle East and regulatory timelines for nonylphenol ethoxylate phase-outs.
The model holds under current geopolitical stability and feedstock supply conditions; deviation in crude oil prices or environmental policy would shift projections. Forecasts reflect documented assumptions regarding technological advancements and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Solketal Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market