
 Bulk Liquid Containers Market | 2026-2036
Bulk Liquid Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Liquid Containers Market Analysis
REACH compliance is repositioning material selection across European supply chains. Greif Inc. leverages its steel drum refurbishment network to lower lifecycle emissions for chemical clients. Mauser Packaging Solutions anchors its competitiveness through closed-loop IBC pooling systems across North America and Europe. SCHÜTZ GmbH & Co. KGaA dominates intermediate bulk container engineering with proprietary composite layering technology.
Bulk liquid containers are engineered vessels designed for transporting and storing non-hazardous and hazardous liquids in volumes typically exceeding 100 liters, constructed from high-density polyethylene, stainless steel, or multi-layer composites with UN-certified stacking and drop-test ratings. Their primary purpose centers on reducing per-unit logistics cost while preserving product integrity across multi-modal freight. Plastic IBCs now lead unit volume due to weight advantages in food-grade and chemical applications, though steel drums retain margin concentration in solvent and lubricant segments where thermal stability matters. Composite materials represent the fastest-expanding material category as manufacturers seek to bridge the durability gap between polymer flexibility and metal structural integrity.
The EPA governs hazardous waste container standards under RCRASubtitle C, while the FDA maintains cGMP requirements for food-contact surfaces; DOT regulations further dictate pressure-relief and stacking protocols for over-the-road tankers and drums. These overlapping frameworks raise compliance costs but also create product differentiation opportunities for certified suppliers. Stakeholders must track how California's SB 54 extended producer responsibility rules and pending EU Packaging and Packaging Waste Regulation amendments will reshape container return obligations and recycled-content thresholds.
Market Dynamics
The EU Green Deal's recycled-content mandates are forcing rapid material recertification across European chemical supply chains, while food-grade IBC pooling systems compress asset utilization rates in North American beverage logistics.
Growth Catalysts
- REACH compliance repositioning:Chemical processors in Germany and the Netherlands are accelerating composite IBC adoption to meet ECHA substance restrictions on legacy polymer formulations.
- Reusable fleet expansion:Food and beverage manufacturers are scaling closed-loop IBC networks to eliminate single-use packaging waste and reduce per-shipment container costs.
- Sustainability infrastructure concentration:Germany's dense chemical manufacturing base and established container refurbishment networks create demand pull for high-durability liquid handling systems.
Market Restraints
- Steel price volatility:Input cost swings for cold-rolled stainless steel directly squeeze margin stability in drum manufacturing for solvent and lubricant applications.
- Refurbishment capacity concentration:Steel drum reconditioning networks cluster in the US Rust Belt and Germany's industrial corridor, creating geographic supply risk for chemical clients elsewhere.
- Composite thermal limitation:Multi-layer polymer IBCs face performance ceilings in high-temperature chemical transport where metal vessels retain structural integrity.
Strategic Opportunities
- India chemical corridor penetration:Gujarat and Maharashtra's expanding specialty chemical clusters present underdeveloped demand for UN-certified intermediate bulk containers with local refurbishment support.
- California SB 54 tailwinds:Extended producer responsibility rules for plastic packaging create compliance-driven replacement cycles for single-use drums in West Coast food processing.
- RFID-telemetry convergence:Asset tracking integration with IoT pressure sensors enables predictive maintenance models for chemical fleet operators seeking to monetize container uptime data.
Industry Challenges
- Multi-jurisdiction certification lag:UN/DOT stacking test protocols, EPA RCRA Subtitle C hazardous waste standards, and FDA cGMP food-contact requirements impose overlapping compliance timelines that delay new product launches.
- Legacy ERP integration friction:Container pooling operators struggle to synchronize RFID-tagged asset data with customer inventory management systems built on decade-old warehouse software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Liquid Containers Market |
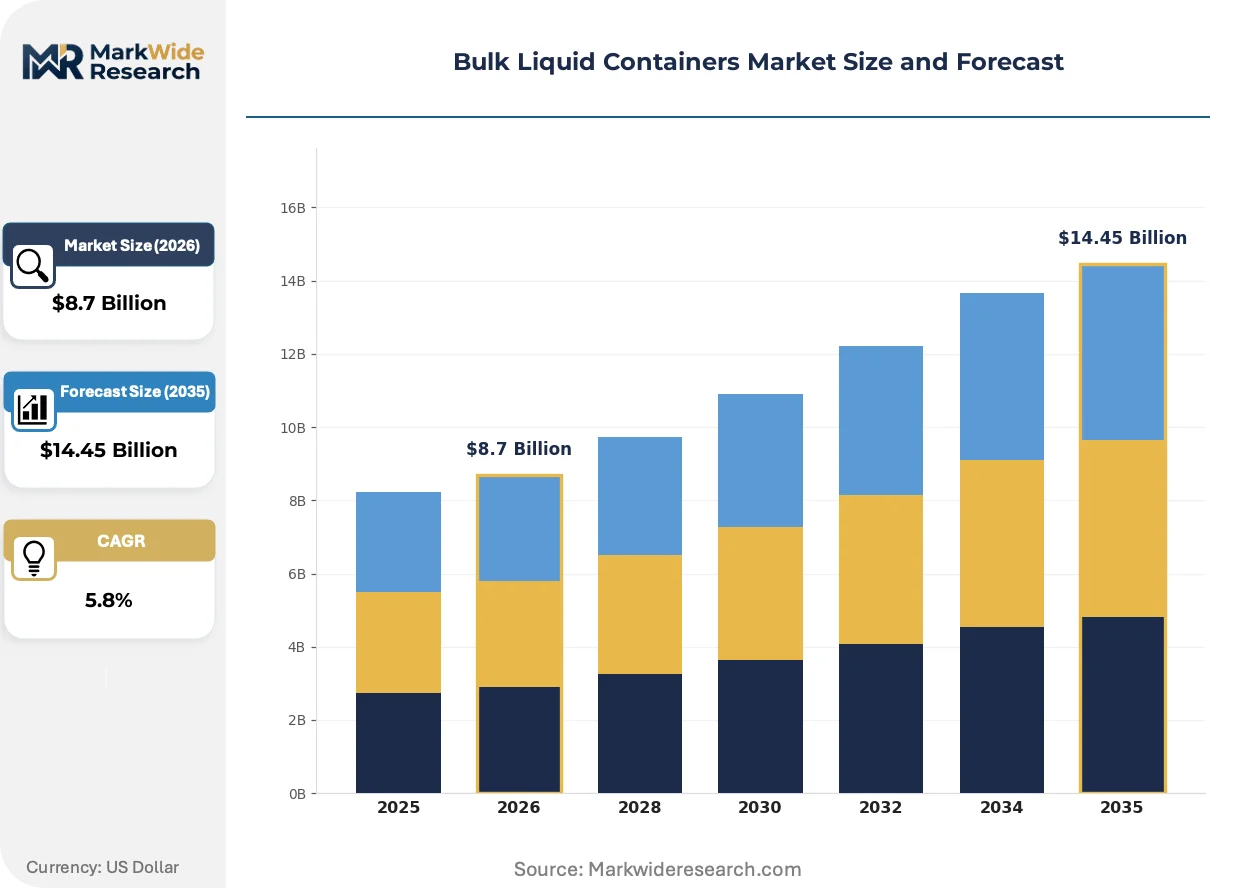
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Tote Tanks, IBCs, Drum Containers, Tankers Material: Plastic, Steel, Aluminum, Composite End User: Food & Beverage, Chemicals, Pharmaceuticals, Oil & Gas Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Greif Inc., Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, Berry Global, DS Smith, Mondi, Stolt Tank Containers, Hoyer Group, Pyramid Technoplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Liquid Containers Market Emerging Trajectories
Material science advances and regulatory tightening are converging to redefine competitive advantage in liquid containment, with durability standards and circularity metrics now outweighing unit price in procurement decisions.
Multi-layer composite IBC engineering is expanding into solvent and agrochemical applications previously dominated by steel drums. Specialty chemical distributors in the US Gulf Coast and Rotterdam port zones are piloting these vessels for corrosive intermediate transport. The technology is expanding into temperature-sensitive cargo segments where thermal bridging properties outperform single-material alternatives.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation amendments are tightening recycled-content verification requirements for industrial plastics. Chemical manufacturers must now document post-consumer resin percentages across container supply chains. German IBC producers are responding by vertically integrating into polymer recycling to secure certified feedstock streams.
Asset-light pooling models are displacing owned-container fleets among mid-sized food processors. Third-party IBC operators now bundle container supply, cleaning, and tracking into per-use fees that eliminate capital deployment. This shift concentrates most visibly in Benelux dairy and beverage corridors where logistics density supports rapid container turnaround economics.
Bulk Liquid Containers Market Segmentation
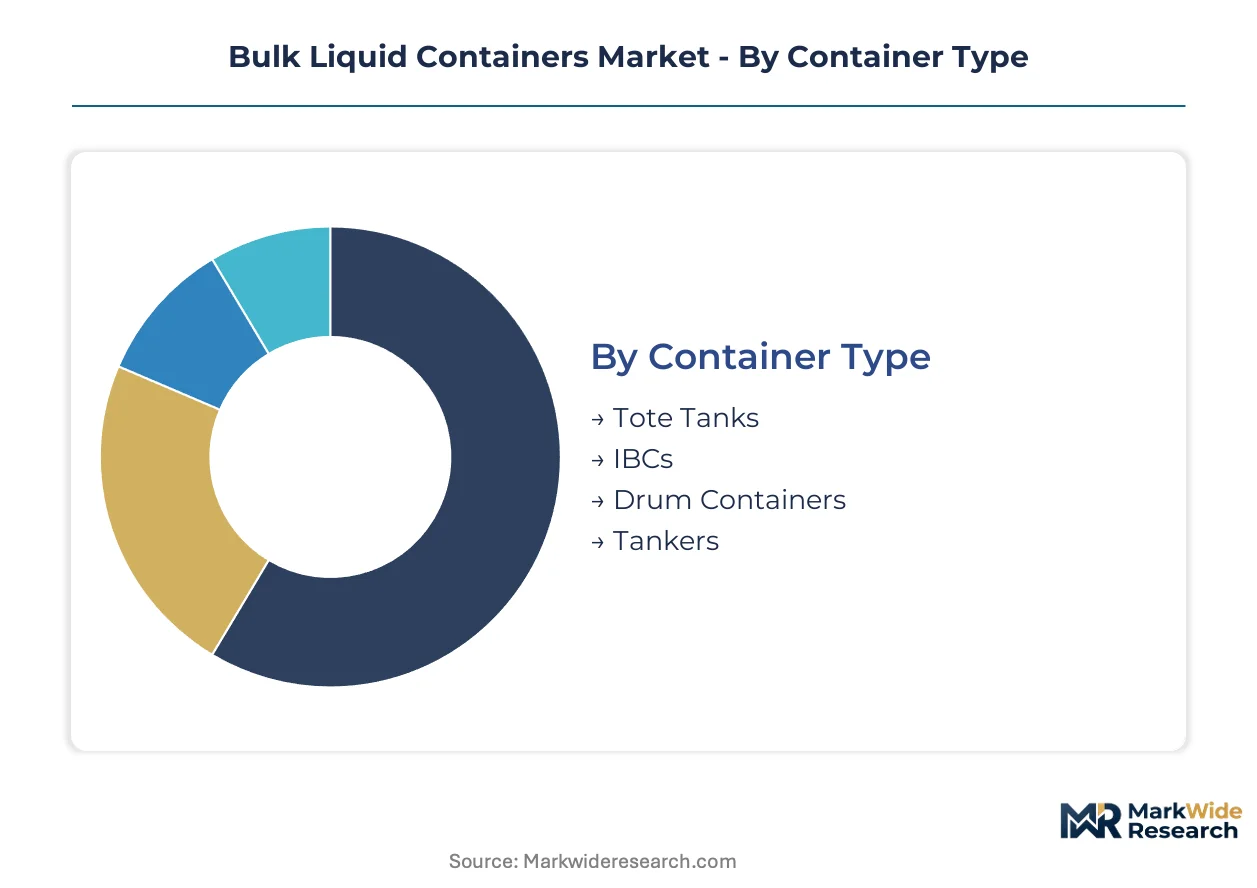
Container selection in bulk liquid logistics hinges on chemical compatibility, regulatory certification, and total cost of ownership across handling cycles. Procurement teams weigh material durability against weight efficiency and refurbishment economics when specifying fleet assets.
Container Type:
Volume requirements and handling infrastructure drive format selection, with chemical processors prioritizing UN certification tiers and food manufacturers emphasizing cleanability protocols.
- IBCs:Intermediate bulk containers combine 275-330 gallon capacity with forklift mobility and stackable geometry. Chemical distributors in Germany's Rhine-Ruhr corridor are expanding composite IBC fleets to meet ECHA substance restrictions while maintaining drop-test ratings. Food-grade pooling systems in the Netherlands compress turnaround times through shared cleaning infrastructure.
- Drum Containers:Standardized 55-gallon steel drums retain dominance in solvent and lubricant logistics where thermal stability and pressure tolerance exceed polymer capabilities. Cold-rolled stainless specifications face margin pressure from scrap price volatility, though refurbishment networks in the US Rust Belt extend asset lifecycles.
- Tote Tanks:Rigid polymer totes serve high-volume food ingredient transport with collapsible variants reducing backhaul empty miles.
- Tankers:Dedicated tank trailers and ISO tank containers handle bulk chemical and fuel movements across intermodal corridors.
IBCs lead on scale; composite IBCs lead on momentum.
Material:
Performance thresholds and circularity mandates reshape material procurement, with REACH compliance accelerating substitution away from legacy polymer formulations.
- Plastic:High-density polyethylene dominates food-grade and non-hazardous chemical applications through weight advantages and corrosion resistance. German producers are integrating post-consumer resin streams to satisfy EU Packaging and Packaging Waste Regulation verification requirements.
- Composite:Multi-layer constructions combining polymer liners with structural reinforcement bridge the durability gap between plastics and metals. Rotterdam and Houston specialty chemical handlers are piloting these vessels for corrosive intermediate transport previously reserved for steel.
- Steel:Cold-rolled and stainless grades retain structural integrity in high-temperature solvent logistics and pressure-rated applications.
- Aluminum:Lightweight alloys serve aerospace fuel containment and select pharmaceutical applications demanding non-magnetic properties.
Plastic commands unit volume; composite materials are climbing the fastest.
End User:
Regulatory stringency and contamination risk determine specification tiers, with pharmaceutical and food sectors imposing the most demanding surface finish and traceability standards.
- Chemicals:Specialty and commodity chemical processors require UN-certified containment for hazardous intermediates, with ECHA registration driving material recertification across European supply chains.
- Food & Beverage:Dairy and beverage manufacturers in Benelux corridors are displacing owned fleets with third-party IBC pooling to eliminate capital deployment and cleaning liability.
- Pharmaceuticals:cGMP-compliant containers with validated cleaning protocols support active pharmaceutical ingredient and excipient logistics.
- Oil & Gas:Lubricant and drilling fluid applications favor steel drum durability in remote extraction environments.
Chemicals anchor revenue concentration; food and beverage is gaining share fastest.
Distribution Channel:
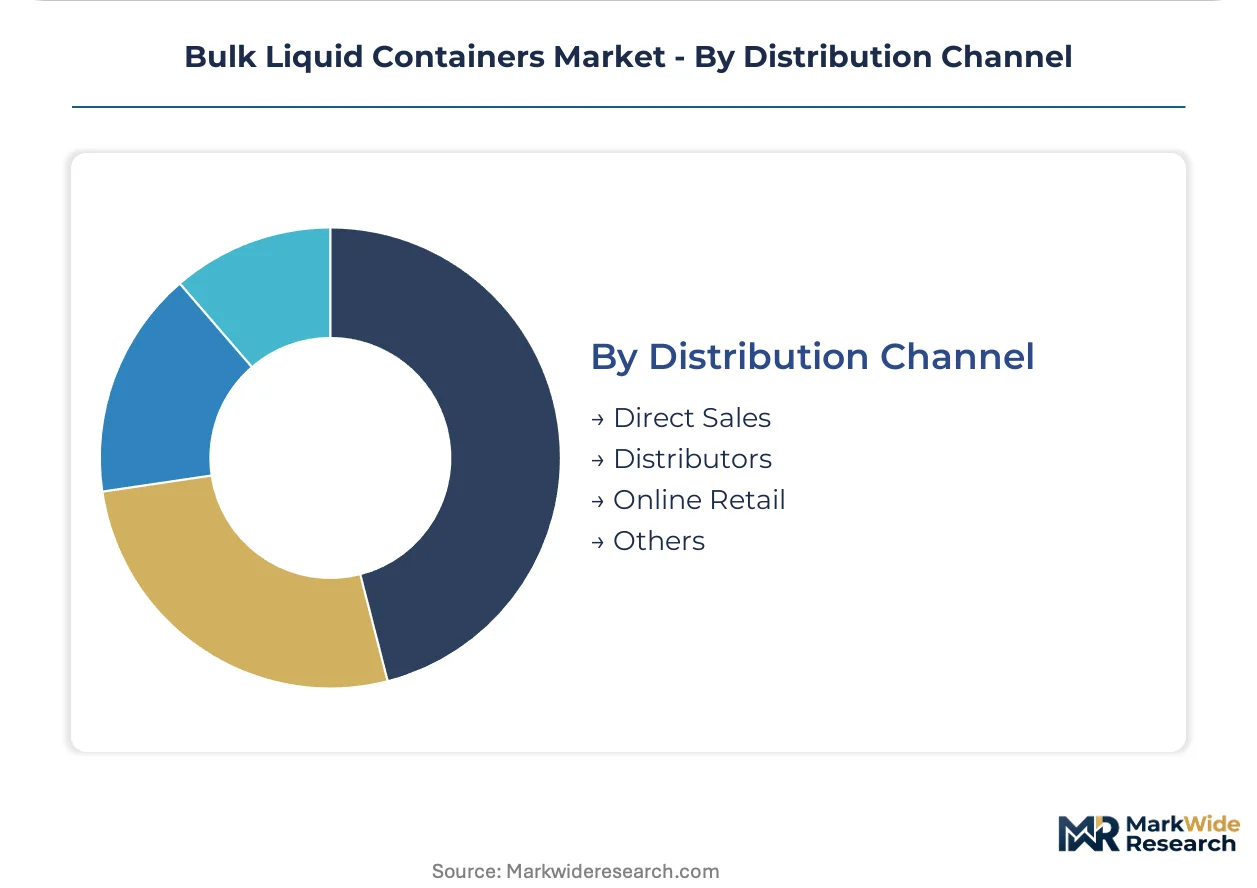
Customer scale and technical support requirements determine channel economics, with large chemical processors bypassing intermediaries while mid-sized operators rely on distributor inventory buffers.
- Direct Sales:Major chemical and food manufacturers negotiate fleet supply agreements with container producers for customized specifications and refurbishment scheduling.
- Distributors:Regional industrial supply networks stock standard drum and IBC formats for immediate availability to mid-sized processors.
- Online Retail:E-commerce platforms serve small-batch and replacement container demand with limited technical consultation.
- Others:Leasing and pooling operators bundle asset supply with logistics management for customers seeking capital avoidance.
Direct sales lead on contract value; pooling models show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers and Dutch logistics specialists anchor European demand for certified intermediate bulk containers, while US Gulf Coast petrochemical technicians and Indian process engineers drive adoption across Atlantic and Asian supply corridors.
Germany
Rhine-Ruhr chemical processors are expanding composite IBC fleets to satisfy ECHA substance restrictions under REACH. The EU Green Deal's recycled-content mandates are forcing rapid material recertification across container supply chains. BASF and Bayer facilities in Ludwigshafen and Leverkusen are piloting closed-loop pooling systems with integrated RFID tracking.
United States
Specialty chemical distributors along the Texas-Louisiana Gulf Coast are driving demand for UN-certified composite vessels in corrosive intermediate transport. EPA RCRA Subtitle C hazardous waste standards govern container specifications for petrochemical clients. Houston port logistics clusters are testing multi-layer IBCs for solvent applications previously reserved for steel drums.
India
Gujarat and Maharashtra specialty chemical clusters present underdeveloped demand for certified intermediate bulk containers with local refurbishment support. The country's national chemical regulator enforces BIS standards for hazardous material packaging. Reliance and UPL facilities in Dahej and Tarapur are evaluating composite IBC adoption for agrochemical export logistics.
Netherlands
Benelux dairy and beverage manufacturers are displacing owned fleets with third-party IBC pooling to eliminate capital deployment. EFSA food-contact regulations and national dairy board hygiene protocols govern container cleaning standards. Rotterdam port chemical handlers are piloting composite vessels for corrosive intermediate storage alongside traditional steel infrastructure.
China
Yangtze River Delta petrochemical complexes are scaling intermediate bulk container adoption for domestic chemical distribution. MIIT industrial standards and GB certification requirements shape container specifications for hazardous cargo. Shanghai and Ningbo port logistics zones are integrating RFID-tagged IBC fleets with smart warehouse management systems.
Bulk Liquid Containers Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive refurbishment networks and material science capabilities. Container producers cluster around three strategic archetypes: steel drum reconditioners leveraging circular economy credentials, composite engineers with proprietary layering technology, and pooling operators monetizing asset-light logistics models. Dominant competitive moves include backward integration into polymer recycling streams and geographic expansion through regional reconditioning partnerships.
Among North American and European fabricators, Greif Inc., Mauser Packaging Solutions, and SCHÜTZ GmbH & Co. KGaA occupy distinct positions within this structure. Greif represents the refurbishment-network archetype with steel drum lifecycle services. Mauser exemplifies the pooling-operator model across transatlantic corridors. SCHÜTZ anchors the composite-engineering tier with German manufacturing heritage. These three structures illustrate how certification depth, geographic density, and circular infrastructure separate competitive positions in liquid containment.
| Leading Market Players |
|---|
| Greif Inc. |
| Mauser Packaging Solutions |
| SCHÜTZ GmbH & Co. KGaA |
| Berry Global |
| DS Smith |
| Mondi |
| Stolt Tank Containers |
| Hoyer Group |
| Pyramid Technoplast |
| Others |
Supply Flow & Price Mechanics
Large chemical processors in Germany's Rhine-Ruhr corridor dominate procurement volume and dictate contract structures that bundle container supply with refurbishment services into long-term agreements.
Pricing Analysis
Per-use pooling fees separate from outright purchase pricing. Premium-mid-economy pricing differentiation rests on UN certification tier and RFID integration depth. Cost compression in standard-grade steel drums intensifies because cold-rolled stainless scrap volatility squeezes fabricator margins. Small food processors exhibit acute price sensitivity while pharmaceutical multinationals prioritize validated cleaning protocols over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese high-density polyethylene resin suppliers feeding European composite IBC manufacturers. Cold-rolled stainless steel draws from German and Japanese mills while polymer liners source from South Korean petrochemical complexes. Tariff exposure on Chinese resin imports threatens margin stability for Rotterdam-based container assemblers. Distribution runs through regional refurbishment hubs in Germany's industrial corridor and the US Rust Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as circular economy mandates across the EU and North America force replacement cycles for legacy single-use packaging fleets.
For Market Incumbents: Anchor market position by deepening captive refurbishment networks in underpenetrated Indian chemical corridors and accelerating composite material R&D to offset REACH-driven polymer substitution costs. Composite IBC specialists threaten steel drum incumbents in solvent applications. For New Entrants and Emerging Players: Launch via asset-light pooling partnerships targeting mid-sized Benelux dairy processors seeking capital avoidance. Gujarat specialty chemical clusters present the most penetrable geography. Differentiate through IoT-enabled container tracking bundled into per-use fees. For Investors and Strategic Acquirers: Packaging logistics platforms are the most active acquirer in this space, consolidating regional reconditioning networks to capture circular economy service revenue. Five-to-ten-year viability hinges on regulatory tailwinds for reusable packaging. Target container pooling operators with established RFID infrastructure. Watch EU Packaging and Packaging Waste Regulation enforcement timing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Recycling | German IBC producers secure certified post-consumer resin streams under EU Green Deal mandates. |
| RFID-Telemetry Fleet Integration | Pooling operators monetize uptime data for chemical clients through predictive maintenance algorithms. |
| Regional Refurbishment Partnership | Western suppliers establish local reconditioning in Gujarat to serve Reliance and UPL export logistics. |
| Composite Material Scale-Up | Rotterdam handlers pilot multi-layer vessels for corrosive intermediates previously requiring steel drums. |
| Closed-Loop Pooling Expansion | Benelux dairy manufacturers eliminate capital deployment through third-party IBC cleaning and tracking services. |
Methodological Framework
Direct dialogue with container fleet managers, chemical procurement leads, food-grade logistics coordinators, and refurbishment network operators grounded qualitative findings in operational reality. Secondary validation drew from customs trade databases, SEC filings of listed packaging producers, ECHA substance restriction updates, and EU Packaging and Packaging Waste Regulation draft texts. Bottom-up unit economics and top-down sector sizing triangulated market estimates.
Bottom-up modeling tracked IBC, drum, and tote tank unit shipments across material grades and end-use verticals. Top-down analysis cross-referenced chemical production volumes against container intensity ratios by logistics format. CAGRs emerged from segmented growth rate blending across the projection horizon. Forecast inputs included REACH compliance timelines, California SB 54 implementation phases, and steel scrap price trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt tariff shifts on Chinese resin or accelerated EU recycled-content mandates. Container pooling adoption rates and refurbishment network buildout speeds represent key assumption sensitivities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market