
 Mexico Calcium Carbonate Market | 2026-2036
Mexico Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Calcium Carbonate Market Foresight
Modular packaging configurations is broadening buyer choice across the Mexico calcium carbonate market. Imerys leverages its specialized product lines to serve high-specification coatings customers in Guanajuato and Querétaro. Minerals Technologies Inc. anchors its position through captive limestone reserves and integrated grinding capacity in northern Mexico. Omya AG competes by controlling bulk bag and small bag distribution channels that reach mid-size plastics compounders.
Calcium carbonate is a naturally occurring mineral compound of calcium, carbon, and oxygen, typically processed to purity levels exceeding 98% calcium carbonate content through wet or dry grinding of limestone or precipitated via carbonation of calcium hydroxide slurry. It functions primarily as a functional filler, whitener, and cost-reducing extender across paper, plastics, coatings, and construction formulations. Ground calcium carbonate dominates volume flows into Mexico's paper and construction sectors, where cost-performance ratios favor uncoated, high-brightness grades. Precipitated calcium carbonate commands premium positioning in plastics and coatings applications requiring controlled particle size distribution and surface area. Coated calcium carbonate occupies a narrower but higher-margin niche serving automotive and specialty packaging films where dispersion and polymer compatibility determine specification compliance.
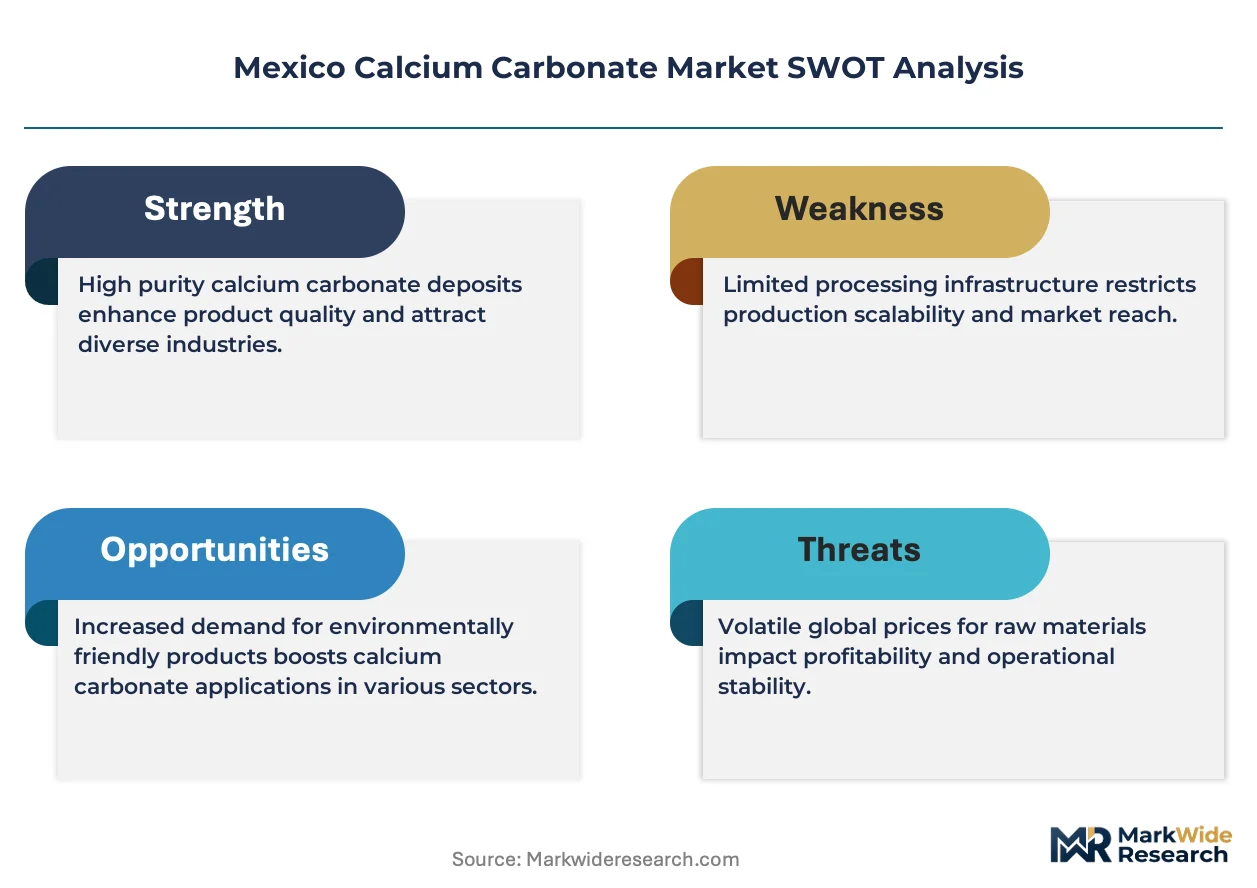
SEMARNAT environmental standards govern quarry permitting and emissions controls for limestone extraction operations, while NOM-001-SECRE-2010 establishes minimum quality thresholds for construction-grade calcium carbonate used in cement and concrete. PROFECO consumer protection regulations extend to labeling and weight accuracy for retail-packaged mineral additives sold through distributor and retail channels. Stakeholders must monitor pending updates to Mexican Official Standards for industrial minerals and assess how carbon border adjustments in key export markets could reshape competitiveness of domestically processed filler grades.
Market Dynamics
SEMARNAT quarry permitting bottlenecks and NOM-001-SECRE-2010 certification requirements are compressing supply elasticity for construction-grade calcium carbonate in central Mexico. These regulatory layers favor operators with integrated limestone reserves and captive grinding assets.
Growth Catalysts
- Construction sector expansion:Cement and concrete applications in Mexico City and Puebla industrial corridors drive ground calcium carbonate consumption for residential and infrastructure projects.
- NOM-001-SECRE-2010 compliance:Mandatory quality thresholds for building materials create certification barriers that reward established domestic producers with testing infrastructure.
- Plastics compounding growth:Precipitated calcium carbonate with controlled particle size distribution penetrates automotive and specialty packaging films in Guanajuato and Querétaro manufacturing zones.
Market Restraints
- Limestone reserve concentration:Captive quarry access in northern Mexico limits new entrant supply security and raises barrier to scale.
- Energy cost volatility:Wet and dry grinding operations face input cost pressure from Mexican electricity tariffs and natural gas pricing.
- Substitute filler competition:Talc and kaolin alternatives capture share in coatings applications where surface chemistry requirements permit mineral substitution.
Strategic Opportunities
- Coated calcium carbonate niche:Automotive and specialty packaging films in central Mexico offer premium-margin positioning where dispersion and polymer compatibility determine specification compliance.
- PROFECO retail channel:Consumer protection regulations for labeling and weight accuracy create structured distributor opportunities for packaged mineral additives.
- Carbon border preparation:Process efficiency investments position Mexican processors for competitiveness in export markets implementing embodied carbon adjustments.
Industry Challenges
- SEMARNAT permitting timelines:Environmental impact assessments for limestone extraction create multi-year delays between reserve identification and commercial production.
- Particle engineering talent:Precipitated calcium carbonate operations require specialized process engineers for carbonation reactor optimization and surface modification chemistry.
- Legacy grinding asset integration:Wet grinding capacity retrofitting for high-brightness paper grades demands capital deployment with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Calcium Carbonate Market |
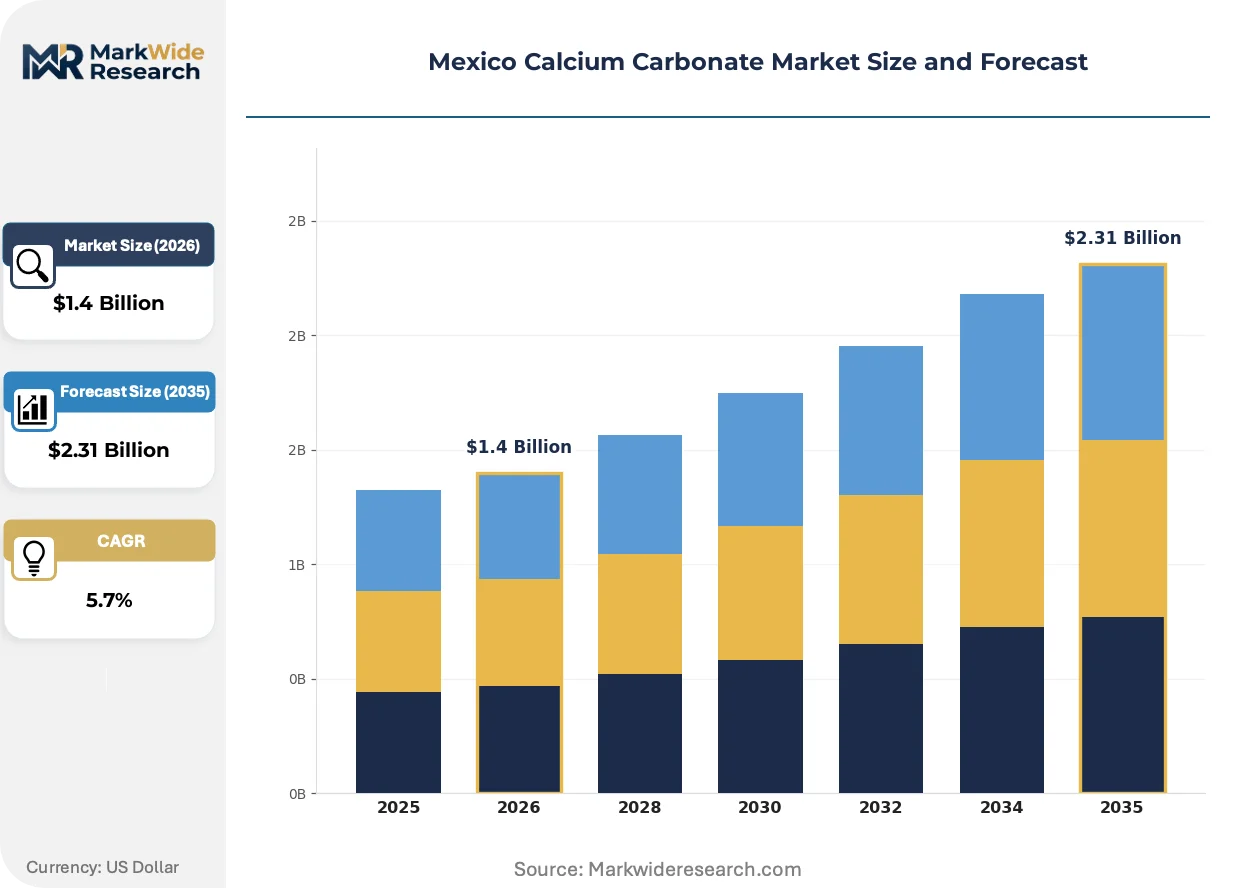
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Calcium Carbonate, Precipitated Calcium Carbonate, Coated Calcium Carbonate, Mineral Additives End Use Industry: Paper, Plastics, Coatings, Construction Packaging Type: Bulk Bags, Small Bags, Drums, Pails Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Imerys, Minerals Technologies Inc., Omya AG, Sibelco, J.M. Huber Corporation, Calidra, Lhoist, Vitro, C. Cales de Lampa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Calcium Carbonate Market Shifts & Advancements
Surface modification chemistry and particle size engineering are redefining specification boundaries between commodity ground calcium carbonate and premium precipitated grades. Mexican producers are investing in controlled carbonation and coating lines to capture margin expansion.
Coated calcium carbonate with tailored surface treatments is expanding into automotive interior films and barrier packaging where polymer compatibility and dispersion stability command price premiums. Tier-one automotive suppliers in Querétaro are qualifying these grades for instrument panel and door trim applications. The technology is expanding into specification tiers previously served by precipitated calcium carbonate, compressing the traditional grade hierarchy.
SEMARNAT emissions controls for limestone quarrying and processing operations are tightening particulate matter thresholds for extraction permits. Industrial consequence includes accelerated capital deployment in baghouse filtration and wet suppression systems at northern Mexico grinding facilities. Central Mexico operations with dated environmental infrastructure face compliance-driven modernization timelines or volume constraints.
Buyers in the paper and plastics sectors are consolidating supplier relationships around integrated producers offering technical service and specification customization. Mid-size compounders previously served through distributor networks now contract directly with Imerys and Minerals Technologies Inc. for volume commitments and joint development programs. This concentration is most visible in the Mexico City-Puebla corridor where logistics optimization favors single-source arrangements over fragmented procurement.
Mexico Calcium Carbonate Market Segmentation
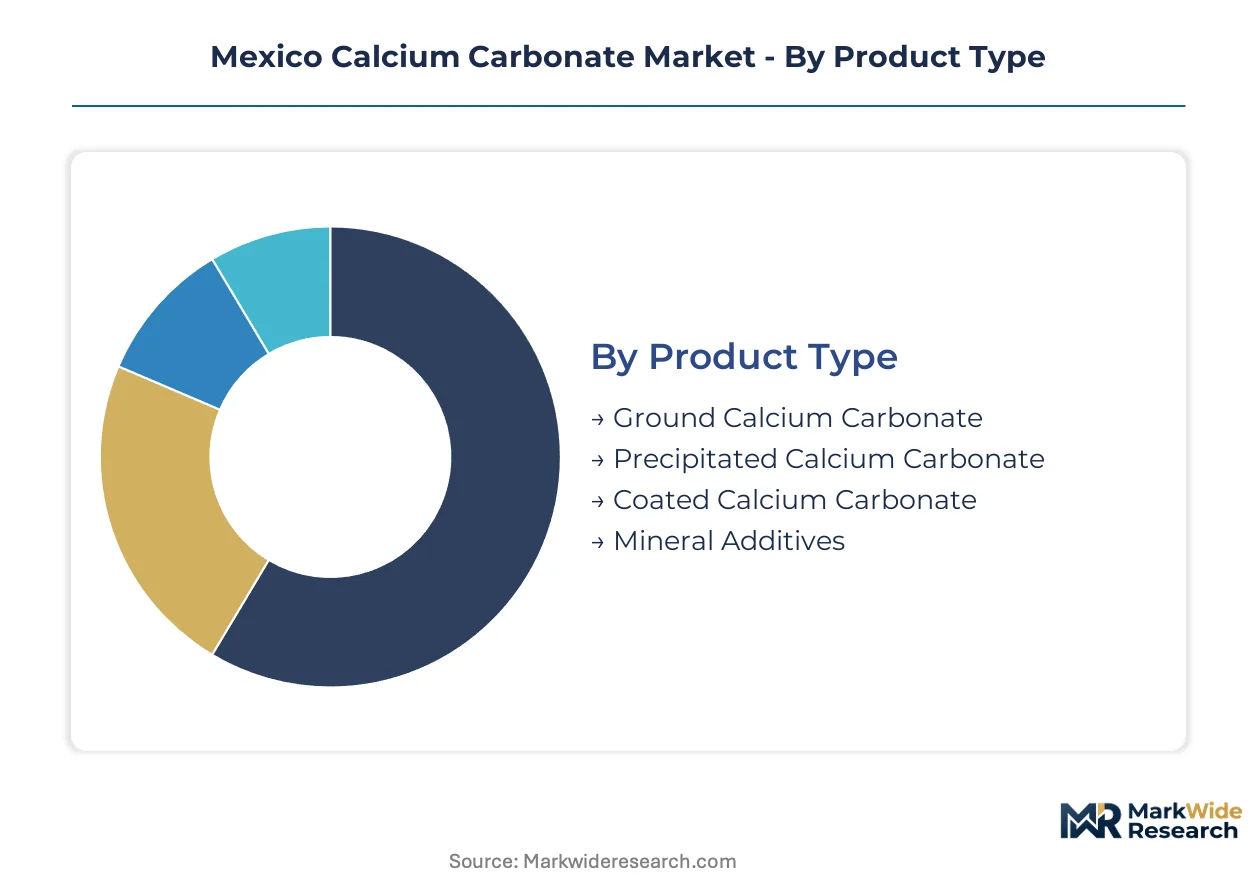
Calcium carbonate segmentation in Mexico reflects a bifurcation between high-volume commodity flows and specification-driven premium grades. Product type determines margin structure, while end-use concentration shapes regional supply chain configuration across central and northern production zones.
Product Type:
Ground calcium carbonate dominates tonnage flows, while precipitated and coated variants capture margin premiums through particle engineering capabilities.
- Ground Calcium Carbonate:Produced through dry or wet grinding of limestone to purity levels exceeding 98%, this grade serves as the primary functional filler for Mexico's cement and concrete sectors. Demand concentrates in the Mexico City-Puebla corridor where residential and infrastructure projects consume uncoated, high-brightness grades for cost-performance optimization in building materials.
- Precipitated Calcium Carbonate:Manufactured via carbonation of calcium hydroxide slurry, this grade delivers controlled particle size distribution and surface area specifications required by automotive and specialty packaging films. Guanajuato and Querétaro manufacturing zones drive qualification programs for instrument panel and barrier film applications where polymer compatibility determines supplier selection.
- Coated Calcium Carbonate:Surface-modified variants with tailored treatments penetrate specification tiers previously served by precipitated grades, compressing traditional grade hierarchies in automotive interior applications.
- Mineral Additives:Blended formulations incorporating calcium carbonate as a base component serve retail-packaged construction and DIY channels under PROFECO labeling regulations.
Mature deployment sits with ground calcium carbonate in bulk construction applications. Newer deployment is concentrated in coated and precipitated grades serving automotive and barrier packaging films.
End Use Industry:
Construction absorbs the largest volume share, while plastics and coatings deliver the steepest expansion trajectory through specification upgrading.
- Paper:Uncoated ground calcium carbonate functions as a cost-reducing extender and whitener in paper formulations, with procurement consolidating around integrated producers offering technical service and joint development programs.
- Plastics:Precipitated and coated grades with engineered particle size distribution penetrate automotive compounds and specialty packaging films in Querétaro manufacturing clusters where dispersion stability commands price premiums.
- Coatings:Talc and kaolin alternatives capture share in surface chemistry-sensitive applications, though calcium carbonate maintains position in cost-driven architectural and industrial coatings formulations.
- Construction:Ground calcium carbonate serves as the dominant functional filler for cement and concrete applications under NOM-001-SECRE-2010 quality thresholds, with demand anchored in central Mexico infrastructure and residential development.
Volume leadership resides with construction-grade consumption. Value expansion is accelerating fastest in plastics compounding for automotive and barrier packaging specifications.
Packaging Type:
Packaging configuration aligns with customer scale and application sensitivity, from bulk industrial flows to precision retail formats.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve paper mills and cement producers with dedicated pneumatic unloading systems, optimizing logistics for high-volume ground calcium carbonate movements.
- Small Bags:Twenty-five to fifty-kilogram woven polypropylene units reach mid-size plastics compounders and coatings formulators through distributor networks, with Omya AG controlling critical channel access in central Mexico.
- Drums:Fiber or steel containers protect moisture-sensitive precipitated and coated grades during transport to specialty film manufacturers requiring specification integrity.
- Pails:Retail-format plastic containers serve PROFECO-regulated consumer channels for mineral additives in DIY construction and home improvement applications.
Industrial-scale procurement favors bulk bag formats with dedicated handling infrastructure. Small bag and pail configurations are expanding through distributor and retail channels serving fragmented end-user bases.
Distribution Channel:
Channel structure reflects customer consolidation patterns, with direct relationships displacing fragmented procurement in high-volume corridors.
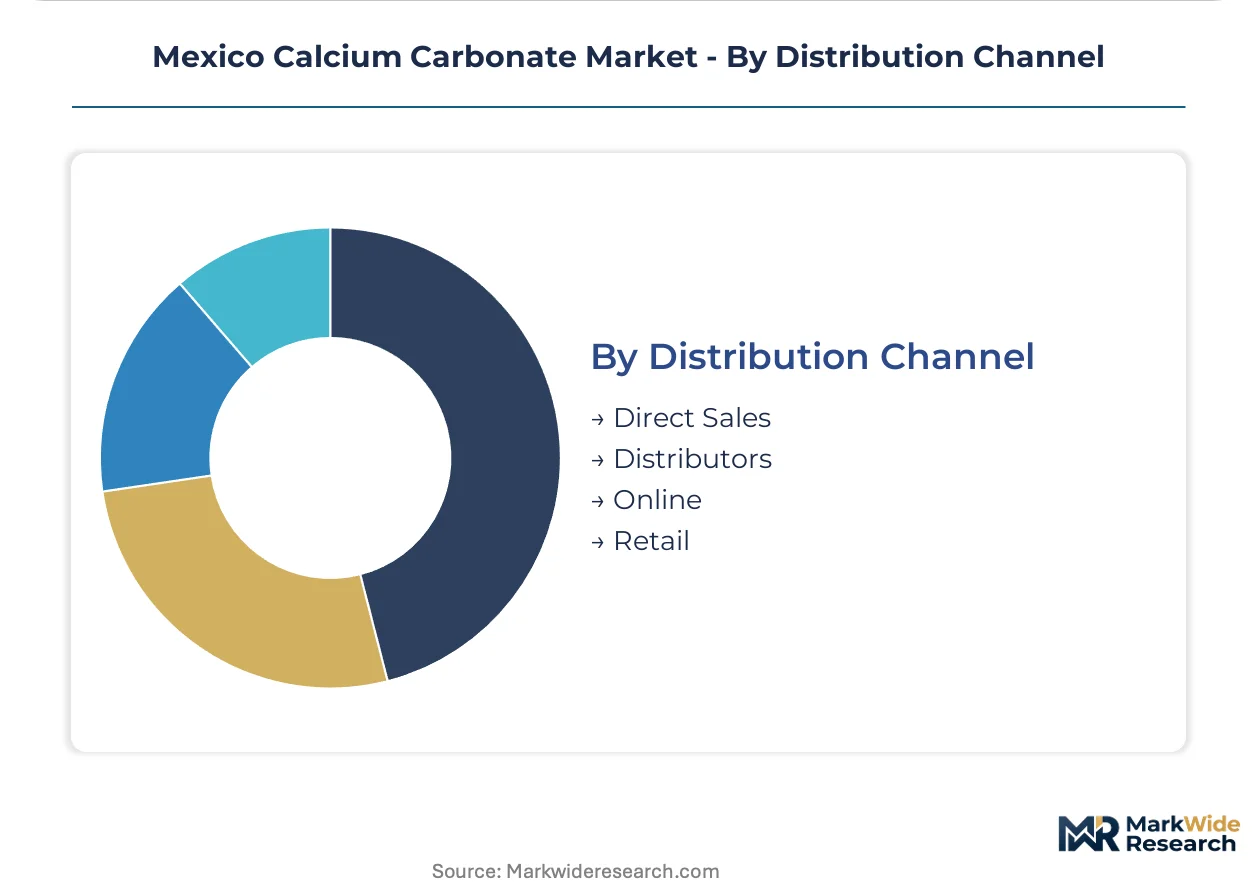
- Direct Sales:Integrated producers including Imerys and Minerals Technologies Inc. contract directly with tier-one paper mills and automotive compounders for volume commitments and technical collaboration, particularly visible in the Mexico City-Puebla logistics optimization zone.
- Distributors:Regional mineral specialists manage inventory and delivery for mid-size coatings and plastics processors lacking dedicated procurement infrastructure, with channel control representing a competitive moat for established operators.
- Online:Emerging platform-based procurement serves small-scale formulators and research laboratories requiring rapid sample access and technical documentation.
- Retail:Hardware and construction supply stores deliver packaged mineral additives to DIY and small contractor segments under PROFECO weight accuracy and labeling requirements.
Established volume relationships concentrate in direct sales channels with integrated producers. Distributor and online channels are gaining traction among mid-size and fragmented customer segments seeking procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central Mexico generates the bulk of calcium carbonate consumption, while northern states concentrate limestone extraction and integrated grinding assets. This geographic split shapes logistics costs and supply security calculations for construction and plastics compounders.
Mexico City Metro
The capital region anchors demand for NOM-001-SECRE-2010 certified construction-grade material in cement and concrete applications. SEMARNAT emissions controls for limestone processing operations tighten compliance timelines for local grinding facilities. Puebla industrial corridor manufacturers consume high-brightness ground calcium carbonate for infrastructure and residential development projects.
Nuevo León
Monterrey-based automotive suppliers drive qualification programs for precipitated calcium carbonate in instrument panel compounds. The state's manufacturing promotion agency coordinates technical standards alignment with tier-one OEM requirements. Apodaca and Santa Catarina industrial parks host plastics compounders specifying controlled particle size distribution for barrier film applications.
Jalisco
Guadalajara metropolitan area coatings formulators consume ground calcium carbonate for cost-driven architectural formulations. PROFECO labeling regulations govern retail-packaged mineral additives distributed through construction supply channels. El Salto industrial zone processors face energy cost pressure from Mexican electricity tariffs affecting wet grinding economics.
Bajío Region
Guanajuato and Querétaro manufacturing clusters represent the fastest-growing consumption zone for coated calcium carbonate in specialty packaging films. State environmental agencies enforce particulate matter thresholds for limestone quarrying permits. San Luis Potosí logistics corridors enable bulk bag distribution to mid-size plastics compounders lacking dedicated procurement infrastructure.
Northern Border States
Chihuahua and Coahuila limestone reserves supply captive grinding capacity for paper mill and cement producer integration. SEMARNAT quarry permitting bottlenecks create multi-year delays between reserve identification and commercial production. Piedras Negras and Ciudad Juárez processing facilities optimize bulk bag movements to Texas and southwestern US markets.
Mexico Calcium Carbonate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product-grade tiers. Market structure tilts toward consolidation around integrated producers with captive limestone reserves and technical service capabilities. Three archetypes dominate: multinational mineral processors with global R&D networks, regional quarry-to-grind operators with logistics optimization, and specialty coating technology licensors. Competitive moves concentrate on backward integration into limestone assets and direct contracting relationships displacing distributor channels.
Within the multinational processor tier, Imerys occupies a position exemplifying premium-grade specialization for coatings customers, while Minerals Technologies Inc. anchors the integrated reserves archetype through northern Mexico quarry control. Omya AG sits within the distribution channel mastery segment, with bulk bag and small bag reach into mid-size compounder networks. These three represent distinct strategic postures rather than overlapping competitive sets.
| Leading Market Players |
|---|
| Imerys |
| Minerals Technologies Inc. |
| Omya AG |
| Sibelco |
| J.M. Huber Corporation |
| Calidra |
| Lhoist |
| Vitro |
| C. Cales de Lampa |
| Others |
Supply & Pricing Matrix
Tier-one automotive compounders and cement producers in central Mexico anchor pricing power through long-term offtake agreements that lock volume commitments against NOM-001-SECRE-2010 certification premiums. Their procurement concentration forces suppliers to absorb energy cost volatility while maintaining grade-specific price bands.
Pricing Analysis
Cost compression in ground calcium carbonate accelerates because SEMARNAT compliance investments and electricity tariff exposure squeeze wet grinding margins. Contract-based long-term offtake dominates, with price differentiation hinging on NOM-001-SECRE-2010 certification tier and volume scale. Small bag distribution channels serving mid-size plastics compounders face the steepest pricing pressure, while precipitated grades for automotive applications command relative stability through specification lock-in.
Supply Chain Analysis
NOM-001-SECRE-2010 domestic-content requirements for construction-grade certification reshape sourcing toward captive limestone reserves in northern Mexico. Supply draws from Chihuahua, Coahuila, and Nuevo León extraction zones, with grinding capacity tethered to high-purity limestone deposits and natural gas availability. Single-source vulnerability concentrates around SEMARNAT permitting bottlenecks that delay reserve commercialization. Distribution runs through bulk bag pneumatic systems for paper mills and cement producers, supplemented by Omya AG's small bag network for fragmented compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface modification chemistry is displacing legacy uncoated grades in automotive and barrier packaging specifications, compressing traditional product hierarchies and forcing capital reallocation across the supply base.
For Market Incumbents: Deepen backward integration into northern Mexico limestone assets to defend against captive-reserve newcomers and SEMARNAT permitting delays. Lock tier-one automotive compounders in Querétaro through joint development programs for coated grade qualification, reinforcing switching costs against mineral substitute encroachment from talc and kaolin alternatives. For New Entrants and Emerging Players: Launch via PROFECO-regulated retail channels for packaged mineral additives in Jalisco and Guanajuato DIY construction segments, bypassing direct competition with integrated producers. Target coated calcium carbonate white space in San Luis Potosí logistics corridors serving mid-size plastics compounders lacking technical service relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional quarry-to-grind operators with dated environmental infrastructure facing SEMARNAT compliance deadlines in central Mexico. Long-term viability rests on carbonation reactor capability and surface modification chemistry talent. Watch SEMARNAT permitting velocity as the inflection signal for supply elasticity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive supply security in Chihuahua and Coahuila neutralizes SEMARNAT permitting risk for construction-grade volumes. |
| Coated Grade Production Line Investment | Surface modification capability captures automotive interior film specifications from Imerys in Querétaro manufacturing clusters. |
| Long-term Supply Agreement with Cement Producers | NOM-001-SECRE-2010 volume commitments in Mexico City-Puebla corridor lock out distributor-dependent competitors. |
| Joint Venture with Automotive Compounders | Collaborative particle engineering accelerates qualification timelines for instrument panel and barrier film applications. |
| Green Manufacturing Transition | Baghouse filtration and wet suppression upgrades preempt SEMARNAT emissions threshold tightening in northern Mexico. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving quarry operations managers, cement producer procurement leads, automotive compounder technical directors, and distributor channel partners. SEC 10-K disclosures, SEMARNAT environmental impact assessments, and PROFECO consumer protection filings supplemented bottom-up volume triangulation against top-down construction sector consumption models.
Granularity-level modeling deployed product-grade tier, end-use industry, packaging format, and regional production hub dimensions across the analysis window. CAGRs derived from elasticity-adjusted consumption functions incorporating NOM-001-SECRE-2010 compliance timelines and plastics compounding growth coefficients. Forecast inputs integrated SEMARNAT permitting velocity assumptions and energy tariff trajectory scenarios.
SEMARNAT regulatory delays, natural gas price volatility, and automotive qualification timeline extensions are the dominant revision risks to projection envelopes. Forecasts reflect documented assumptions on limestone reserve depletion rates and coated grade adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market