
 Global Silica Flour Market | 2026-2036
Global Silica Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silica Flour Market Foresight
The EU Green Deal is expanding compliance obligations for industrial mineral processors across European foundry and coatings supply chains. U.S. Silica Holdings leverages its Appalachian mining footprint to sustain long-term supply security for North American tire producers. Sibelco Group anchors its position through vertically integrated logistics spanning Belgian quarries to Asian electronics hubs. Quarzwerke GmbH competes on precision milling capabilities that serve German automotive casting specifications.
Silica flour consists of finely ground crystalline silicon dioxide with particle sizes typically ranging below 75 micrometers, produced through ball milling, air classification, or chemical precipitation to achieve specific purity and distribution profiles for industrial binding, reinforcement, and thermal resistance applications. Fine silica powder and ultrafine silica dominate value capture in electronics manufacturing, where semiconductor packaging and substrate fabrication require sub-micron consistency that commands technical premiums. Foundry and refractory applications represent mature volume anchors, while filtration and rubber compounds present faster growth trajectories driven by water infrastructure upgrades and EV tire formulation shifts.
EPA particulate standards in the United States, REACH registration requirements under ECHA oversight in Europe, and China's GB air quality enforcement through MEE collectively tighten permissible silica dust exposure thresholds and processing emissions. These frameworks elevate capital requirements for wet processing upgrades and closed-loop dust containment, advantaging scaled operators over artisanal producers. Stakeholders must monitor evolving crystalline silica classification debates at WHO and national OSHA-equivalent bodies that could trigger additional workplace exposure rules or product labeling mandates.
Market Dynamics
EU Green Deal decarbonization mandates are restructuring procurement criteria across European foundry and coatings supply chains, forcing processors to retool wet processing systems and abandon legacy dry-milling configurations that exceed tightening crystalline silica emission thresholds.
Growth Catalysts
- Foundry binder demand:Automotive casting clusters in Germany and China consume rising volumes of ultrafine silica flour for precision mold cores, with EV powertrain housing production requiring tighter thermal resistance specifications.
- REACH registration:ECHA oversight of crystalline silica classification under SVHC review is accelerating consolidation toward compliant processors with closed-loop dust containment infrastructure.
- Semiconductor packaging:Substrate fabrication facilities in South Korea and Taiwan source sub-micron silica grades for underfill compounds, creating technical premium capture outside commodity refractory markets.
Market Restraints
- Energy cost volatility:Ball milling and air classification operations face margin compression from natural gas and electricity price swings, particularly affecting European wet processing upgrades.
- Appalachian supply concentration:Premium frac sand and silica flour feedstock from Pennsylvania and West Virginia mines creates geographic dependency risk for North American tire and foundry customers.
- Fumed silica substitution:Cabot and Wacker Chemie supply pyrogenic silica alternatives that displace precipitated silica flour in high-performance rubber compounding for EV tires.
Strategic Opportunities
- Indian refractory expansion:Tata Steel and JSW Steel greenfield capacity in Odisha and Jharkhand creates uncontracted demand for metallurgical-grade silica flour with low alumina content specifications.
- Water filtration infrastructure:MEE enforcement of GB standards for municipal drinking water drives replacement of legacy sand media with precision-milled silica in tertiary treatment systems.
- Dual carbon alignment:China's MIIT carbon intensity benchmarks reward processors deploying renewable-powered milling, creating first-mover certification advantages for export-qualified material.
Industry Challenges
- Process engineering talent:Wet processing retrofits require operators skilled in closed-loop water chemistry and membrane filtration, a capability scarce outside Belgian and German technical centers.
- ISO crystalline silica certification:Workplace exposure testing and third-party validation timelines extend 18-24 months, delaying market access for new entrants in regulated European jurisdictions.
- Legacy ERP integration:Dust monitoring sensors and automated batch tracking systems face interoperability friction with existing foundry management software, complicating compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silica Flour Market |
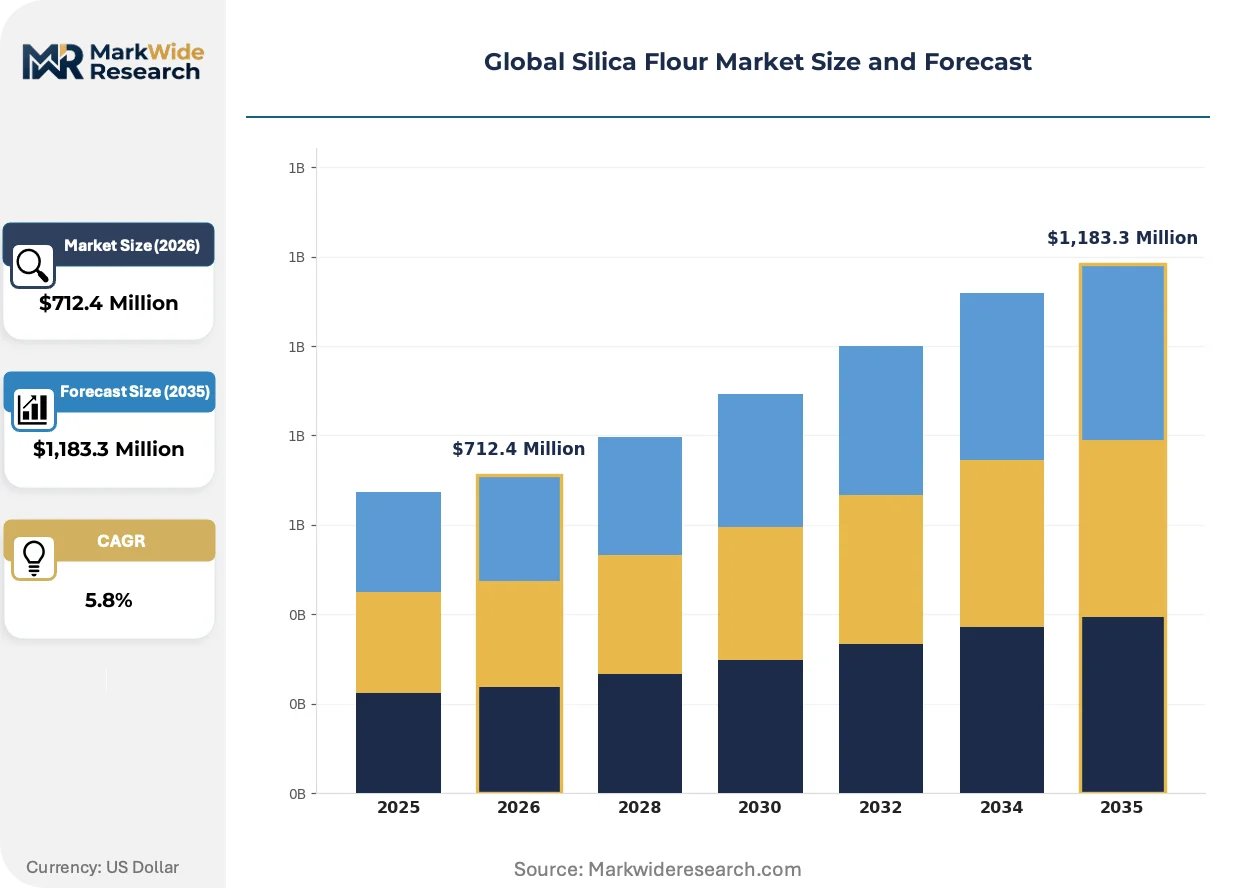
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
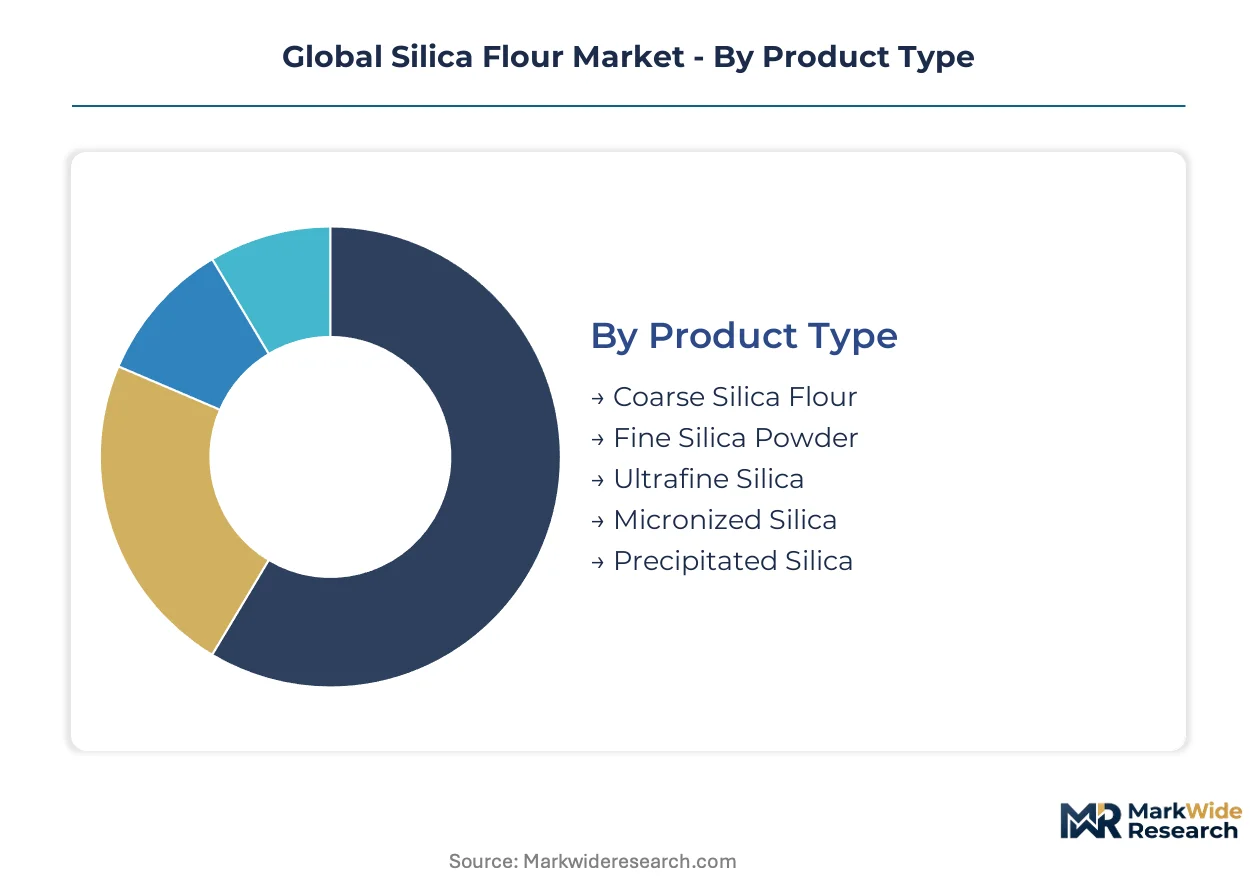
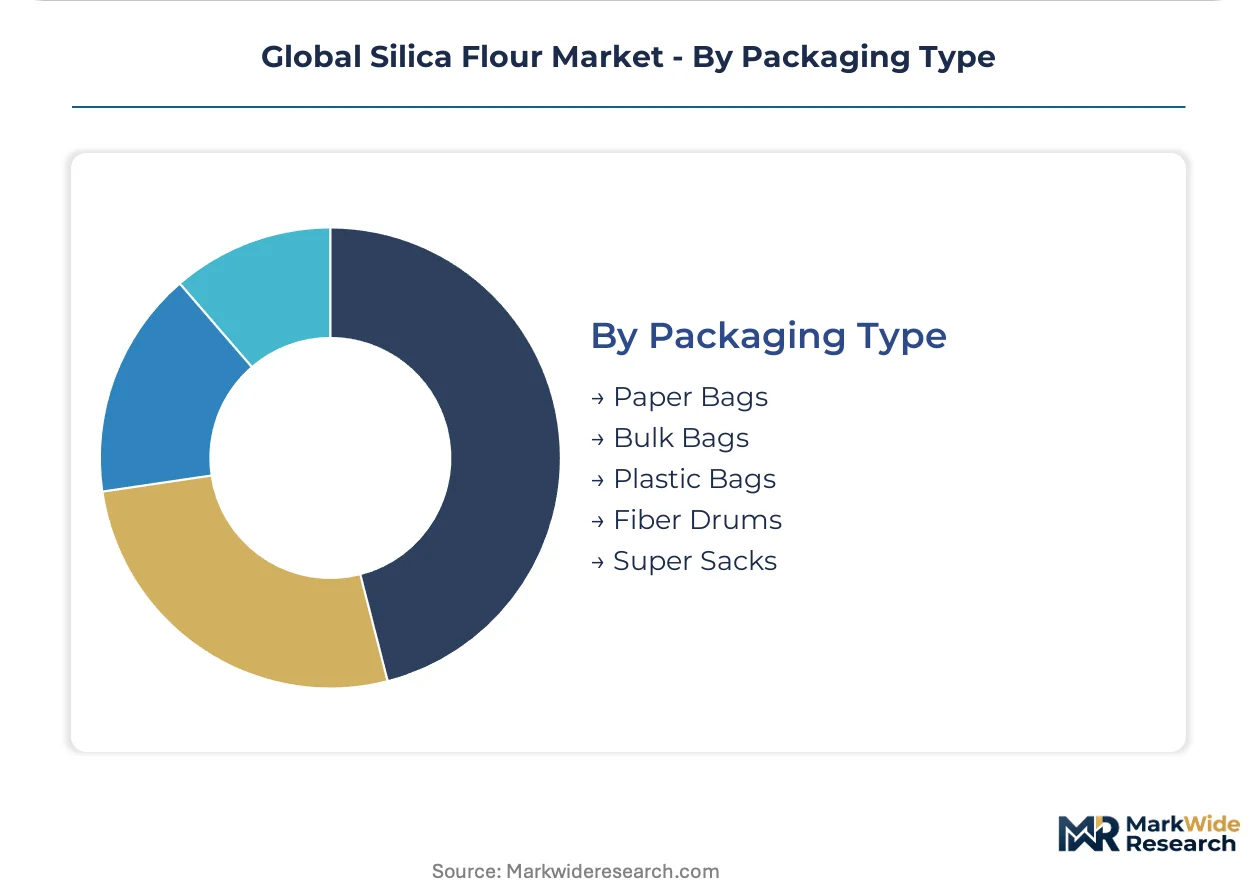
| Segmentation | Product Type: Coarse Silica Flour, Fine Silica Powder, Ultrafine Silica, Micronized Silica, Precipitated Silica Application: Paints & Coatings, Foundry, Rubber Compounds, Refractories, Electronics Manufacturing, Filtration End User: Construction Firms, Consumer Electronics Manufacturers, Tire Producers, Metal Casting Factories, Water Treatment Plants Packaging Type: Paper Bags, Bulk Bags, Plastic Bags, Fiber Drums, Super Sacks |
| Companies Covered | Sil Industrial Minerals, Fineton Industrial Minerals Limited, U.S. Silica Holdings, Capital Sand Company, Hoben International, Sibelco Group, Adwan Chemical Industries Company, Quarzwerke GmbH, AGSCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silica Flour Market Shifts & Advancements
Silica flour processing is converging with digital quality control and renewable energy sourcing, compressing the gap between commodity refractory supply and premium electronics-grade production while reshaping competitive requirements across value tiers.
Precision air classification systems with inline laser diffraction sensors are decentralizing quality assurance from centralized labs to production lines. German automotive casting suppliers now specify real-time particle distribution data with every batch, eliminating incoming inspection delays. This capability compression is decentralizing procurement decisions from headquarters technical teams to plant-level metallurgists who verify conformance on receipt.
REACH authorization requirements for crystalline silica under ECHA's 2023-2025 work program are forcing foundry customers to document supply chain exposure assessments. Processors without SVHC communication systems face exclusion from automotive tier-one supplier lists. German and French coating manufacturers are responding by dual-sourcing from REACH-registered European mills and qualifying Asian alternatives with equivalent documentation packages.
Direct mill-to-plant contracting is displacing distributor intermediaries in high-volume foundry segments. Large automotive casting groups in China and Germany negotiate annual silica flour supply agreements with fixed volume tiers and indexed energy adjustments, bypassing regional traders. This channel consolidation is most visible in the Yangtze River Delta, where BYD and NIO supplier parks source bonded silica through captive procurement offices co-located with Sibelco and domestic processor facilities.
Global Silica Flour Market Segmentation
Silica flour segmentation reflects divergent technical specifications and compliance burdens across end-use applications. Procurement patterns fragment sharply between commodity refractory grades and precision electronics materials. Supply chain configuration determines which processors capture value in each tier.
Product Type:
Supply concentration in ultrafine milling capabilities separates premium capture from commodity volume plays.
- Ultrafine Silica:Sub-micron particle distribution with tight D50 control serves semiconductor underfill compounds in South Korea and Taiwan. Substrate fabricators mandate ISO crystalline silica certification and real-time laser diffraction data with every batch.
- Fine Silica Powder:5-50 micrometer grades dominate automotive casting binders in Germany and China. EV powertrain housing production tightens thermal resistance specifications beyond legacy internal combustion requirements.
- Coarse Silica Flour:75-150 micrometer material anchors water filtration media replacement cycles in Chinese municipal systems.
- Micronized Silica:Jet-milled precision grades serve pharmaceutical and cosmetic applications with enhanced surface area profiles.
- Precipitated Silica:Synthetic amorphous material competes against ground crystalline grades in rubber reinforcement for EV tire sidewalls.
Today's leader: Ultrafine Silica. Tomorrow's challenger: Fine Silica Powder.
Application:
Cost tier separation between mature refractory demand and emerging filtration infrastructure creates divergent margin profiles.
- Electronics Manufacturing:Sub-micron silica flour enables epoxy molding compounds for semiconductor packaging. Taiwan-based substrate fabricators source exclusively from REACH-registered processors with closed-loop dust containment validation.
- Foundry:Mold and core binders consume the largest volume tonnage globally. German automotive casting clusters specify real-time particle distribution verification to eliminate incoming inspection delays.
- Filtration:Precision-milled silica replaces legacy sand media in Chinese tertiary water treatment systems under MEE GB standard enforcement.
- Refractories:Metallurgical-grade material with low alumina content feeds steel production expansion in Odisha and Jharkhand.
- Rubber Compounds:Tire producers blend silica flour for rolling resistance optimization in EV range extension.
- Paints & Coatings:Matting agents and rheology modifiers utilize controlled particle size distribution for automotive and industrial finishes.
Electronics Manufacturing commands the steepest expansion trajectory. Foundry retains volume dominance.
End User:
Customer type determines specification stringency and contract structure across direct mill-to-plant negotiations.
- Consumer Electronics Manufacturers:Sub-micron consistency requirements for smartphone and computing substrate fabrication. South Korean packaging houses specify sub-500 nanometer D50 with batch-level traceability.
- Tire Producers:North American manufacturers source from Appalachian mining footprints to secure long-term supply security against geographic concentration risk.
- Metal Casting Factories:German and Chinese automotive tier-one suppliers enforce REACH documentation and SVHC communication systems for mold core procurement.
- Water Treatment Plants:Chinese municipal operators replace legacy media under MEE enforcement timelines.
- Construction Firms:Cement and concrete admixture applications utilize coarser grades with less stringent particle distribution controls.
Consumer Electronics Manufacturers set the premium benchmark. Tire Producers drive contract innovation.
Packaging Type:
Volume scale and handling automation requirements segment logistics configurations across customer tiers.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate foundry and refractory shipments to automotive casting clusters and steel mills.
- Super Sacks:Reinforced woven polypropylene handles ultrafine silica with enhanced dust containment for electronics-grade material.
- Fiber Drums:Rigid containment suits precipitation-sensitive grades in coating and adhesive applications.
- Paper Bags:Multi-wall kraft construction serves smaller volume construction and specialty chemical customers.
- Plastic Bags:Polyethylene liners provide moisture barrier protection for hygroscopic fine powders.
Bulk Bags anchor industrial volume. Super Sacks gain share in precision material handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial silica flour processing originated in the Belgian quarries of the Meuse valley during the early twentieth century, establishing technical standards that persist in precision milling today. Foundry demand subsequently migrated to German automotive clusters and Chinese manufacturing hubs, creating geographically dispersed production centers with distinct compliance regimes.
United States
Appalachian mining operations in Pennsylvania and West Virginia supply premium feedstock for North American tire producers and foundry customers. EPA particulate standards enforce crystalline silica exposure thresholds that elevate capital requirements for wet processing upgrades. Pittsburgh-area processors serve automotive casting clusters in Michigan and Ohio with long-term supply agreements indexed to energy costs.
Germany
Automotive powertrain housing production for EV platforms consumes ultrafine silica flour with tightened thermal resistance specifications. ECHA REACH registration mandates SVHC communication systems that exclude non-compliant processors from tier-one supplier lists. Bavarian casting clusters around Ingolstadt and Munich specify real-time particle distribution verification to eliminate incoming inspection delays.
China
Electronics manufacturing in the Yangtze River Delta and Pearl River Delta drives sub-micron silica consumption for semiconductor packaging substrates. MIIT carbon intensity benchmarks reward processors deploying renewable-powered milling with export certification advantages. BYD and NIO supplier parks source bonded silica through captive procurement offices co-located with domestic processor facilities in Jiangsu and Guangdong.
Belgium
Sibelco Group anchors European supply through vertically integrated logistics spanning domestic quarries to Asian electronics hubs. EU Green Deal decarbonization mandates force abandonment of legacy dry-milling configurations that exceed tightening emission thresholds. Antwerp-area technical centers retain scarce process engineering talent in closed-loop water chemistry and membrane filtration.
India
Tata Steel and JSW Steel greenfield capacity in Odisha and Jharkhand creates uncontracted demand for metallurgical-grade silica flour with low alumina content specifications. Central Electricity Authority enforcement of ambient air quality standards drives wet processing retrofits at legacy refractory suppliers. Bhilai and Rourkela steel corridors concentrate procurement negotiations for direct mill-to-plant contracting.
Global Silica Flour Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across distinct value tiers in silica flour supply. The vendor base separates between integrated miners with captive quarry assets and precision processors specializing in air classification technology. Three archetypes dominate: Appalachian mining conglomerates securing long-term feedstock contracts, European precision millers serving automotive specifications, and Asian electronics-grade specialists capturing technical premiums. Consolidation pressure accelerates through REACH registration deadlines and EPA compliance timelines, while capacity expansion concentrates in Chinese renewable-powered facilities and Indian refractory corridors.
Among North American mining conglomerates, U.S. Silica Holdings and Capital Sand Company exemplify the feedstock-security archetype through Appalachian quarry control. European precision milling is represented by Quarzwerke GmbH and Sibelco Group, whose Belgian-German operations anchor REACH-compliant supply chains. These named entities occupy positions that reflect broader structural patterns: geographic concentration in premium feedstock basins, vertical integration into logistics networks, and certification barriers that exclude artisanal competitors from regulated automotive and electronics supply chains.
| Leading Market Players |
|---|
| Sil Industrial Minerals |
| Fineton Industrial Minerals Limited |
| U.S. Silica Holdings |
| Capital Sand Company |
| Hoben International |
| Sibelco Group |
| Adwan Chemical Industries Company |
| Quarzwerke GmbH |
| AGSCO Corporation |
| Others |
Supply & Pricing Matrix
Captive quarry-to-plant integration across Appalachian and Belgian mining basins anchors supply security for North American tire producers and European automotive casters, compressing procurement cycles and insulating premium processors from feedstock volatility that erodes margin at merchant-dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments silica flour procurement by certification grade and volume commitment scale. Electronics-grade sub-micron material with ISO crystalline silica certification and real-time laser diffraction data commands technical premiums from Taiwan substrate fabricators, while ungraded refractory tonnage faces price erosion from Chinese oversupply. Tire producers exhibit lowest price sensitivity due to long-term Appalachian supply agreements indexed to energy costs, whereas municipal water treatment operators in China prioritize unit economics over performance specifications.
Supply Chain Analysis
Regional distribution centers in Antwerp, Pittsburgh, and Shanghai orchestrate hub-and-spoke logistics for silica flour delivery to automotive casting clusters and electronics manufacturing hubs. Supply concentrates in Pennsylvania, West Virginia, and Belgian Meuse valley quarries for premium feedstock, with Chinese Jiangsu and Guangdong provinces hosting precision milling capacity for semiconductor packaging grades. Ball milling and air classification operations draw from natural gas and electricity inputs vulnerable to European energy cost volatility. Single-source vulnerability runs through Appalachian frac sand corridors for North American tire producers. Distribution runs through direct mill-to-plant contracting that displaces regional trader intermediaries in high-volume foundry segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silica flour market functions as a stable compounder anchored by irreplaceable foundry binder demand from automotive powertrain housing production, where EV thermal resistance specifications tighten procurement standards beyond commodity substitution thresholds.
For Market Incumbents: Anticipate fumed silica substitution threats from Cabot and Wacker Chemie in high-performance EV tire compounding by deepening captive quarry control and accelerating REACH-registered capacity expansion in Belgian and German precision milling corridors. Secure process engineering talent in closed-loop water chemistry through technical center retention packages, as wet processing retrofits become mandatory for ECHA compliance. For New Entrants and Emerging Players: Municipal water treatment operators in Chinese tertiary systems under MEE GB enforcement represent an underserved buyer archetype with uncontracted demand for precision-milled filtration media. Target Odisha and Jharkhand steel corridors in India for metallurgical-grade silica flour with low alumina specifications, leveraging direct mill-to-plant contracting structures that bypass established distributor networks. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precision millers with REACH registration and closed-loop dust containment infrastructure because ECHA SVHC review timelines extend 18-24 months and exclude artisanal competitors from automotive tier-one supplier lists. Monitor crystalline silica classification debates at WHO and national OSHA-equivalent bodies as inflection indicators for additional workplace exposure rules that would accelerate consolidation toward compliant scaled operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive Appalachian or Belgian feedstock supply secures long-term tire and foundry contracts against geographic concentration risk. |
| Green Manufacturing Transition | Renewable-powered milling in Chinese facilities earns MIIT carbon intensity certification advantages for export-qualified material. |
| Long-term Supply Agreement | Annual volume tiers with indexed energy adjustments lock in automotive casting demand from BYD and NIO supplier parks. |
| Joint Venture with Electronics Distributor | Co-location with Taiwan substrate fabricators accelerates sub-micron grade qualification and technical premium capture. |
| Capacity Expansion in Indian Refractory Corridor | Greenfield Tata Steel and JSW Steel capacity in Odisha creates uncontracted demand for low-alumina metallurgical grades. |
Research Methodology
Bottom-up foundry and electronics manufacturing modeling reconciled against top-down quarry production and trade flow tracking forms the analytical core of this study. Primary interviews with plant managers at German automotive casting clusters, procurement leads at South Korean semiconductor packaging houses, technical R&D directors at Belgian precision milling operations, and channel partners in Chinese refractory distribution networks were cross-validated against secondary sources including customs and trade data, SEC 10-K filings from listed miners, ECHA REACH registration databases, and MIIT carbon intensity disclosure records.
Input-output matrices across product type, application, end user, and packaging format dimensions drive volume and value projections over the analysis window. CAGRs were derived from segment-level demand elasticity modeling calibrated to automotive powertrain housing production forecasts and water infrastructure investment pipelines. Forecast inputs include EV thermal resistance specification tightening timelines and MEE GB standard enforcement trajectories for municipal drinking water systems.
Inputs from ECHA registration databases and MIIT disclosure systems were available through the study window; gaps in artisanal producer output data and real-time energy cost indices introduce uncertainty bands around European wet processing upgrade assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
United States Soda Ash Market