
 Lignosulfonates Market | 2026-2036
Lignosulfonates Market Size, Share, and Industry Trends Forecast 2026-2036
Lignosulfonates Market Intelligence
A capital-intensity divergence between integrated pulp-to-lignin operators and merchant chemical producers is rotating competitive dynamics across the value chain. Borregaard LignoTech leverages its backward integration into Norwegian wood pulping to sustain cost-advantaged sodium lignosulfonate output. Ingevity competes through specialized oilfield-grade formulations that command premium positioning in drilling-fluid applications. Green Agrochem anchors its position via geographic dominance in Asian agricultural binder markets, where it controls regional distribution channels.
Lignosulfonates are sulfonated lignin derivatives obtained from the sulfite pulping process, typically carrying molecular weights between 1,000 and 50,000 daltons and functional sulfonate group densities that confer water solubility and dispersant activity. Their primary commercial purpose centers on surface-charge modification of particles in aqueous systems, enabling cement plasticization, dust particle agglomeration, and feed pellet integrity. Sodium lignosulfonate occupies the largest volume share across product types due to its versatility in concrete additive and oil drilling applications, while calcium lignosulfonate generates concentrated margin pools in animal feed pellet binder segments where pellet durability specifications are stringent. Powder form dominates current trade flows for logistical efficiency, though liquid formulations are gaining traction in oilfield services where on-site dilution reduces handling costs.
EPA regulations under the Clean Air Act constrain dust-control product formulations in mining and unpaved road applications, while REACH registration requirements in Europe mandate full toxicological dossiers for lignosulfonate imports above one tonne annually. China's GB standards for concrete admixtures, administered by SAMR, set performance benchmarks that directly shape product development priorities for domestic construction chemical suppliers. Stakeholders must monitor evolving sulfate-emission thresholds at pulp mills, as environmental compliance costs at the lignin extraction stage will determine which integrated producers can defend merchant-market supply positions without captive pulp economics.
Market Dynamics
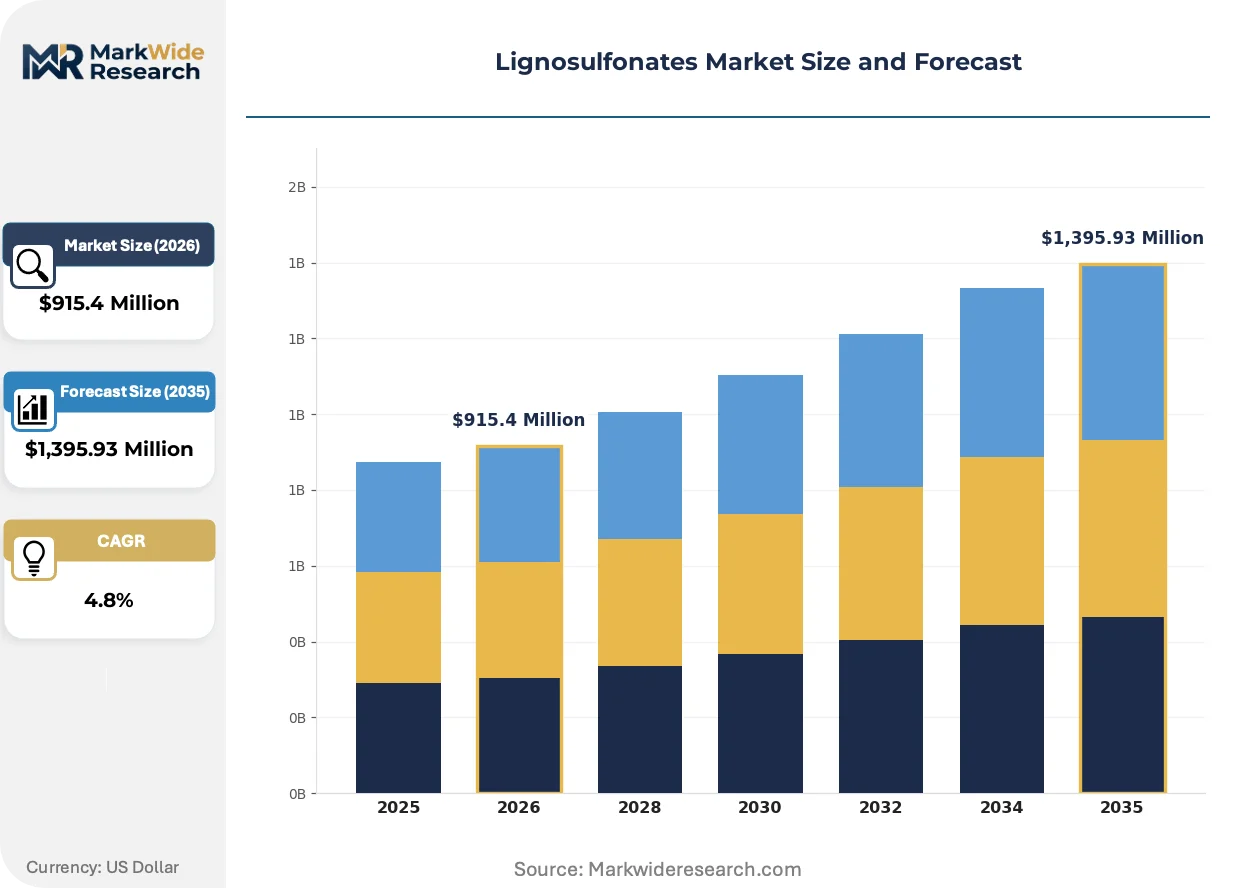
Integrated pulp-to-lignin operators are compressing merchant chemical producer margins through captive sulfate supply and lower extraction costs. This capital-intensity divergence is rotating competitive positioning across the value chain, forcing non-integrated suppliers toward specialty formulations or geographic niches.
Growth Catalysts
- EPA dust-control mandates:Stricter Clean Air Act enforcement for mining and unpaved road applications is expanding specification-grade lignosulfonate procurement in the United States.
- Concrete admixture demand:China's state-backed infrastructure projects are consuming substantial sodium lignosulfonate volumes for cement dispersion and plasticization.
- REACH compliance:Full toxicological dossier requirements for imports above one tonne annually are consolidating supplier bases toward established European registrants.
Market Restraints
- Sulfate input volatility:Pulp mill sulfate-emission threshold tightening raises environmental compliance costs at the lignin extraction stage, squeezing merchant producers without captive pulp economics.
- Substitution pressure from synthetic dispersants:Polycarboxylate ether superplasticizers in high-performance concrete threaten sodium lignosulfonate share in premium construction applications.
- Supply concentration in Nordic integrated producers:Backward integration into Norwegian and Swedish wood pulping limits independent chemical producer access to cost-advantaged raw material streams.
Strategic Opportunities
- Underpenetrated oilfield services in the Middle East:Drilling-fluid grade lignosulfonate demand in Saudi Arabia and UAE remains below saturation, creating white space for specialty formulation suppliers.
- Biostimulant convergence with agricultural binders:Combining lignosulfonate pellet binders with microbial inoculant carriers opens premium positioning in precision agriculture input portfolios.
- EU Green Deal bio-based procurement incentives:Public construction tender preferences for renewable admixtures create regulatory tailwind for certified sustainable lignosulfonate sourcing.
Industry Challenges
- Sulfonation chemistry expertise scarcity:Specialized process engineering talent for molecular weight control and functional group density optimization limits capacity expansion timelines.
- Multi-jurisdiction registration synchronization:Aligning REACH dossiers with China's GB standard testing protocols and EPA PMN requirements extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignosulfonates Market |
| Market Size in 2026 | $915.4 Million |
| Market Size in 2035 | $1,395.93 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Lignosulfonate, Sodium Lignosulfonate, Magnesium Lignosulfonate, Ammonium Lignosulfonate, Zinc Lignosulfonate Application: Concrete Additive, Dust Control, Animal Feed Pellet Binder, Oil Drilling, Ceramic Processing End User Industry: Construction Companies, Mining Operators, Feed Producers, Oilfield Services, Ceramics Manufacturers Form: Powder, Granules, Liquid, Crystals |
| Companies Covered | Rayonier Advanced Materials, Green Agrochem, Borregaard LignoTech, Burgo Group, Ingevity, Sappi, Domsjö Fabriker, Xingzhenghe Chemical, Nippon Paper Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignosulfonates Market Strategic Shifts & Innovations
Product differentiation is compressing toward molecular weight precision and functional group customization rather than commodity volume competition. This shift favors suppliers with in-house sulfonation process control and application-specific formulation capabilities.
Membrane filtration technology for lignosulfonate fractionation is miniaturizing production footprints while enabling targeted molecular weight cuts. Oilfield service contractors are adopting these modular systems for on-site liquid formulation preparation. The technology is compressing logistics costs and reducing powder-to-liquid conversion losses at remote drilling locations.
REACH registration requirements are tightening toxicological data standards for lignosulfonate imports above one tonne annually. This regulatory friction is consolidating European supplier bases toward established dossier holders with full substance identity documentation. Construction chemical distributors are shifting procurement toward pre-registered supply channels to avoid customs delays.
Specification-driven procurement is replacing commodity spot purchasing in concrete admixture supply chains. Large ready-mix operators are implementing certified supplier programs with batch-to-batch consistency guarantees. This behavioral shift is most visible in China, where SAMR-administered GB standards enforcement has elevated quality documentation requirements above price-only selection criteria.
Lignosulfonates Market Segmentation
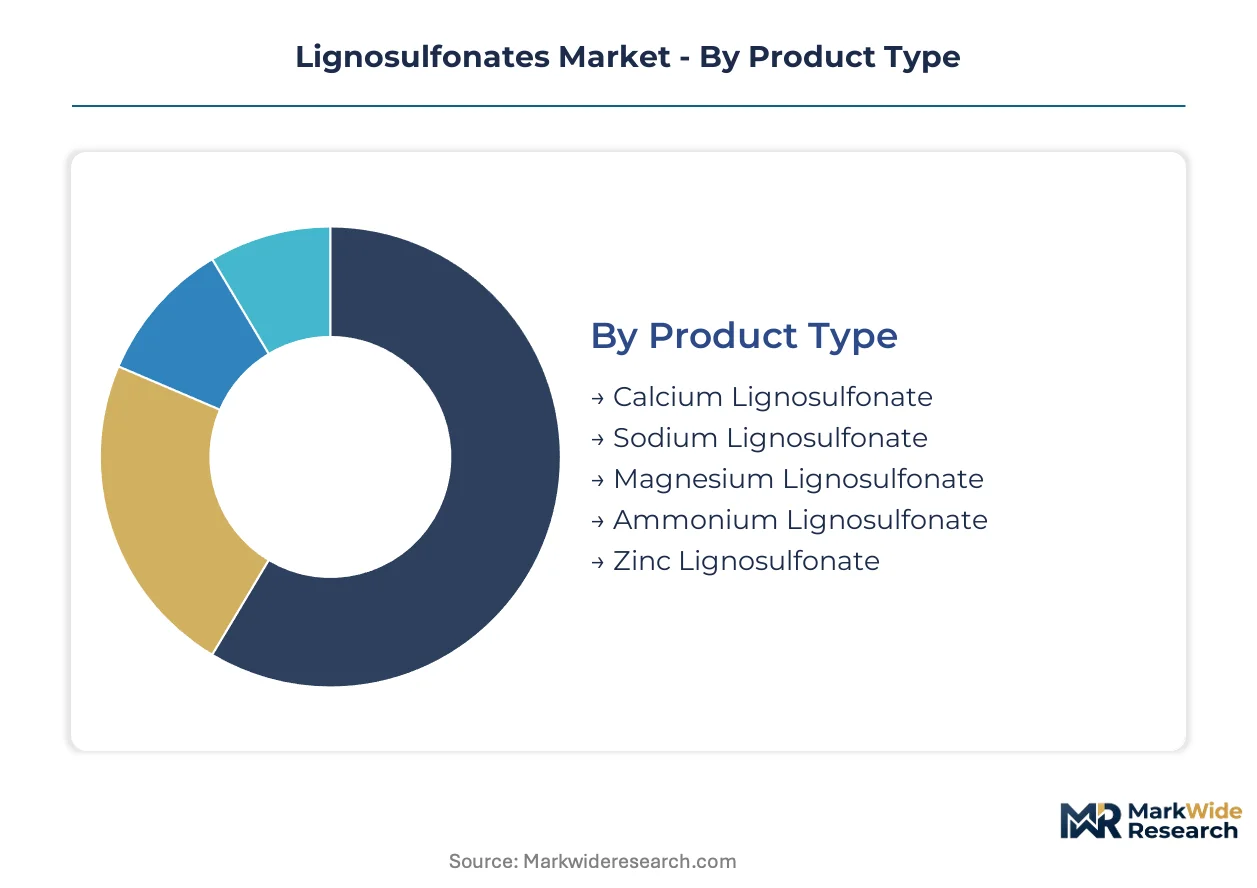
Lignosulfonate procurement channels diverge sharply by product chemistry and end-use specification. Construction chemical distributors, oilfield service contractors, and agricultural input suppliers each demand distinct formulation grades, forcing suppliers to align production with channel-specific certification requirements.
Product Type:
Channel distribution varies by cation chemistry: sodium grades flow through construction chemical distributors, calcium through feed ingredient brokers, and specialty cations through direct oilfield supply contracts.
- Sodium Lignosulfonate:Carries the highest sulfonate group density among commercial grades, enabling superior cement particle dispersion at low dosage rates. Demand concentrates in China, where SAMR-administered GB standards for concrete admixtures mandate consistent plasticization performance in state-backed infrastructure projects.
- Calcium Lignosulfonate:Forms harder, more durable feed pellets through enhanced protein binding and reduced fines generation. Feed producers in the US Corn Belt specify this grade for swine and poultry rations, with EPA-registered dust-control applications providing secondary volume in Midwest mining operations.
- Magnesium Lignosulfonate:Niche ceramic processing applications in Germany and Italy leverage its controlled burn-out characteristics.
- Ammonium Lignosulfonate:Oilfield services in Texas and Oklahoma specify this grade for high-temperature drilling fluid stability.
- Zinc Lignosulfonate:Micronutrient fertilizer applications in Brazil and Australia drive modest specialty volumes.
By volume, sodium lignosulfonate leads. By growth pace, ammonium grades for oilfield applications are climbing the fastest.
Application:
Cost tiers separate specification-grade applications from commodity spot markets, with certified admixture programs commanding 15-25% price premiums over unbranded dust-control supplies.
- Concrete Additive:Requires batch-to-batch consistency guarantees under certified supplier programs. China's ready-mix operators have shifted procurement toward pre-qualified sodium lignosulfonate channels to avoid SAMR enforcement actions on non-compliant admixtures.
- Dust Control:EPA Clean Air Act enforcement for mining and unpaved road applications has elevated specification requirements above commodity purchasing. US surface mining operators in Wyoming and Arizona now require dust-suppression efficacy documentation for regulatory compliance.
- Animal Feed Pellet Binder:Concentrated margin pool where pellet durability specifications from Tyson Foods and Cargill procurement standards favor calcium lignosulfonate with guaranteed protein binding indices.
- Oil Drilling:High-temperature rheology stability requirements in Saudi Aramco and ADNOC drilling programs favor specialized ammonium and sodium formulations.
- Ceramic Processing:Italian tile manufacturers and German sanitary ware producers specify controlled ash content for defect-free sintering.
Concrete additive applications generate the largest revenue base. Oil drilling formulations show the steepest expansion trajectory as Middle East drilling activity intensifies.
End User Industry:
Customer sophistication separates industries: construction companies demand full REACH dossiers and GB standard compliance documentation, while mining operators prioritize EPA-registered efficacy data over molecular specifications.
- Construction Companies:Large ready-mix operators in China and Germany have implemented vendor certification programs requiring sulfonate content consistency within 2% batch-to-batch variation. Sika and BASF construction chemical divisions specify pre-registered sodium lignosulfonate supply channels to avoid customs delays.
- Mining Operators:US surface coal and copper producers in Montana and Nevada face EPA regional enforcement of PM10 dust standards, expanding specification-grade lignosulfonate procurement for haul road stabilization.
- Feed Producers:Tyson Foods, Cargill, and JBS procurement standards mandate pellet durability indices above 95% for calcium lignosulfonate inclusion in premium rations.
- Oilfield Services:Schlumberger and Halliburton drilling fluid divisions specify high-temperature stability above 150°C for deep Saudi and UAE well programs.
- Ceramics Manufacturers:Italian tile clusters in Sassuolo and German sanitary ware producers in Selb require low-ash magnesium grades for defect-free glaze compatibility.
Construction companies anchor volume demand. Oilfield services are gaining share fastest as Middle East drilling deepens.
Form:
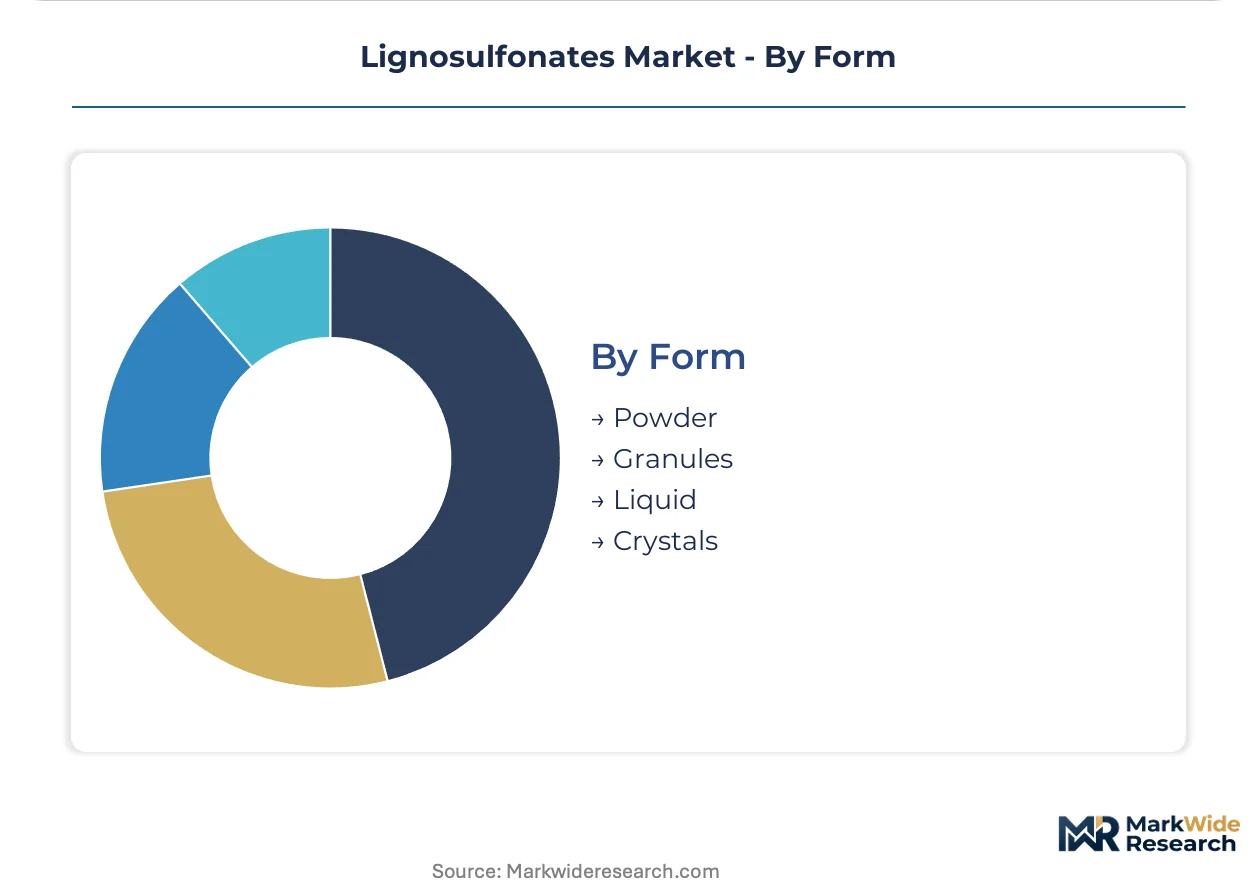
Supply concentration favors powder production at Nordic integrated pulp mills, while liquid formulation growth reflects oilfield service contractor preferences for on-site dilution economics.
- Powder:Dominates current trade flows for logistical efficiency in cement admixture and feed binder applications. Borregaard LignoTech's Norwegian production ships powder grades to construction chemical distributors across Germany, France, and China with 18-month shelf stability guarantees.
- Liquid:Gaining traction in oilfield services where on-site dilution reduces handling costs at remote Saudi and UAE drilling locations. Membrane filtration miniaturization enables modular production footprints for regional blending.
- Granules:Specialized dust-control applications in Australian mining favor slow-dissolution formats for extended road stabilization.
- Crystals:Niche ceramic processing segment in Japan requires ultra-pure grades for electronic substrate applications.
Powder form leads by tonnage. Liquid formulations are expanding most quickly as oilfield logistics optimize for reduced transport mass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China exhibit the lowest price elasticity, absorbing premium sodium lignosulfonate for certified concrete admixture programs, while US mining operators remain highly price-sensitive in dust-control procurement. European construction chemical distributors occupy a middle position, prioritizing REACH-registered supply channels over marginal cost savings. This demand-elasticity spectrum shapes regional supplier strategies and investment allocation.
China
State-backed infrastructure projects under the 14th Five-Year Plan consume substantial sodium lignosulfonate volumes for high-speed rail and dam construction. SAMR-administered GB 8076 standards mandate consistent cement plasticization performance, elevating documentation requirements above price-only selection. Construction chemical clusters in Jiangsu and Shandong provinces concentrate domestic formulation capacity.
United States
EPA Clean Air Act enforcement for PM10 dust standards in surface mining expands specification-grade procurement for haul road stabilization. Wyoming and Arizona copper producers now require efficacy documentation for regulatory compliance. The Corn Belt feed industry anchors calcium lignosulfonate demand through Tyson Foods and Cargill procurement standards.
Germany
REACH registration requirements consolidate supplier bases toward established dossier holders with full substance identity documentation. Ready-mix operators in North Rhine-Westphalia implement vendor certification programs requiring sulfonate content consistency within 2% batch-to-batch variation. The Rhine-Ruhr industrial corridor hosts construction chemical distribution hubs serving Benelux markets.
Saudi Arabia
Saudi Aramco drilling programs drive ammonium lignosulfonate demand for high-temperature rheology stability above 150°C. The kingdom's Vision 2030 infrastructure diversification expands cement admixture procurement beyond oilfield services. Eastern Province industrial cities concentrate oilfield service contractor operations.
Brazil
Zinc lignosulfonate micronutrient fertilizer applications support precision agriculture expansion in Mato Grosso and Goiás soybean belts. ANVISA registration requirements for feed additives shape calcium lignosulfonate import protocols. São Paulo state anchors agricultural input distribution networks serving Mercosur markets.
Lignosulfonates Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across the value chain. Nordic integrated pulp-to-lignin operators sustain cost advantages through captive sulfate supply and lower extraction economics. Merchant chemical producers without backward integration compete through specialty formulation capabilities and geographic niche dominance. The dominant competitive moves center on membrane filtration technology licensing for modular production footprints and strategic partnerships with oilfield service contractors for drilling-fluid grade supply.
Among Nordic integrated operators, Borregaard LignoTech and Domsjö Fabriker exemplify the cost-leadership archetype through pulp mill backward integration. Ingevity occupies a position representing the specialty-formulation tier, anchoring premium positioning in oilfield applications. Green Agrochem and Xingzhenghe Chemical sit within the geographic-niche category, controlling regional distribution channels in Asian agricultural and construction markets respectively.
| Leading Market Players |
|---|
| Rayonier Advanced Materials |
| Green Agrochem |
| Borregaard LignoTech |
| Burgo Group |
| Ingevity |
| Sappi |
| Domsjö Fabriker |
| Xingzhenghe Chemical |
| Nippon Paper Industries |
| Others |
Cost & Logistics Intelligence
REACH registration requirements in Europe simultaneously gate supply qualification and create price differentiation between dossier-holding incumbents and unregistered challengers. This regulatory filter compresses margins for non-compliant imports while rewarding established European suppliers with pricing power in certified construction chemical channels.
Pricing Analysis
After-sales service contracts for drilling-fluid technical support drive lifetime value in oilfield applications. Three-tier pricing structure across certified admixture, specification-grade dust control, and commodity feed binder levels separates construction chemical distributors from mining operators and agricultural brokers. Cost compression in commodity sodium lignosulfonate intensifies as polycarboxylate ether superplasticizers displace volume in premium concrete applications. US mining operators exhibit highest price sensitivity in dust-control procurement, while Chinese ready-mix operators absorb premiums for GB 8076-compliant certification.
Supply Chain Analysis
Norway and Sweden anchor cost-advantaged lignosulfonate production through integrated pulp-to-lignin operations. Raw material flows draw from softwood sulfate supply, sulfite pulping liquor streams, and membrane filtration equipment for molecular weight fractionation. Single-source vulnerability concentrates in Nordic integrated producers controlling captive sulfate economics. Distribution runs through construction chemical distributors in Germany, oilfield service contractors in Texas, and agricultural input brokers in Iowa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where membrane filtration miniaturization enables modular, on-site formulation ecosystems that displace centralized powder production. Interoperability between sulfonation process control and application-specific formulation capabilities is reshaping competitive boundaries.
For Market Incumbents: Shield market position by deepening backward integration into Norwegian and Swedish pulp milling to defend cost structures against merchant chemical challengers. Invest in REACH dossier maintenance and GB standard testing protocol alignment to preserve European and Chinese channel access. Prioritize membrane filtration technology licensing to capture value from oilfield service contractor decentralization trends.
For New Entrants and Emerging Players: Oilfield logistics optimization services represent the most penetrable white space, where incumbent suppliers under-serve remote Saudi and UAE drilling locations with liquid formulation flexibility. Target ammonium lignosulfonate specialty grades for high-temperature stability applications in Middle East drilling programs. Pursue joint development agreements with regional oilfield service contractors to bypass established powder distribution networks.
For Investors and Strategic Acquirers: EPA dust-control mandate enforcement reshapes the acquisition landscape by consolidating procurement toward specification-grade suppliers with efficacy documentation capabilities. Long-term viability favors integrated pulp-to-lignin operators with captive sulfate supply and established toxicological dossiers. Watch for sulfate-emission threshold tightening at pulp mills as the signal for which merchant producers will exit versus defend market positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Milling | Nordic producers leverage captive sulfate supply to sustain cost advantages against merchant chemical competitors. |
| Membrane Filtration Technology Licensing | Modular production footprints enable oilfield service contractors to formulate on-site at remote Saudi drilling locations. |
| REACH Dossier Investment | Full toxicological documentation preserves European customs clearance and construction chemical distributor channel access. |
| Specialty Ammonium Grade Development | High-temperature stability above 150°C captures premium positioning in Saudi Aramco and ADNOC drilling programs. |
| Biostimulant Binder Convergence | Combining lignosulfonate pellet binders with microbial carriers opens precision agriculture input portfolios in Brazil. |
Research Approach
A spread of perspectives from construction chemical procurement managers, oilfield drilling fluid engineers, feed ingredient brokers, pulp mill operations directors, and agricultural input distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, SEC 10-K filings from integrated pulp producers, EPA enforcement action records, and SAMR GB standard publication archives. Bottom-up volume modeling triangulated against top-down value estimates across the projection horizon.
Segmentation dimensions modeled include cation chemistry tier, end-use application specification, form factor, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis by buyer archetype and input cost trajectory assumptions. Forecast inputs incorporated sulfate-emission compliance cost curves at pulp mills and polycarboxylate ether substitution rates in high-performance concrete.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement, REACH registration requirements, and SAMR GB 8076 standards; material policy shifts would require re-modeling. Specific risks include pulp mill closure cascades from environmental compliance cost spikes and accelerated synthetic dispersant adoption in premium construction segments. Recalibration cycles align with material shifts in sulfate input economics and Middle East drilling activity intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market