
 Glass Adhesive Market | 2026-2036
Glass Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Adhesive Market Analytics
Asset-light toll manufacturing and third-party formulation partnerships is tilting competitive dynamics toward firms that outsource production while retaining IP control. Henkel AG & Co KGaA leverages its automotive OEM relationships to sustain specification lock-in across windshield bonding protocols. Dow Inc. anchors its position through captive silicone supply and in-house production of organofunctional silanes. Sika AG competes via construction channel density and direct contractor training programs.
Glass adhesive denotes a structural bonding agent engineered to join glass substrates to metal, composite, or ceramic surfaces, typically achieving lap-shear strengths exceeding 15 MPa and maintaining optical clarity after UV or thermal cure cycles. These formulations serve critical load-bearing and sealing functions where mechanical fasteners would compromise transparency or induce stress concentrations. Silicone formulations dominate architectural glazing and automotive sealing due to their elastomeric recovery and weathering resistance, while polyurethane systems lead structural automotive applications where crash energy absorption is specified. Epoxy segments occupy high-strength electronics and aerospace niches where outgassing limits and thermal cycling tolerance are mandated, though their rigidity restricts use in expansion-joint scenarios.
FDA regulates glass adhesive indirect food contact under 21 CFR 175.105 for appliance and packaging applications, while EPA VOC limits under 40 CFR 59 reshape formulation chemistry toward water-based and reactive hot-melt systems. OSHA hazard communication standards govern isocyanate handling in polyurethane production, elevating capital costs for smaller compounders. Stakeholders must monitor evolving state-level VOC thresholds and automotive OEM bonding specifications that increasingly mandate crash-durable structural integrity without mechanical assist.
Market Dynamics
Automotive OEM crashworthiness mandates for electric vehicle panoramic roofs are forcing adhesive suppliers to reformulate for higher dynamic shear strength without sacrificing optical clarity, compressing qualification timelines from 36 months to 18 months.
Growth Catalysts
- EU REACH VOC restrictions:Regulatory pressure on volatile organic compounds accelerates water-based and reactive hot-melt formulation adoption across architectural glazing applications in Germany and France.
- Windshield bonding protocols:Automotive OEM specification lock-in for structural glass bonding creates durable demand pull from electric vehicle production lines requiring seamless panoramic roof integration.
- Silicone elastomer recovery:Superior weathering resistance and thermal cycling tolerance position silicone formulations as the default choice for high-performance architectural sealing in coastal climates.
Market Restraints
- Organofunctional silane supply concentration:Captive production of critical silicone precursors concentrates among integrated chemical majors, limiting formulation flexibility for mid-tier compounders.
- Isocyanate handling capital intensity:OSHA hazard communication standards for polyurethane production elevate facility investment thresholds, squeezing smaller regional manufacturers.
- Epoxy rigidity limitation:Thermal expansion mismatch restricts epoxy systems to electronics and aerospace niches, excluding them from expansion-joint architectural applications where silicone dominates.
Strategic Opportunities
- India construction channel penetration:Underdeveloped contractor certification programs for structural glazing create first-mover advantage for training-integrated adhesive suppliers.
- Photovoltaic module edge-sealing:Dual-glass solar panel architectures generate incremental demand for UV-stable, moisture-blocking perimeter bonding solutions.
- Japan METI carbon neutrality roadmap:Domestic green procurement incentives favor low-carbon-footprint waterborne formulations in public infrastructure projects.
Industry Challenges
- Automotive OEM qualification compression:Compressed 18-month validation cycles strain R&D throughput for crash-durable structural adhesives requiring simultaneous optical and mechanical certification.
- Cross-regulatory formulation complexity:Divergent EPA VOC limits, EU REACH substance restrictions, and state-level thresholds force parallel product line maintenance, fragmenting production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Adhesive Market |
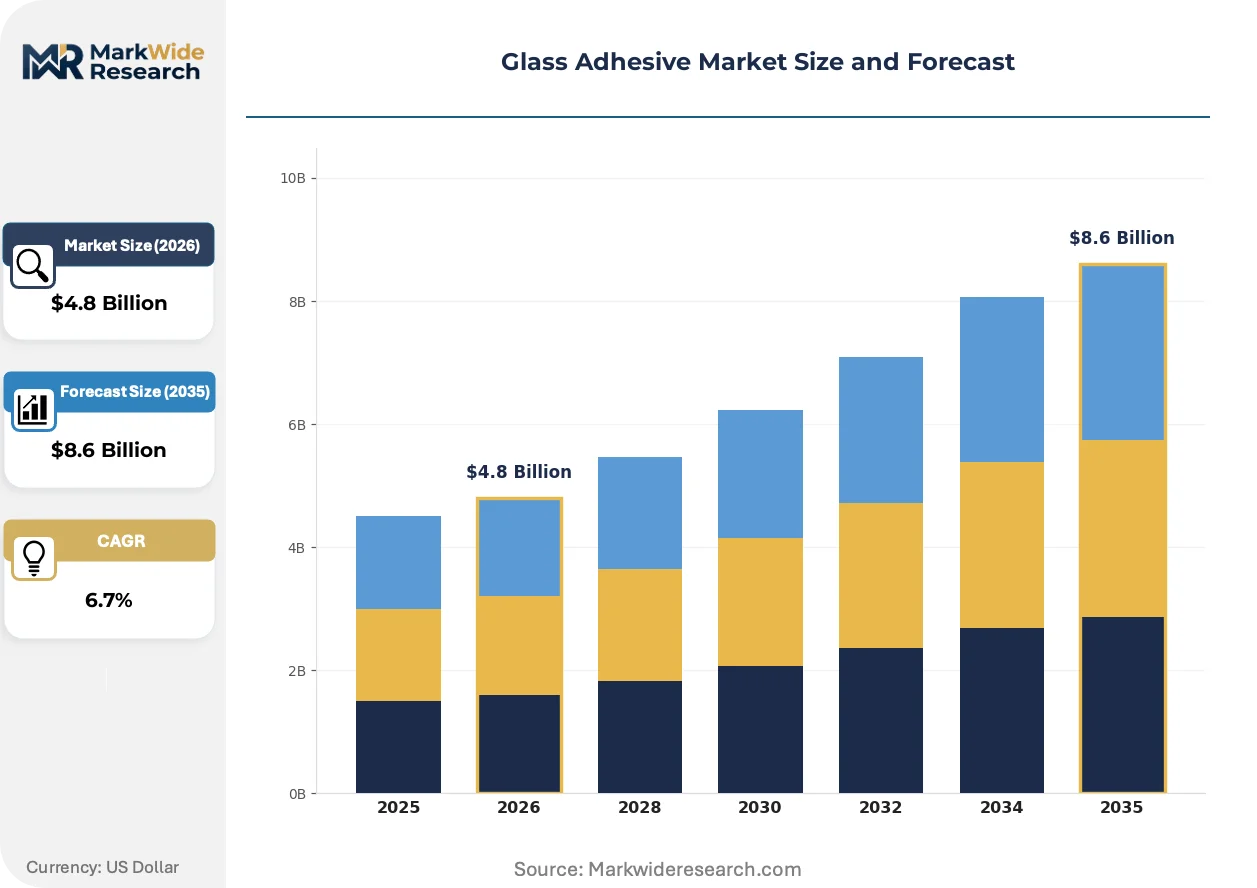
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Epoxy, Acrylic Application: Automotive, Construction, Electronics, Aerospace End User: Manufacturers, Contractors, Retailers, Wholesalers Formulation: Solvent-based, Water-based, Hot-melt, Reactive |
| Companies Covered | 3M, Arkema SA, Henkel AG & Co KGaA, Wacker Chemie AG, DuPont de Nemours Inc., Sika AG, Dow Inc., Dymax Corporation, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Adhesive Market Evolving Landscape
Formulation chemistry is pivoting toward reactive systems that cure on demand while eliminating solvent carriers, driven by regulatory pressure and automotive qualification demands. This shift is compressing traditional product lifecycles and reshaping supplier R&D priorities.
Two-part polyurethane structural adhesives with crash-durable energy absorption are rendering obsolete conventional one-component moisture-cure systems in automotive windshield bonding. Tier 1 suppliers in Germany and South Korea have adopted these formulations for electric vehicle platforms. The technology is rendering obsolete legacy bonding protocols that relied on mechanical fasteners for secondary structural assurance.
EPA 40 CFR 59 VOC limits are forcing architectural adhesive manufacturers toward water-based and reactive hot-melt chemistries that eliminate solvent carriers. The regulation compresses allowable emissions thresholds in commercial construction applications. Formulators serving the US Northeast corridor are accelerating capital deployment to hot-melt production lines ahead of state-level adoption of federal standards.
Automotive OEMs are consolidating approved supplier lists for structural glass bonding, compressing switching options for tiered component manufacturers. Direct specification relationships between adhesive producers and OEM engineering teams are displacing distributor-mediated procurement in high-volume programs. This concentration is most visible in German automotive manufacturing clusters where KBA type-approval requirements elevate barrier-to-entry for unqualified suppliers.
Glass Adhesive Market Segmentation
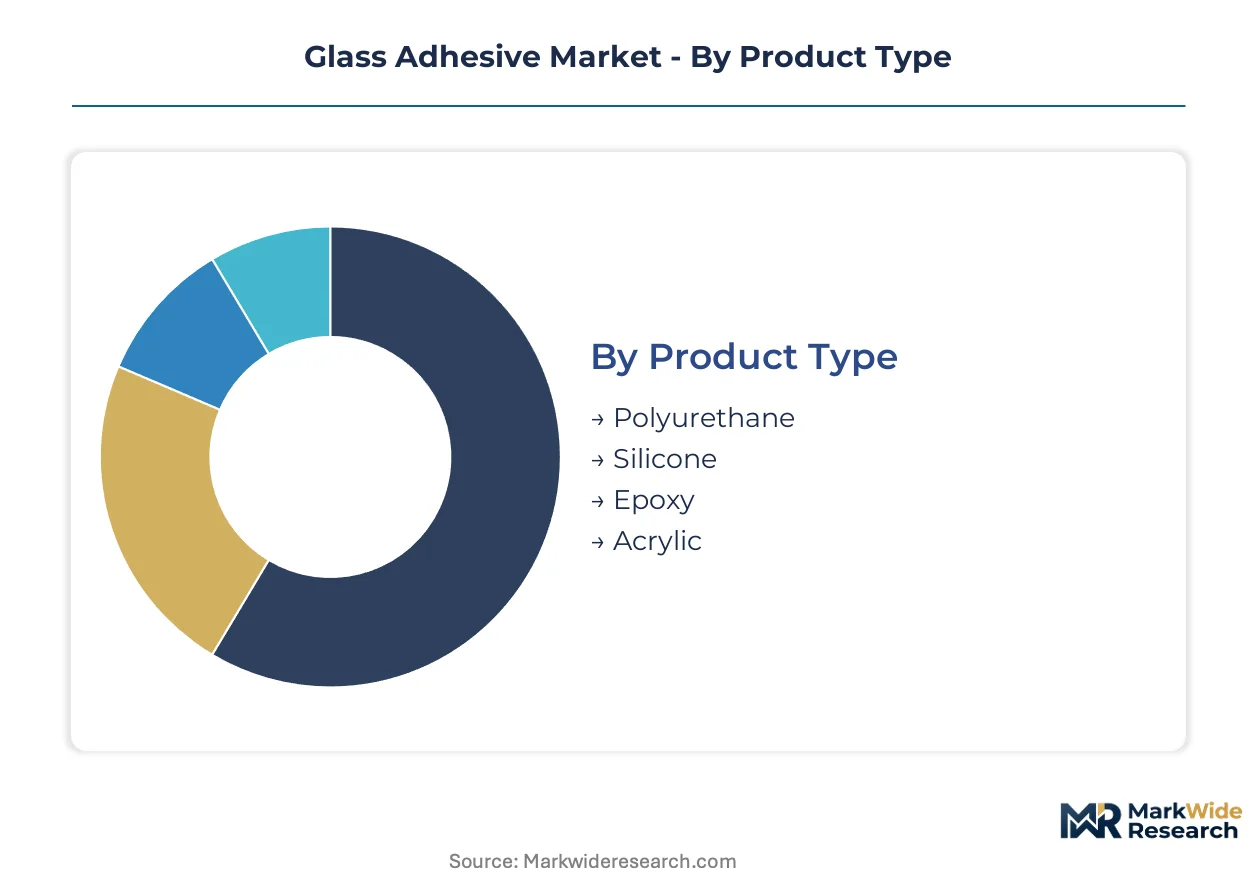
Glass adhesive segmentation reveals how formulation chemistry, application requirements, and channel economics create distinct competitive arenas. Suppliers must align R&D investment and distribution strategy with the technical and regulatory demands of each segment cluster.
Product Type:
Product chemistry determines performance ceilings across load-bearing, optical, and environmental stress scenarios.
- Polyurethane:Two-part structural systems achieve crash-durable energy absorption for automotive windshield bonding. German OEMs specify these formulations for electric vehicle panoramic roof assemblies where dynamic shear strength must exceed 15 MPa without optical distortion.
- Silicone:Elastomeric formulations with superior weathering resistance and thermal cycling tolerance dominate architectural glazing and automotive sealing. Coastal climate applications in Florida and Mediterranean markets drive specification for UV-stable perimeter bonding.
- Epoxy:High-rigidity systems serve electronics and aerospace niches demanding outgassing control and thermal cycling tolerance, though thermal expansion mismatch excludes expansion-joint applications.
- Acrylic:Cost-competitive formulations for general-purpose bonding where optical clarity requirements are moderate and load-bearing demands are secondary.
The dominant share belongs to Silicone, while Polyurethane is closing the gap fastest.
Application:
End-use verticals impose divergent certification timelines and performance validation protocols.
- Automotive:Structural glass bonding for electric vehicle production lines requires 18-month OEM qualification cycles for crash-durable formulations. KBA type-approval requirements in Germany elevate barrier-to-entry for unqualified suppliers.
- Construction:Architectural glazing demand concentrates in commercial facade and residential window systems. EPA 40 CFR 59 VOC limits are accelerating water-based and reactive hot-melt adoption across US Northeast corridor projects.
- Electronics:Epoxy-based die-attach and display bonding applications mandate low-outgassing formulations for semiconductor packaging and optical device assembly.
- Aerospace:Thermal cycling tolerance and outgassing limits under FAA certification protocols restrict qualified suppliers to specialized epoxy and modified silicone systems.
Automotive commands the largest revenue pool, with Construction expanding most quickly on regulatory-driven formulation shifts.
End User:
Channel structure determines margin capture and specification influence.
- Manufacturers:Direct OEM relationships for automotive and electronics producers enable specification lock-in and technical collaboration on custom formulations.
- Contractors:Installation channel density in construction markets requires training-integrated supplier programs, particularly underdeveloped in emerging markets like India.
- Retailers:Consumer and light commercial segments through hardware and home improvement channels, price-sensitive with limited technical support requirements.
- Wholesalers:Distribution intermediaries serving regional construction markets with inventory breadth and logistics efficiency as primary value propositions.
Manufacturers retain the highest margin profile, while Contractors offer the steepest expansion trajectory in underpenetrated construction markets.
Formulation:
Regulatory pressure on volatile organic compounds is restructuring production economics and capital allocation.
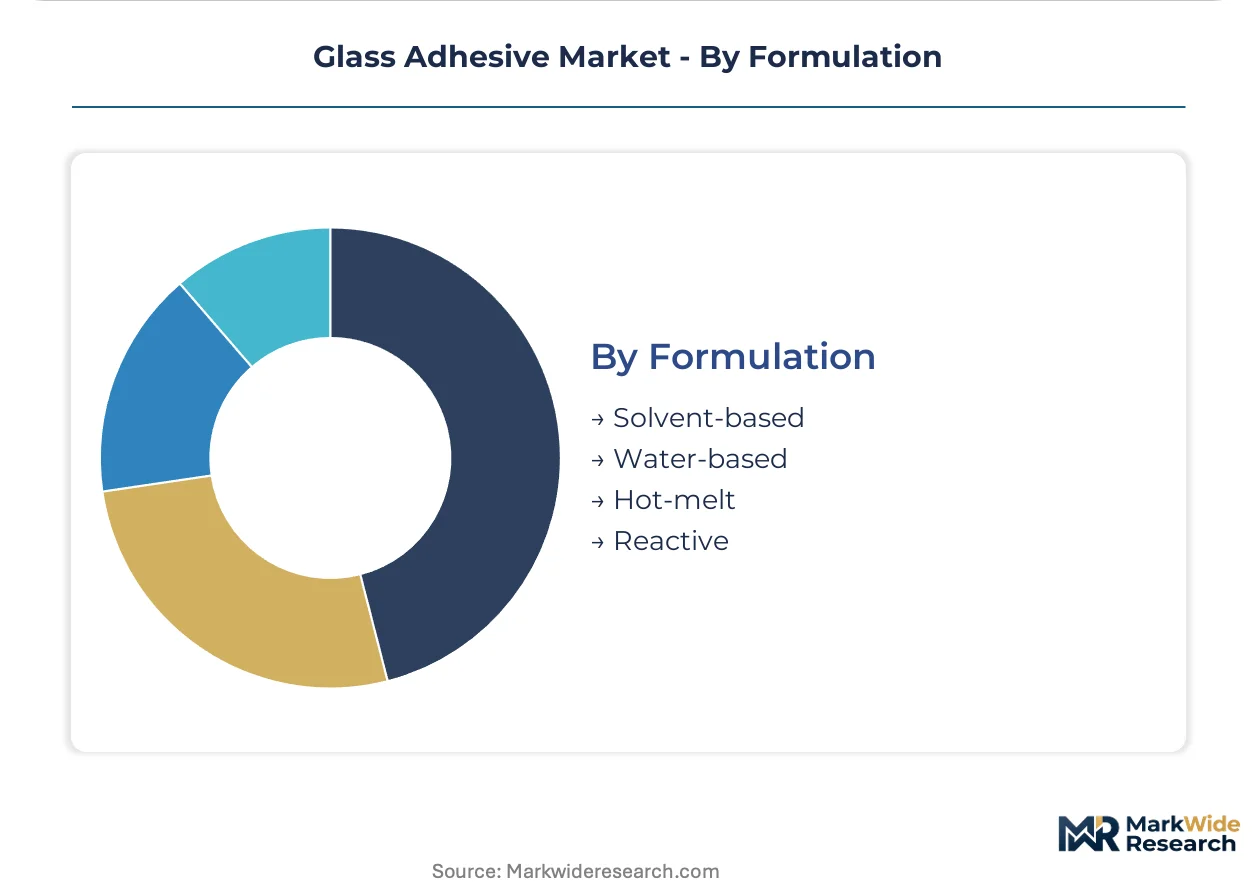
- Solvent-based:Legacy formulations facing contraction under EPA VOC limits and EU REACH restrictions, with remaining demand concentrated in aerospace applications where exemption pathways persist.
- Water-based:Low-emission systems gaining share in architectural glazing as US Northeast states adopt federal VOC standards ahead of schedule.
- Hot-melt:Reactive systems eliminating solvent carriers through thermal activation, requiring capital deployment to modified production lines.
- Reactive:Two-part polyurethane and silicone systems curing on demand for structural automotive applications, compressing traditional moisture-cure product lifecycles.
Reactive formulations lead technology investment, with Water-based gaining share fastest on regulatory compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH VOC restrictions and Japan METI carbon neutrality incentives are redirecting formulation investments toward water-based and reactive systems across automotive and construction applications. National procurement policies now favor low-emission bonding solutions in public infrastructure tenders. Industrial clusters in Germany, Japan, South Korea, and the United States concentrate qualified supplier relationships for structural glass bonding.
Germany
Automotive OEM specification lock-in for electric vehicle panoramic roofs drives demand for crash-durable polyurethane formulations. KBA type-approval requirements elevate barrier-to-entry for adhesive suppliers seeking windshield bonding protocol qualification. Stuttgart and Munich manufacturing clusters host tier-1 suppliers deploying two-part structural systems for premium EV platforms.
United States
EPA 40 CFR 59 VOC limits are accelerating water-based and reactive hot-melt adoption across architectural glazing in the Northeast corridor. OSHA hazard communication standards for isocyanate handling concentrate polyurethane production among capital-intensive compounders. Detroit automotive engineering centers specify structural glass bonding protocols for electric vehicle assembly lines.
Japan
METI carbon neutrality roadmap incentives favor low-carbon-footprint waterborne formulations in public infrastructure procurement. Domestic automotive OEMs consolidate approved supplier lists for structural glass bonding, compressing qualification timelines. Nagoya and Tokyo industrial corridors anchor silicone formulation R&D for high-performance architectural sealing applications.
South Korea
Electric vehicle production expansion creates demand pull for crash-durable structural adhesives in panoramic roof assemblies. MFDS-equivalent industrial chemical regulations govern formulation registration for construction and automotive applications. Ulsan and Gyeonggi-do manufacturing hubs host tier-1 suppliers adopting two-part polyurethane systems for OEM qualification.
China
Dual carbon goals under MEE direction push architectural adhesive manufacturers toward water-based chemistries in commercial facade projects. GB standards for construction materials increasingly reference VOC emission limits comparable to EU REACH thresholds. Yangtze River Delta industrial zones concentrate silicone formulation capacity for photovoltaic module edge-sealing applications.
Glass Adhesive Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-driven automotive segments and training-dependent construction markets. Consolidation concentrates among integrated chemical majors with captive silicone precursor supply, while mid-tier compounders face capital barriers to polyurethane production. Three archetypes dominate: automotive OEM specification holders, construction channel trainers, and vertically integrated silicone producers. Competitive moves center on qualification timeline compression and regional toll manufacturing partnerships.
Within the integrated chemical tier, Dow Inc. and Wacker Chemie AG exemplify upstream control over organofunctional silane supply. Henkel AG & Co KGaA occupies a position as an automotive OEM relationship anchor. Sika AG represents the construction channel density archetype through contractor training programs. These three patterns illustrate how specification lock-in, captive supply, and installation expertise create defensible positioning across divergent end-use verticals.
| Leading Market Players |
|---|
| 3M |
| Arkema SA |
| Henkel AG & Co KGaA |
| Wacker Chemie AG |
| DuPont de Nemours Inc. |
| Sika AG |
| Dow Inc. |
| Dymax Corporation |
| H.B. Fuller Company |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp chemical corridor anchors European glass adhesive logistics, with freight cost volatility amplifying price spreads between captive silane producers and formulation-dependent compounders while compressing margins for non-integrated suppliers serving automotive OEMs.
Pricing Analysis
Certification level creates the primary spread, with KBA type-approved automotive formulations commanding substantial premia over general architectural grades. Three-tier pricing structure separates OEM-validated structural systems from commercial construction standards and economy-grade retail products. Cost compression in mid-tier polyurethane segments is intensifying because German automotive qualification timelines have compressed from 36 months to 18 months, forcing accelerated R&D amortization. Contract manufacturers exhibit highest price sensitivity, while direct OEM relationships retain pricing power through specification lock-in.
Supply Chain Analysis
Toll manufacturers in Germany, the United States, and China hold the majority of formulation capacity for non-integrated compounders. Raw material flows draw from organofunctional silane production concentrated among integrated chemical majors, isocyanate supply chains governed by OSHA handling standards, and epoxy resin networks serving electronics niches. Single-source vulnerability in silicone precursor supply elevates risk for mid-tier adhesive producers lacking captive silane production. Distribution runs through direct OEM specification channels for automotive, contractor training programs for construction, and wholesale distributors for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation of approved supplier lists is creating platform-economics dynamics where interoperability across windshield bonding protocols determines competitive survival, similar to software ecosystem lock-in.
For Market Incumbents: Entrench specification relationships by embedding technical teams within Stuttgart and Detroit OEM engineering centers to compress qualification cycles. Prioritize backward integration into organofunctional silane production to neutralize raw material leverage from integrated chemical majors. The threat of captive silicone supply from Dow and Wacker demands defensive supply agreements with second-tier silane producers.
For New Entrants and Emerging Players: Pursue underdeveloped contractor certification programs in India's construction channel, where structural glazing training infrastructure remains fragmented and first-mover advantage is available. Target photovoltaic module edge-sealing applications, where dual-glass solar panel architectures generate incremental demand without entrenched incumbent relationships. A training-integrated go-to-market approach builds channel loyalty faster than price competition.
For Investors and Strategic Acquirers: Asset-light formulation specialists with OEM qualification relationships represent the most defensible acquisition archetype, combining IP control with outsourced production flexibility. Long-term viability hinges on regulatory compliance capabilities across divergent EPA VOC limits and EU REACH substance restrictions. Watch for inflection when automotive OEMs consolidate approved supplier lists below ten qualified structural glass bonding providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Captive organofunctional silane production neutralizes supply concentration risk from Dow and Wacker. |
| Automotive OEM Co-Development Programs | Direct engineering collaboration with Stuttgart and Detroit platforms secures 18-month qualification lock-in. |
| Contractor Certification Infrastructure | Training-integrated programs in India and Southeast Asia build construction channel density ahead of competitors. |
| Reactive Formulation Capacity Expansion | Hot-melt and two-part polyurethane lines address EPA 40 CFR 59 VOC compliance and automotive crash-durable specifications. |
| Photovoltaic Edge-Sealing Partnerships | Dual-glass solar panel architectures in China and South Korea generate UV-stable bonding demand outside entrenched automotive supply chains. |
Research Methodology
A spread of perspectives from adhesive formulators, automotive OEM procurement leads, construction contractors, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with plant managers at German and South Korean tier-1 suppliers, technical R&D directors at silicone and polyurethane compounders, and channel partners serving US Northeast architectural glazing markets. Secondary validation drew from KBA type-approval databases, EPA 40 CFR 59 regulatory filings, EU REACH substance restriction updates, and customs data tracking organofunctional silane trade flows. Bottom-up segment sizing triangulated against top-down chemical industry production estimates.
Demand-supply balance modeling anchored the forecast framework, with volume projections built from automotive OEM production schedules, commercial construction permit data, and photovoltaic installation forecasts across the analysis window. Segmentation dimensions included formulation chemistry, application vertical, end-user channel structure, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines reported by integrated chemical majors. Industry-specific inputs incorporated electric vehicle panoramic roof penetration rates and state-level VOC threshold adoption patterns.
Sensitivities concentrate around automotive OEM qualification timeline compression, REACH substance restriction scope expansion, and silane precursor supply disruptions. Forecasts reflect assumptions about regulatory enforcement intensity and OEM supplier list consolidation velocity. Quarterly review of KBA type-approval announcements, EPA state-level VOC adoption, and photovoltaic module architecture shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market