
 Atrazine Market | 2026-2036
Atrazine Market Size, Share, and Industry Trends Forecast 2026-2036
Atrazine Market Intelligence
Procurement within the atrazine user base is pivoting from smallholder farms toward large, consolidated agricultural corporations. Syngenta AG leverages its extensive R&D to develop specific formulations for major crops. Corteva Agriscience competes with a broad portfolio of crop protection solutions, including atrazine-based products. ADAMA Ltd. specializes in providing off-patent herbicide options to cost-sensitive agricultural markets.
Atrazine is a selective triazine herbicide, with the chemical formula C8H14ClN5, that functions by inhibiting photosynthesis in targeted weeds. It is applied pre- or post-emergence to control broadleaf and grassy species. Liquid formulations dominate the product landscape due to their ease of mixing and application with standard farm equipment. Corn and sugarcane applications constitute the primary volume segments, far outweighing use in turf management.
Regulatory scrutiny defines market access and product specifications. The U.S. EPA periodically reviews and sets strict application rates, while the European Union maintains a complete ban on atrazine under ECHA regulations. In parallel, Brazil's ANVISA oversees registration and use in its vast agricultural sector. Consequently, future success depends on developing formulations that meet disparate and evolving environmental safety standards.
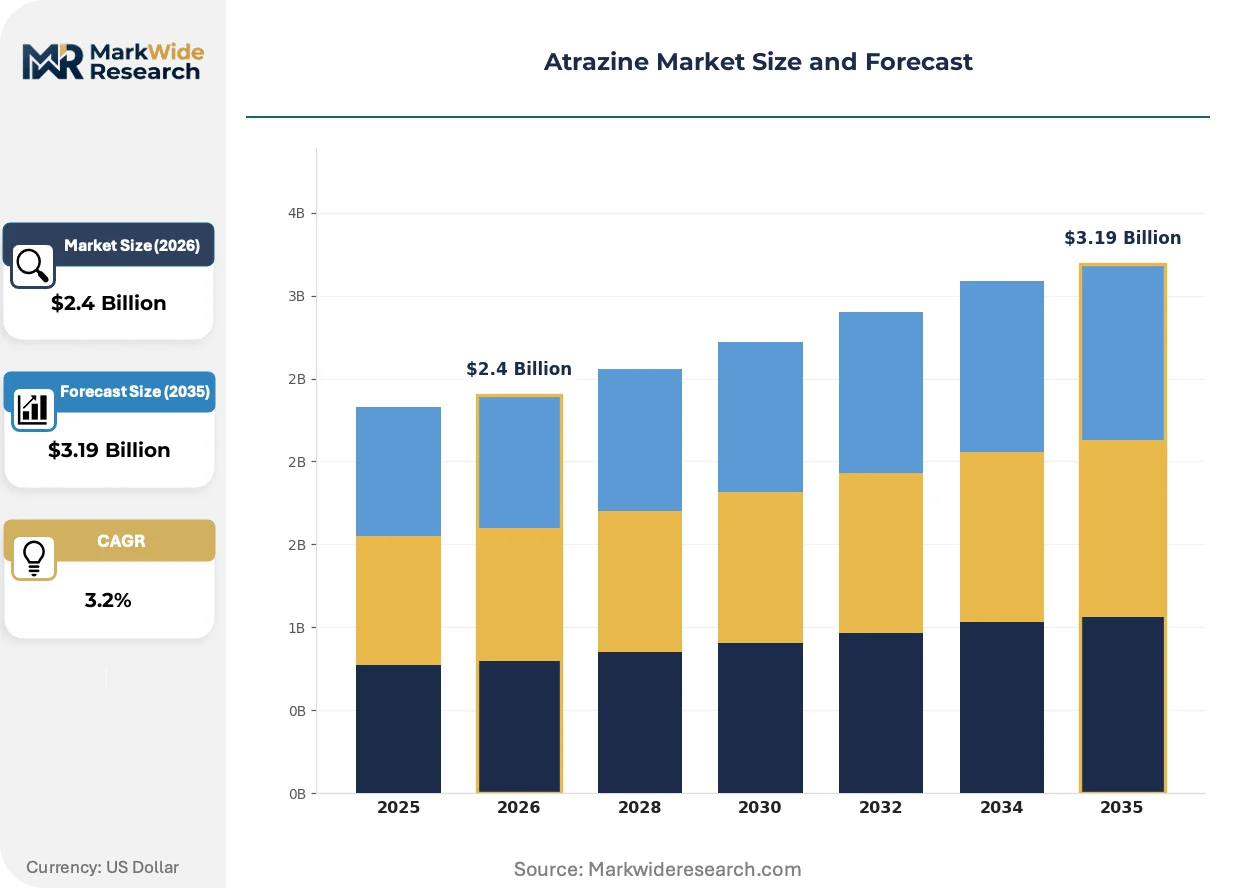
Market Dynamics
The central dynamic within the atrazine market is the conflict between its established agricultural utility, particularly in corn and sugarcane, and intensifying regulatory pressure. This tension, driven by environmental safety concerns, forces continuous product reformulation to comply with disparate standards from agencies like the U.S. EPA and Brazil's ANVISA.
Growth Catalysts
- Sugarcane Cultivation:High efficacy in controlling broadleaf weeds in sugarcane fields sustains demand, especially in Brazil, which is a leading producer and consumer of atrazine for this specific application.
- Cost-Effectiveness:As an off-patent herbicide, atrazine offers a cost-competitive solution for large-scale agricultural corporations managing vast acreages of corn and sorghum, helping to control operational input costs.
- Liquid Formulations:The dominance of liquid formulations, which are easy to handle and compatible with standard farm spraying equipment, facilitates straightforward application and integration into existing agricultural workflows.
Market Restraints
- Regulatory Prohibitions:The complete ban on atrazine use within the European Union, enforced by ECHA, permanently closes off a substantial market and serves as a precedent for regulators in other regions.
- Alternative Weed Control:The development and adoption of alternative herbicides with different modes of action, alongside the promotion of integrated pest management (IPM) techniques, create a persistent substitution threat.
- Water Contamination Scrutiny:Ongoing concerns regarding atrazine's potential for leaching into groundwater and surface water runoff drive stricter application rate limits and buffer zone requirements from regulators like the EPA.
Strategic Opportunities
- Low-Drift Formulations:There is a clear opportunity in developing advanced formulations, such as encapsulated or polymer-coated atrazine, that minimize off-target drift and volatilization to meet stricter environmental regulations.
- Bio-herbicide Blends:Creating blended products that combine atrazine with bio-based herbicides can improve environmental profiles, address weed resistance, and appeal to markets with a growing interest in sustainable agriculture.
- Expansion in Turf Management:Targeting the professional turfgrass sector for golf courses and sod farms with specialized, lower-concentration products provides a diversification opportunity beyond primary row crop applications.
Industry Challenges
- Navigating Divergent Regulations:Manufacturers face the significant operational burden of developing, registering, and marketing products that comply with a patchwork of different and evolving safety standards across key markets like the U.S., Brazil, and Australia.
- Managing Public Perception:Countering negative public and media narratives surrounding atrazine's environmental and health impacts requires sustained investment in scientific communication, stakeholder engagement, and transparent data sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrazine Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Granules, Liquid Formulation, Wettable Powder Application: Corn, Sugarcane, Sorghum, Turf Management, Pasture, Others End Use Industry: Crop Producers, Plantations, Greenhouse Operators, Organic Farming, Seed Producers Packaging Type: Drums, Bottles, Jugs, Bulk Containers, Bags |
| Companies Covered | ADAMA Ltd., Nufarm Limited, Syngenta AG, Albaugh LLC, AMVAC Chemical Corporation, Corteva Agriscience, UPL Limited, Zhejiang Jinfanda Biochemical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrazine Market Strategic Shifts & Innovations
Product innovation is concentrating on enhancing formulation stability and targeted delivery to satisfy stringent environmental mandates. This effort runs parallel to advancements in application hardware, which are enabling more precise and efficient use of the herbicide in large-scale agricultural operations.
Precision application technology, including GPS-guided sprayers and sensor-equipped drones, enables variable-rate application of atrazine directly where it is needed. Major agricultural corporations in the United States and Brazil are integrating these tools to optimize chemical use and reduce waste. This technology is automating field-level decisions on herbicide dosage, minimizing overuse and mitigating the risk of environmental contamination.
The U.S. EPA’s ongoing registration review process for triazine herbicides directly influences product development cycles. These regulatory evaluations compel manufacturers to invest heavily in new toxicological and environmental fate studies to defend existing uses or gain approval for new ones. The corn and sugarcane segments are most impacted, with formulators adjusting product compositions to maintain efficacy while adhering to revised application rates.
A notable shift in purchasing behavior is the centralization of crop protection procurement within large, consolidated farming enterprises. This trend moves purchasing decisions away from individual farm managers to corporate sourcing teams that demand volume-based pricing and comprehensive support. This dynamic is most visible in the primary agricultural economies of North and South America, altering supplier-customer relationships.
Atrazine Market Segmentation
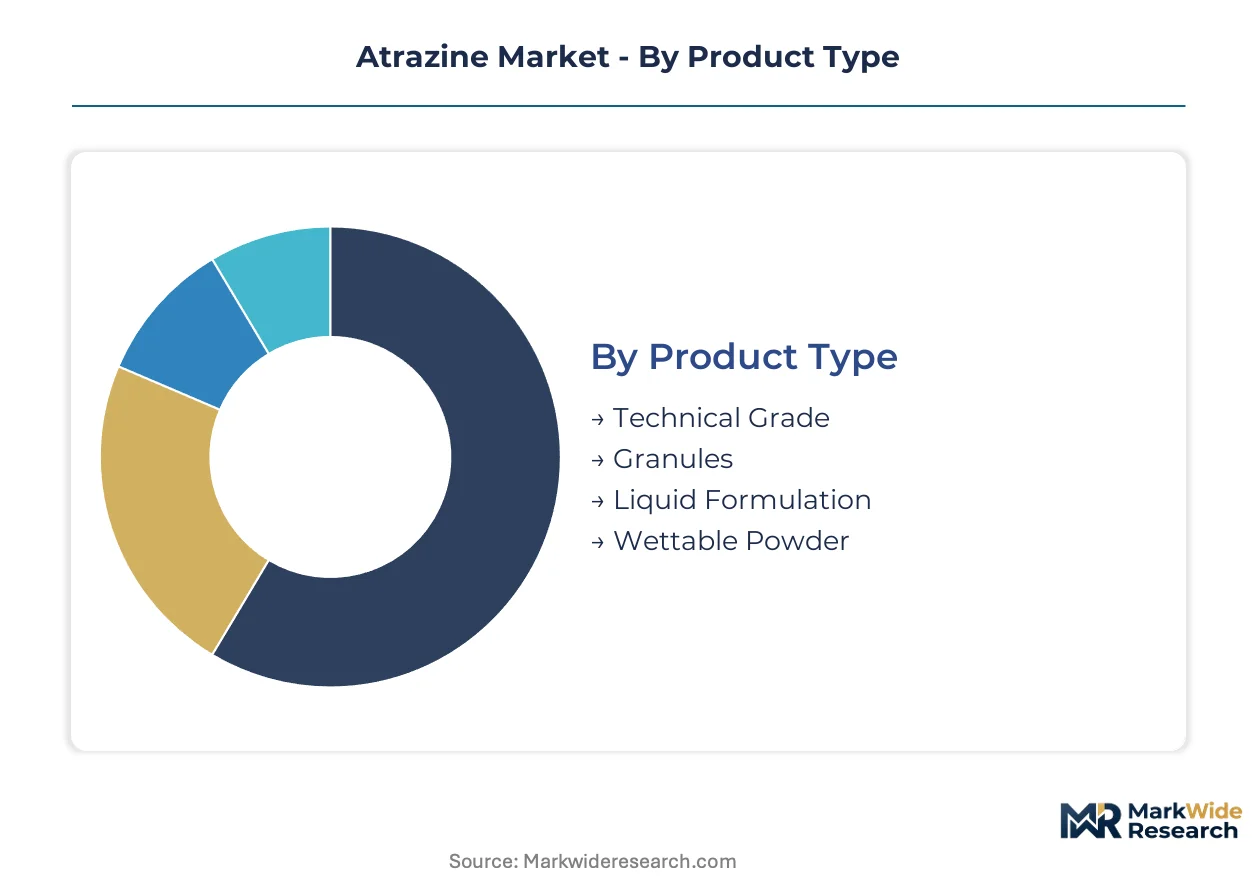
The atrazine market segments across product type, application, end-use industry, and packaging, reflecting diverse agricultural practices and regulatory environments. Understanding these segments helps manufacturers tailor product formulations and delivery strategies for specific customer needs. This segmentation highlights the varying demands across different agricultural scales and crop types.
Product Type:
Product type segmentation is heavily influenced by the regulatory burden associated with formulation approvals and environmental safety standards. Manufacturers must ensure each variant meets specific agency requirements, such as those from the U.S. EPA and Brazil's ANVISA.
- Liquid Formulation:This product type consists of emulsifiable concentrates or soluble liquids, offering superior mixing characteristics and ease of application through standard farm spraying equipment. Demand concentrates in corn and sugarcane cultivation across the United States and Brazil, driven by operational efficiency and compatibility with existing machinery.
- Technical Grade:This segment represents the pure active ingredient, requiring stringent quality control and registration for manufacturing other formulations. Demand primarily comes from formulators and large chemical companies for further processing into end-use products, necessitating high purity and compliance with active ingredient regulations.
- Granules:Granular atrazine formulations are solid, designed for specific soil application methods.
- Wettable Powder:This powder form disperses in water before spraying, offering an alternative for specific equipment types.
Liquid Formulation sits at the top of the volume ranking, with Technical Grade climbing the fastest.
Application:
Application segments clarify where atrazine delivers its primary utility, with demand volume heavily concentrated in major row crops. These applications define the largest commercial opportunities for manufacturers.
- Corn:Atrazine is a foundational herbicide in corn production, providing effective pre- and post-emergence control of broadleaf and grassy weeds. Demand is robust in the United States and other major corn-producing regions, supporting large-scale, cost-effective weed management.
- Sugarcane:The herbicide offers high efficacy in controlling broadleaf weeds in sugarcane fields, which is crucial for maximizing crop yield in tropical and subtropical climates. Brazil is a leading consumer for this application, where its utility sustains significant market demand.
- Sorghum:Atrazine provides essential weed control for sorghum crops in key agricultural regions.
- Turf Management:This segment includes professional applications on golf courses and sod farms, requiring specialized, lower-concentration products.
- Pasture:Atrazine is used for selective weed control in pasture to improve forage quality.
- Others:This category encompasses smaller, specialized applications across various minor crops.
The market sees significant demand from Corn while Turf Management exhibits steepest expansion trajectory.
End Use Industry:
The end-use industry segmentation reflects the diverse customer base for atrazine, with procurement patterns increasingly centralized among larger entities. This shift influences product packaging and distribution strategies.
- Crop Producers:This segment includes large-scale agricultural corporations and individual farm owners cultivating vast acreages of crops like corn and sorghum. Procurement within this group increasingly centralizes, demanding volume-based pricing and comprehensive support services.
- Plantations:Plantations, particularly those focused on sugarcane, represent a significant end-use, requiring consistent supply and specialized application solutions. These operations often have dedicated procurement teams and long-term supply agreements.
- Greenhouse Operators:Greenhouse operators use atrazine for weed control in controlled environments, subject to environmental restrictions.
- Organic Farming:Atrazine is not permitted in certified organic farming due to its synthetic nature.
- Seed Producers:Seed producers utilize herbicides to maintain weed-free fields, ensuring seed purity.
Consolidated agricultural corporations drive procurement, impacting supplier relationships.
Packaging Type:
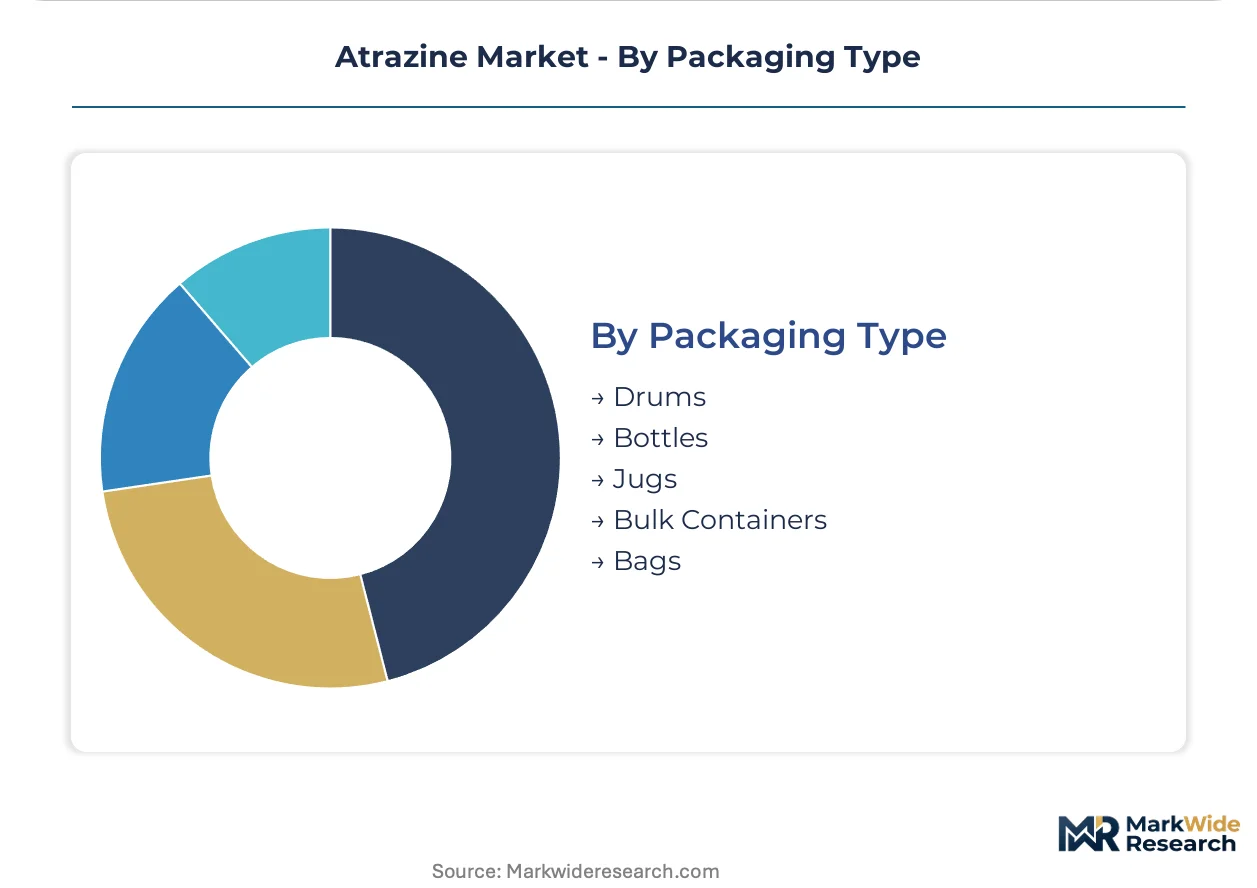
Packaging type is closely tied to the scale of agricultural operations and distribution logistics, with larger formats catering to high-volume users. Supply concentration in this segment is driven by efficiency and cost-effectiveness for major agricultural economies.
- Bulk Containers:These large-capacity containers are designed for high-volume delivery to major agricultural corporations and cooperative buying groups. They optimize logistics and reduce per-unit costs for extensive acreage applications in regions like the United States and Brazil.
- Drums:Standard industrial drums, typically 200-liter capacity, provide a common packaging solution for liquid atrazine formulations. They serve medium to large-scale farms and distributors, balancing volume with manageable handling.
- Bottles:Smaller bottles cater to specialized applications or smaller farm operations requiring lower volumes.
- Jugs:Intermediate-sized jugs offer a practical option for farm-level distribution, balancing volume with ease of handling.
- Bags:Bags are primarily used for granular or wettable powder formulations, offering convenience for dry product handling.
Large-scale agricultural operations prioritize efficient, high-volume packaging solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory divergence between Brazil and the European Union significantly shapes global atrazine market dynamics. While Brazil's ANVISA permits its widespread use in sugarcane, the European Union maintains a complete ban, influencing global trade flows and product development strategies. This regulatory landscape compels manufacturers to adapt formulations for specific regional requirements.
United States
Corn and sorghum cultivation drives substantial atrazine demand across the Midwest agricultural belt. The U.S. EPA's ongoing re-registration reviews influence product formulation and application rates. Major agricultural corporations in states like Iowa and Nebraska integrate precision application technologies to optimize chemical use and comply with environmental mandates.
Brazil
Sugarcane cultivation represents the primary volume segment for atrazine in Brazil, supporting the country's dominant position in global sugar production. ANVISA oversees the registration and use of herbicides, ensuring adherence to national environmental standards. The vast agricultural regions of São Paulo and Minas Gerais are key consumption hubs for atrazine-based products.
China
Agricultural expansion and the need for efficient weed control in corn and sorghum fields contribute to atrazine demand in China. The Ministry of Agriculture and Rural Affairs (MARA) regulates pesticide use and environmental protection. Producers in provinces like Shandong and Henan are increasingly adopting modern farming techniques, influencing herbicide consumption patterns.
India
Atrazine finds application in corn and sugarcane farming across various agricultural states in India, supporting crop yield. The Central Insecticides Board & Registration Committee (CIBRC) governs the registration and use of agrochemicals. Farming communities in Punjab and Maharashtra utilize atrazine as a cost-effective weed management solution for major crops.
Australia
Broadacre cropping, particularly in corn and sorghum, underpins atrazine consumption in Australia's agricultural sector. The Australian Pesticides and Veterinary Medicines Authority (APVMA) sets stringent standards for chemical registration and application. Farmers in Queensland and New South Wales rely on atrazine for effective weed control in their extensive farming operations.
Atrazine Market Key Industry Players
North American and European producers anchor one tier of the atrazine market, emphasizing advanced formulations and regulatory compliance, while Asian and Latin American specialists hold positions based on cost-effectiveness and regional distribution. The market exhibits a tiered structure, with a few large multinational corporations dominating, supported by numerous regional players. Strategic archetypes include diversified crop protection giants, off-patent herbicide specialists, and niche formulators. Portfolio diversification and geographic expansion remain dominant competitive moves across the industry.
Within the diversified crop protection giant tier, Syngenta AG and Corteva Agriscience exemplify companies leveraging extensive R&D capabilities to develop specific formulations for major crops. ADAMA Ltd. occupies a position as a specialist in providing off-patent herbicide options, primarily targeting cost-sensitive agricultural markets. These companies utilize their established distribution networks and product portfolios to maintain market presence globally.
| Leading Market Players |
|---|
| ADAMA Ltd. |
| Nufarm Limited |
| Syngenta AG |
| Albaugh LLC |
| AMVAC Chemical Corporation |
| Corteva Agriscience |
| UPL Limited |
| Zhejiang Jinfanda Biochemical |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Specialized chemical manufacturing expertise in Asia, particularly for off-patent herbicide production, creates labor-cost differentials that significantly influence atrazine pricing tiers. These cost advantages allow for broader market access in price-sensitive agricultural economies.
Pricing Analysis
Capacity additions in China are reshaping price floors for technical-grade atrazine, driving cost-competitive options for formulators. The dominant pricing structure is contract-based long-term offtake for large agricultural corporations. Price differentiation stems from formulation complexity and regulatory compliance, with advanced liquid formulations commanding a premium. Pricing pressure intensifies due to the availability of generic alternatives, making crop producers in developing economies highly price-sensitive.
Supply Chain Analysis
Reverse logistics for atrazine primarily involve the regulated collection and disposal of empty containers and unused product, ensuring environmental compliance. Geographic supply concentration centers on manufacturing hubs in China and India for active ingredients, with formulation plants in the United States and Brazil. Raw material dependencies include chlorine, cyanuric acid, and other chemical intermediates. A structural risk is commodity price volatility for key chemical inputs. Distribution runs through a network of agricultural distributors and direct sales to large plantations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atrazine market presents a geographic-arbitrage opportunity, driven by the stark regulatory divergence between the European Union's ban and Brazil's extensive use. This creates distinct product development and market access strategies.
For Market Incumbents: Anticipate stricter application rate limits from regulators like the U.S. EPA by investing in advanced formulation R&D. Defend market share against alternative weed control methods through bio-herbicide blends and enhanced efficacy. Leverage existing distribution networks to counter the threat of new off-patent entrants targeting cost-sensitive segments. Vertical integration into precision application technology offers channel control.
For New Entrants and Emerging Players: Launch via specialized agricultural distributors targeting under-served regions in South America with cost-effective, off-patent solutions. The turf management segment offers a penetrable white-space opportunity for lower-concentration products. Focus on developing formulations that minimize environmental impact to gain regulatory favor and differentiate from established products. Emphasize localized support and technical assistance as a go-to-market angle.
For Investors and Strategic Acquirers: Diversified crop protection giants are the most active acquirers in this space, seeking to expand their herbicide portfolios. The long-term viability of atrazine hinges on continuous innovation in environmental safety and targeted delivery over a 5-10 year window. Target acquisition archetypes include niche formulators with proprietary low-drift technologies or bio-herbicide blend expertise. Regulatory changes from the U.S. EPA or Brazil's ANVISA serve as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Formulation R&D | Develops products meeting evolving environmental safety standards for global markets. |
| Bio-herbicide Blend Development | Addresses weed resistance and improves environmental profiles for sustainable agriculture. |
| Precision Application Technology Integration | Optimizes chemical use and minimizes off-target environmental contamination risks. |
| Geographic Market Diversification | Expands presence in high-growth agricultural economies like Brazil and India. |
| Regulatory Compliance Expertise Investment | Navigates complex and divergent global regulations from agencies like ANVISA and EPA. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to build a comprehensive view of the atrazine market. This involved conversations with agricultural chemical R&D directors, procurement managers at large farming corporations, and regulatory affairs specialists. Secondary validation drew from U.S. EPA documents, ANVISA registrations, and agricultural trade association data. Bottom-up and top-down triangulation ensured data accuracy.
Data stream reconciliation informed the analytical framework, projecting market growth across the analysis window. Segmentation dimensions modeled included product type, application, end-use industry, packaging type, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected demand-supply dynamics. Key forecast inputs included crop acreage trends and evolving environmental safety standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or major environmental incidents. Forecasts reflect assumptions regarding agricultural policy and technological adoption. Practitioners should monitor new scientific studies on environmental impact and evolving international trade agreements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
Global Tetrahydrofuran Market