
 Acetochlor Market | 2026-2036
Acetochlor Market Size, Share, and Industry Trends Forecast 2026-2036
Acetochlor Market Outlook
Corn cultivation is recalibrating acetochlor demand as growers shift toward integrated weed management protocols. Corteva leverages its seed-chemistry bundling strength to anchor herbicide placement across North American row-crop operations. Syngenta competes through formulation innovation in emulsifiable concentrate variants. Shanghai Mingdou Agrochemical Company sustains cost-positioned supply into Asian agricultural markets.
Acetochlor is a chloroacetanilide herbicide applied as a selective pre-emergence treatment, typically formulated as 88% technical concentrate or loaded onto granule carriers for soil incorporation, functioning through inhibition of very-long-chain fatty acid synthesis in germinating weed seedlings. The formulation type dimension shows emulsifiable concentrate formulations dominating commercial volumes while suspended concentrate formats gain traction from reduced solvent exposure and handler safety preferences. Application segmentation centers on corn as the established revenue base, with soybeans representing the faster-expanding outlet as growers rotate crops and seek residual grass control in dicamba-tolerant systems.
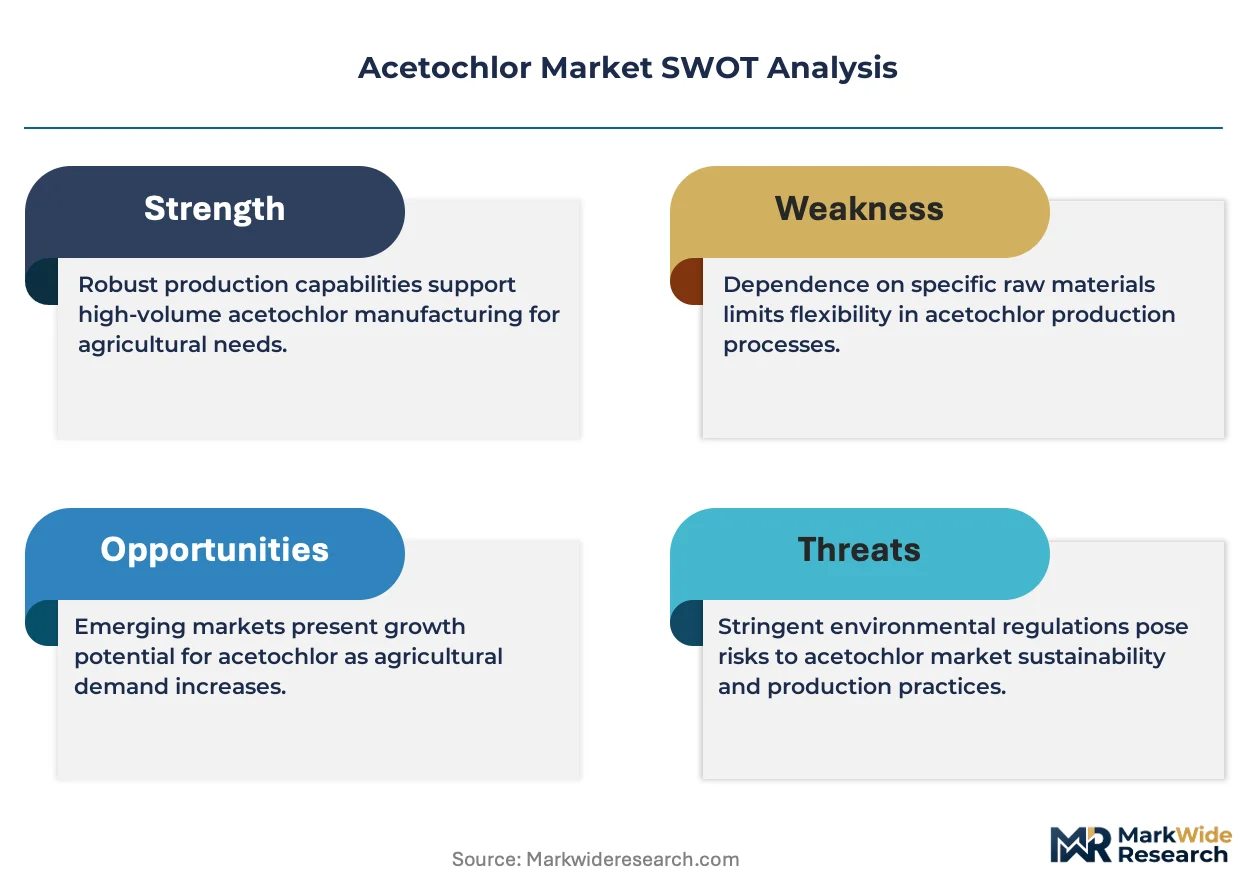
EPA registration requirements under FIFRA mandate chronic toxicity and ecological risk assessments that shape product label restrictions and buffer zone specifications. China's MEE enforces emission controls on chloroacetanilide production facilities through its dual carbon goals framework, elevating compliance costs for Jiangsu Yangnon and domestic manufacturers. EU REACH restrictions on hazardous substance imports limit market access for non-compliant formulations. Stakeholders must monitor regulatory divergence between jurisdictions to optimize registration investments and manufacturing location decisions.
Market Dynamics
EPA's registration review process for chloroacetanilide herbicides is compressing product reformulation timelines while Midwest corn growers recalibrate pre-emergence weed control protocols under integrated management mandates.
Growth Catalysts
- Integrated weed management mandates:Corn growers across Iowa, Illinois, and Nebraska are layering residual herbicides into dicamba-tolerant systems, expanding acetochlor placement in rotation protocols.
- FIFRA registration continuity:EPA's conditional approval frameworks for existing chloroacetanilide registrations preserve market access while manufacturers submit supplemental ecological data.
- Soybean rotation expansion:Row-crop farmers in the Dakotas and Minnesota are adopting acetochlor for residual grass control in soybean acres previously untreated with pre-emergence chemistry.
Market Restraints
- Chloroacetanilide supply concentration:Active ingredient manufacturing clusters in Jiangsu Province face MEE emission enforcement actions that constrain export volumes.
- Glyphosate-tolerant system displacement:Post-emergence glyphosate applications in Roundup Ready corn and soybean systems capture budget share from residual herbicide slots.
- REACH import friction:EU hazardous substance restrictions block non-compliant acetochlor formulations from accessing member state crop protection markets.
Strategic Opportunities
- Granule formulation expansion:Dry-applied carriers for soil incorporation are penetrating Brazilian soybean operations seeking handler safety improvements over liquid concentrates.
- Suspended concentrate adoption:Water-based formulations with reduced solvent exposure are capturing share among US custom applicators and cooperative supply channels.
- Seed-chemistry bundling protocols:Trait-herbicide integration models are opening placement opportunities in Argentine corn production zones.
Industry Challenges
- Ecotoxicology study completion timelines:Chronic toxicity data requirements under EPA registration review are extending label maintenance costs and deferring portfolio refresh cycles.
- Formulation facility reconfiguration:MEE emission control mandates in China are forcing capital redeployment into scrubber systems and solvent recovery infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetochlor Market |
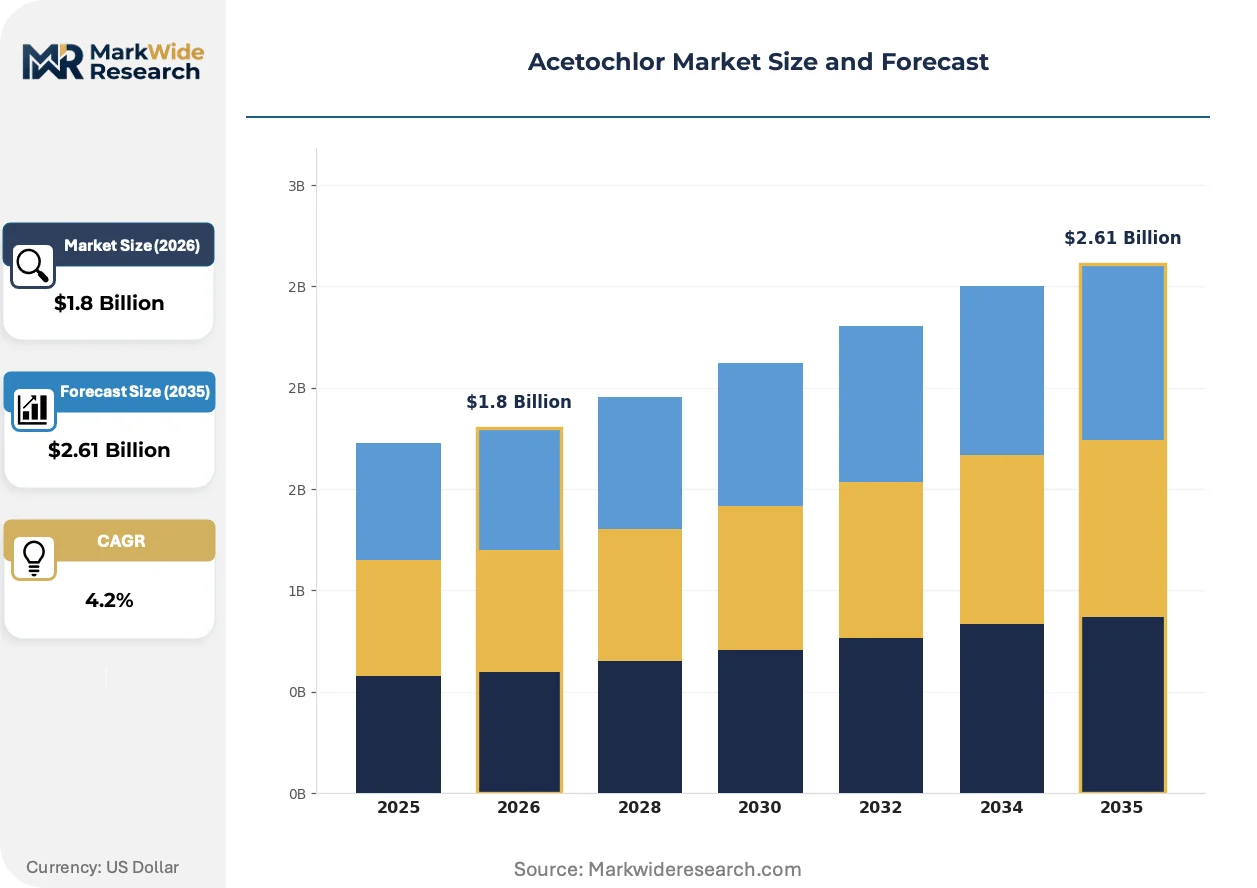
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Corn, Soybeans, Cotton, Rice Formulation Type: Granules, Emulsifiable Concentrate, Suspended Concentrate, Wettable Powder End Use Industry: Agriculture, Horticulture, Landscaping, Turf Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Cooperatives |
| Companies Covered | Corteva, Shanghai Mingdou Agrochemical Company, Monsanto, Nantong Jiangshan Agrochemical & Chemical, SinoHarvest Corporation, Syngenta, Dow AgroSciences, Jiangsu Yangnon, Bayer CropScience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetochlor Market Strategic Shifts
Formulation chemistry and regulatory compliance protocols are the twin axes of competitive differentiation, with water-based delivery systems and emission-controlled manufacturing emerging as decisive capability markers.
Microencapsulated acetochlor delivery systems are rewriting application flexibility standards for pre-emergence herbicides. The technology enables extended release kinetics that align with germination windows across variable soil moisture conditions. Large-scale corn operations in Nebraska and Iowa are adopting these formulations at accelerated rates. This chemistry is compressing the performance gap between standard emulsifiable concentrates and premium controlled-release alternatives.
EPA's ecological risk assessment protocols for non-target plant species are tightening buffer zone specifications and application timing restrictions. The industrial consequence is label contraction for aerial and ground-rig applications near sensitive habitats. Corn Belt custom applicators are responding with precision application technologies and automated boom control systems to maintain compliance coverage.
Cooperative procurement consolidation is compressing distributor margins and shifting volume commitments toward direct manufacturer relationships. Regional agricultural supply cooperatives in Minnesota and the Dakotas are consolidating herbicide purchasing through centralized tender processes. This pattern is most visible in the upper Midwest where farmer-owned supply systems command substantial row-crop input budgets.
Acetochlor Market Segmentation
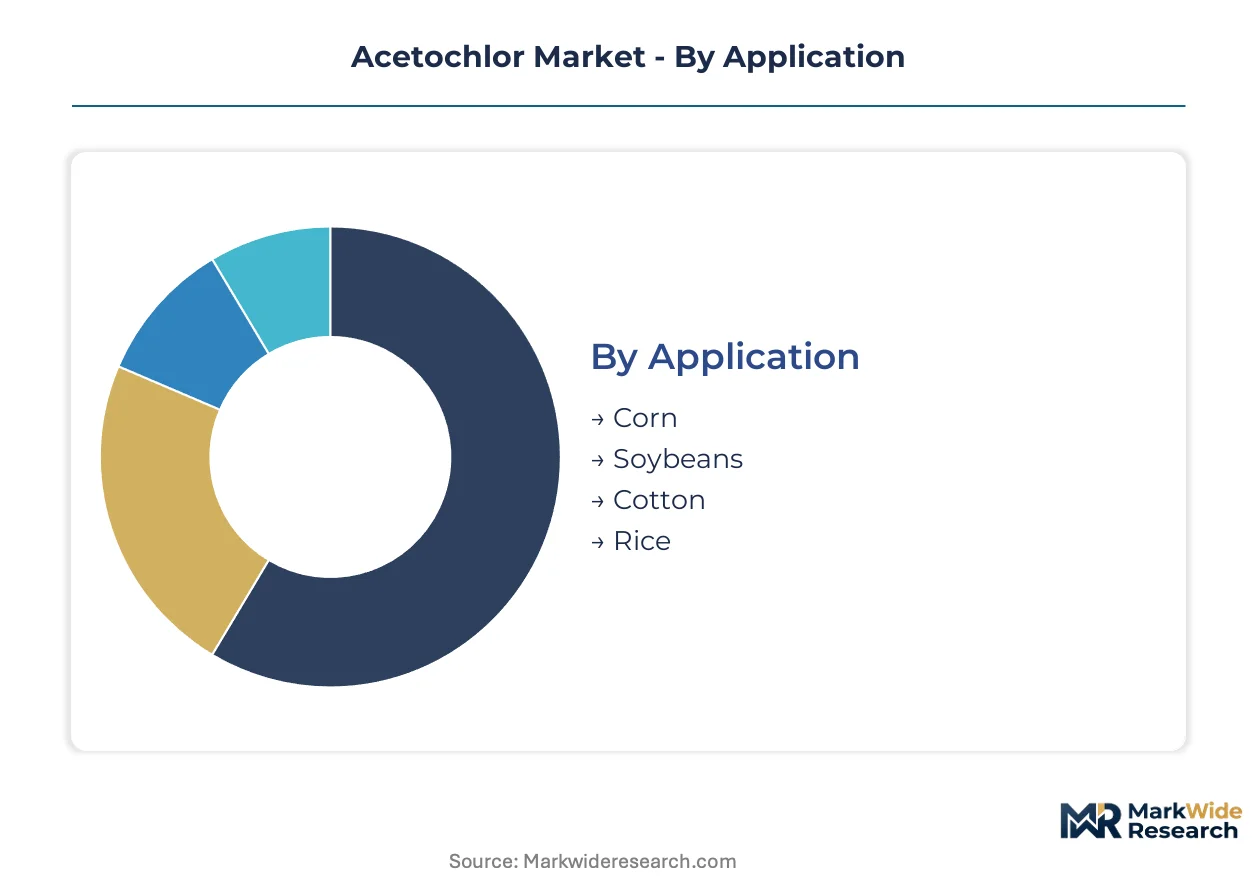
Acetochlor procurement patterns vary sharply across crop systems and application formats, with formulation chemistry and distribution channel structure determining commercial outcomes for manufacturers and growers alike.
Application:
Crop rotation cycles and trait-herbicide compatibility are reshaping which outlets command residual herbicide budgets across North American row-crop operations.
- Corn:Pre-emergence applications in Iowa and Illinois dominate commercial volumes, with dicamba-tolerant trait platforms preserving residual chemistry slots against glyphosate-only programs. EPA buffer zone restrictions near sensitive habitats are compressing aerial application windows in Nebraska.
- Soybeans:Residual grass control in Minnesota and Dakotas rotation systems is climbing fastest as growers layer acetochlor beneath post-emergence dicamba or glufosinate programs. The segment is expanding beyond traditional corn-centric procurement patterns.
- Cotton:Belt-wide adoption concentrates in Texas High Plains pre-plant incorporated applications for early-season weed suppression.
- Rice:Arkansas and Mississippi Delta operations utilize water-seeded and drill-seeded protocols with limited residual herbicide penetration.
Corn sits at the top of the volume ranking, with soybeans climbing the fastest.
Formulation Type:
Handler safety preferences and application equipment compatibility are concentrating demand toward water-based and dry-carrier formats away from solvent-heavy legacy systems.
- Emulsifiable Concentrate:Oil-based formulations with 88% technical loading remain the volume standard across US Midwest custom applicator fleets, though solvent exposure liabilities are eroding share in cooperative supply channels.
- Suspended Concentrate:Water-based delivery systems with reduced handler exposure are gaining fastest among Minnesota and Dakotas agricultural cooperatives seeking regulatory compliance advantages.
- Granules:Dry-applied carriers for soil incorporation penetrate Brazilian soybean operations and US no-till systems requiring reduced drift potential.
- Wettable Powder:Powder formulations for tank-mix compatibility retain niche positioning in specialty crop and horticultural outlets.
Emulsifiable concentrate maintains volume leadership, with suspended concentrate expanding most quickly.
End Use Industry:
Input cost sensitivity and scale economies separate commercial agriculture from specialty outlets with diverging specification requirements.
- Agriculture:Row-crop operations across Corn Belt and Brazilian Cerrado command procurement scale, with pre-emergence protocols anchoring farm input budgets.
- Horticulture:Vegetable and fruit operations in California Central Valley and Florida utilize acetochlor for selective weed control in transplant production systems.
- Landscaping:Commercial grounds maintenance contractors in metropolitan corridors apply granule formulations for ornamental bed weed suppression.
- Turf:Golf course superintendents and sports field managers in Sun Belt states utilize limited volumes for warm-season grass establishment windows.
Agriculture dominates absolute volume, with horticulture showing the steepest expansion trajectory among non-row-crop outlets.
Distribution Channel:
Procurement consolidation and digital platform penetration are restructuring how growers access residual herbicide chemistry across price-sensitive and service-oriented segments.
- Distributors:Independent agricultural retailers across Iowa, Illinois, and Nebraska maintain formulation blending capabilities and application advisory services.
- Agricultural Cooperatives:Farmer-owned supply systems in Minnesota and Dakotas are consolidating tender processes and compressing manufacturer margins through centralized purchasing.
- Direct Sales:Large-scale operations in Brazil and Argentina receive bulk shipments bypassing retail markup structures.
- Online Retail:E-commerce platforms penetrate small-acreage growers and horticultural operators with limited distributor proximity.
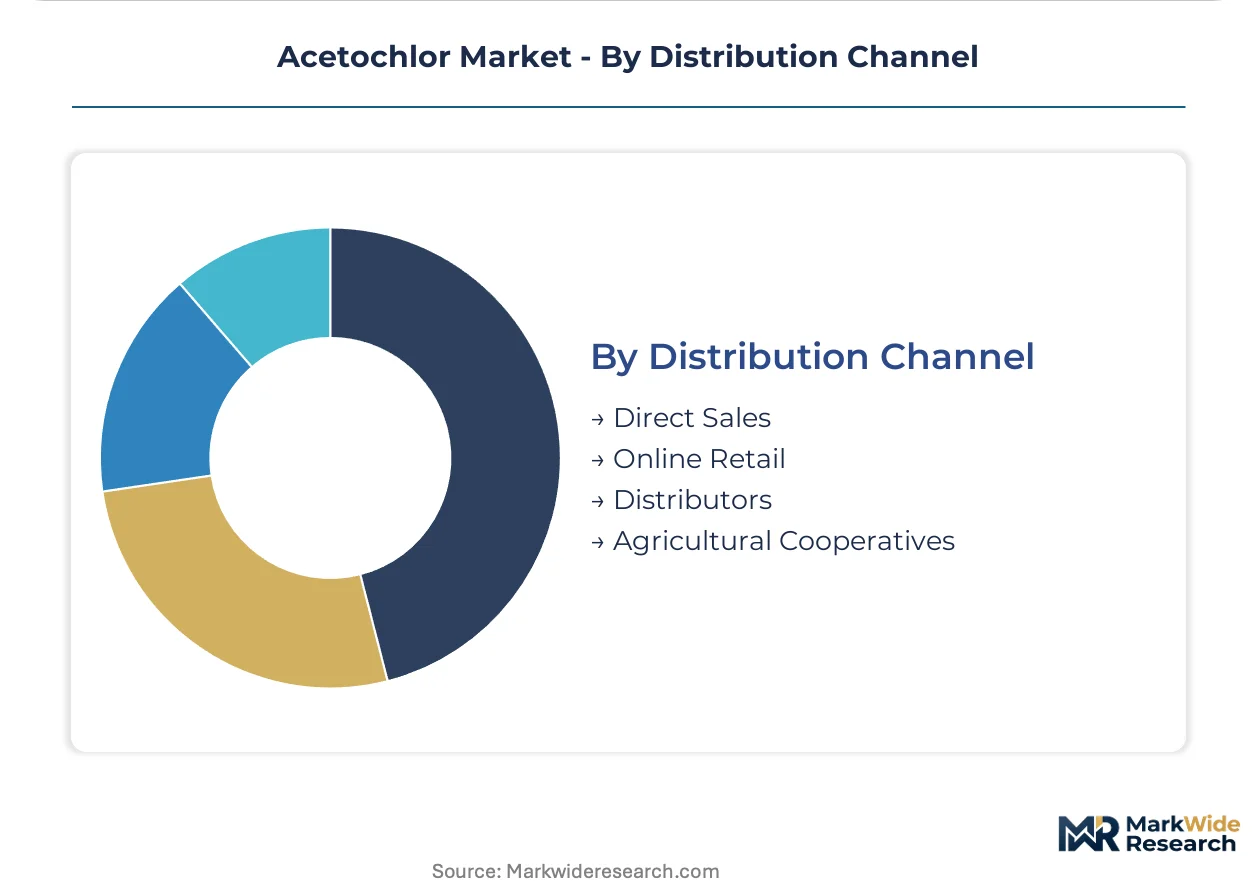
Distributors hold volume primacy, with agricultural cooperatives gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Corn Belt anchors acetochlor demand through pre-emergence weed control protocols across Iowa, Illinois, and Nebraska. EPA registration reviews under FIFRA compress reformulation timelines for chloroacetanilide manufacturers. Regional procurement patterns concentrate in farmer-owned cooperatives and custom applicator networks.
United States
Midwest corn operations in Iowa and Illinois drive residual herbicide volumes through dicamba-tolerant trait systems. EPA buffer zone restrictions near sensitive habitats compress aerial application windows in Nebraska. Formulation blending facilities cluster in St. Louis and Des Moines supply corridors.
Brazil
Cerrado soybean expansion creates demand for dry-applied granule carriers in no-till systems. ANVISA pesticide registration protocols govern import approval timelines for chloroacetanilide formulations. Manufacturing distribution concentrates in São Paulo state chemical processing zones.
China
Jiangsu Province active ingredient production supplies export markets under MEE emission control enforcement. Dual carbon goals framework elevates compliance costs for chloroacetanilide synthesis facilities. Yangzhou and Nantong chemical industrial parks face scrubber system retrofit mandates.
Argentina
Cordoba and Buenos Aires corn zones adopt seed-chemistry bundling models for pre-emergence protocols. National agricultural technology institute registration requirements shape product entry timelines. Rosario port logistics corridors handle bulk herbicide import volumes.
Canada
Prairie Province canola and corn rotations utilize acetochlor for residual grass control in Manitoba. Health Canada PMRA re-evaluation schedules align with EPA chronic toxicity data requirements. Saskatoon and Red Deer distribution hubs serve prairie farm input supply chains.
Acetochlor Market Competitive Environment
Formulation innovation dominates the current landscape as manufacturers differentiate through delivery system chemistry. The vendor base concentrates around integrated agrochemical conglomerates and specialized chloroacetanilide producers. Three strategic archetypes prevail: trait-chemistry bundlers, cost-positioned Asian manufacturers, and formulation technology specialists. Portfolio diversification into water-based suspended concentrates and geographic expansion into South American soybean zones represent the dominant competitive vectors.
Among North American trait-chemistry integrators, Corteva occupies a position exemplifying seed-herbicide bundling strength across Corn Belt operations. Shanghai Mingdou Agrochemical Company and Jiangsu Yangnon represent the cost-positioned manufacturing tier supplying Asian export markets. Syngenta sits within the formulation innovation archetype, anchoring emulsifiable concentrate and microencapsulated delivery system development.
| Leading Market Players |
|---|
| Corteva |
| Shanghai Mingdou Agrochemical Company |
| Monsanto |
| Nantong Jiangshan Agrochemical & Chemical |
| SinoHarvest Corporation |
| Syngenta |
| Dow AgroSciences |
| Jiangsu Yangnon |
| Bayer CropScience |
| Others |
Value Chain & Pricing Dynamics
China's MEE dual carbon goals framework gates qualified supply for chloroacetanilide manufacturers while simultaneously filtering premium-tier pricing access to buyers with certified emission-compliant sourcing protocols.
Pricing Analysis
Distributor margins compress as agricultural cooperatives in Minnesota and the Dakotas consolidate tender processes and negotiate direct manufacturer relationships. Three-tier pricing structure across premium microencapsulated, standard emulsifiable concentrate, and economy technical-grade levels reflects formulation sophistication and handler safety profiles. Price differentiation hinges on EPA registration status and buffer zone compliance certification. Cost compression in economy technical-grade tiers intensifies because Jiangsu Province emission enforcement actions constrain export volumes from cost-positioned suppliers.
Supply Chain Analysis
Dual-sourcing requirements from US and Brazilian formulators mandate multi-supplier qualification across Jiangsu Province active ingredient producers and Indian chloroacetanilide synthesis facilities. Manufacturing gravity centers on Yangzhou and Nantong chemical industrial parks in China, with secondary capacity anchored in Gujarat and Maharashtra states. Feedstock dependencies encompass chloroacetyl chloride, 2-ethyl-6-methylaniline, and specialized solvent carriers. Tariff exposure on Chinese-origin technical concentrate shipments threatens margin structures for North American blenders. Distribution runs through St. Louis and Des Moines formulation corridors for US Midwest custom applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where emission compliance costs in China's Jiangsu Province create manufacturing displacement opportunities for Indian and North American producers serving EPA-registered demand pools.
For Market Incumbents: Anchor seed-chemistry bundling strength across dicamba-tolerant trait platforms in Iowa and Illinois corn zones to defend against glyphosate-only program displacement. Pursue backward integration into microencapsulated formulation technology to capture premium-tier pricing. Deepen cooperative supply channel control through centralized tender participation in Minnesota and Dakotas procurement consolidation. For New Entrants and Emerging Players: Launch via direct-to-grower digital platforms targeting small-acreage horticultural operators in California Central Valley with wettable powder formats bypassing distributor markup structures. Penetrate Brazilian Cerrado soybean operations through ANVISA-registered granule formulations for no-till handler safety protocols. Exploit white-space in suspended concentrate water-based delivery systems for US custom applicator compliance preferences. For Investors and Strategic Acquirers: Valuations sit cheapest among cost-positioned Asian technical-grade manufacturers facing MEE emission retrofit mandates and constrained export eligibility. Long-term viability frames around EPA registration continuity and FIFRA chronic toxicity data completion timelines. Target acquisition archetype: formulation technology specialists with microencapsulated delivery system IP and South American regulatory approvals. Monitor EPA ecological risk assessment buffer zone specification tightening as inflection signal for precision application technology demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captures margin from Jiangsu Province emission-constrained suppliers while securing EPA registration data continuity. |
| Microencapsulated Formulation Launch | Aligns release kinetics with variable soil moisture across Nebraska and Iowa corn germination windows. |
| ANVISA Registration Pathway Expansion | Unlocks Brazilian Cerrado soybean demand through granule carrier handler safety positioning. |
| Agricultural Cooperative Tender Consolidation | Compresses distributor margins while anchoring volume commitments in Minnesota and Dakotas procurement. |
| MEE Emission Compliance Certification | Preserves Chinese manufacturing access for Yangzhou and Nantong facilities under dual carbon goals enforcement. |
Study Parameters
Direct dialogue with chloroacetanilide plant managers, agricultural cooperative procurement leads, EPA regulatory affairs specialists, and Brazilian ANVISA registration consultants grounded qualitative insights. Secondary validation drew from EPA FIFRA registration databases, USITC customs trade records, China MEE emission disclosure filings, and ANVISA pesticide approval timelines. Bottom-up acreage-by-acreage herbicide application modeling triangulated against top-down agrochemical manufacturer revenue segmentation.
Bottom-up volume construction aggregated corn, soybean, cotton, and rice acreage across Iowa, Illinois, Nebraska, Minnesota, and Brazil's Mato Grosso state with pre-emergence protocol penetration rates. Top-down demand calibration referenced chloroacetanilide technical concentrate trade flows and formulation facility capacity utilization. Segmentation dimensions spanned crop system, formulation chemistry, and distribution channel structure. CAGRs derived from acreage expansion trajectories, trait-herbicide compatibility shifts, and regulatory approval continuity assumptions across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA registration review acceleration or MEE emission enforcement intensification. Deviation in FIFRA chronic toxicity data completion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Putty Powder Market