
 Anaerobic Adhesives and Sealants Market | 2026-2036
Anaerobic Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Anaerobic Adhesives and Sealants Market Outlook
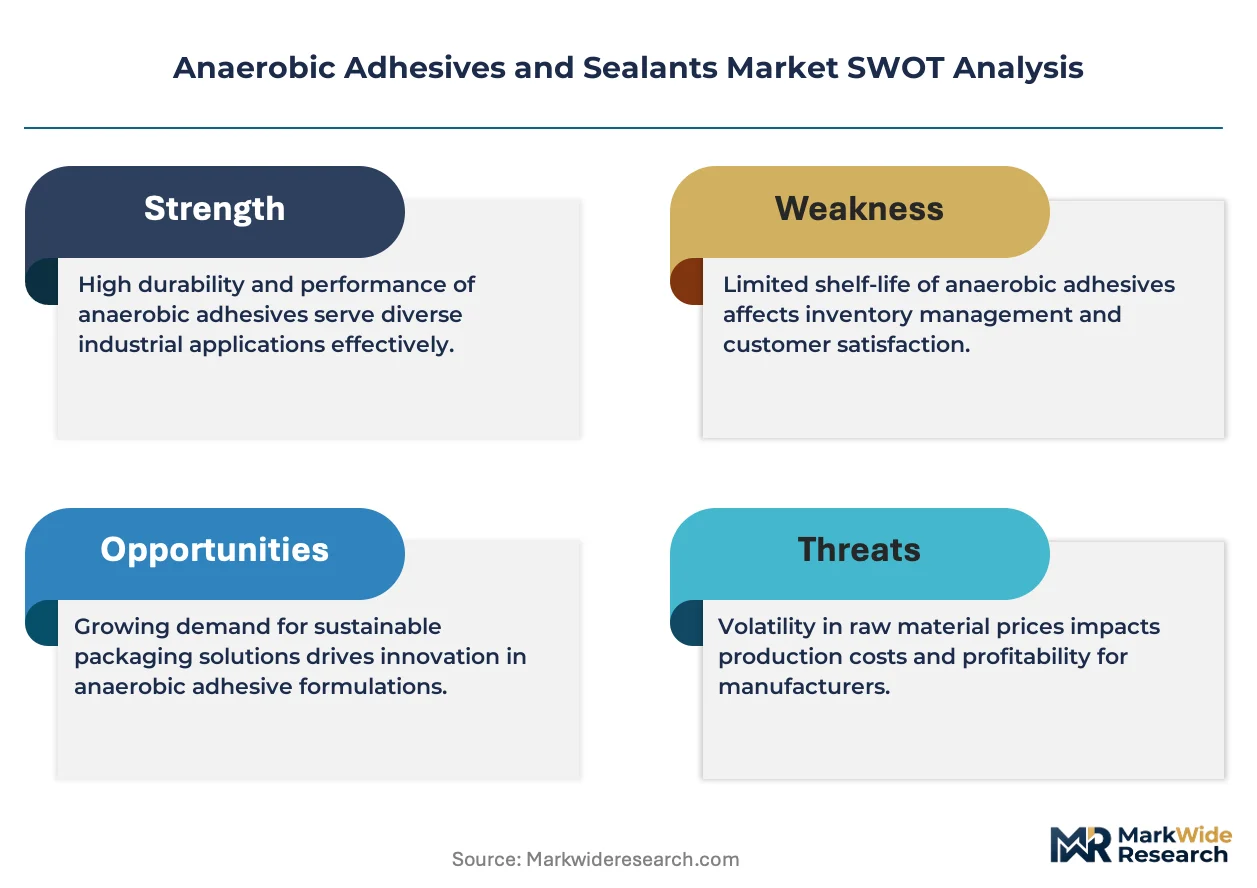
The gap between premium-grade threadlockers and commodity anaerobic sealants is broadening as OEM specifications diverge by load-bearing requirement and chemical resistance. Henkel AG & Co. KGaA leverages its Loctite brand heritage to dominate aerospace-grade formulations with exacting outgassing standards. H.B. Fuller Company anchors its position through captive resin synthesis and direct technical service to tier-one automotive suppliers. ThreeBond Holdings Co., Ltd. specializes in low-odor, low-halogen variants tailored for Japanese electronics assembly lines.
Anaerobic adhesives and sealants cure in the absence of oxygen between closely mated metal surfaces through redox-initiated polymerization of dimethacrylate monomers, typically achieving handling strength within minutes and full cure within 24 hours at room temperature. Their primary industrial purpose is to lock threaded fasteners, seal flanges, and retain cylindrical assemblies against vibration loosening and fluid leakage. Threadlocker formulations command the deepest margin pools in maintenance-repair-overhaul channels, while structural adhesive grades are displacing mechanical fasteners in powertrain lightweighting programs. Single-component technology leads volume shipments due to dispensing simplicity, though UV-curable hybrids are capturing share in visible-bondline electronics applications where rapid fixturing accelerates line throughput.
REACH registration requirements and the EU F-Gas Regulation constrain formulation choices for European suppliers, while OSHA permissible exposure limits and EPA VOC rules govern workplace and environmental compliance in United States manufacturing plants. FDA indirect food-contact approvals additionally shape product development for packaging machinery OEMs serving regulated consumer goods sectors. Stakeholders must monitor evolving substance restrictions under the EU Green Deal and assess backward integration into specialty monomer supply as feedstock availability tightens.
Market Dynamics
Electric powertrain architectures are redefining fastening specifications across automotive assembly, with vibration resistance thresholds tightening for battery tray mounts and inverter housings. OEMs now specify anaerobic threadlockers for torque retention in aluminum-intensive designs where thermal cycling exceeds traditional mechanical fastener limits.
Growth Catalysts
- REACH Substance Restrictions:European ECHA registration deadlines are accelerating reformulation investments toward bio-based monomer alternatives, opening premium positioning for compliant suppliers.
- Wind Turbine Assembly:Gearbox manufacturers specify high-retaining compounds for main bearing seats and pitch system fasteners exposed to cyclic loading.
- Medical Device Miniaturization:Precision instrument OEMs specify low-outgassing anaerobic grades for implantable device housings and surgical tool assemblies.
Market Restraints
- Methacrylic Acid Volatility:Feedstock price swings for dimethacrylate monomers compress formulation margins and destabilize contract pricing.
- German Resin Concentration:Captive monomer synthesis capacity clusters along the Rhine corridor, creating single-source exposure for non-integrated compounders.
- UV-Curable Substitution:Acrylic adhesives with photoinitiator packages displace anaerobics in visible-bondline electronics where oxygen inhibition is unavoidable.
Strategic Opportunities
- India Industrial Corridor:PLI scheme incentives for precision manufacturing are drawing adhesive distributors to Pune and Chennai clusters.
- Hydrogen Infrastructure:Fuel cell stack assembly requires thread-sealing compounds compatible with hydrogen permeation and pressure cycling.
- EU Green Deal Procurement:Public tender rules now weight embodied carbon in maintenance chemical selections, favoring regional producers with verified supply chains.
Industry Challenges
- Formulation Chemist Scarcity:Redox polymerization expertise concentrates among aging specialists, constraining R&D throughput for mid-tier compounders.
- FDA Indirect Food Contact Timelines:Packaging machinery OEMs face 18-24 month approval cycles for conveyor system adhesives, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaerobic Adhesives and Sealants Market |
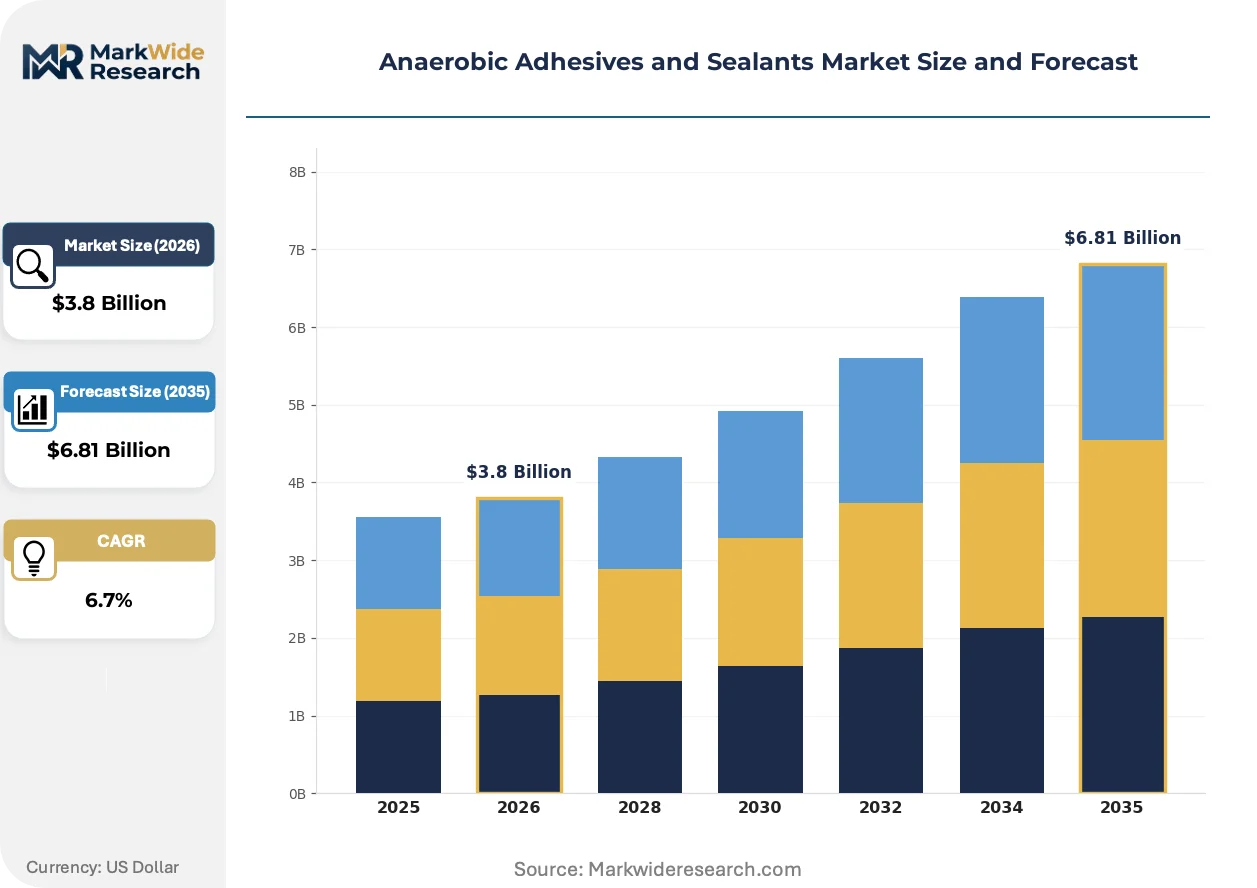
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Threadlocker, Gasket Maker, Structural Adhesive, Sealant End User: Aerospace, Automotive, Electronics, Construction Application: Bonding, Sealing, Coating, Repairing Technology: Single Component, Two Component, UV-Curable, Others |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Permabond LLC, ITW LLC & Co. KG, ThreeBond Holdings Co., Ltd., WEICON GmbH & Co. KG, Parson Adhesives, Inc., Loxeal S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaerobic Adhesives and Sealants Market Strategic Shifts
Hybrid curing chemistries are bridging the gap between anaerobic reliability and electronics manufacturing speed requirements. Formulators now balance oxygen exclusion with secondary activation mechanisms to serve divergent assembly line constraints.
Dual-cure anaerobic-UV systems are expanding into camera module bonding for smartphones and automotive LiDAR housings. Tier-one electronics contract manufacturers in South Korea and Taiwan specify these grades for immediate handling strength under UV exposure followed by full anaerobic cure in shadowed regions. The technology is expanding into flip-chip underfill applications where capillary flow must coexist with rapid fixturing.
EPA VOC content rules under 40 CFR 59 are forcing architectural and industrial maintenance formulators toward exempt solvent systems. Compliance deadlines in 2025-2027 are compressing product development cycles for US suppliers serving machinery rebuild channels. California CARB standards extend these constraints to consumer-grade threadlocker retail formulations.
Maintenance procurement teams now specify certified cure-time performance rather than generic strength grades. Airlines and heavy equipment fleets in Germany and Japan require lot-traceable anaerobic compounds with documented fixture and full-strength intervals. This behavior concentrates purchasing power among distributors offering technical data packages and application engineering support.
Anaerobic Adhesives and Sealants Market Segmentation
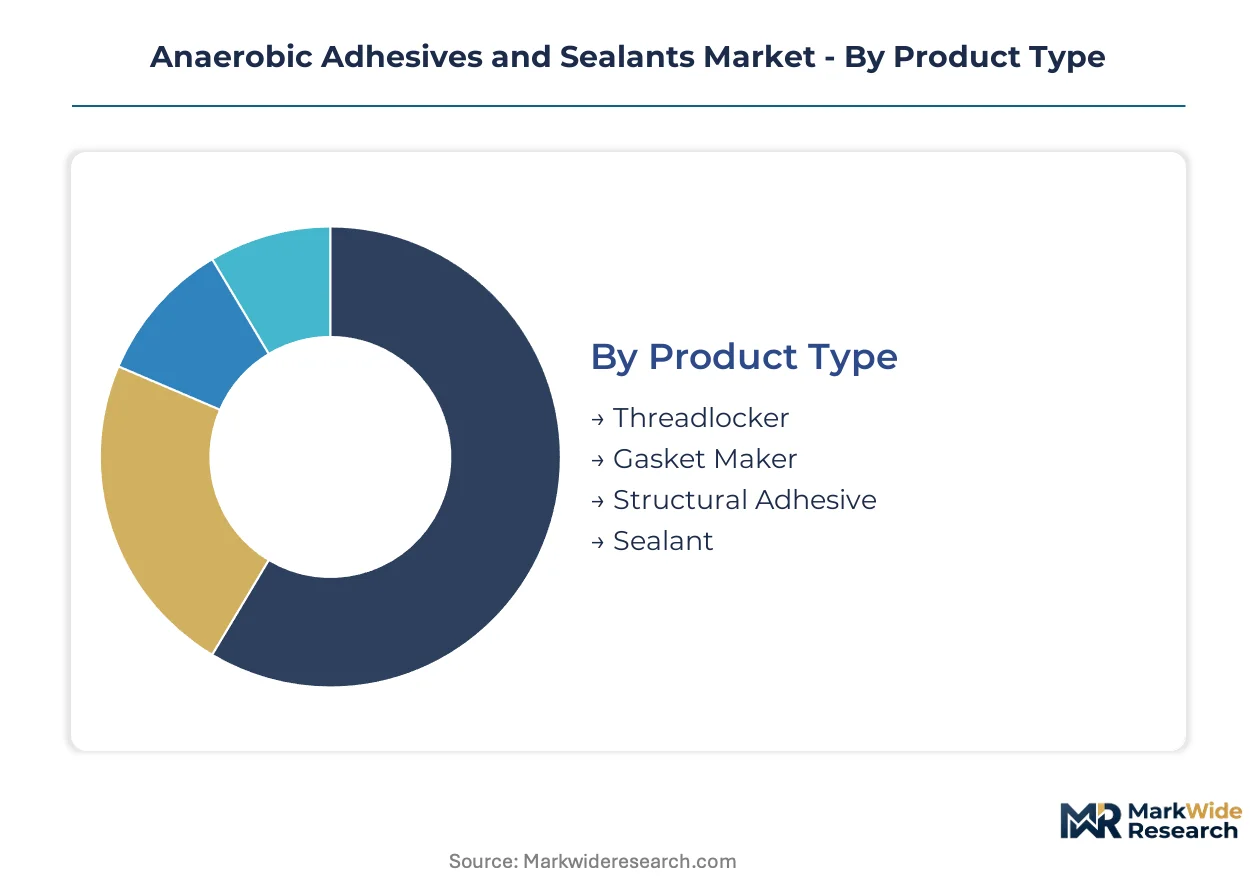
Anaerobic adhesive specifications diverge sharply by functional load and curing chemistry. Threadlockers dominate maintenance procurement, while structural grades penetrate powertrain lightweighting programs.
Product Type:
Formulation chemistry dictates performance thresholds across fastening, sealing, and load-bearing applications.
- Threadlocker:Dimethacrylate-based formulations cure in the absence of oxygen between threaded metal interfaces. Automotive OEMs in Germany specify high-strength grades for aluminum powertrain fasteners subject to thermal cycling.
- Structural Adhesive:Toughened methacrylate systems achieve lap shear strengths exceeding 20 MPa for cylindrical retention and structural bonding. Electric vehicle battery tray manufacturers specify these grades to replace mechanical welds in aluminum-intensive architectures.
- Gasket Maker:Viscous anaerobic pastes conform to flange surface irregularities for fluid sealing. Demand concentrates in gearbox and hydraulic system rebuild channels.
- Sealant:Lower-viscosity formulations penetrate close-tolerance joints for porosity sealing. Precision instrument OEMs specify low-outgassing variants for vacuum and cleanroom environments.
Mature deployment sits with Threadlocker. Newer deployment is concentrated in Structural Adhesive.
End User:
Customer specifications diverge by regulatory burden, vibration tolerance, and thermal exposure profiles.
- Automotive:Electric powertrain architectures demand threadlockers with extended temperature ratings for inverter housings and battery mounts. OEM torque retention specifications now exceed traditional mechanical fastener limits.
- Aerospace:Outgassing standards per ASTM E595 constrain formulation choices for satellite and aircraft assemblies. Maintenance-repair-overhaul channels specify lot-traceable compounds with documented cure intervals.
- Electronics:Camera module and LiDAR manufacturers drive dual-cure anaerobic-UV adoption for immediate handling strength.
- Construction:Heavy equipment fleet maintenance specifies high-viscosity retaining compounds for bearing seats and pivot pins exposed to shock loading.
Volume leadership belongs to Automotive. Steepest expansion trajectory is in Electronics.
Application:
Functional purpose determines viscosity, cure speed, and strength grade selection.
- Bonding:Structural grades achieve permanent assembly of dissimilar metals in powertrain and chassis applications. Manufacturers specify toughened formulations for peel resistance.
- Sealing:Thread sealants and flange sealers prevent fluid leakage under pressure and thermal cycling. Hydrogen infrastructure projects specify compounds compatible with permeation and pressure cycling.
- Coating:Thin-film anaerobics protect threaded components from corrosion and galling during storage and assembly.
- Repairing:Wicking-grade threadlockers penetrate pre-assembled fasteners for post-installation locking in maintenance operations.
Established practice centers on Bonding. Emerging specification growth is in Sealing.
Technology:
Cure mechanism selection balances oxygen exclusion requirements with line speed constraints.
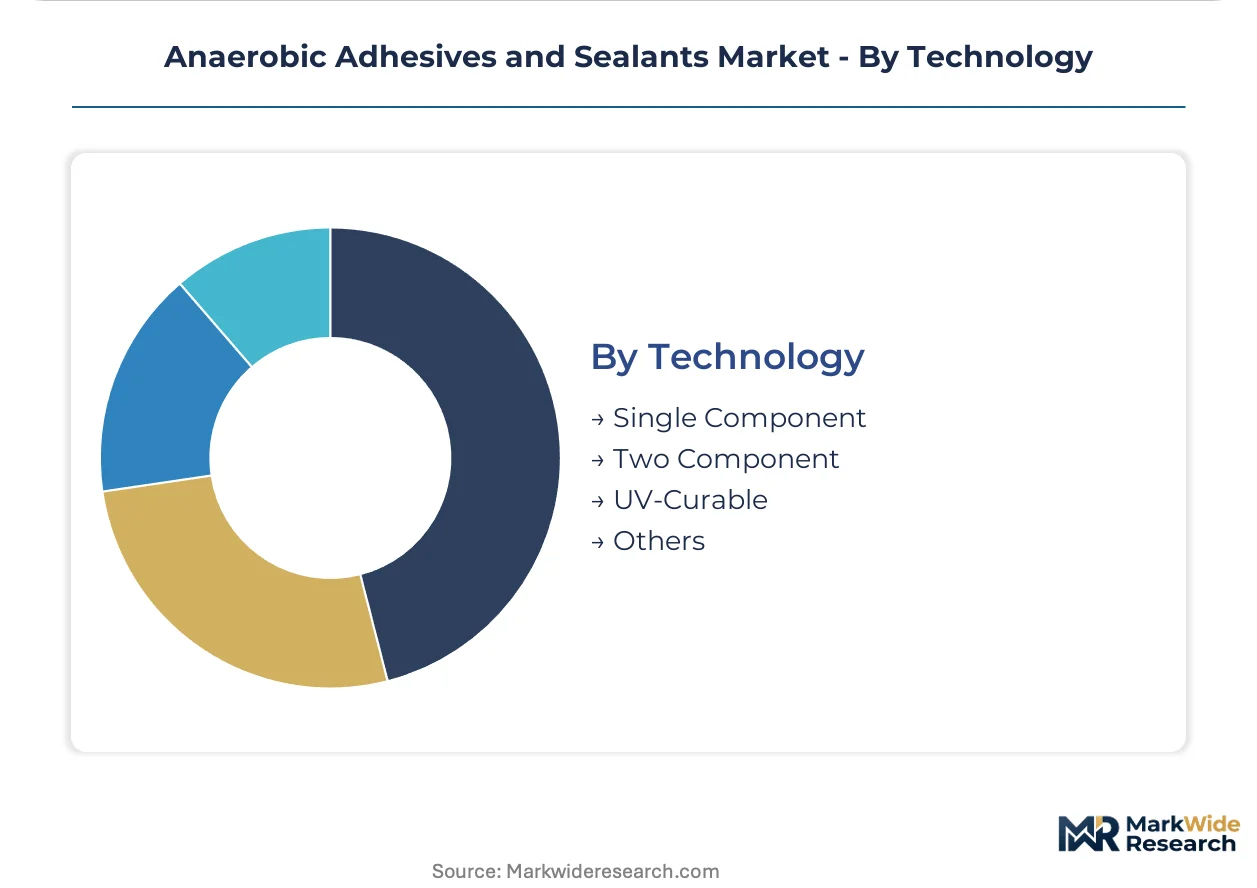
- Single Component:One-part systems dominate volume shipments due to dispensing simplicity and indefinite shelf stability. Automotive assembly lines specify these for high-throughput fastening stations.
- UV-Curable:Photoinitiator-accelerated systems achieve fixture in seconds for visible-bondline electronics. South Korean contract manufacturers specify hybrid anaerobic-UV grades for smartphone camera modules.
- Two Component:Accelerator-activated systems cure through larger gaps where oxygen exclusion is incomplete. Wind turbine gearbox manufacturers specify these for main bearing seats.
- Others:Heat-accelerated and primer-activated variants serve specialty applications with extended cure windows or inactive substrates.
Installed base concentration is in Single Component. Technology transition is accelerating in UV-Curable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor along the Rhine dominates precision engineering demand for anaerobic fastening systems. Automotive OEMs in Stuttgart and Munich specify high-strength threadlockers for aluminum powertrain assemblies. REACH compliance deadlines are accelerating reformulation investments toward bio-based monomer alternatives.
United States
Electric vehicle manufacturers in Michigan and California drive threadlocker procurement for battery tray mounts and inverter housings. EPA VOC rules under 40 CFR 59 compress product development cycles for machinery rebuild suppliers. Detroit's automotive cluster now specifies anaerobic compounds with extended temperature ratings for thermal cycling applications.
Japan
Electronics contract manufacturers in Osaka and Nagoya specify dual-cure anaerobic-UV systems for smartphone camera modules. METI industrial standards constrain halogen content in precision instrument assemblies. The Kansai region's medical device OEMs demand low-outgassing grades for surgical tool miniaturization.
China
Wind turbine gearbox producers in Jiangsu and Zhejiang specify high-retaining compounds for main bearing seats exposed to cyclic loading. MIIT equipment manufacturing directives favor domestic adhesive suppliers for critical infrastructure. The Yangtze River Delta cluster concentrates precision machinery maintenance procurement.
South Korea
LiDAR housing manufacturers in Suwon and Pyeongtaek drive hybrid curing chemistry adoption for immediate handling strength. MFDS medical device regulations shape low-outgassing formulation requirements for implantable equipment. The Seoul Capital Area's electronics foundries specify lot-traceable compounds with documented cure intervals.
Anaerobic Adhesives and Sealants Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and technical service intensity. The vendor base stratifies between integrated resin producers and formulation compounders dependent on merchant monomer supply. Two strategic archetypes dominate: aerospace-grade specialists with exacting outgassing credentials, and automotive-anchored suppliers with captive technical service teams. Competitive moves concentrate on backward integration into specialty monomer synthesis and direct distributor acquisition in precision manufacturing clusters.
Within the integrated-formulator tier, Henkel AG & Co. KGaA and H.B. Fuller Company occupy positions defined by brand heritage and captive resin synthesis respectively. ThreeBond Holdings Co., Ltd. exemplifies the regional-specialist archetype, anchoring low-odor, low-halogen supply relationships with Japanese electronics assemblers. These three entities represent distinct competitive vectors: heritage-brand premium positioning, upstream supply control, and geography-bound specialization.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Permabond LLC |
| ITW LLC & Co. KG |
| ThreeBond Holdings Co., Ltd. |
| WEICON GmbH & Co. KG |
| Parson Adhesives, Inc. |
| Loxeal S.r.l. |
| Others |
Value Chain & Pricing Dynamics
Redox polymerization chemist scarcity along Germany's Rhine corridor widens labor-cost differentials between premium-grade formulators and commodity compounders. Pricing tiers separate aerospace-certified suppliers from maintenance-grade distributors based on formulation expertise concentration and regulatory compliance depth.
Pricing Analysis
Value-based pricing anchors on torque retention performance and documented cure intervals rather than per-unit resin costs. Three-tier pricing structure across aerospace-certified, automotive-specified, and maintenance-grade levels reflects ECHA registration status and outgassing certification tiers. Cost compression in commodity threadlockers intensifies as merchant monomer supply tightens and REACH reformulation investments concentrate among integrated producers. Maintenance distributors exhibit highest price sensitivity due to spot-buying patterns, while aerospace OEMs prioritize lot traceability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one automotive and electronics contract manufacturer demand, while authorized distributors serve maintenance-repair-overhaul procurement. Captive dimethacrylate synthesis capacity clusters in Germany, Japan, and the United States, with merchant monomer supply drawing from Chinese and South Korean petrochemical feedstocks. Formulation margins hinge on specialty monomer availability and REACH-registered bio-based alternative development. Single-source exposure runs through Rhine corridor resin producers for non-integrated compounders lacking backward integration into redox polymerization chemistry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH registration deadlines and captive monomer synthesis requirements force weaker compounders toward exit or acquisition.
For Market Incumbents: Deepen backward integration into specialty dimethacrylate production to secure feedstock access as merchant supply tightens. Expand direct technical service teams in Stuttgart and Munich automotive clusters to defend against emerging Asian suppliers with cost-advantaged formulations. Prioritize ECHA bio-based monomer registration to capture premium positioning as substance restrictions accelerate. For New Entrants and Emerging Players: Launch via specialized electronics distributors in South Korea and Taiwan where dual-cure anaerobic-UV demand outpaces established supply. Target hydrogen infrastructure sealing applications as fuel cell stack assembly specifications crystallize around permeation-resistant compounds. Enter through low-outgassing certification investment for medical device OEMs facing extended FDA approval timelines. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier compounders possessing REACH-registered portfolios and regional distributor relationships given consolidation pressure from integrated resin producers. Long-term viability favors suppliers with demonstrated cure-time documentation and lot-traceable quality systems serving aerospace and medical device verticals. Monitor ECHA substance restriction announcements as inflection indicators for reformulation investment cycles and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomer Synthesis | Captive dimethacrylate production secures margin control as Rhine corridor supply tightens under REACH pressure. |
| Dual-Cure Anaerobic-UV Product Launch | Hybrid curing chemistry captures smartphone camera module and automotive LiDAR assembly specifications from South Korean contract manufacturers. |
| Long-Term Supply Agreement with Wind Turbine OEMs | Gearbox retaining compound contracts with Jiangsu and Zhejiang producers anchor volume through cyclic loading application expertise. |
| Green Manufacturing Transition | Bio-based monomer alternatives align with EU Green Deal procurement weighting for verified supply chain carbon accounting. |
| Joint Venture with Regional Distributor | Direct channel control in Pune and Chennai precision manufacturing clusters leverages PLI scheme incentives for industrial chemical localization. |
Study Parameters
Independent corroboration across formulation chemist interviews, automotive procurement lead discussions, and electronics contract manufacturer technical director consultations underwrites the qualitative findings. Primary fieldwork engaged plant managers at anaerobic adhesive production facilities, distribution channel partners serving maintenance-repair-overhaul networks, and technical R&D directors at integrated resin producers. Secondary validation drew from ECHA substance registration databases, SEC 10-K filings of listed chemical companies, customs and trade flow data for dimethacrylate monomer imports, and ACC sector reports on industrial adhesive demand. Bottom-up volume modeling across threadlocker, structural adhesive, gasket maker, and sealant grades triangulated against top-down market sizing from end-use industry consumption patterns.
Rate-of-change decomposition segmented growth contributions by product type chemistry, end-use industry regulatory burden, application functional purpose, and cure mechanism technology across the analysis window. CAGRs derived from segment-level volume trajectories adjusted for substitution effects from UV-curable acrylics and thermal cycling performance requirements in aluminum-intensive automotive designs. Forecast inputs incorporated electric powertrain architecture penetration rates, wind turbine installation schedules, and hydrogen infrastructure deployment timelines without specifying annual milestones.
Feedstock price volatility for methacrylic acid derivatives, ECHA substance restriction scope expansion, and UV-curable substitution acceleration in visible-bondline electronics are the dominant revision risks. Forecasts reflect base-case assumptions regarding REACH registration compliance timelines and monomer supply chain stability. Periodic stress-testing of base assumptions against regulatory announcement calendars and raw material futures market movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Die Cut Adhesive Market