
 Cyclamate Market | 2026-2036
Cyclamate Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclamate Market Analysis
The capital-intensity divergence between integrated manufacturers and commodity traders is rotating competitive advantage toward firms with captive raw material supply. Foodchem International Corporation leverages backward integration into cyclohexylamine feedstock to sustain margin stability across pricing cycles. PT Batang Alum Industrie anchors its position through dedicated sodium cyclamate capacity serving Indonesian domestic demand. Golden Time Chemical competes on scale economics at its Shandong production complex.
Cyclamate denotes a family of artificial sweeteners derived from cyclamic acid, with sodium cyclamate (C6H11NHSO3Na) representing the most commercially prevalent form at approximately 30 times the sweetness intensity of sucrose; manufacturers synthesize the compound through sulfonation of cyclohexylamine followed by neutralization with sodium hydroxide, primarily for calorie reduction in processed foods and beverages. Sodium cyclamate dominates product-type revenue owing to its solubility profile and established food-grade certification pathways, while calcium cyclamate occupies niche pharmaceutical applications where sodium content must be restricted. Food and beverage applications generate the largest volume pull, though personal care formulations represent a faster-growing margin pool as cosmetic brands seek sugar-free positioning claims.
FDA maintains its ban on cyclamate under the Delaney Clause, while EFSA and Health Canada permit specified usage levels, creating a bifurcated regulatory landscape that segments market access by geography. China's SAMR enforces GB standards for cyclamate purity and maximum permitted levels in food categories, with MEE oversight extending to manufacturing effluent controls. Stakeholders must monitor pending regulatory reviews in Brazil and Mexico where ANVISA and national health agencies are reassessing sweetener safety databases.
Market Dynamics
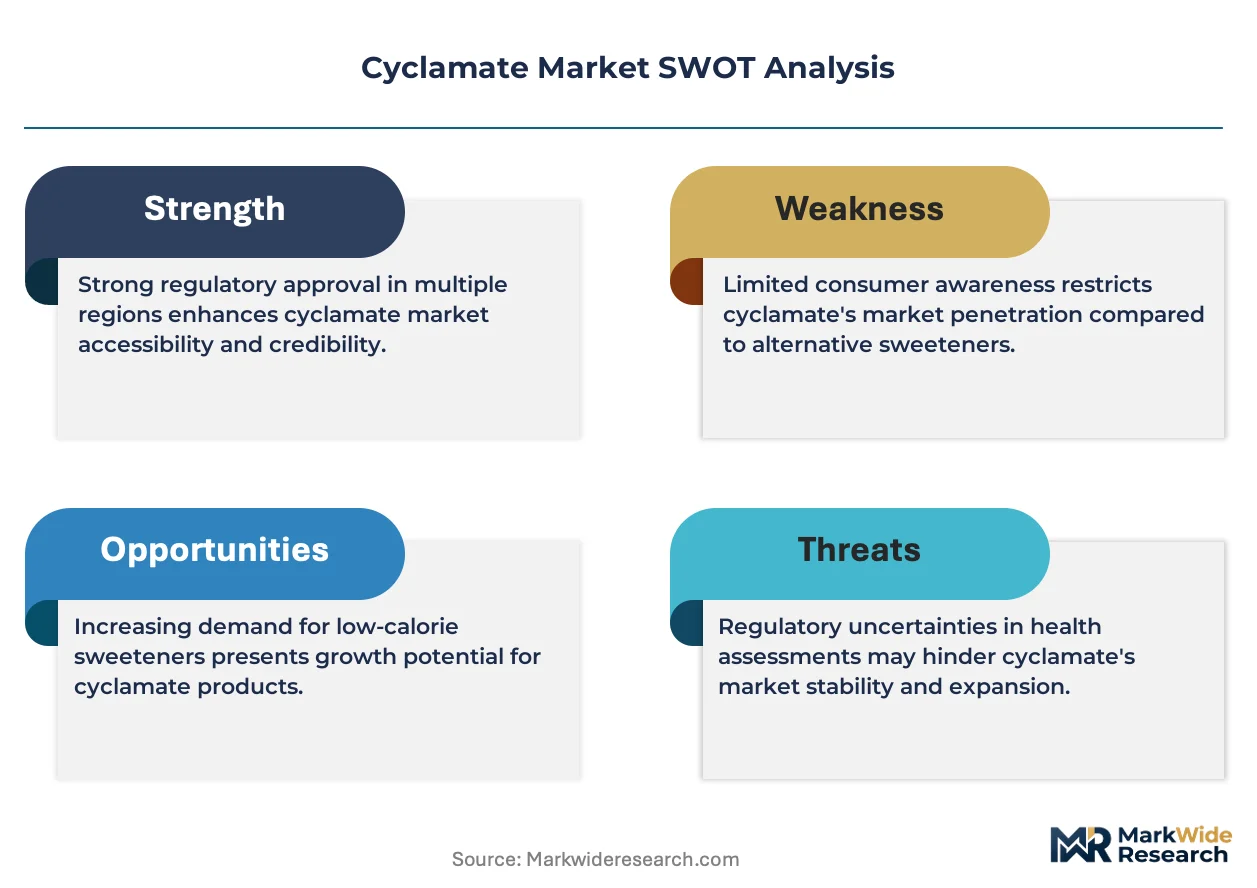
Regulatory divergence between major jurisdictions is fragmenting cyclamate market access and forcing manufacturers to maintain parallel formulation portfolios for different export destinations. This structural condition elevates compliance capability as the primary competitive differentiator over pure production economics.
Growth Catalysts
- Cost-sensitive beverage manufacturing:Southeast Asian soft drink producers are expanding cyclamate adoption as sugar prices fluctuate, with Thai and Indonesian bottlers driving volume procurement.
- EFSA clearance maintenance:The European regulator's continued authorization of specified usage levels permits sustained food-grade applications across EU member states and aligned markets.
- Cyclohexylamine feedstock availability:Dedicated chemical intermediate supply from Chinese petrochemical corridors secures input cost stability for integrated manufacturers.
Market Restraints
- FDA Delaney Clause prohibition:The US ban eliminates access to the world's largest high-margin sweetener market, compressing achievable pricing premiums for export-oriented producers.
- Single-source synthesis dependency:Cyclamate production relies on sulfonation chemistry concentrated in Shandong and Jiangsu provinces, creating geographic supply vulnerability.
- Aspartame and sucralose substitution:Alternative high-intensity sweeteners with broader regulatory acceptance capture formulation slots in multinational brand portfolios.
Strategic Opportunities
- Personal care sugar-free positioning:Cosmetic and oral hygiene brands in South Korea and Japan are adopting cyclamate for non-caloric product claims in toothpaste and mouthwash formulations.
- Health Canada alignment:The regulator's permitted usage framework offers a North American beachhead distinct from FDA jurisdiction, enabling targeted market development.
- Direct-to-manufacturer digital procurement:Food ingredient platforms are disintermediating traditional distributor networks for mid-volume Southeast Asian processors.
Industry Challenges
- Pharmaceutical-grade certification timelines:Calcium cyclamate applications require extended stability testing protocols that delay revenue recognition by 18-24 months.
- Legacy formulation lock-in:Established beverage recipes with approved cyclamate levels resist rapid adjustment when regulatory limits shift, forcing costly reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclamate Market |
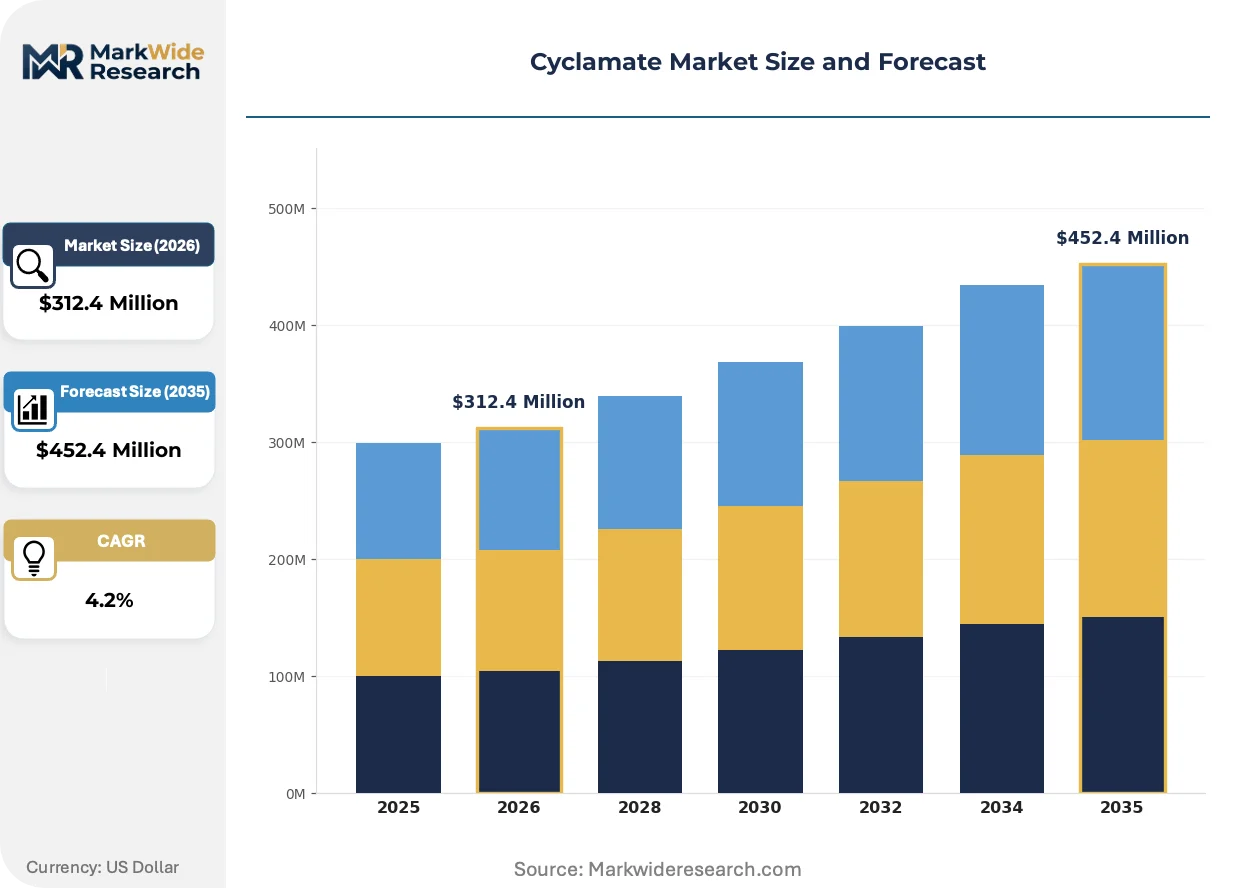
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $452.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclamic Acid, Sodium Cyclamate, Calcium Cyclamate, Potassium Cyclamate Application: Food & Beverages, Pharmaceuticals, Personal Care, Industrial Applications End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Cosmetic Brands Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Foodchem International Corporation, PT Batang Alum Industrie, PRODUCTOS ADITIVOS, Tongaat Hulett, Golden Time Chemical, Shanghai Rich Chemical New Material, Arshine Group Company, Jinyao Ruida Biology Technology, Rasna Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclamate Market Emerging Trajectories
Continuous processing technology is displacing batch sulfonation in cyclamate manufacturing, altering capital requirements and competitive positioning simultaneously. This shift intersects with tightening environmental oversight and evolving procurement patterns to reshape market structure.
Membrane filtration technology is fragmenting traditional purification workflows in cyclamate production. Chinese manufacturers are adopting nanofiltration systems to reduce solvent consumption and improve yield consistency. The technology is compressing margins for commodity-grade producers while enabling premium pricing for pharmaceutical-certified output.
China's MEE effluent discharge standards are tightening manufacturing environmental compliance burdens for cyclohexylamine derivative producers. The regulations are elevating capital requirements for wastewater treatment infrastructure. Smaller batch operators in Hebei province are consolidating or exiting as full compliance costs exceed viable operating margins.
Ingredient specification transparency is altering procurement relationships between cyclamate suppliers and Southeast Asian food processors. Buyers are demanding batch-level certification documentation and third-party audit trails previously reserved for pharmaceutical applications. Thai and Vietnamese contract manufacturers are leading this specification elevation, forcing supplier investment in digital traceability systems.
Cyclamate Market Segmentation
Cyclamate procurement channels diverge sharply by segment concentration. Food-grade volumes flow through distributor networks serving Southeast Asian bottlers, while pharmaceutical and personal care grades command direct manufacturer relationships with audit-intensive documentation requirements.
Product Type:
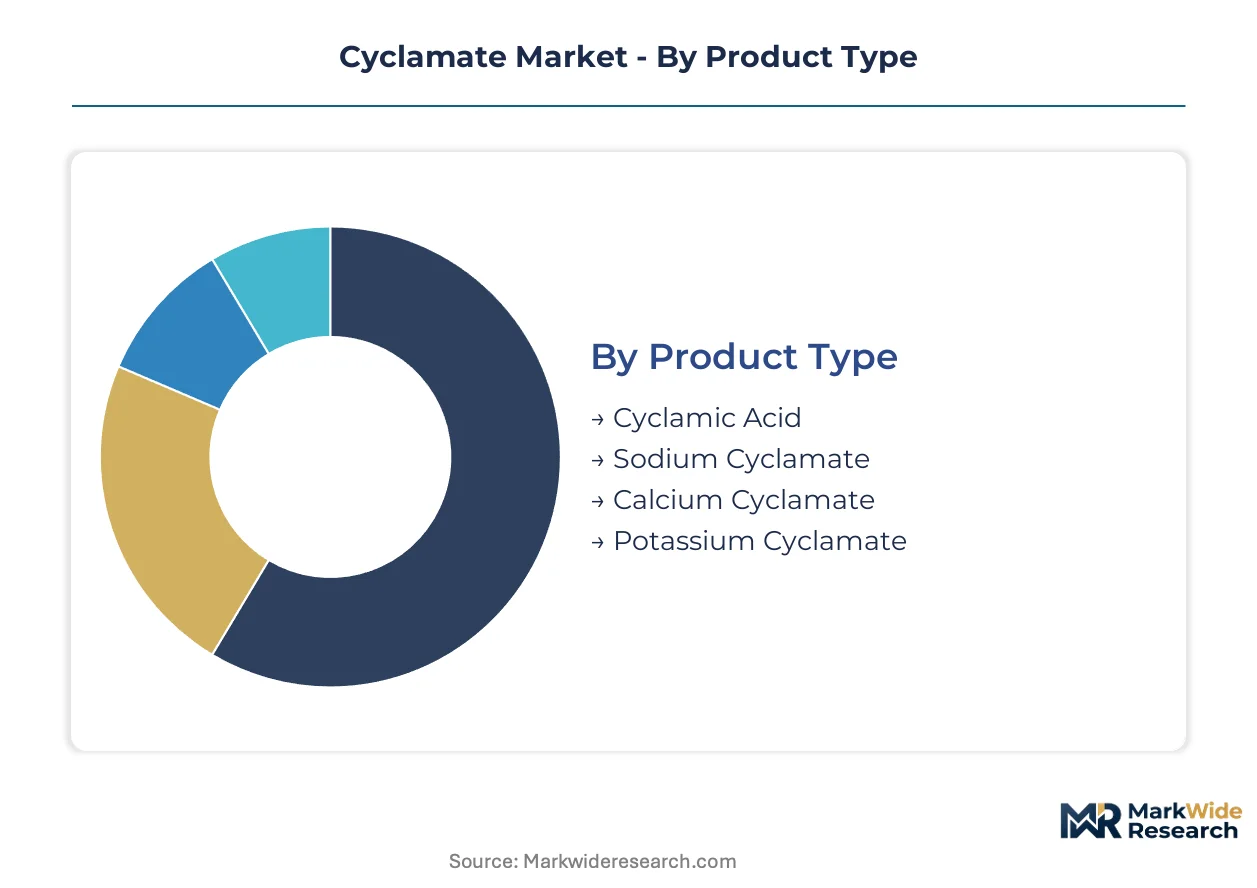
Channel mix varies by solubility profile and certification tier. Sodium and calcium salts dominate food-pharma procurement through specialized chemical distributors, while cyclamic acid and potassium variants serve industrial formulators via bulk commodity channels.
- Sodium Cyclamate:The predominant commercial form synthesized through cyclohexylamine sulfonation and sodium hydroxide neutralization. Thai and Indonesian beverage bottlers drive procurement volumes as sugar price volatility accelerates formulation switches. EFSA food-grade certification pathways sustain EU market access despite FDA exclusion.
- Calcium Cyclamate:Restricted-sodium pharmaceutical applications anchor demand, with extended stability testing protocols delaying revenue recognition. Health Canada permitted usage frameworks enable North American market development distinct from FDA jurisdiction.
- Cyclamic Acid:Intermediate chemical feedstock for downstream salt production, concentrated in Shandong province manufacturing clusters.
- Potassium Cyclamate:Niche specialty applications in reduced-sodium food formulations with limited commercial scale.
By volume, sodium cyclamate leads. By growth pace, calcium cyclamate is ahead.
Application:
Cost tier stratification separates commodity food-grade from premium pharmaceutical and personal care positioning. Beverage applications compete on input cost, while cosmetic and oral hygiene brands extract margin through sugar-free claims.
- Food & Beverages:Processed food and soft drink manufacturing generates the largest volume pull, with Southeast Asian hubs concentrating procurement. Thai bottlers expand cyclamate adoption as cost-effective sucrose replacement.
- Personal Care:Toothpaste and mouthwash formulations in South Korea and Japan adopt cyclamate for non-caloric positioning claims. Cosmetic brands extract faster margin expansion than commodity food applications.
- Pharmaceuticals:Tablet and syrup formulations requiring sodium-restricted sweetening alternatives.
- Industrial Applications:Chemical intermediate and laboratory reagent consumption with limited growth trajectory.
Food and beverages capture volume dominance. Personal care delivers the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication and documentation intensity. Multinational beverage producers maintain parallel formulation portfolios for regulatory divergence, while cosmetic brands demand batch-level traceability previously reserved for pharmaceutical buyers.
- Beverage Producers:Southeast Asian soft drink manufacturers drive cyclamate volume procurement as sugar price fluctuations accelerate adoption. Thai and Indonesian bottlers lead regional procurement expansion.
- Cosmetic Brands:South Korean and Japanese oral hygiene formulators demand sugar-free positioning claims with third-party audit trails.
- Food Manufacturers:Processed food processors in Vietnam and Thailand specification elevation forces supplier investment in digital traceability systems.
- Pharmaceutical Companies:Sodium-restricted formulation requirements with extended certification timelines.
Beverage producers dominate volume share. Cosmetic brands are gaining share fastest.
Distribution Channel:
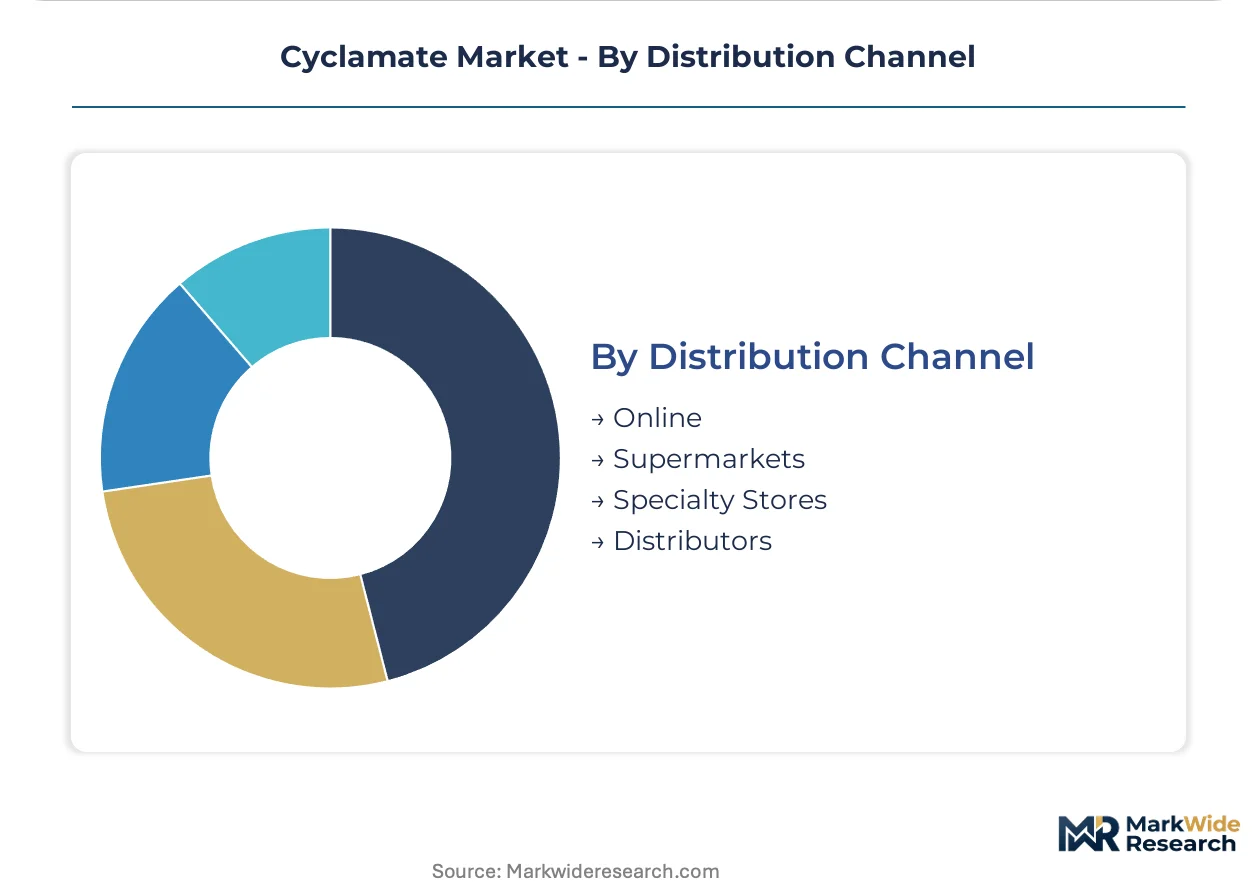
Geography shapes channel configuration. Southeast Asian procurement concentrates through distributor networks, while digital platforms disintermediate traditional channels for mid-volume processors seeking direct manufacturer relationships.
- Distributors:Traditional chemical distribution networks dominate food-grade cyclamate procurement serving Southeast Asian processors. Established relationships sustain volume flows despite platform disintermediation pressure.
- Online:Food ingredient platforms enable direct-to-manufacturer procurement for mid-volume Thai and Vietnamese contract manufacturers. Digital traceability documentation accompanies platform transactions.
- Specialty Stores:Laboratory and pharmaceutical-grade supply for small-batch formulators with certification requirements.
- Supermarkets:Limited retail channel presence for consumer-packaged sweetener alternatives.
Distributors retain volume leadership. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply between permissive Asian markets and restricted Western jurisdictions. Thai and Indonesian bottlers drive food-grade procurement volumes, while Chinese production clusters supply global export demand. European formulators maintain steady offtake under EFSA authorization frameworks.
China
Shandong and Jiangsu provinces concentrate cyclamate synthesis capacity serving export-oriented manufacturers. SAMR enforces GB standards for food-grade purity and maximum permitted levels across categories. The Yangtze River Delta chemical corridor anchors production scale with integrated cyclohexylamine feedstock supply.
Indonesia
Domestic beverage bottlers expand cyclamate adoption as sugar price volatility accelerates cost-driven formulation switches. National food safety regulations permit specified usage levels in soft drink manufacturing. PT Batang Alum Industrie anchors local supply serving Java-based processing clusters.
Thailand
Soft drink producers drive regional procurement expansion as ASEAN trade integration reduces cross-border input costs. The Thai Food and Drug Administration maintains permitted additive frameworks aligned with Codex standards. Bangkok metropolitan area concentrates bottling capacity demanding steady cyclamate offtake.
Germany
EFSA authorization sustains food-grade applications across EU member states despite FDA exclusion from transatlantic markets. German processed food manufacturers maintain steady demand for sodium cyclamate in reduced-calorie formulations. The North Rhine-Westphalia chemical processing belt channels distribution into broader European markets.
Canada
Health Canada permitted usage frameworks offer North American market access distinct from FDA Delaney Clause prohibition. Domestic food processors leverage this regulatory divergence for export-competitive positioning. Ontario and Quebec manufacturing corridors concentrate formulation demand serving continental distribution networks.
Cyclamate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in cyclamate manufacturing. Foodchem International Corporation leverages backward integration into cyclohexylamine feedstock to sustain margin stability across pricing cycles. PT Batang Alum Industrie anchors its position through dedicated sodium cyclamate capacity serving Indonesian domestic demand. Golden Time Chemical competes on scale economics at its Shandong production complex. Strategic differentiation concentrates on captive raw material supply and geographic proximity to Southeast Asian demand centers.
Among Asia-Pacific-based manufacturers, Foodchem International Corporation, PT Batang Alum Industrie, and Golden Time Chemical occupy positions reflecting distinct competitive archetypes. Foodchem represents the integrated leader model with upstream control over critical feedstock. PT Batang Alum Industrie exemplifies domestic-market anchoring with dedicated capacity serving regional bottlers. Golden Time Chemical sits within the scale-driven export tier leveraging Shandong province production concentration. These three patterns—vertical integration, geographic specialization, and manufacturing scale—structure competitive positioning across the market.
| Leading Market Players |
|---|
| Foodchem International Corporation |
| PT Batang Alum Industrie |
| PRODUCTOS ADITIVOS |
| Tongaat Hulett |
| Golden Time Chemical |
| Shanghai Rich Chemical New Material |
| Arshine Group Company |
| Jinyao Ruida Biology Technology |
| Rasna Private Limited |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles at Southeast Asian beverage processors compress pricing leverage for cyclamate suppliers, binding procurement rhythms to cyclohexylamine feedstock availability from Shandong province and EFSA certification tiers that stratify buyer willingness-to-pay.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between integrated manufacturers and Indonesian bottlers, while spot transactions serve mid-volume Vietnamese processors. Price differentiation separates pharmaceutical-grade calcium cyclamate with extended stability documentation from commodity sodium grades. Pricing pressure intensifies in standard food-grade tiers as aspartame and sucralose substitution accelerates formulation switches. Beverage producers exhibit highest price sensitivity; cosmetic brands in South Korea absorb premiums for sugar-free positioning claims.
Supply Chain Analysis
Strategic stockpiling of cyclohexylamine feedstock characterizes integrated producers' inventory posture, contrasting with just-in-time chemical sourcing among smaller batch operators. Supply concentrates in China, Indonesia, and Germany, drawing from cyclohexylamine sulfonation chemistry and sodium hydroxide neutralization inputs. Single-source synthesis dependency in Shandong and Jiangsu provinces creates geographic supply vulnerability. Distribution runs through specialized chemical distributors serving Southeast Asian food processors, with digital platforms disintermediating traditional channels for mid-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclamate procurement is shifting toward platform-mediated transparency, with ingredient specification databases and batch-level traceability systems emerging as the interoperability layer that reconfigures supplier-buyer power dynamics.
For Market Incumbents: Shield margin stability through backward integration into cyclohexylamine feedstock production and captive sodium hydroxide supply. Elevation of Thai and Vietnamese buyer documentation requirements demands investment in digital audit trail systems to defend against commodity traders with lower compliance capability. For New Entrants and Emerging Players: Anchor in Health Canada-permitted usage frameworks as a North American beachhead distinct from FDA prohibition. Personal care sugar-free positioning in Japanese and South Korean oral hygiene markets offers the most penetrable white-space, with direct-to-manufacturer digital procurement as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected cyclamate divisions lacking EFSA pharmaceutical-grade certification pathways. Long-term viability hinges on regulatory divergence persistence across jurisdictions. Monitor ANVISA and Mexican health agency safety database reviews as the critical inflection signal for Brazilian market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclohexylamine | Captive feedstock supply insulates Foodchem International Corporation from petrochemical price volatility cycles. |
| Pharmaceutical-Grade Certification Investment | Extended stability testing protocols unlock calcium cyclamate premiums in Health Canada-aligned markets. |
| Digital Traceability System Deployment | Batch-level documentation satisfies Thai and Vietnamese contract manufacturer audit requirements. |
| Continuous Processing Technology Adoption | Membrane filtration displacement of batch sulfonation reduces solvent consumption and improves yield consistency. |
| Direct-to-Manufacturer Platform Partnership | Food ingredient platforms disintermediate distributor networks for mid-volume Southeast Asian processors. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with plant managers at Shandong and Jiangsu production facilities, procurement leads at Thai and Indonesian beverage bottlers, distribution channel partners, and EFSA regulatory affairs specialists; and secondary validation through customs and trade flow databases, SAMR GB standard filings, SEC chemical sector disclosures, and ACC specialty chemical reports. Bottom-up volume triangulation against top-down market sizing anchored the approach.
Across the analysis window, the forecasting framework modeled product type segmentation by solubility profile and certification tier, application segmentation by cost tier stratification, and end-user segmentation by procurement sophistication. CAGRs derived from regression against historical cyclohexylamine price cycles and Southeast Asian soft drink production indices. Shandong province capacity utilization rates and EFSA authorization maintenance probability served as industry-specific forecast inputs.
Material uncertainties — pending ANVISA and Mexican health agency regulatory reviews, MEE effluent standard enforcement intensity, and aspartame substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory divergence persistence and feedstock supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Global Linear Alpha Olefins Market