
 Barite Market | 2026-2036
Barite Market Size, Share, and Industry Trends Forecast 2026-2036
Barite Market Intelligence
API 13A specification-grade barite is redrawing competitive thresholds across the market. Halliburton leverages captive mine-to-well supply chains across Nevada and Missouri to secure consistent high-density ore quality. Schlumberger Limited anchors its barite procurement through long-term offtake agreements with Mexican and Moroccan producers. CIMBAR Performance Minerals dominates the specialty-grade segment through in-house grinding and particle-size control down to sub-44-micron specifications.
Barite is a barium sulfate mineral with a specific gravity of 4.2 to 4.5, mined from sedimentary deposits and processed through jigging, flotation, and grinding to meet density and purity requirements for industrial applications. Its primary commercial purpose centers on serving as a weighting agent in drilling fluids to control formation pressure during oil and gas extraction. Drilling-grade barite commands the largest volume share given its irreplaceable role in wellbore stability, while ultra-fine-grade material captures premium pricing in high-temperature deepwater formulations where particle-size distribution determines performance under extreme downhole conditions. Industrial-grade barite serves mature demand in paints and coatings, with margin pools thinning as synthetic alternatives gain traction in plastics compounding.
The American Petroleum Institute enforces density, hardness, and soluble-salt limits through API 13A, directly determining which ore sources qualify for North American drilling contracts. The EPA regulates barite mining under Clean Water Act discharge permits, constraining domestic production expansion and pushing buyers toward imported material. The Bureau of Land Management controls access to federal barite reserves in Nevada, shaping long-term supply security for domestic processors. Stakeholders must monitor API specification revision cycles and federal leasing policy shifts to anticipate qualification changes that would restructure qualified supplier rosters.
Market Dynamics
API 13A specification enforcement is compressing qualified supplier rosters and forcing processors to invest in density upgrading and contaminant removal infrastructure that smaller mines cannot afford.
Growth Catalysts
- Deepwater drilling expansion:Brazil's pre-salt formations and Guyana's offshore blocks require high-purity barite with sub-44-micron particle distribution for high-temperature wellbore stability.
- EPA discharge permit constraints:Clean Water Act limitations on Nevada mine tailings are redirecting US demand toward Moroccan and Mexican import channels with established beneficiation capacity.
- API specification upgrades:The American Petroleum Institute's tightened soluble-salt thresholds are disqualifying low-grade ore sources and concentrating procurement among certified processors.
Market Restraints
- Input cost volatility:Diesel and grinding media expenses fluctuate with energy markets, squeezing margin pools for independent Nevada processors without captive mining operations.
- Supply concentration risk:Moroccan and Chinese export channels control roughly two-thirds of seaborne drilling-grade material, exposing buyers to port congestion and customs inspection delays.
- Substitution threat:Micronized hematite and synthetic ilmenite weighting agents are capturing niche share in ultra-high-density formulations above 4.3 specific gravity.
Strategic Opportunities
- Underpenetrated geography:Argentina's Vaca Muerta shale development lacks established barite supply chains, creating first-mover advantage for processors willing to establish grinding terminals near Neuquén drilling clusters.
- Regulatory tailwind:India's Production Linked Incentive scheme for critical minerals is subsidizing beneficiation plant upgrades that could redirect domestic barite toward export-grade API certification.
- Technology convergence:Integration of real-time particle-size analyzers with automated grinding circuits is enabling on-specification production with lower reprocessing rates and reduced waste generation.
Industry Challenges
- Certification timeline compression:API 13A requalification cycles now demand six-month analytical traceability documentation that legacy quality systems cannot generate without ERP upgrades.
- Supply chain reconfiguration friction:Shifting procurement from Nevada domestic sources to Moroccan import channels requires renegotiation of long-term rig-site inventory agreements with drilling contractors.
- Skill gap in mineral processing:Qualified flotation engineers and grinding specialists are concentrated among retiring cohorts at established Missouri and Nevada operations, constraining plant expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barite Market |
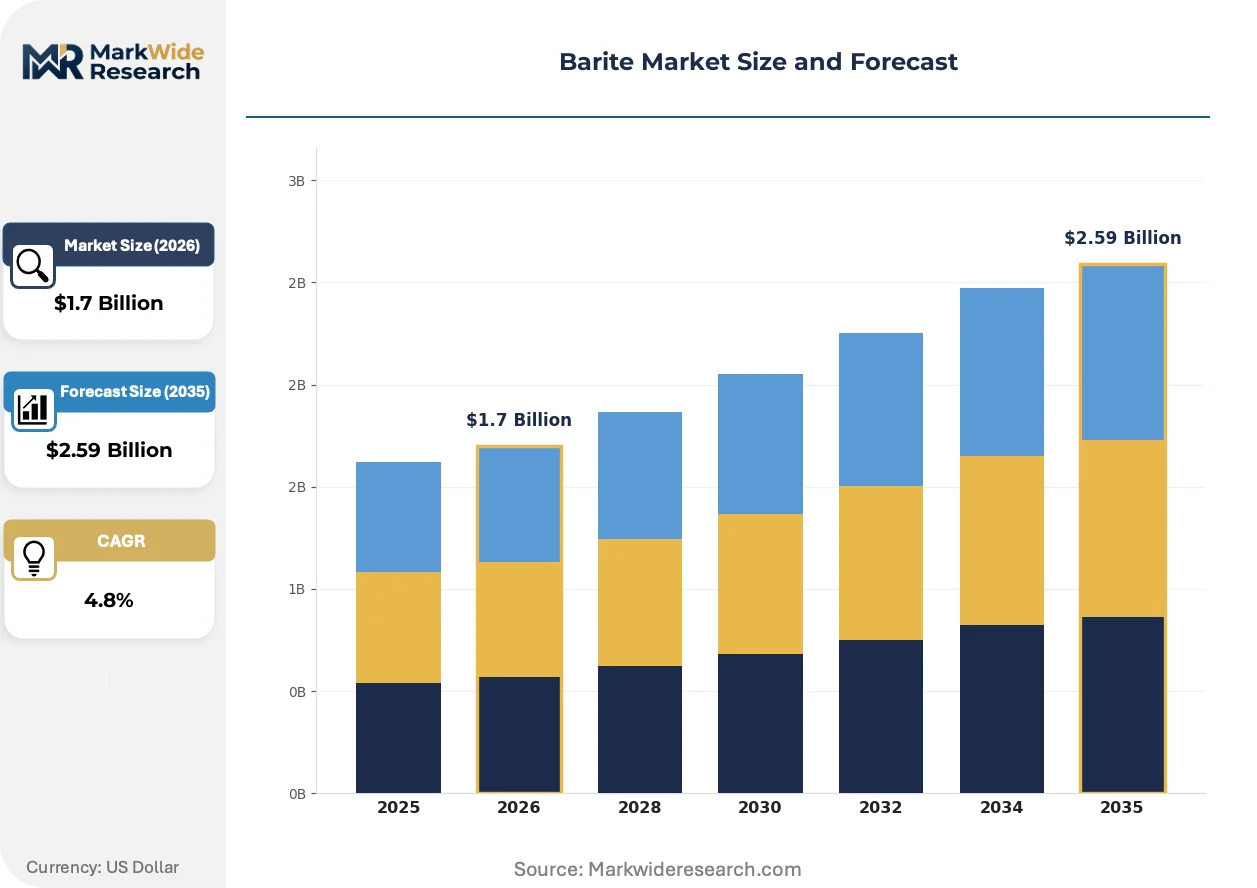
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Grade, Standard Grade, Ultra-Fine Grade, Industrial Grade Application: Oil & Gas, Paints & Coatings, Plastics, Pharmaceuticals End User: Energy Sector, Industrial Manufacturing, Chemical Industry, Healthcare Providers Distribution Channel: Direct Sales, Online Retail, Distributors, Agents |
| Companies Covered | Halliburton, Schlumberger Limited, CIMBAR Performance Minerals, Excalibar Minerals LLC, Ashapura Minechem Limited, Andhra Pradesh Mineral Development Corporation, Guizhou Saboman Import & Export Co., Ltd., Newpark Resources Inc., Huber Engineered Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barite Market Strategic Shifts & Innovations
Processing technology upgrades and procurement model restructuring are redrawing competitive boundaries between integrated miners and independent grinding specialists.
Advanced sensor-based ore sorting is displacing conventional dense-media separation in front-end beneficiation. Major Chinese processors are installing X-ray transmission sorters at Moroccan mine sites to reject sub-4.2 specific gravity material before grinding. This technology is displacing labor-intensive hand-sorting and reducing downstream energy consumption by 15-20 percent.
REACH authorization requirements for barium compounds in industrial applications are tightening purity documentation for European paint and coatings buyers. ECHA's extended safety data sheet obligations now mandate crystalline silica quantification below 0.1 percent for non-drilling applications. Specialty-grade processors serving European industrial markets are responding with dedicated low-silica production lines and third-party certification audits.
Long-term offtake contracting is replacing spot market purchasing among North American drilling contractors. Major pressure-pumping service companies are locking in five-year supply agreements with fixed-volume, floating-price structures indexed to API density premiums. This shift is most visible in Permian Basin operations where inventory carrying costs and rail logistics complexity favor committed supply relationships over transactional procurement.
Barite Market Segmentation
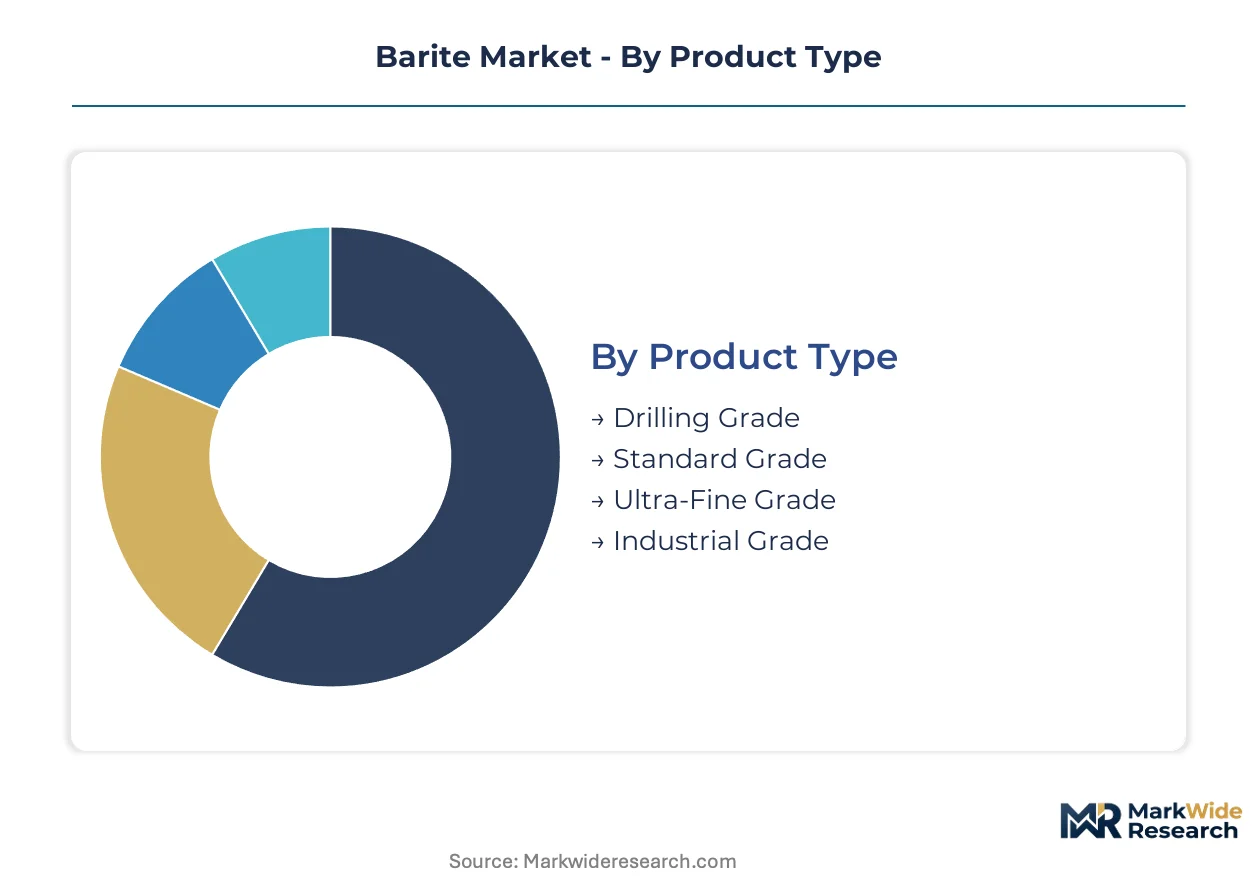
Segmentation in the barite market determines procurement pathways, certification requirements, and margin capture. API-grade material flows through rig-site direct channels, while industrial grades leverage distributor networks. Understanding these segment boundaries enables suppliers to align beneficiation investments with channel economics.
Product Type:
Channel-mix dynamics vary sharply by density and particle specification. Drilling-grade material moves predominantly through direct sales to pressure-pumping service companies, while industrial grades rely on distributor networks for fragmented paint and plastics customers.
- Drilling Grade:API 13A-compliant material with minimum 4.2 specific gravity serves as the weighting agent of choice for wellbore pressure control. Demand concentrates in the Permian Basin and offshore Brazil, where deepwater formations require consistent high-density ore quality that only certified Moroccan and Nevada processors reliably deliver.
- Ultra-Fine Grade:Sub-44-micron particle distribution enables high-temperature stability in deepwater formulations above 300°F bottom-hole conditions. Growth is accelerating fastest in Guyana's offshore blocks and Brazil's pre-salt clusters, where particle-size distribution determines performance under extreme downhole pressure.
- Standard Grade:Intermediate density material serves mid-depth drilling and well workover applications.
- Industrial Grade:Lower-density ore finds outlets in mature paint and coatings markets facing substitution pressure from synthetic alternatives.
By volume, Drilling Grade leads. By growth pace, Ultra-Fine Grade is climbing the fastest.
Application:
Cost-tier stratification separates commodity drilling fluids from premium industrial formulations. Oil and gas applications command density premiums, while pharmaceutical and specialty coatings justify purity-based pricing.
- Oil & Gas:Drilling fluids represent the irreplaceable commercial foundation, consuming material with strict API density, hardness, and soluble-salt thresholds. Procurement concentrates among Halliburton, Schlumberger, and Baker Hughes, who lock in five-year offtake agreements with fixed-volume, floating-price structures.
- Pharmaceuticals:High-purity barium sulfate serves contrast media and diagnostic applications requiring crystalline silica below 0.1 percent. ECHA's extended safety data sheet obligations in Europe are tightening purity documentation, redirecting qualified supply toward dedicated low-silica production lines.
- Paints & Coatings:Industrial-grade material provides opacity and weight in marine and industrial coatings, with margin pools thinning as titanium dioxide alternatives gain formulation share.
- Plastics:Compounding applications face displacement from synthetic weighting agents in density-sensitive polymer formulations.
By revenue contribution, Oil & Gas dominates. By margin expansion, Pharmaceuticals is gaining share fastest.
End User:
Customer-type concentration shapes contract structure and inventory positioning. Integrated energy companies favor long-term commitments, while fragmented industrial buyers tolerate spot-market volatility.
- Energy Sector:Pressure-pumping service companies and exploration-and-production operators drive volume, with Permian Basin drillers demanding just-in-time rig-site delivery that favors rail-served grinding terminals in Texas and New Mexico.
- Chemical Industry:Specialty processors serving barium carbonate and barium chloride derivatives require consistent ore chemistry for downstream conversion efficiency.
- Industrial Manufacturing:Paint formulators and plastics compounders purchase smaller lots through distributor channels with less stringent certification requirements.
- Healthcare Providers:Radiology departments and diagnostic imaging centers represent the terminal demand point for pharmaceutical-grade material, with procurement filtered through medical device and contrast media manufacturers.
By procurement scale, Energy Sector leads. By contract duration extension, Healthcare Providers is expanding most quickly.
Distribution Channel:
Supply concentration and logistics complexity determine channel viability. High-volume drilling-grade material bypasses intermediaries, while fragmented industrial demand sustains distributor networks.
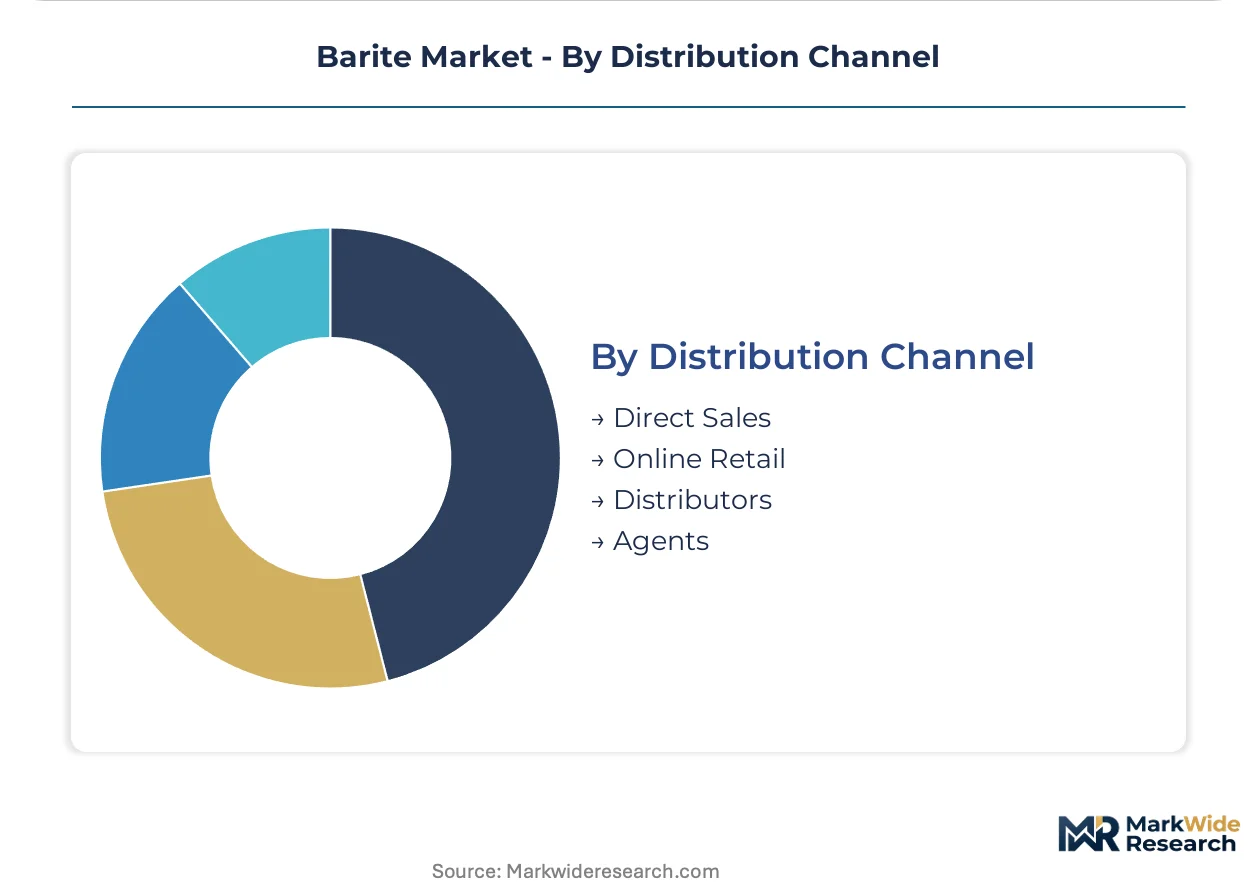
- Direct Sales:Long-term offtake agreements with fixed-volume, floating-price structures are displacing spot purchasing among North American drilling contractors. This channel captures the full API density premium and eliminates distributor margin stacking.
- Distributors:Industrial-grade material for paints, coatings, and plastics moves through regional chemical distributors who aggregate fragmented demand and provide technical service support.
- Agents:Moroccan and Chinese export channels rely on commission-based representatives to manage customs documentation and port logistics for seaborne material.
- Online Retail:Small-lot industrial and laboratory-grade purchases migrate toward digital platforms for price transparency and rapid fulfillment.
By volume share, Direct Sales leads. By digital penetration growth, Online Retail is advancing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward Moroccan and Chinese seaborne channels as EPA discharge constraints compress domestic US beneficiation capacity. Buyers in North America and Brazil are restructuring procurement geography to secure API-certified material.
United States
Permian Basin drilling operations in Texas and New Mexico consume the bulk of imported drilling-grade material, with rail-served grinding terminals enabling just-in-time rig-site delivery. The EPA enforces Clean Water Act discharge permits on Nevada mine tailings, redirecting demand toward Moroccan and Mexican import channels. Halliburton operates captive mine-to-well supply chains across Nevada and Missouri to secure consistent high-density ore quality.
China
Domestic barite processors serve both internal shale exploration in Sichuan and export markets through established beneficiation capacity in Guizhou province. The MIIT oversees mineral resource utilization standards that shape grinding circuit investments. X-ray transmission sorters at mine sites are displacing labor-intensive hand-sorting and reducing downstream energy consumption.
Brazil
Pre-salt offshore formations and Guyana's adjacent blocks require high-purity barite with sub-44-micron particle distribution for high-temperature wellbore stability. ANVISA regulates industrial chemical imports while Petrobras anchors procurement through long-term offtake structures. Deepwater drilling clusters off Rio de Janeiro drive premium-grade consumption.
India
The Production Linked Incentive scheme for critical minerals subsidizes beneficiation plant upgrades that could redirect domestic barite toward export-grade API certification. Andhra Pradesh Mineral Development Corporation controls state-level resource extraction. Gujarat and Rajasthan processing hubs are expanding grinding capacity to serve Middle East drilling contractors.
Morocco
Seaborne export channels control roughly two-thirds of drilling-grade material entering North America and Europe, with established port infrastructure at Casablanca and Agadir. The country's national mining regulator oversees export licensing for strategic minerals. Beneficiation partnerships with Chinese processors are installing automated ore sorting technology at mine sites.
Barite Market Key Industry Players
Concentration sits with integrated oilfield service companies and specialty mineral processors who control captive mining or long-term offtake agreements. The vendor base stratifies across three tiers: global energy service conglomerates with backward integration into ore sources, regional grinding specialists with API certification infrastructure, and commodity traders aggregating fragmented mine output. Dominant competitive moves include securing Moroccan and Mexican mine offtake contracts and deploying sensor-based ore sorting technology to upgrade sub-4.2 specific gravity material.
Among integrated energy service providers, Halliburton and Schlumberger Limited represent the backward-integrated archetype with captive supply chains and long-term procurement structures. CIMBAR Performance Minerals exemplifies the specialty-grade processor tier with in-house particle-size control capabilities. These three entities anchor competitive positioning across the API certification threshold that determines contract eligibility for North American drilling operations.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger Limited |
| CIMBAR Performance Minerals |
| Excalibar Minerals LLC |
| Ashapura Minechem Limited |
| Andhra Pradesh Mineral Development Corporation |
| Guizhou Saboman Import & Export Co., Ltd. |
| Newpark Resources Inc. |
| Huber Engineered Materials |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles at Permian Basin drilling terminals concentrate pricing power among rail-served grinding operators in Texas and New Mexico. Moroccan seaborne channels capture API density premiums while Nevada domestic processors absorb EPA compliance cost compression.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across North American drilling operations. Price differentiation rests on API 13A certification tier and volume scale commitments. Cost compression in standard-grade material is intensifying because Moroccan import channels undercut domestic beneficiation margins. Pressure-pumping service companies exhibit lowest price sensitivity due to pass-through drilling contracts, while independent industrial compounders face acute margin pressure from synthetic substitute availability.
Supply Chain Analysis
Just-in-time rig-site delivery preferences favor rail-served terminals over seaborne bulk channels with longer port-to-wellhead lead times. Supply concentrates in Morocco, China, and India, with ore quality varying by sedimentary deposit chemistry. Raw material flows draw from diesel fuel, grinding media, and beneficiation reagent inputs. Single-source vulnerability runs through Casablanca-Agadir port corridors where customs inspection delays cascade to Permian Basin inventory positions. Distribution runs through direct sales to pressure-pumping service companies, bypassing intermediary margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 13A certification interoperability is transforming procurement into platform-mediated supply relationships where certified processor status determines contract eligibility. Ecosystem lock-in effects favor early movers who secure backward integration into Moroccan ore sources.
For Market Incumbents: Consolidate captive mining positions in Nevada and Missouri against Moroccan import channel expansion. Secure long-term offtake agreements with Brazilian pre-salt drillers before API specification upgrades disqualify sub-4.2 specific gravity material. Prioritize sensor-based ore sorting investments to upgrade marginal ore and defend density premium capture. For New Entrants and Emerging Players: API 13A fast-track certification through third-party laboratory partnerships unlocks contract eligibility with Permian Basin pressure-pumping service companies. Argentina's Vaca Muerta shale development offers the most penetrable geography with absent established supply chains. Target grinding terminal joint ventures near Neuquén drilling clusters with rail logistics partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with non-core barite assets in Guizhou province and Rajasthan state. Five-to-ten year viability hinges on API certification infrastructure rather than commodity ore access alone. Watch for EPA discharge permit revocation signals that would accelerate import channel substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Moroccan Ore Sources | Secures API 13A-compliant supply outside EPA discharge permit constraints. |
| Sensor-Based Ore Sorting Deployment | Reduces downstream energy consumption at Guizhou and Moroccan mine sites. |
| Long-Term Offtake Agreement Structuring | Locks in five-year fixed-volume commitments with Halliburton and Schlumberger. |
| Grinding Terminal Capacity Expansion | Enables just-in-time rig-site delivery across Permian Basin drilling clusters. |
| Ultra-Fine Grade Production Line Investment | Captures premium pricing from Brazil pre-salt and Guyana offshore blocks. |
Research Approach
Initial hypotheses were tested against primary input from pressure-pumping procurement directors, Nevada mine operations managers, Moroccan export channel agents, and API laboratory certification specialists and refined through customs trade data, SEC 10-K filings from integrated service companies, Bureau of Land Management leasing records, and ECHA extended safety data sheet obligations. Bottom-up volume estimates triangulated against top-down drilling activity forecasts across the analysis window.
Variance decomposition across grade tier, end-use application, and regional production hub dimensions shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macro drilling expenditure patterns. Industry-specific inputs included rig-count trajectories in named shale basins and API specification revision timelines.
Decision-makers should treat outputs as directional under stable EPA discharge permit enforcement and Moroccan export licensing continuity; material deviation would warrant model refresh. Revision becomes warranted when API 13A soluble-salt thresholds tighten beyond current analytical traceability capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Formic Acid Market