
 Europe Luxury Packaging Market | 2026-2036
Europe Luxury Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Packaging Market Foresight
Molded fiber is recalibrating cost structures across rigid luxury boxes as converters offset pulp premiums against elimination of plastic window films. WestRock leverages integrated paperboard mills to secure fiber traceability for cosmetics clients. Mondi anchors European supply through kraftliner specialization and on-site finishing partnerships with fragrance houses.
Europe luxury packaging denotes high-aesthetics primary and secondary containers engineered from paperboard, glass, metal, or coated substrates, typically incorporating embossing, foil stamping, magnetic closures, or soft-touch laminates to signal brand prestige and protect premium contents. The category spans boxes, bags, bottles, and tins, with paper-based formats dominating volume due to printability and structural versatility while glass bottles command margin pools in spirits and fragrance. Cosmetics and fashion end-use segments drive customization intensity, whereas food and electronics applications favor standardized formats with shorter lead times.
EMA packaging guidelines, REACH substance restrictions, and the EU Green Deal circularity targets collectively elevate compliance costs for imported laminates and solvent-based coatings while favoring domestic fiber and glass supply chains. The F-Gas Regulation further constrains certain foam-in-place cushioning alternatives, pushing converters toward paper-based protective structures. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and material passport requirements before committing to multi-year tooling investments.
Market Dynamics
The EU Green Deal's circularity mandates are compressing converter margins while simultaneously unlocking premium pricing for fiber-based formats that eliminate plastic laminates entirely.
Growth Catalysts
- REACH compliance deadlines:Cosmetics houses accelerate rigid box transitions to eliminate restricted solvent-based coatings ahead of ECHA substance evaluations.
- Unboxing content amplification:Heritage maisons in France and Italy expand magnetic closure and foil-stamped orders as social media visibility directly correlates with brand equity metrics.
- Molded fiber tooling advances:Pulp-forming precision now matches thermoformed plastic tolerances for fragrance inserts and cosmetic trays.
Market Restraints
- Softwood pulp price volatility:Nordic kraftliner supply tightness transmits directly to rigid box substrate costs with limited hedging mechanisms for mid-tier converters.
- Artisan converter concentration:Paris, Milan, and Hamburg clusters control specialized embossing and hot-stamping capacity, creating bottleneck risks for new market entrants.
- Glass bottle weight standards:Spirits and fragrance houses face EU packaging weight directives that constrain premium heft signals without alternative tactile differentiators.
Strategic Opportunities
- Extended Producer Responsibility fee arbitrage:Germany's VerpackG modulation criteria reward fiber-dominant formats with lower compliance costs versus plastic-laminated alternatives.
- Refillable fragrance systems:Magnetic closure engineering for permanent outer cases creates recurring component demand separate from consumable glass bottle cycles.
- CSRD disclosure requirements:Listed cosmetics groups must document packaging circularity metrics, creating audit-ready supply chain premiums for certified fiber traceability.
Industry Challenges
- Hot-stamping operator scarcity:Specialized foil application craftsmanship concentrates among aging workforces in Northern Italy with inadequate apprenticeship pipeline replenishment.
- Multi-material separation infrastructure:Magnetic closures combining metal, paperboard, and textile liners complicate post-consumer sorting compliance under evolving EU harmonized waste frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Packaging Market |
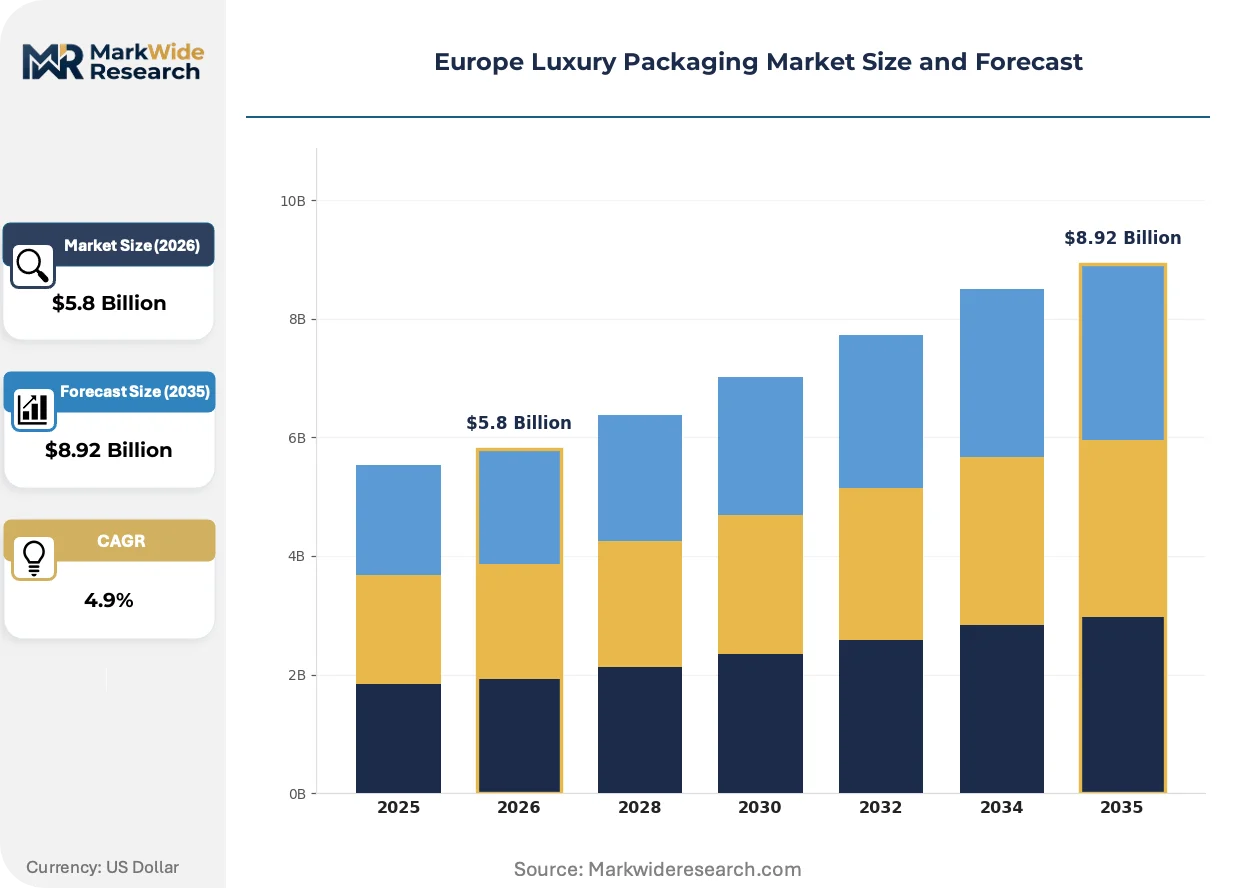
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Bottles, Tins Material: Paper, Glass, Metal, Plastic End User: Cosmetics, Food & Beverages, Electronics, Fashion Design Style: Minimalist, Vintage, Eco-Friendly, Luxury |
| Companies Covered | WestRock, Mondi, Amcor, Prestige Packaging Industries, McLaren Packaging, Smurfit Kappa, Crown Holdings, Graphic Packaging International, DS Smith, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Packaging Market Shifts & Advancements
Digital finishing technologies are collapsing minimum order thresholds for customization while regulatory pressure on material composition accelerates substrate experimentation across heritage supply chains.
Laser die-cutting systems are automating intricate window and aperture geometries previously requiring manual tooling changeovers. Fragrance houses in France now specify sub-millimeter tolerance cutouts for box reveals without plastic films. This capability compression enables economic production runs below five thousand units, eroding the volume advantage of standardized formats.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant paper coatings for food-adjacent cosmetic applications. Converters pivot to bio-based barrier treatments derived from agricultural byproducts. The F-Gas Regulation simultaneously constrains polyurethane foam cushioning, pushing protective structures toward molded pulp architectures for glass bottle transit.
Direct-to-consumer channel expansion by heritage cosmetics groups is fragmenting order profiles toward smaller batches with accelerated turnaround. E-commerce fulfillment requirements now specify drop-test certification for individual unit shipping without secondary overbox protection. German fragrance houses lead this specification shift, compressing traditional wholesale palletization economics while demanding integrated unboxing experience design.
Europe Luxury Packaging Market Segmentation
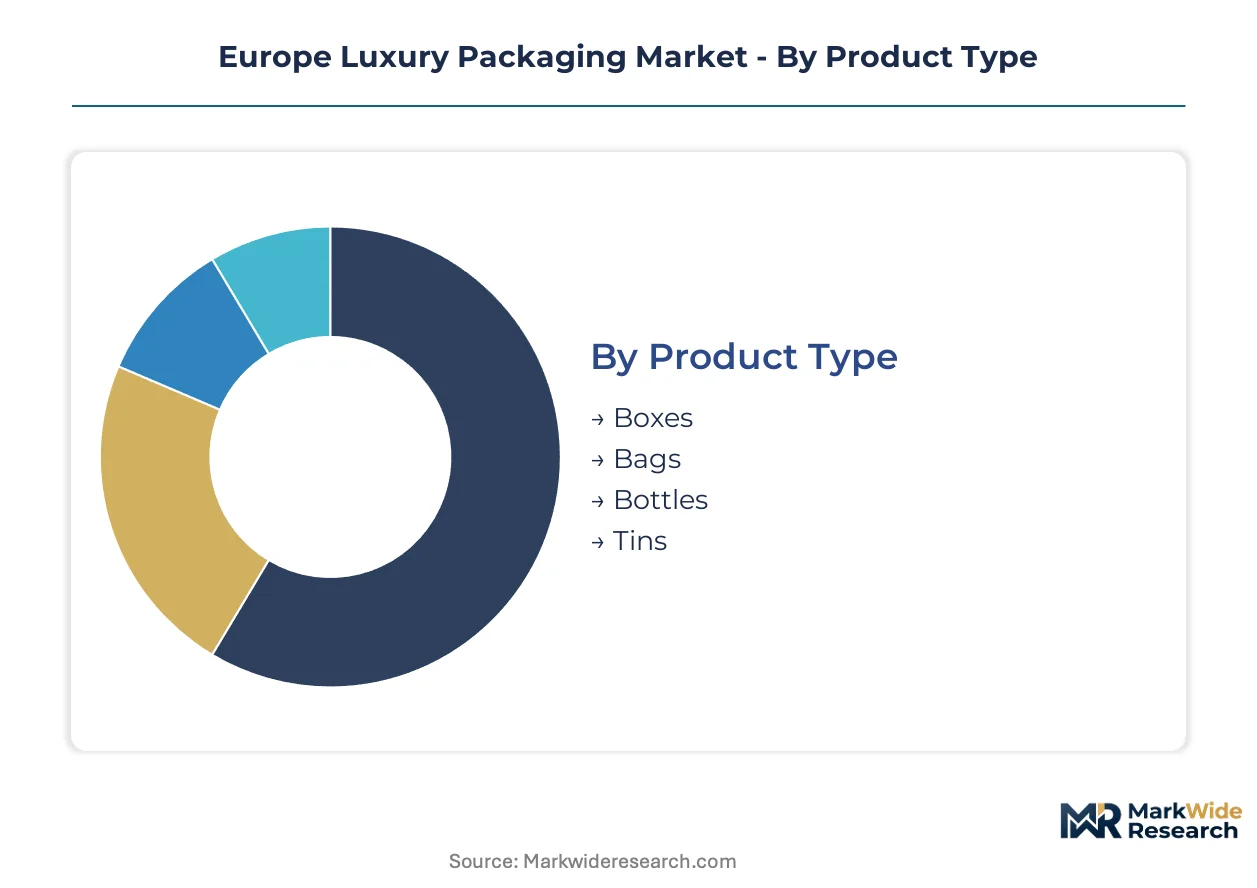
Luxury packaging segmentation in Europe reflects divergent pressures between heritage craftsmanship requirements and regulatory-driven material transitions. Each dimension captures distinct value pools shaped by cosmetics house specifications, REACH compliance deadlines, and unboxing experience investments.
Product Type:
Customization intensity varies sharply across formats, with rigid structures commanding premium tooling investments while flexible formats prioritize speed-to-market.
- Boxes:Rigid paperboard constructions with magnetic closures and foil-stamped surfaces dominate cosmetics primary packaging. French heritage maisons in Paris cluster demand around embossed rigid boxes as unboxing content amplification directly correlates with brand equity metrics.
- Bottles:Molded glass with weighted bases and silk-screened decoration commands margin pools in fragrance and spirits applications. Italian fragrance houses face EU packaging weight directives that constrain premium heft signals, accelerating investment in tactile surface treatments as alternative differentiators.
- Bags:Laminated paper and textile-lined carriers serve fashion and gift-with-purchase applications with shorter lead times.
- Tins:Metal cylinders and hinged containers concentrate in food-adjacent cosmetics and seasonal confectionery collaborations.
Leading the category by volume: Boxes. Growing fastest: Bottles.
Material:
Cost tier stratification separates fiber-dominant formats with lower Extended Producer Responsibility compliance costs from laminate-dependent alternatives facing REACH substance restrictions.
- Paper:Coated paperboard and molded fiber architectures eliminate plastic window films through pulp-forming precision matching thermoformed tolerances. German converters leverage kraftliner specialization to secure fiber traceability for audit-ready supply chains under CSRD disclosure requirements.
- Glass:Heavy-base bottles with metallized closures and silk-screened decoration anchor fragrance margin pools. Hamburg-area spirits houses specify drop-test certified individual unit shipping for direct-to-consumer channels, compressing traditional palletization economics.
- Metal:Aluminum tins and steel hinged boxes serve protective and premium tactile applications with full recyclability credentials.
- Plastic:Thermoformed trays and windows face accelerating substitution as EU Green Deal circularity mandates compress converter margins for multi-material formats.
Dominant by revenue: Paper. Steepest expansion trajectory: Molded fiber variants within paper.
End User:
Application-driven specification intensity separates cosmetics and fashion investment in bespoke unboxing engineering from electronics and food standardization priorities.
- Cosmetics:Primary and secondary packaging with magnetic closures, soft-touch laminates, and foil-stamped surfaces drives customization intensity. French and Italian heritage maisons expand rigid box orders as social media visibility directly shapes brand equity metrics.
- Fashion:Garment carriers, shoe boxes, and accessory packaging balance protection with tactile prestige signals for boutique and e-commerce fulfillment.
- Food & Beverages:Spirits bottles and confectionery tins favor standardized formats with shorter lead times and weight-constrained specifications.
- Electronics:Protective luxury boxing for high-end devices prioritizes drop-test certification and sustainable material credentials over elaborate finishing.
Commanding highest customization investment: Cosmetics. Expanding most quickly: Fashion direct-to-consumer packaging.
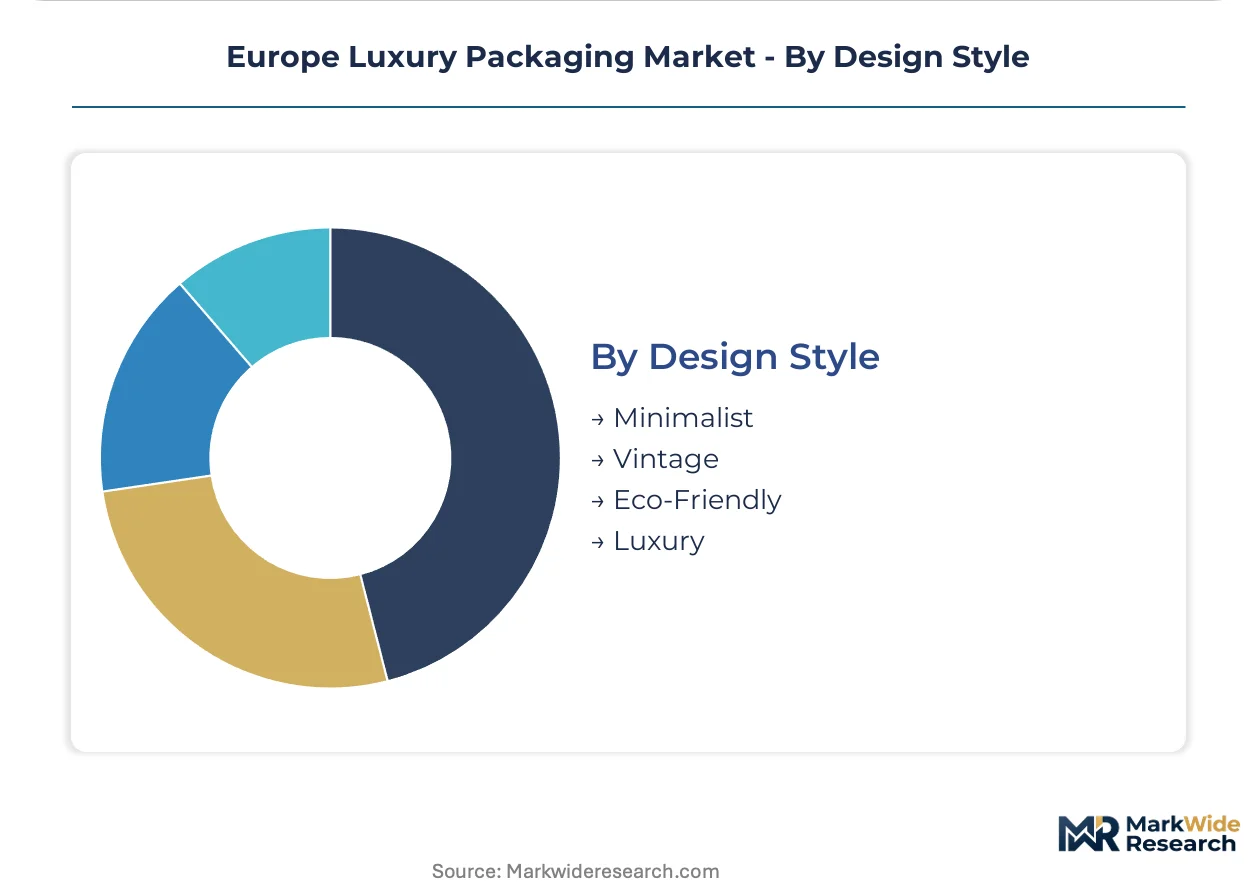
Design Style:
Maturity differentiation separates established minimalist and vintage codes from emerging regulatory-responsive and prestige-maximizing approaches.
- Luxury:Maximalist finishing with embossing, debossing, foil stamping, and magnetic closures represents established heritage house codes. Northern Italian artisan clusters control specialized hot-stamping capacity with aging workforce constraints.
- Eco-Friendly:Fiber-dominant formats with visible recycled content and plastic-free constructions gain share as Germany's VerpackG modulation criteria reward compliance cost arbitrage.
- Minimalist:Reduced surface decoration and structural simplicity prioritize substrate quality and precise proportions.
- Vintage:Nostalgic typography, aged color palettes, and heritage reproduction formats serve niche fragrance and spirits positioning.
Highest volume share: Luxury. Gaining share fastest: Eco-Friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French and Italian heritage maisons concentrate demand for rigid boxes with magnetic closures and foil-stamped surfaces. Germany's VerpackG modulation criteria reward fiber-dominant formats with lower Extended Producer Responsibility compliance costs. Artisan converter clusters in Paris, Milan, and Hamburg control specialized embossing and hot-stamping capacity.
France
Parisian heritage cosmetics houses expand rigid box orders as unboxing content amplification directly correlates with brand equity metrics. REACH compliance deadlines from ECHA accelerate transitions away from solvent-based coatings. The Île-de-France cluster anchors specialized foil-stamping and magnetic closure engineering for fragrance primary packaging.
Italy
Milan-based artisan converters command premium pricing for embossed rigid boxes serving luxury fashion and cosmetics segments. The EU Green Deal's circularity mandates compress margins for plastic-laminated formats while unlocking premiums for fiber-based alternatives. Northern Italian hot-stamping workshops face workforce constraints as aging craftsmen retire without adequate apprenticeship pipeline replenishment.
Germany
Hamburg-area spirits houses specify drop-test certified individual unit shipping for direct-to-consumer channel expansion. Germany's VerpackG Extended Producer Responsibility framework rewards fiber-dominant formats with lower modulation fees versus plastic-laminated alternatives. The Hamburg cluster integrates kraftliner specialization with on-site finishing partnerships for fragrance houses.
United Kingdom
London-based heritage brands drive demand for bespoke unboxing engineering with accelerated turnaround requirements. CSRD disclosure requirements mandate packaging circularity metrics documentation for listed cosmetics groups. British converters leverage fiber traceability certifications to capture audit-ready supply chain premiums from multinational beauty conglomerates.
Switzerland
Swiss fragrance and skincare houses prioritize tactile surface treatments as EU packaging weight directives constrain premium glass bottle heft signals. Swissmedic compliance frameworks align with REACH substance restrictions for cosmetic packaging materials. The Geneva-Zurich corridor hosts precision finishing specialists serving alpine heritage beauty brands.
Europe Luxury Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paperboard mills commanding fiber traceability premiums while artisan converters retain finishing craftsmanship margins. The vendor base organizes around three archetypes: integrated pulp-to-box operators securing supply chain transparency, regional rigid box specialists with heritage finishing capabilities, and multinational diversified packaging groups leveraging scale economies. Consolidation pressures concentrate among mid-tier converters facing REACH compliance cost escalation. Dominant competitive moves include backward integration into kraftliner production and strategic partnerships with cosmetics houses for co-developed refillable system engineering.
Among integrated paperboard operators, WestRock and Mondi exemplify the fiber-traceability archetype through captive mill networks. Smurfit Kappa occupies a position within the regional rigid box specialist tier with heritage European finishing capabilities. These three anchors demonstrate how scale and craftsmanship requirements create distinct competitive positioning vectors across the value chain.
| Leading Market Players |
|---|
| WestRock |
| Mondi |
| Amcor |
| Prestige Packaging Industries |
| McLaren Packaging |
| Smurfit Kappa |
| Crown Holdings |
| Graphic Packaging International |
| DS Smith |
| Others |
Supply & Pricing Matrix
Molded fiber tooling advances are compressing rigid box production economics while simultaneously redrawing supplier power toward integrated paperboard mills with captive pulp supply. This dual shift elevates fiber traceability premiums for cosmetics houses facing CSRD disclosure requirements while squeezing mid-tier converters dependent on spot-market kraftliner.
Pricing Analysis
Volume-mid economies separate from premium craftsmanship tiers. Three-tier pricing structure across premium, standard, and economy levels tracks customization intensity and certification grade. Cost compression in mid-tier rigid boxes intensifies because REACH compliance deadlines accelerate substrate transitions. Mass-market cosmetics buyers exhibit highest price sensitivity; heritage maisons in Paris and Milan demonstrate lowest sensitivity due to brand equity anchoring.
Supply Chain Analysis
Freight cost escalation from Nordic kraftliner mills to Paris and Milan converter clusters amplifies landed substrate premiums for non-integrated buyers. Supply concentrates in Sweden, Finland, and Germany for softwood pulp; France, Italy, and Germany for finishing craftsmanship. Raw material dependencies span bleached kraftliner, metallized films, and magnetic closure hardware. Single-source vulnerability concentrates in Northern Italian hot-stamping workshops with aging workforces. Distribution runs through direct mill partnerships for volume accounts and artisan converter networks for bespoke orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fiber traceability and finishing craftsmanship determines margin capture. Players are pursuing backward integration into kraftliner production to secure audit-ready supply chains under tightening EU circularity mandates.
For Market Incumbents: Cement fiber traceability advantages through captive mill investments or exclusive kraftliner offtake agreements with Nordic suppliers. Acquire distressed mid-tier converters in Paris and Milan clusters to lock in hot-stamping capacity before workforce attrition accelerates. Threat substitution from digital finishing technologies demands preemptive laser die-cutting deployment to maintain customization economics at lower volumes. For New Entrants and Emerging Players: Digital finishing automation offers entry into sub-five-thousand-unit production runs previously uneconomic for artisan converters. Target German fragrance houses expanding direct-to-consumer channels with drop-test certified molded fiber solutions bypassing traditional palletization. White-space concentrates in refillable fragrance system engineering where magnetic closure expertise creates recurring component demand. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational packaging groups seeking European finishing capabilities. Long-term viability favors integrated operators with captive fiber supply and CSRD-ready traceability documentation. Acquisition target archetype: regional rigid box specialists with established cosmetics house relationships and underutilized hot-stamping capacity. Signal to watch is ECHA substance evaluation timelines accelerating consolidation among REACH-noncompliant laminators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraftliner Production | Secures fiber traceability for CSRD-compliant cosmetics supply chains under EU Green Deal mandates. |
| Laser Die-Cutting System Deployment | Enables economic sub-five-thousand-unit runs for French fragrance houses fragmenting order profiles. |
| Refillable System Engineering Partnership | Creates recurring magnetic closure demand separate from consumable glass bottle cycles. |
| Artisan Converter Acquisition | Locks in scarce Northern Italian hot-stamping capacity facing workforce replenishment gaps. |
| Molded Fiber Architecture Pivot | Eliminates plastic window films while matching thermoformed tolerances for fragrance inserts. |
Research Methodology
Trade association filings, EU regulatory databases, and customs records formed the secondary backbone for substrate flow analysis. Primary interviews with rigid box converters, cosmetics packaging procurement leads, and kraftliner mill sales directors validated cost structure assumptions. Bottom-up triangulation across converter capacity utilization and top-down reconciliation against cosmetics house packaging spend estimates anchored volume projections.
Historical trendline analysis of rigid box order patterns and pulp price series informed growth trajectory modeling across the projection horizon. Segmentation dimensions spanned product type, material substrate, end-use vertical, and design style tier. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance deadline impacts and unboxing investment intensity. Industry-specific inputs included ECHA substance evaluation timelines and VerpackG fee modulation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp price volatility spikes and accelerated EU packaging weight directive enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Tipping Foils Market