
 Tipping Foils Market | 2026-2036
Tipping Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Tipping Foils Market Analytics
Buyer concentration among cosmetics and pharmaceutical contract packagers is consolidating as multinational brand owners reduce supplier panels to three-to-five approved vendors. Kurz leverages its vertical integration from holographic master origination to reel-to-reel coating, sustaining technology leadership in diffractive tipping foils. Tavani Oy anchors Nordic supply chains through specialized short-run capabilities for security and tax-stamp applications. Avery Dennison competes via global adhesive science platforms that extend into pressure-sensitive tipping constructions for variable-data labeling.
Tipping foils are thin metallized or pigmented transfer films, typically 12–25 micrometers in thickness, that release from a polyester carrier substrate onto paper, board, or plastic surfaces through hot-stamp or cold-foil processes to impart decorative or functional finishes. The primary commercial purpose is to simulate precious-metal aesthetics or embed security features without the weight, cost, or environmental burden of solid metal lamination. Polyester-based tipping foils occupy the mature volume tier across food packaging and general stationery, while polycarbonate variants command premium positioning in pharmaceutical blister lidding where chemical resistance and heat stability define specification compliance. BOPP substrates are gaining fastest in Asian flexible packaging conversions where moisture barrier and down-gauging priorities align with sustainability targets.
The U.S. Food and Drug Administration enforces indirect food-contact compliance under 21 CFR 177.1520 for olefin-based substrates used in tipping foils destined for food packaging, while the EPA monitors volatile organic compound emissions from solvent-based coating operations. The European Chemicals Agency implements REACH substance restrictions that affect pigment and adhesive formulations in decorative transfer films, altering raw-material qualification timelines. The EU F-Gas Regulation indirectly shapes foil manufacturing through compressed-gas propellant phase-outs in metallization chambers. Stakeholders must monitor evolving extended-producer-responsibility frameworks in major economies, as post-consumer recyclability of multi-layer foil-decorated packaging becomes a design-gate criterion rather than a downstream afterthought.
Market Dynamics
Cosmetics brand owners are consolidating approved vendor panels to three-to-five suppliers, compressing pricing power for mid-tier foil converters while rewarding vertically integrated holographic masters with reel-to-reel coating capabilities.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates for decorative substrates are accelerating qualification programs among German premium print finishing clusters serving central European supply chains.
- Pharmaceutical blister lidding specifications:Polycarbonate variants with chemical resistance and heat stability properties are capturing specification-driven demand from contract packagers.
- Asian flexible packaging down-gauging:BOPP substrates with moisture barrier properties are displacing conventional constructions in sustainability-aligned conversions.
Market Restraints
- Raw material qualification timelines:ECHA REACH substance restrictions on pigment and adhesive formulations extend development cycles for decorative transfer films by 12-18 months.
- Metallization chamber propellant phase-outs:EU F-Gas Regulation compressed-gas restrictions force capital retooling for vacuum deposition equipment.
- Multi-layer recyclability barriers:Extended-producer-responsibility frameworks in major economies are design-gating foil-decorated packaging where post-consumer separation remains uneconomical.
Strategic Opportunities
- Security and tax-stamp short-runs:Nordic supply chains present white space for specialized converters with holographic origination capabilities.
- Pressure-sensitive tipping constructions:Variable-data labeling applications converge adhesive science platforms with cold-foil transfer technologies.
- Indirect food-contact compliance:FDA 21 CFR 177.1520 olefin-based qualifications open pharmaceutical-adjacent food packaging segments.
Industry Challenges
- Holographic master origination talent scarcity:Diffractive design and electroforming expertise concentrates among aging specialist workforces in Germany and Austria.
- Solvent-based coating emission controls:EPA volatile organic compound monitoring demands continuous abatement investment without pass-through pricing power.
- Carrier substrate thickness standardization:12-25 micrometer polyester specifications fragment across hot-stamp versus cold-foil process lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tipping Foils Market |
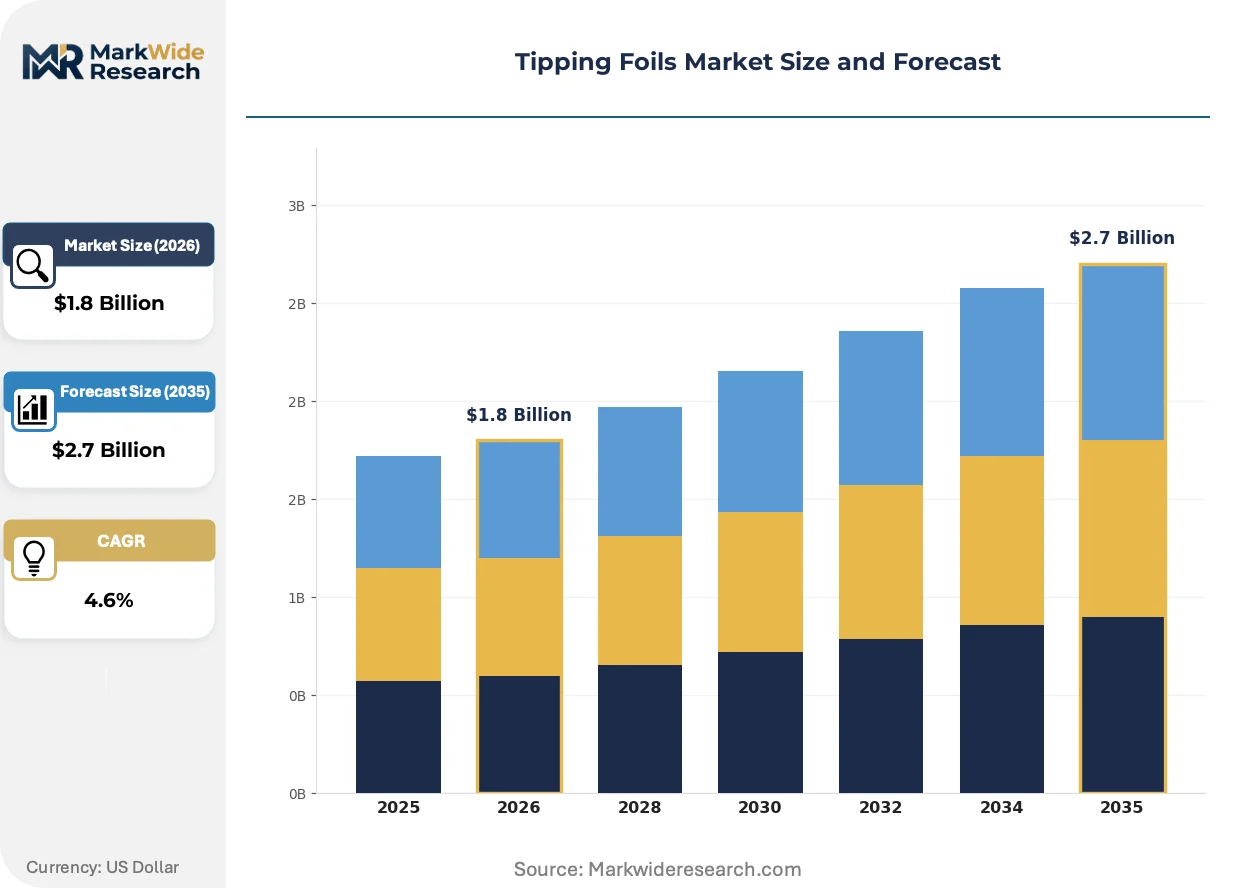
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polycarbonate, BOPP, PVC Application: Packaging, Labeling, Printing, Stationery End User: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics Sales Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Caxton Mark, Tavani Oy, Kurz, Capture Technologies, ITW Card Technologies, Zebra, Avery Dennison, UPM Raflatac, KROY LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tipping Foils Market Evolving Landscape
Digital print finishing and sustainability-driven substrate substitution are compressing traditional metallization volumes while expanding functional foil applications in authentication and smart packaging.
Cold-foil transfer technology is rewriting the economics of short-run decorative finishing. Brand owners in cosmetics and limited-edition consumer goods are adopting reel-to-reel cold foil at run lengths below 5,000 meters. This technology is compressing minimum order quantities and enabling versioning strategies that were previously uneconomical under hot-stamp tooling.
REACH substance restrictions are forcing pigment reformulation across decorative transfer films. ECHA enforcement of candidate list substances is disqualifying legacy colorants used in metallized and pigmented foils. Pharmaceutical blister lidding and food-contact applications are responding with accelerated qualification programs for alternative organic and inorganic pigment systems.
Vendor panel consolidation is shortening switching cycles for approved suppliers. Multinational brand owners in cosmetics and pharmaceuticals are unbundling decorative finishing from general print procurement. Germany and Austria are witnessing the fastest compression of supplier relationships as three-to-five approved vendor structures disperse specification authority to central European packaging development centers.
Tipping Foils Market Segmentation
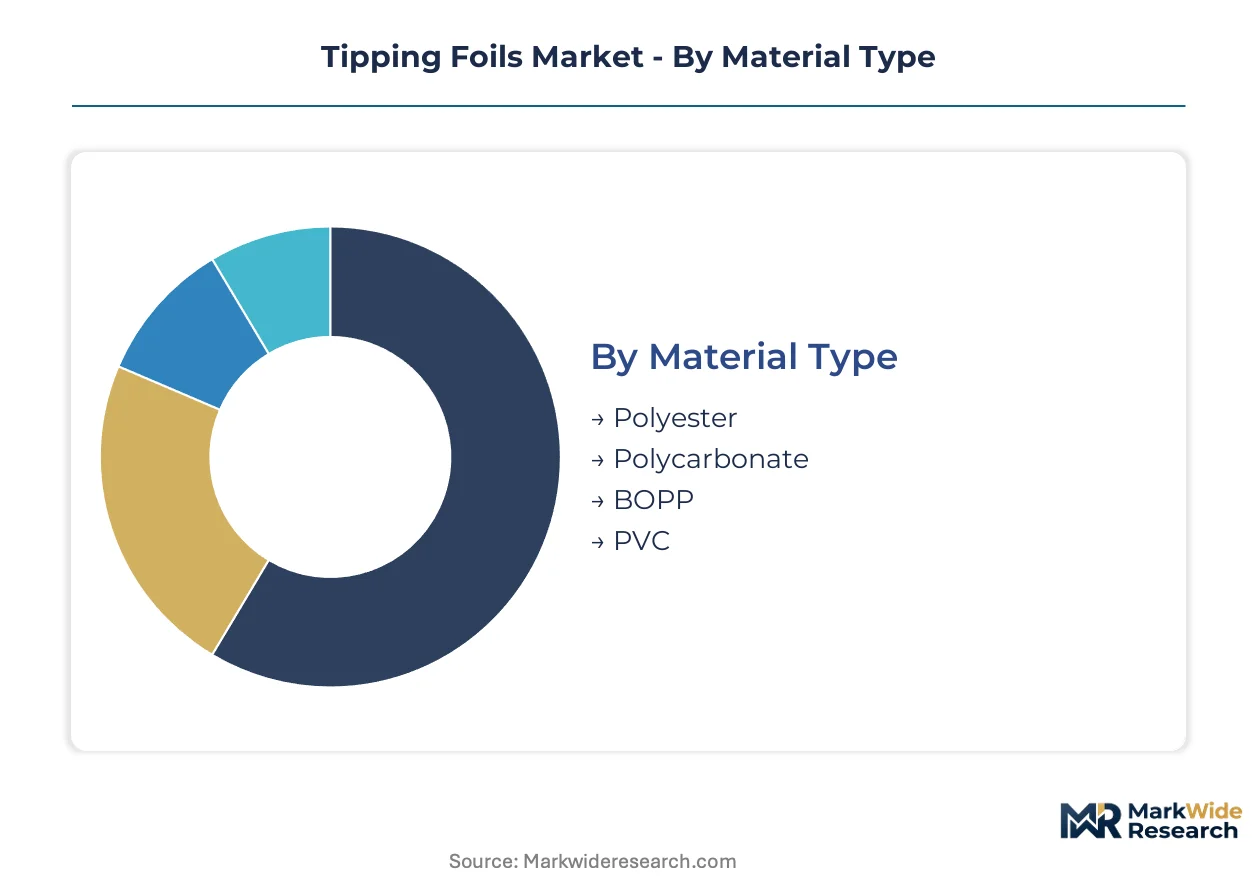
Segmentation in tipping foils reveals how certification burdens, substrate chemistry, and end-use specifications fragment procurement strategies. Brand owners in cosmetics and pharmaceuticals navigate distinct qualification pathways that reshape supplier relationships across each material and application tier.
Material Type:
FDA 21 CFR 177.1520 compliance for olefin-based substrates separates food-contact eligible materials from decorative-only grades, while ECHA REACH pigment restrictions hit metallized polyester hardest.
- Polyester:The 12-25 micrometer carrier substrate dominates volume across hot-stamp and cold-foil process lines. Demand concentrates in German premium print finishing clusters where reel-to-reel coating capabilities serve central European brand supply chains facing EU Packaging and Packaging Waste Regulation traceability mandates.
- Polycarbonate:Chemical resistance and heat stability specifications command premium positioning in pharmaceutical blister lidding. Contract packagers in Germany and Austria specify this grade for compliance with EMA stability requirements, though raw material qualification timelines extend 12-18 months under REACH substance restrictions.
- BOPP:Moisture barrier properties align with Asian flexible packaging down-gauging priorities.
- PVC:Legacy substrate facing displacement from sustainability-aligned conversions in European markets.
Polyester sits at the top of the volume ranking, with BOPP climbing the fastest.
Application:
Cold-foil transfer economics are rewriting run-length thresholds, compressing minimum order quantities below 5,000 meters for versioning strategies previously uneconomical under hot-stamp tooling.
- Packaging:Cosmetics brand owners expand foil-decorated programs to differentiate shelf presence. German clusters anchor specification authority as multinational owners consolidate vendor panels to three-to-five approved suppliers.
- Labeling:Pressure-sensitive constructions converge adhesive science platforms with variable-data capabilities. Demand from pharmaceutical serialization and tax-stamp applications concentrates in Nordic supply chains.
- Printing:Digital print finishing compresses traditional metallization volumes while expanding authentication applications.
- Stationery:Mature volume tier facing substrate substitution pressure from sustainability targets.
Packaging holds the revenue concentration, with labeling expanding most quickly.
End User:
Indirect food-contact compliance opens pharmaceutical-adjacent segments, while security feature integration differentiates cosmetics and electronics procurement.
- Cosmetics:Foil-decorated packaging programs drive specification authority toward central European packaging development centers. Brand owners unbundle decorative finishing from general print procurement, shortening switching cycles for approved suppliers.
- Pharmaceuticals:Blister lidding specifications demand polycarbonate variants with EMA-aligned stability profiles. Contract packager consolidation compresses pricing power for mid-tier converters.
- Food & Beverage:FDA 21 CFR 177.1520 olefin-based qualifications govern substrate selection.
- Electronics:Authentication and smart packaging applications emerging from holographic master origination capabilities.
Cosmetics leads specification-driven value, with pharmaceuticals showing steepest expansion trajectory.
Sales Channel:
Vendor panel consolidation favors direct relationships with vertically integrated holographic masters, while distributors serve fragmented short-run demand.
- Direct Sales:Vertically integrated suppliers with captive holographic origination and reel-to-reel coating capabilities capture multinational brand owner contracts. German and Austrian producers anchor these relationships through specialized electroforming expertise.
- Distributors:Channel serves mid-tier converters and regional stationery markets where specification complexity remains lower.
- Online Retail:Emerging channel for standardized polyester grades in small-format stationery and craft applications.
- Others:Includes agent-mediated procurement for security and tax-stamp applications in regulated markets.
Direct sales dominates premium segment value capture, with distributor relationships gaining share in standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Holographic master origination talent concentrates in German and Austrian electroforming workshops, anchoring premium specification authority for central European brand supply chains.
Germany
Cosmetics brand owners consolidate vendor panels to three-to-five approved suppliers, compressing pricing power for mid-tier converters. The EU Packaging and Packaging Waste Regulation tightens material traceability requirements for decorative substrates. Premium print finishing clusters in Bavaria and Baden-Württemberg serve multinational packaging development centers with reel-to-reel coating capabilities.
United States
FDA 21 CFR 177.1520 enforcement for olefin-based substrates governs food-contact eligibility in pharmaceutical-adjacent packaging segments. EPA volatile organic compound monitoring drives continuous abatement investment across solvent-based coating operations. Midwestern flexible packaging converters face design-gate pressure from emerging extended-producer-responsibility frameworks in California and New York.
China
BOPP substrate demand accelerates with flexible packaging down-gauging priorities aligned to sustainability targets. National standards under GB frameworks shape substrate chemistry qualification for export-oriented converters. Yangtze River Delta coating clusters supply Asian brand owners with moisture-barrier constructions displacing conventional metallized grades.
Japan
Authentication and smart packaging applications emerge from holographic master capabilities serving electronics brand owners. METI industrial policy supports substrate substitution research for multi-layer recyclability compliance. Kansai region converters specialize in short-run security applications with diffractive finishing technologies.
India
Pharmaceutical contract packager consolidation creates specification-driven demand for polycarbonate blister lidding variants. BIS standards govern substrate quality benchmarks for domestic and export markets. Gujarat and Maharashtra flexible packaging corridors attract investment in cold-foil transfer capacity for cosmetics versioning strategies.
Tipping Foils Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented supply tiers. The vendor base separates into three strategic archetypes: vertically integrated holographic masters with captive electroforming capabilities, adhesive science platforms extending into pressure-sensitive constructions, and regional short-run specialists serving security applications. Dominant competitive moves include M&A-driven consolidation of approved supplier panels and geographic expansion through qualification programs aligned to EU traceability mandates.
Among Germany-based specialists, Kurz occupies a position exemplifying integrated holographic origination through reel-to-reel coating capabilities. Tavani Oy anchors Nordic supply chain representation for security and tax-stamp short-run applications. Avery Dennison sits within the adhesive science platform tier, extending pressure-sensitive expertise into variable-data labeling constructions.
| Leading Market Players |
|---|
| Caxton Mark |
| Tavani Oy |
| Kurz |
| Capture Technologies |
| ITW Card Technologies |
| Zebra |
| Avery Dennison |
| UPM Raflatac |
| KROY LLC |
| Others |
Value Network & Pricing Analysis
Backward integration into holographic master origination and reel-to-reel coating capabilities anchors pricing power for German and Austrian producers serving EU Packaging and Packaging Waste Regulation traceability mandates. Captive electroforming expertise insulates premium-grade suppliers from commodity polyester pricing cycles while compressing margins for mid-tier converters lacking in-house metallization capacity.
Pricing Analysis
Capacity additions in Asian BOPP coating corridors are reshaping price floors for moisture-barrier grades displacing conventional metallized constructions. Three-tier pricing structure across premium polycarbonate, standard polyester, and economy PVC levels reflects certification-grade differentiation under FDA 21 CFR 177.1520 and EMA stability requirements. Cost compression in commodity hot-stamp foils intensifies because cosmetics brand owners consolidated vendor panels to three-to-five approved suppliers. Pharmaceutical contract packagers show least price sensitivity given 12-18 month qualification timelines for blister lidding specifications.
Supply Chain Analysis
Single-source vulnerability sits with German electroforming workshops supplying diffractive master origination expertise for security and authentication applications. Manufacturing gravity centers on Germany, Austria, and China, with raw material flows drawing from polyester resin producers, vacuum metallization equipment fabricators, and REACH-compliant pigment specialists. Tariff exposure runs through EU F-Gas Regulation compressed-gas propellant restrictions forcing capital retooling. Distribution runs through direct relationships with vertically integrated holographic masters for multinational brand owners, while regional distributors serve fragmented short-run stationery demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through substrate substitution toward BOPP and polycarbonate premium tiers, offsetting commodity polyester price erosion. Cold-foil transfer technology compresses minimum order quantities below 5,000 meters, enabling versioning economics that widen spread capture.
For Market Incumbents: Acquire electroforming and holographic origination talent pools to defend against emerging digital print finishing substitutes. Consolidate reel-to-reel coating capacity in Bavaria and Baden-Württemberg clusters to capture EU traceability mandate-driven specification authority. Investment in REACH-compliant pigment qualification programs extends development cycle moats against mid-tier competitors.
For New Entrants and Emerging Players: Enter via Nordic security and tax-stamp short-run applications where Tavani Oy anchors limited specialist supply. Target Indian pharmaceutical contract packager consolidation creating polycarbonate blister lidding demand in Gujarat and Maharashtra corridors. Lead with cold-foil transfer service capabilities priced below hot-stamp tooling thresholds for cosmetics versioning strategies.
For Investors and Strategic Acquirers: Consolidation pressure builds where vendor panel compression eliminates sub-scale converters lacking holographic master capabilities. Five-to-ten year viability favors adhesive science platforms extending into pressure-sensitive variable-data labeling or backward-integrated metallization operations. Watch cold-foil adoption rates in Asian flexible packaging as inflection signal for substrate mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Holographic Origination | Captive electroforming expertise insulates German producers from commodity pricing cycles. |
| Cold-Foil Transfer Capacity Expansion | Enables versioning economics below 5,000 meter run lengths for cosmetics brand owners. |
| REACH-Compliant Pigment Qualification | Accelerates development timelines for pharmaceutical blister lidding applications. |
| BOPP Substrate Manufacturing Scale-Up | Aligns with Asian flexible packaging down-gauging and sustainability priorities. |
| Direct Sales Channel Deepening | Captures multinational vendor panel consolidation toward three-to-five approved suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with foil converter plant managers, cosmetics packaging development directors, pharmaceutical contract packager procurement leads, and holographic origination specialists informed demand-side dynamics. Secondary validation drew from ECHA REACH candidate list updates, FDA 21 CFR guidance documents, EU Packaging and Packaging Waste Regulation drafts, and SEC filings from listed materials companies. Bottom-up volume modeling triangulated against top-down spending estimates across the analysis window.
Historical reference periods anchored projections across material type, application, end user, and sales channel dimensions. Modeled variables included substrate chemistry migration patterns, cold-foil versus hot-stamp process adoption curves, and vendor panel consolidation rates. CAGRs derived from segment-level growth rate distributions applied to base-period value estimates. Industry-specific inputs encompassed EMA stability requirement compliance timelines and EU F-Gas Regulation equipment retooling cycles.
Inputs from regulatory filings and industry association disclosures were available through the study window; gaps in real-time vendor panel composition data introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding REACH substance restriction enforcement timing and cold-foil technology diffusion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Cannabis Packaging Market