
 Gift Boxes Market | 2026-2036
Gift Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Gift Boxes Market Analysis
Asset-light contract manufacturing and third-party packaging outsourcing is rewriting competitive dynamics for mid-tier gift box suppliers. GPA Global leverages flexible production partnerships to serve multinational cosmetics clients without fixed plant commitments. PakFactory anchors its position through digital-first custom ordering platforms that compress design-to-delivery cycles. Taylor Box Company differentiates via artisan rigid-box craftsmanship targeting premium spirits and jewelry houses.
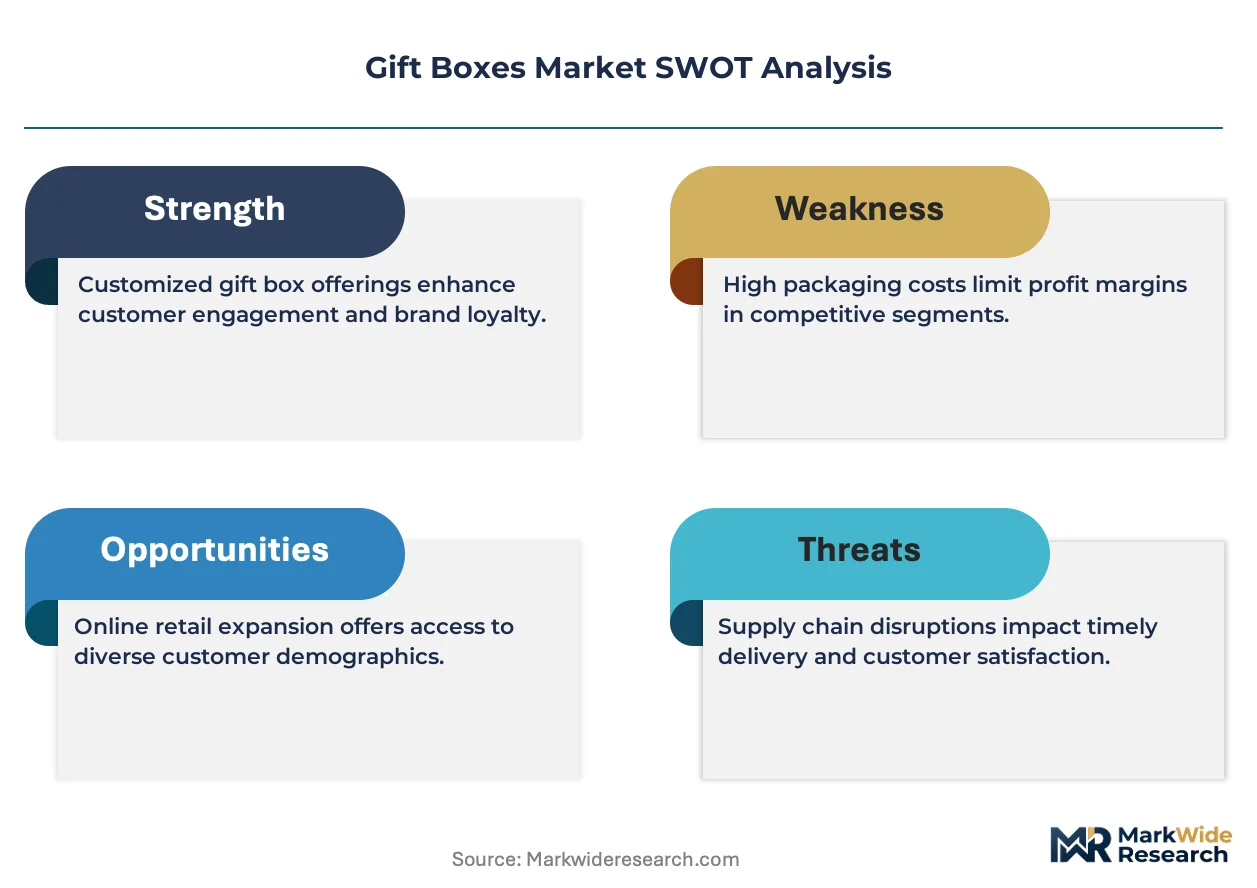
Gift boxes are engineered enclosures combining structural board, decorative substrates, and closure mechanisms to protect and present consumer goods during gifting occasions. Folding cartons dominate volume due to flat-pack shipping efficiency and automated assembly compatibility, while rigid boxes command margin pools in luxury segments where compression strength and tactile finish determine perceived value. Specialty boxes incorporating magnetic closures, ribbon pulls, or embedded electronics represent the fastest-expanding category as experiential unboxing content drives social media engagement. Eco-friendly design styles are maturing from niche positioning to baseline procurement requirements as corporate end users embed sustainability into vendor scorecards.
US EPA guidelines on recycled content thresholds and California's extended producer responsibility framework shape material sourcing decisions for North American suppliers. EU REACH restrictions on heavy metals in printing inks and the F-Gas Regulation's indirect pressure on plastic polymer feedstock costs constrain formulation choices. Stakeholders must monitor how China's GB standards on food-contact packaging migrate into cosmetic and confectionery gift box specifications, as this regulatory convergence will determine which converters retain cross-category production licenses.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's recyclability mandates are compressing design cycles and forcing converters to revalidate material stacks across all export-bound production lines.
Growth Catalysts
- Luxury Cosmetics Unboxing Investment:Premium beauty houses are commissioning rigid boxes with magnetic closures and ribbon pulls to generate social media engagement and repeat purchase intent.
- REACH Ink Restrictions:Heavy metal limitations in EU printing formulations are accelerating water-based and UV-curable ink adoption among compliance-focused exporters.
- Yangtze River Delta Cluster:China's concentrated board substrate and die-cutting capacity enables rapid prototyping for Western brand owners seeking compressed design-to-delivery timelines.
Market Restraints
- Pulp Price Volatility:Structural board input costs fluctuate with Nordic and Brazilian pulp supply disruptions, squeezing converter margins on fixed-price annual contracts.
- Single-Region Substrate Dependency:Recycled linerboard supply concentrates in Guangdong province mills, creating vulnerability to China's environmental inspection shutdowns.
- Polymer Feedstock Pressure:The EU F-Gas Regulation indirectly elevates plastic window film and lamination costs for transparent gift box windows.
Strategic Opportunities
- India Premium Gifting Expansion:Metro tier-1 consumers in Mumbai and Delhi are adopting Western-style rigid box formats for wedding and festival gifting, outpacing local folding carton supply.
- Extended Producer Responsibility Tailwinds:California's EPR framework creates first-mover advantage for converters with certified post-consumer recycled content above EPA guideline thresholds.
- Embedded NFC-Printed Electronics Convergence:Near-field communication chips combined with conductive ink antennae enable authenticated unboxing experiences for spirits and jewelry houses.
Industry Challenges
- Artisan Rigid Box Skill Scarcity:Hand-wrapped corner and edge finishing techniques require multi-year apprenticeship pipelines that automated production cannot replicate.
- Cross-Category GB Standard Migration:China's food-contact packaging specifications are expanding into cosmetic and confectionery gift boxes, forcing dual-licensing investments from multi-category converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gift Boxes Market |
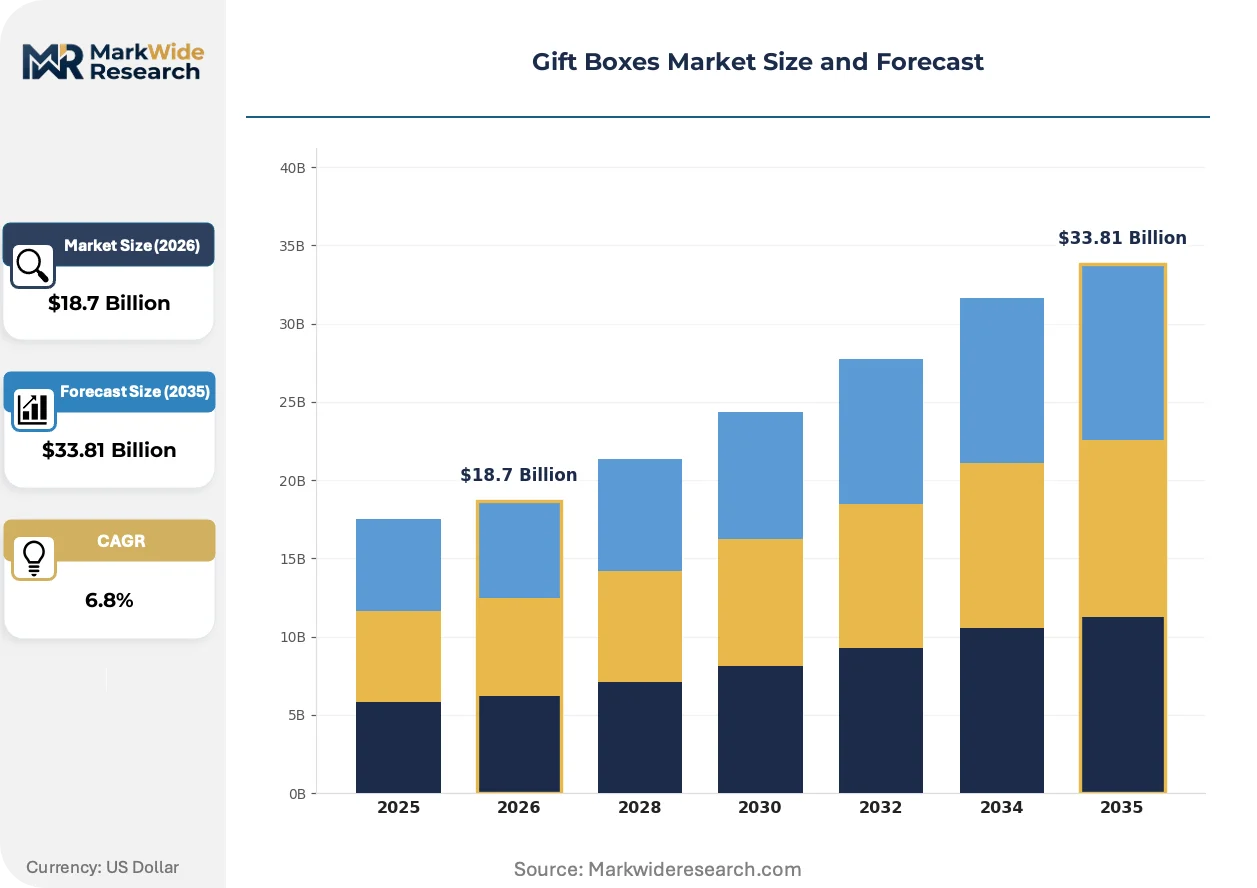
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Folding Cartons, Rigid Boxes, Corrugated Boxes, Specialty Boxes Material: Paper, Plastic, Wood, Metal End User: Retailers, E-commerce, Event Planners, Corporations Design Style: Minimalist, Luxurious, Thematic, Eco-friendly |
| Companies Covered | PakFactory, Ardagh, GPA Global, Shanghai Chenfen Packaging Co., Ltd., Jinguan Printing & Packaging, Amcor, Owens-Illinois, Taylor Box Company, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gift Boxes Market Emerging Trajectories
Experiential unboxing content creation is rewiring gift box engineering priorities, with structural features now designed for camera capture rather than shelf presence alone.
Magnetic closure systems are migrating from ultra-premium jewelry boxes into mid-tier cosmetics and spirits packaging as Chinese component suppliers achieve scale economies on neodymium hinge assemblies. Mass-market fragrance brands are adopting these mechanisms at volume tiers previously served by tuck-end folding cartons. This migration from luxury-exclusive to mainstream deployment is compressing the premiumization timeline for closure innovation.
The EU Packaging and Packaging Waste Regulation's 2030 recyclability targets are forcing laminate separation redesigns across export-bound production. Multi-layer PET film windows must now detach cleanly from paperboard substrates to qualify for single-stream recycling. German and French cosmetic houses are responding by specifying mono-material PET or cellulose-based transparent windows.
Corporate sustainability scorecards are embedding packaging into vendor evaluation rubrics with quantitative weighting. Procurement teams at multinational CPG firms now score gift box suppliers on certified recycled content, carbon disclosure, and end-of-life recyclability. This behavioral shift is most pronounced in North American and Western European headquarters procurement functions, where ESG-linked supplier financing accelerates compliant converter selection.
Gift Boxes Market Segmentation
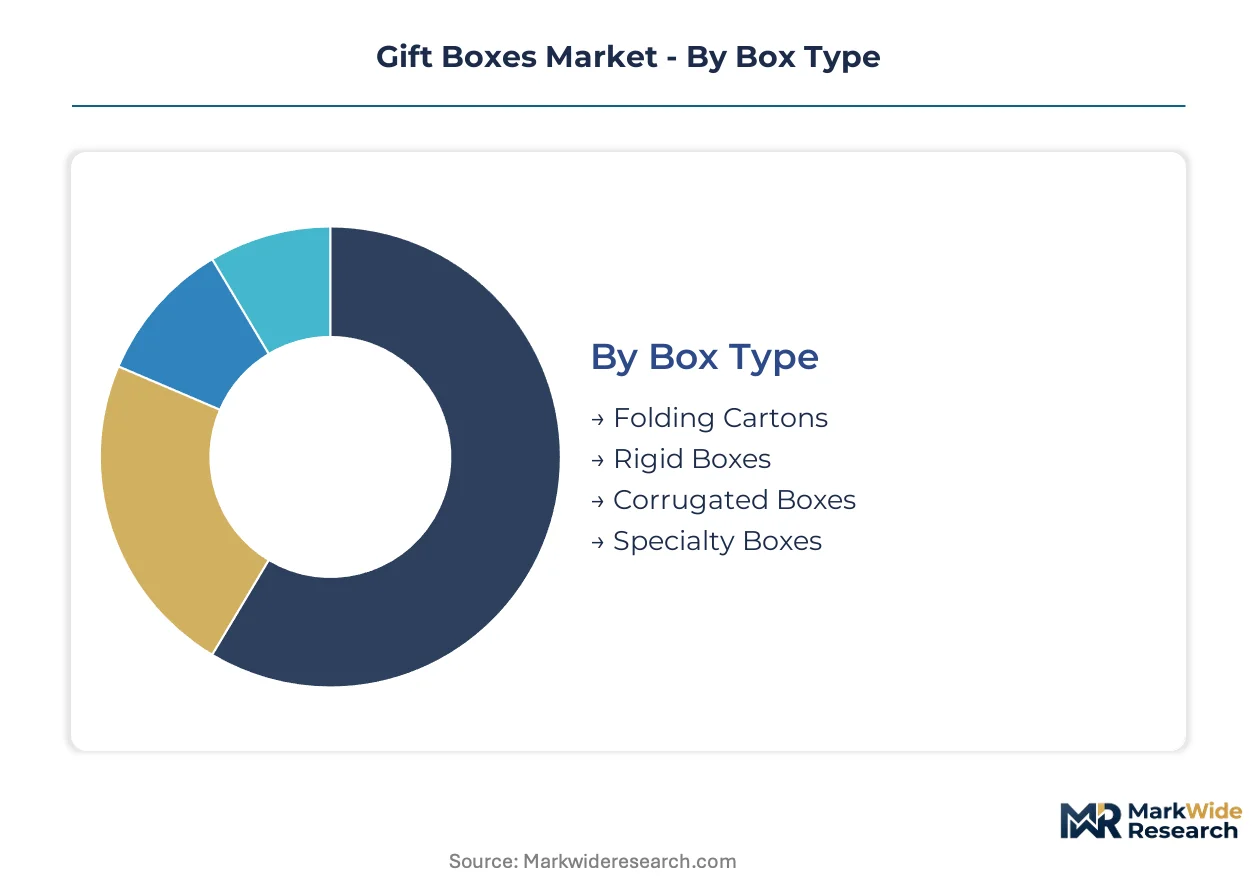
Gift box segmentation reveals how engineering priorities diverge across price tiers and unboxing contexts. Structural choices in box type and material directly determine which suppliers capture volume contracts versus margin-rich premium assignments.
Box Type:
Mature formats dominate volume flows while emerging constructions capture experiential marketing budgets.
- Folding Cartons:Single-piece paperboard structures with creased fold lines enable flat-pack shipping and high-speed automated assembly. Demand concentrates in mass-market cosmetics and confectionery segments where e-commerce fulfillment cost efficiency overrides structural rigidity.
- Rigid Boxes:Wrapped chipboard or greyboard enclosures with separate base and lid components deliver compression strength and tactile surface finish for premium spirits and jewelry presentations. The Yangtze River Delta cluster supplies neodymium magnetic closures that accelerate adoption in mid-tier fragrance brands.
- Corrugated Boxes:Fluted medium sandwiched between linerboards provides cushioning for fragile electronics and glassware shipments.
- Specialty Boxes:Engineered constructions incorporating ribbon pulls, embedded electronics, or unique opening mechanisms target social media unboxing content creation.
Folding cartons retain volume leadership; specialty boxes hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity substrates from certified sustainable alternatives commanding procurement premiums.
- Paper:Recycled linerboard and virgin pulp substrates form the structural core of folding cartons and rigid box wrappers. EU REACH restrictions on heavy metal inks are accelerating water-based formulation adoption among European-exporting converters.
- Plastic:PET window films and polypropylene lamination layers provide transparency and moisture barrier properties. California's extended producer responsibility framework is elevating post-consumer recycled content requirements for North American supply.
- Wood:Solid timber and veneer constructions serve ultra-premium spirits and cigar packaging where natural grain patterns signal craftsmanship.
- Metal:Tinplate and aluminum substrates enable decorative embossing and extended shelf-life protection for luxury confectionery.
Paper substrates command absolute volume; plastic alternatives face the most acute regulatory pressure.
End User:
Customer type determines order cadence, customization depth, and sustainability certification requirements.
- Retailers:Department stores and specialty chains require seasonal design refreshes with rapid replenishment cycles for holiday gifting peaks.
- E-commerce:Direct-to-consumer brands prioritize ship-flat efficiency and damage-resistant construction for last-mile delivery.
- Event Planners:Wedding and corporate event coordinators commission bespoke rigid boxes with personalized finishing for guest favors.
- Corporations:Multinational CPG and technology firms embed packaging into vendor ESG scorecards with quantitative recycled content thresholds.
E-commerce channels drive the fastest order volume expansion; corporate procurement enforces the most stringent compliance frameworks.
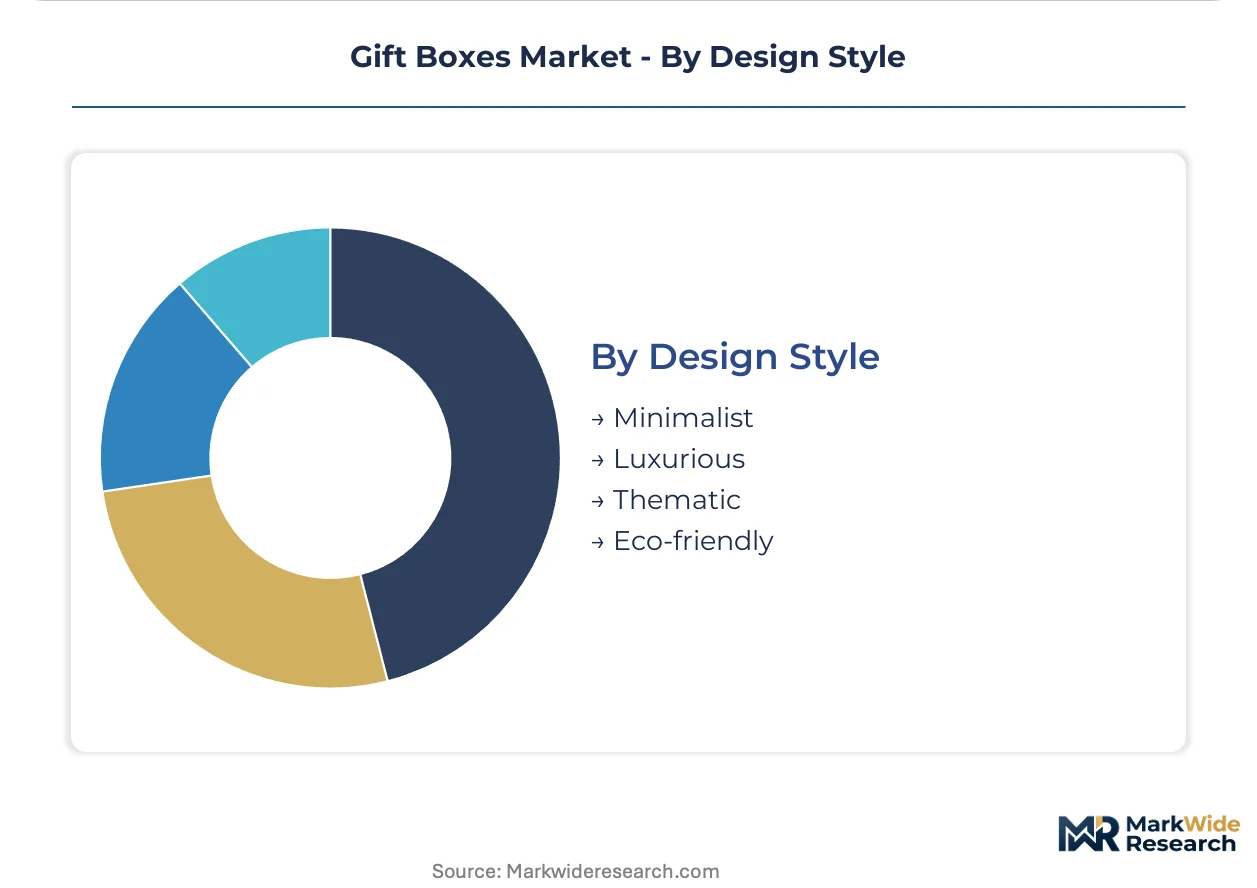
Design Style:
Margin pools concentrate where aesthetic differentiation aligns with sustainability credentials.
- Minimalist:Unprinted kraft surfaces and structural simplicity reduce ink usage and align with Scandinavian retail aesthetics.
- Luxurious:Foil stamping, velvet flocking, and magnetic closures target premium beauty and spirits unboxing experiences.
- Thematic:Seasonal illustrations and licensed character artwork serve holiday confectionery and children's product segments.
- Eco-friendly:Mono-material constructions and certified recycled content meet corporate procurement sustainability mandates.
Luxurious styling captures the highest per-unit margins; eco-friendly specifications are becoming baseline procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's extended producer responsibility framework and the EU Packaging and Packaging Waste Regulation are accelerating regional divergence in material compliance requirements. Brand owners now route orders through converters with certified recycling credentials matched to destination markets.
United States
E-commerce fulfillment demand from direct-to-consumer cosmetics brands drives folding carton volume in New Jersey and Pennsylvania logistics corridors. The EPA's recycled content guidelines shape procurement scorecards for multinational CPG firms headquartered in Chicago and Minneapolis. California's EPR mandates create first-mover advantage for converters with post-consumer certified substrate supply.
China
Luxury unboxing investments from domestic beauty houses expand rigid box demand beyond export production. GB standards on food-contact packaging migrate into cosmetic and confectionery specifications, forcing dual-licensing investments. The Yangtze River Delta cluster concentrates die-cutting capacity and neodymium magnetic closure assembly for Western brand owners.
Germany
REACH restrictions on heavy metal printing inks accelerate water-based formulation adoption among exporters serving EU cosmetic houses. The Packaging and Packaging Waste Regulation's 2030 recyclability targets force laminate separation redesigns for transparent window boxes. Bavarian converters specialize in mono-material PET window films for French and Italian luxury clients.
India
Metro tier-1 consumers in Mumbai and Delhi adopt Western-style rigid box formats for wedding and festival gifting. BIS standards on packaging materials create compliance thresholds for imported substrate converters. Gujarat's Ahmedabad-Surat corridor develops folding carton capacity to serve domestic e-commerce expansion.
Japan
Premium spirits and confectionery brands sustain artisan rigid box demand for seasonal gifting peaks. METI guidelines on plastic resource circulation elevate paper-based mono-material specifications. The Kansai region's Osaka-Kobe industrial zone maintains specialized craftsmanship clusters for hand-finished luxury packaging.
Gift Boxes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price bands. Consolidation pressure concentrates among mid-tier converters facing pulp cost volatility and fixed-price contract exposure. Three archetypes dominate: asset-light contract manufacturers leveraging flexible production partnerships, digital-first custom ordering platforms compressing design cycles, and artisan craftsmanship houses serving premium spirits and jewelry segments. Competitive moves center on strategic partnerships with multinational brand owners and geographic expansion into India's premium gifting corridor.
Within the asset-light manufacturing tier, GPA Global exemplifies flexible production partnerships without fixed plant commitments. Taylor Box Company occupies a position among artisan rigid-box specialists targeting premium market segments. PakFactory anchors the digital-first archetype through custom ordering platforms that accelerate design-to-delivery timelines. Shanghai Chenfen Packaging Co., Ltd. and Jinguan Printing & Packaging represent Chinese converters with concentrated capacity in the Yangtze River Delta cluster.
| Leading Market Players |
|---|
| PakFactory |
| Ardagh |
| GPA Global |
| Shanghai Chenfen Packaging Co., Ltd. |
| Jinguan Printing & Packaging |
| Amcor |
| Owens-Illinois |
| Taylor Box Company |
| Crown Holdings |
| Others |
Supply Flow & Price Mechanics
Single-region substrate dependency in Guangdong province mills determines both margin compression patterns and converter sourcing strategies across the gift box value chain. Pulp price volatility from Nordic and Brazilian supply disruptions squeezes fixed-price contract profitability while forcing tiered pricing stratification between spot-market and long-term offtake buyers.
Pricing Analysis
Certification level creates the primary spread across gift box procurement tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with FSC-certified recycled content and REACH-compliant ink formulations commanding procurement premiums from EU-exporting converters. Price differentiation stems from magnetic closure complexity and substrate grade, with artisan rigid-box finishing capturing the widest spreads. Cost compression in mid-tier folding cartons is intensifying because pulp input volatility erodes fixed-annual-contract margins. Corporate procurement teams demonstrate lowest price sensitivity for certified sustainable specifications, while mass-market e-commerce brands prioritize ship-flat efficiency over tactile finish.
Supply Chain Analysis
Nordic and Brazilian pulp feedstock anchors structural board production for folding carton and rigid box substrates. China's Yangtze River Delta cluster, Germany's Bavarian converter belt, and India's Gujarat corridor concentrate die-cutting and magnetic closure assembly capacity. Raw material dependencies span recycled linerboard from Guangdong mills, neodymium hinge components from Chinese suppliers, and water-based ink formulations from EU-compliant chemical producers. Single-source vulnerability concentrates in recycled linerboard supply subject to China's environmental inspection shutdowns. Distribution runs through brand-owner direct procurement for multinational cosmetics houses and tiered distributor networks serving regional e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping gift box procurement as digital-first custom ordering interfaces displace traditional converter relationships. Interoperability between design-to-delivery platforms and brand-owner ERP systems is compressing specification cycles and rewiring vendor selection criteria.
For Market Incumbents: Harden compliance infrastructure against REACH ink restrictions and California EPR mandates to defend multinational contracts from emerging digital-native competitors. Deepen backward integration into certified recycled substrate supply to offset pulp price volatility exposure. Anchor capacity in the Yangtze River Delta cluster to maintain rapid prototyping advantages for Western brand owners.
For New Entrants and Emerging Players: Establish a beachhead in India's premium wedding and festival gifting corridor where Western-style rigid box demand outpaces local supply. Target embedded NFC-printed electronics convergence for authenticated unboxing experiences in spirits and jewelry segments. Deploy asset-light contract manufacturing partnerships to serve cosmetics clients without fixed plant commitments.
For Investors and Strategic Acquirers: California's extended producer responsibility framework reshapes the acquisition landscape by elevating certified post-consumer recycled content thresholds as a viability filter. Focus on converters with dual-licensing readiness for China's migrating GB standards across food-contact and cosmetic packaging categories. Watch magnetic closure component scale economies as the signal indicating which mid-tier suppliers can sustain margin pressure from premium-format migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | PakFactory's custom ordering interface compresses design-to-delivery cycles for direct-to-consumer cosmetics brands. |
| Certified Substrate Backward Integration | Converters with FSC-certified recycled linerboard supply capture California EPR procurement premiums. |
| Magnetic Closure Scale Partnerships | Neodymium hinge assembly economies from Yangtze River Delta suppliers enable mid-tier fragrance adoption. |
| Dual-Licensing Compliance Investment | GB standard migration into cosmetic packaging forces multi-category converters to retain cross-sector licenses. |
| Embedded NFC Electronics Development | Conductive ink antennae convergence creates authenticated unboxing differentiation for luxury spirits houses. |
Methodological Framework
The analysis maps folding carton, rigid box, corrugated, and specialty box sub-sectors, each validated through procurement directors at multinational CPG firms, converter operations managers, and magnetic closure component suppliers. Primary interviews with brand packaging strategists and e-commerce fulfillment planners combined with secondary validation from EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation filings, and China GB standard migration notices. Bottom-up shipment data from Yangtze River Delta cluster capacity and top-down demand modeling from corporate sustainability scorecard weightings were triangulated for segment sizing.
Assumptions held fixed include EU REACH ink restriction enforcement timelines and California EPR framework implementation scope, while pulp price volatility bands and Chinese environmental inspection frequency were stress-tested across scenarios. The analytical framework models box type, material substrate, end-user channel, and design style segmentation dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating luxury cosmetics unboxing investment trajectories and e-commerce fulfillment expansion patterns.
Stress conditions across Nordic pulp supply disruptions, neodymium magnet export restrictions, and REACH formulation compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory acceleration in China's GB standard migration and corporate ESG procurement mandate timing. Cross-checking against customs records for recycled linerboard trade flows and magnetic closure component shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Child Resistant Packaging Market