
 Europe Child Resistant Packaging Market | 2026-2036
Europe Child Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Child Resistant Packaging Market Analytics
REACH is consolidating the supplier landscape by elevating compliance costs for non-EU substrate imports. Gerresheimer AG anchors its position through captive glass-forming capacity for pharmaceutical vials with integrated child-resistant closures. Berry Global differentiates via blow-molded HDPE bottles engineered to ISO 8317 push-turn standards. Constantia Flexibles competes in high-barrier blister foils where tamper-evidence and child-resistance must coexist.
Europe child resistant packaging denotes engineered containers, closures, and blisters requiring coordinated dual-action or strength-mediated mechanisms to restrict access by children under 52 months while maintaining adult usability, typically validated against EN 862 or ISO 8317 protocols. Blister packs lead value contribution due to unit-dose pharmaceutical dispensing and senior-friendly accessibility mandates, while paperboard cartons gain share as brands eliminate secondary plastic wraps under EU Green Deal commitments. Plastic retains volume dominance across screw caps and snap closures, though glass bottles command premium positioning in biologics and ophthalmic segments where inert contact surfaces are non-negotiable.
EMA pharmacovigilance requirements and the EU Packaging and Packaging Waste Regulation jointly determine format acceptance and material eligibility across member states. Germany's Federal Institute for Drugs and Medical Devices enforces additional testing rigor that shapes product development priorities for suppliers targeting Central European distribution. France's ANSM maintains parallel notification pathways for novel closure mechanisms, creating a dual-gatekeeping environment. Stakeholders must monitor the forthcoming harmonized Extended Producer Responsibility frameworks, as these will recalibrate cost allocation between packaging converters and pharmaceutical marketers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation revision is compressing format development cycles, forcing converters to validate mono-material alternatives before 2030 recyclability mandates take effect. This regulatory compression is reshaping supplier R&D priorities across pharmaceutical and household chemical segments.
Growth Catalysts
- EMA pharmacovigilance expansion:Post-market surveillance requirements now mandate unit-dose traceability, driving pharmaceutical manufacturers toward serialized blister formats with integrated child-resistant features.
- Biologics cold-chain growth:Temperature-sensitive protein therapies require glass vial systems with tamper-evident child-resistant closures, creating premium demand in Germany's contract packaging corridor.
- France ANSM notification acceleration:Streamlined approval pathways for novel closure mechanisms are shortening time-to-market for push-turn innovations targeting senior-accessibility mandates.
Market Restraints
- Glass supply concentration:Borosilicate tubing for pharmaceutical vials depends on a narrow supplier base in Central Europe, exposing packagers to input volatility.
- REACH compliance escalation:Substance restriction updates are disqualifying legacy plasticizers and coatings, forcing reformulation of established closure compounds.
- Multi-material recycling incompatibility:Current child-resistant blister formats combining PVC, aluminum, and paperboard face sorting infrastructure limitations across member state waste systems.
Strategic Opportunities
- Poland contract packaging expansion:Central European pharmaceutical manufacturing migration is creating demand for local child-resistant conversion capacity serving export markets.
- Fiber-based carton integration:Paperboard formats with mechanical locking mechanisms are capturing share from plastic secondary packaging under EU Green Deal commitments.
- Smart closure convergence:NFC-enabled caps combining child-resistance with adherence monitoring are opening reimbursement pathways in digital therapeutics.
Industry Challenges
- ISO 8317 testing bottleneck:Certified laboratory capacity for pediatric panel testing is concentrated in Germany and the UK, extending validation timelines for novel designs.
- Legacy equipment retrofit costs:Converting thermoforming lines for mono-material blister formats requires substantial capital outlay with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Child Resistant Packaging Market |
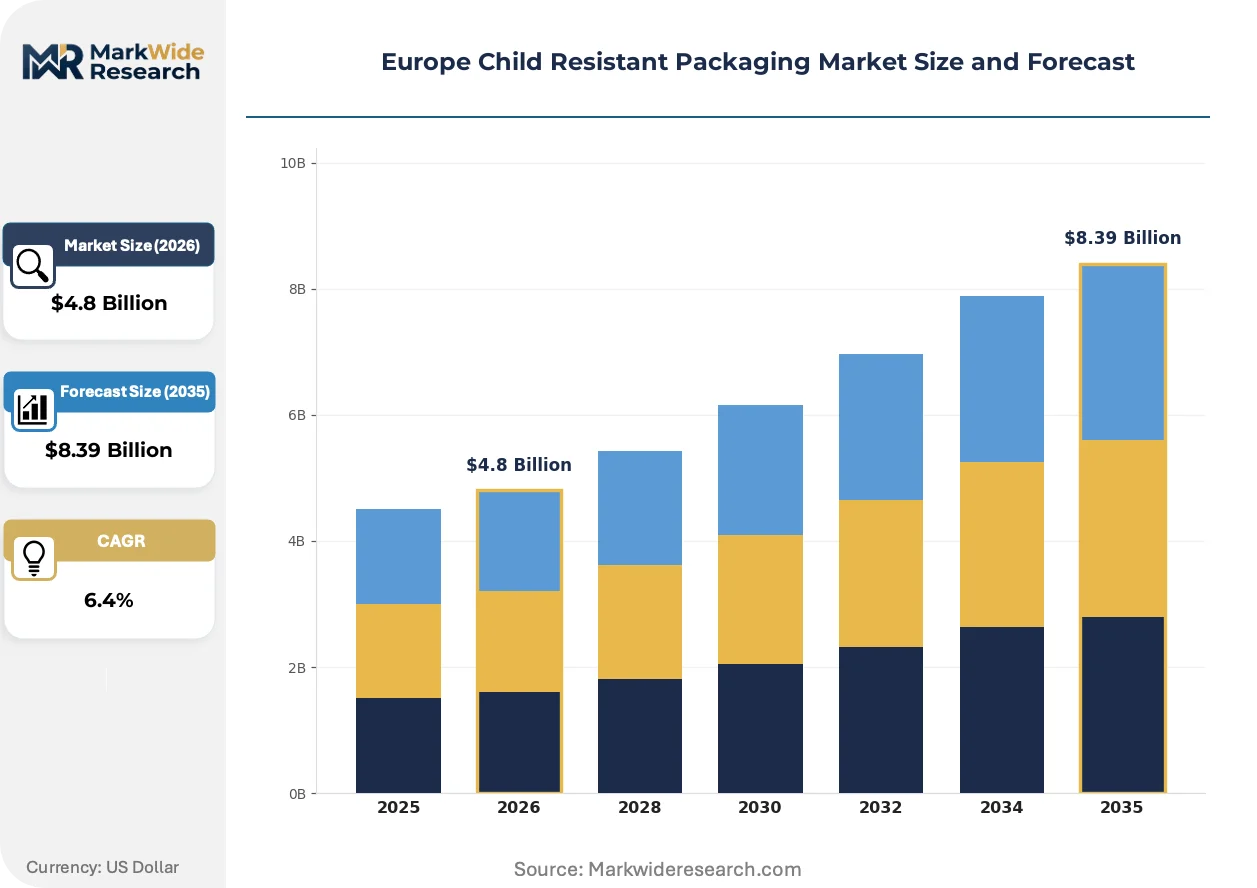
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Bottles, Blister Packs, Cartons Material: Plastic, Glass, Metal, Paperboard Closure Type: Screw Caps, Push-Pull Caps, Snap Closure, Child Resistant Lids End User: Pharmaceuticals, Cosmetics, Household Products, Food |
| Companies Covered | Amcor plc, Gerresheimer AG, Berry Global, AptarGroup, WestRock Company, Constantia Flexibles, ALPLA Group, Closure Systems International, Schott AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Child Resistant Packaging Market Evolving Landscape
Material science advances and regulatory pressure are converging to redefine acceptable performance standards. The market is witnessing accelerated substitution of multi-layer structures with validated mono-material alternatives.
Mono-polyethylene blister films are expanding into unit-dose pharmaceutical packaging, replacing PVC-PVDC-aluminum laminates. German generic drug manufacturers are adopting these formats at scale to meet recyclability targets. This transition is expanding into high-barrier applications previously reserved for multi-material systems, compressing the addressable market for conventional foil structures.
REACH substance restriction updates are eliminating phthalate-based plasticizers from closure compounds. Industrial consequence includes accelerated qualification of bio-based alternatives in polypropylene screw caps. France's ANSM maintains the strictest migration testing protocols, making it the proving ground for compliant reformulations before broader EU deployment.
Pharmaceutical procurement is consolidating contract packaging relationships around full-service providers with integrated testing capabilities. Small and mid-size drug marketers are abandoning fragmented supplier networks in favor of partners offering EN 862 validation, serialization, and distribution under single accountability. This concentration is most visible in the UK's post-Brexit regulatory environment, where domestic testing capacity has become a decisive selection criterion.
Europe Child Resistant Packaging Market Segmentation
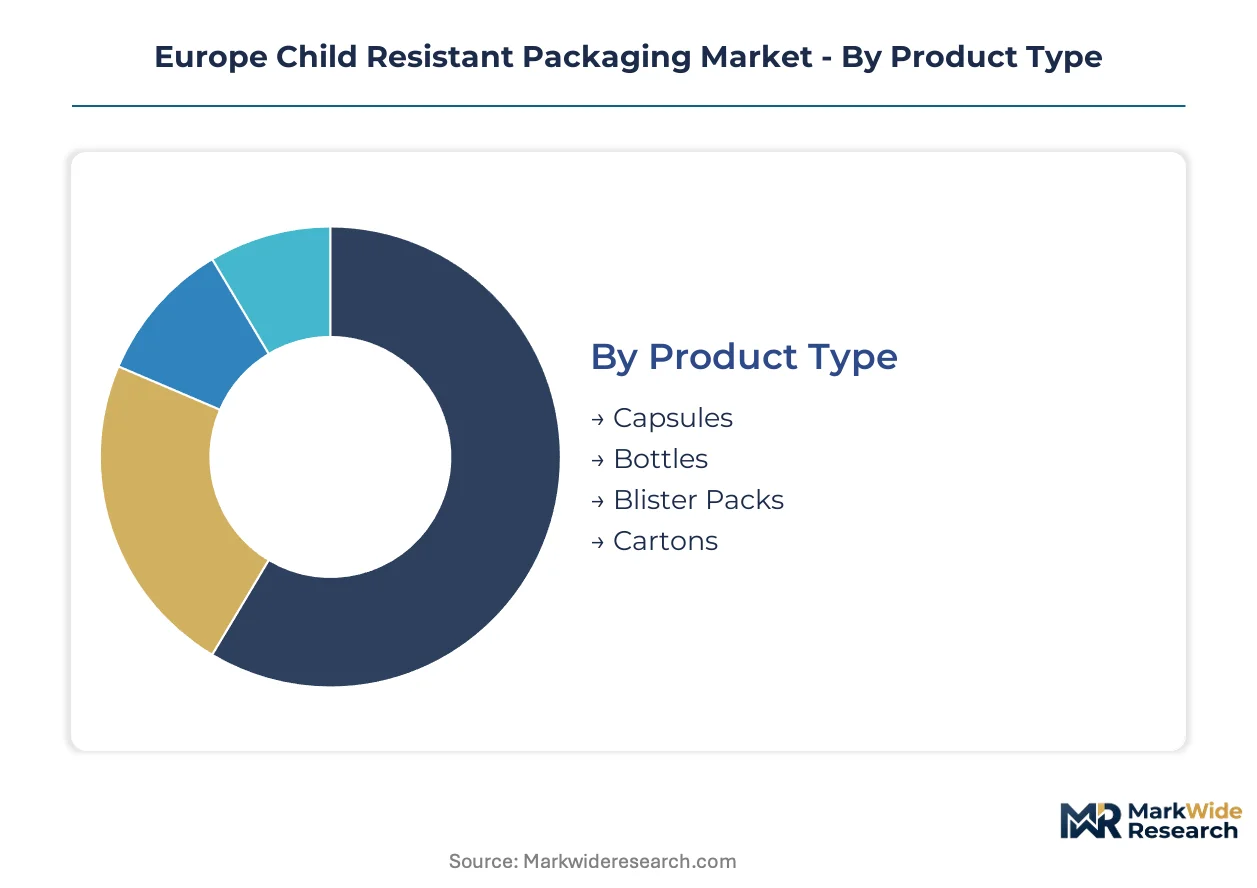
Child-resistant packaging design priorities diverge sharply across pharmaceutical, household, and consumer applications. EMA unit-dose mandates, REACH material restrictions, and EU Green Deal recyclability targets each favor different format configurations, forcing converters to maintain parallel qualification streams.
Product Type:
Pharmaceutical procurement teams prioritize formats based on dosing regimen complexity and senior-accessibility requirements.
- Blister Packs:Multi-cavity aluminum-PVC laminates with push-through or peelable lidding dominate oral solid dose dispensing. German generic manufacturers are migrating toward mono-polyethylene alternatives to satisfy extended producer responsibility frameworks ahead of 2030 mandates.
- Bottles:Blow-molded HDPE and PET containers with integrated closures serve liquid formulations and bulk tablet counts. France's ANSM maintains the strictest migration testing protocols for these formats, making the country the proving ground for compliant designs before broader EU deployment.
- Capsules:Hard gelatin shells requiring secondary child-resistant cartons or wallets for OTC distribution. Demand concentrates in Central European contract packaging corridors serving export markets.
- Cartons:Paperboard secondary packaging with mechanical locking mechanisms replacing plastic wraps under EU Green Deal commitments. Fiber-based formats gain share where primary containers lack integrated resistance features.
Volume sits with bottles; growth tilts toward blister packs.
Material:
REACH substance restrictions and recyclability mandates are disqualifying legacy substrates while elevating qualified alternatives.
- Plastic:Polypropylene and HDPE dominate closure and bottle production. Phthalate-based plasticizer elimination is forcing reformulation of established screw cap compounds, with bio-based alternatives undergoing accelerated qualification.
- Glass:Borosilicate tubing for pharmaceutical vials commands premium positioning in biologics and ophthalmic segments where inert contact surfaces are non-negotiable. Supply concentration in Central Europe exposes packagers to input volatility.
- Paperboard:Fiber-based primary and secondary formats with integrated locking mechanisms. German packaging converters are investing in carton-forming lines capable of pharmaceutical-grade barrier performance.
- Metal:Aluminum lidding foils and steel containers for aerosol and specialty chemical applications. Multi-material recycling incompatibility limits expansion in mainstream pharmaceutical formats.
Plastic retains volume dominance; paperboard is climbing the fastest.
Closure Type:
Adult accessibility mandates and testing cost structures determine closure selection across patient populations.
- Screw Caps:Push-turn mechanisms validated to ISO 8317 standards remain the default for prescription bottles. Certified laboratory capacity for pediatric panel testing is concentrated in Germany and the UK, extending validation timelines for novel designs.
- Push-Pull Caps:Dual-action mechanisms requiring simultaneous depression and rotation. France's ANSM notification acceleration is shortening time-to-market for innovations targeting senior-accessibility mandates.
- Snap Closure:Strength-mediated opening for single-use or short-course medications. Limited penetration outside OTC segments due to resealability concerns.
- Child Resistant Lids:Integrated vial closures for temperature-sensitive protein therapies. Demand is expanding in Germany's contract packaging corridor serving biologics cold-chain requirements.
Screw caps anchor current volume; push-pull configurations are gaining share fastest.
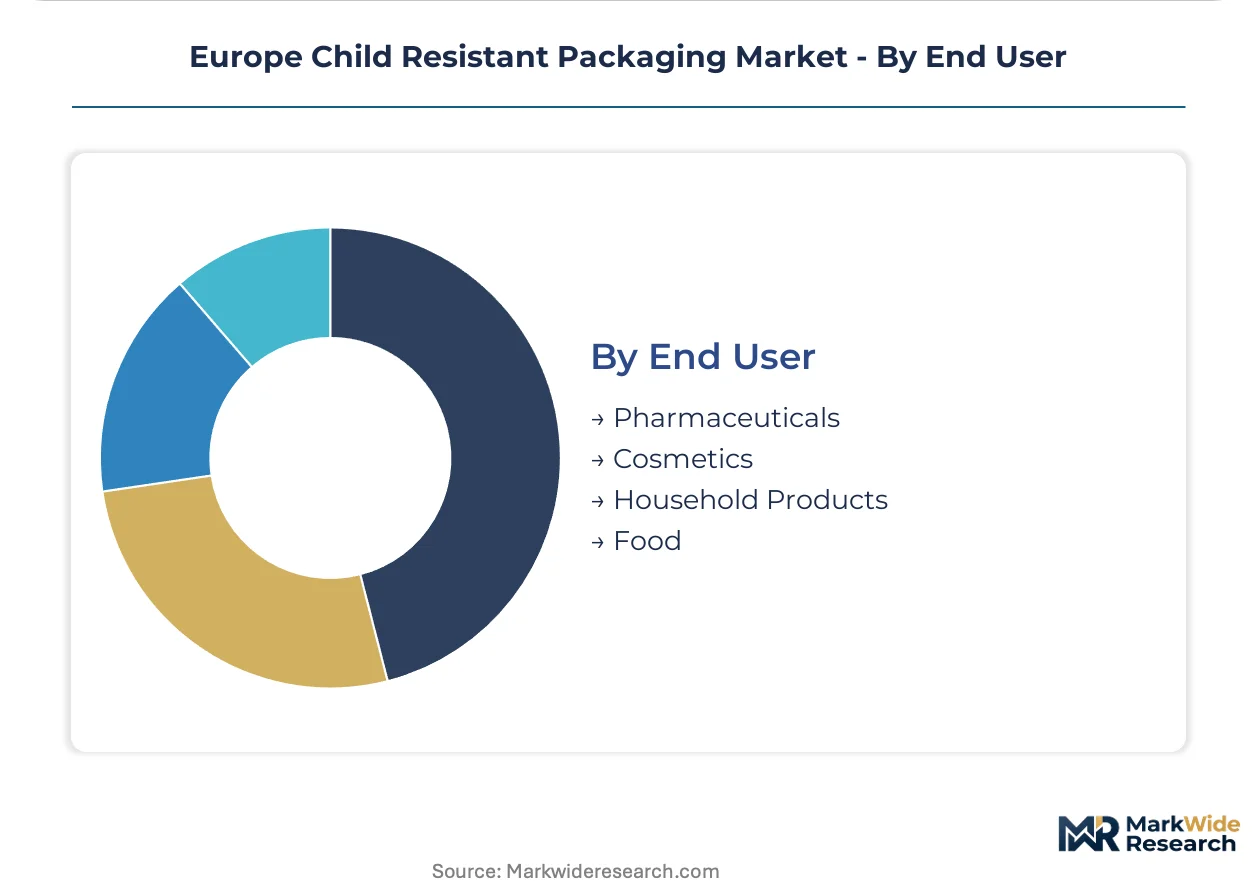
End User:
Regulatory surveillance intensity and liability exposure create distinct performance thresholds across sectors.
- Pharmaceuticals:Unit-dose traceability requirements under EMA pharmacovigilance expansion are driving serialized blister formats. Post-market surveillance mandates now require child-resistant features integrated with authentication technologies.
- Household Products:Cleaning agents and laundry pods trigger national poison prevention statutes tightening across Germany, France, and the UK. Concentrated liquid formats are accelerating demand for squeeze-and-turn closures.
- Cosmetics:Nail care and essential oil products face emerging safety guidelines. Premium positioning supports higher compliance investment than commodity household segments.
- Food:Cannabis-infused edibles and high-caffeine supplements in select jurisdictions. Regulatory fragmentation limits standardized format development.
Pharmaceuticals concentrate value; household products are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging corridors concentrate in Germany's Rhine-Main and Rhine-Ruhr zones, where tax-advantaged industrial parks and proximity to EMA headquarters accelerate child-resistant format development and regulatory pre-qualification.
Germany
Biologics cold-chain expansion drives premium demand for glass vial systems with integrated child-resistant closures. The Federal Institute for Drugs and Medical Devices enforces additional testing rigor beyond baseline EU requirements. Contract packagers in Hesse and Baden-Württemberg serve both domestic drugmakers and export-bound pharmaceutical producers.
France
ANSM notification acceleration shortens time-to-market for novel push-turn closure mechanisms targeting senior-accessibility mandates. Streamlined approval pathways attract innovators testing bio-based plasticizer alternatives. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes host validation laboratories serving broader EU markets.
United Kingdom
Post-Brexit regulatory autonomy has concentrated domestic testing capacity as a decisive supplier selection criterion. MHRA pharmacovigilance requirements mirror EMA standards while maintaining separate notification pathways. Southeast England packaging converters are consolidating serialization and child-resistance capabilities under single accountability frameworks.
Poland
Central European pharmaceutical manufacturing migration creates demand for local child-resistant conversion capacity serving export markets. EU structural funds support packaging infrastructure upgrades in Lower Silesia and Greater Poland Voivodeships. Warsaw and Łódź industrial zones attract contract packaging investments from Western European drug marketers.
Switzerland
Swissmedic maintains parallel but distinct approval pathways for novel closure designs, creating a premium testing destination before broader EU deployment. Precision manufacturing traditions in Basel and Zurich support high-barrier pharmaceutical formats. The country's bilateral agreements with the EU facilitate seamless cross-border distribution of validated packaging systems.
Europe Child Resistant Packaging Market Competitive Landscape
German producers anchor one tier; Anglo-American specialists hold another. The market exhibits moderate consolidation around integrated pharmaceutical packaging providers with captive testing capabilities. Three archetypes dominate: glass-forming specialists with closure integration, blow-molded plastic converters with ISO 8317 validation, and flexible packaging houses combining barrier performance with child-resistance. Competitive moves center on backward integration into substrate production and strategic partnerships with contract packaging organizations.
Within the glass-forming tier, Gerresheimer AG and Schott AG represent European anchor positions. Among flexible packaging specialists, Constantia Flexibles occupies a position exemplifying high-barrier blister foil integration. Berry Global sits within the blow-molded plastic archetype, anchoring volume production of HDPE bottle systems. These three entities collectively illustrate the geographic and technological segmentation defining supplier selection criteria across EMA-regulated markets.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Berry Global |
| AptarGroup |
| WestRock Company |
| Constantia Flexibles |
| ALPLA Group |
| Closure Systems International |
| Schott AG |
| Others |
Value Network & Pricing Analysis
Borosilicate glass tubing spot prices cascade through three distinct pricing tiers across European pharmaceutical packaging corridors. German contract packagers command premium positioning for validated child-resistant vial systems serving biologics cold-chain requirements, while spot-market HDPE resin availability in Poland compresses margins for standardized bottle formats.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical procurement from scheduled contract volumes across the European market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8317 certification tier and volume commitment scale, with German testing laboratory proximity adding geographic cost differentiation. Price erosion runs through economy-tier HDPE bottles as Central European capacity expansion intensifies competition. Generic drug manufacturers exhibit highest price sensitivity; biologics producers prioritize validation speed over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium anchor hub-and-spoke patterns for pharmaceutical packaging distribution across EU member states. Borosilicate tubing supply draws from concentrated Central European glass-forming capacity, while HDPE resin feeds from petrochemical complexes in Belgium and the Netherlands. Single-source vulnerability in pharmaceutical-grade glass tubing exposes packagers to input disruption. Distribution runs through contract packaging organizations with integrated EN 862 validation capabilities serving both domestic and export-bound drugmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH compliance escalation and ISO 8317 testing bottlenecks will eliminate undercapitalized converters unable to fund dual regulatory qualification streams.
For Market Incumbents: Anchor market position through captive glass-forming capacity and backward integration into borosilicate tubing supply. Invest in mono-material blister qualification ahead of 2030 EU Packaging and Packaging Waste Regulation mandates. Defend against Polish contract packaging entrants by co-locating testing laboratories near German pharmaceutical manufacturing clusters. For New Entrants and Emerging Players: Begin with fiber-based carton formats serving OTC pharmaceutical secondary packaging where plastic elimination mandates create immediate white space. Poland's Lower Silesia and Greater Poland Voivodeships offer lowest-barrier entry points for export-serving conversion capacity. Pursue partnership-based go-to-market models with established contract packagers lacking in-house child-resistant design capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap flexible packaging specialists with dormant EN 862 validation credentials in France and Germany. Long-term viability hinges on positioning for post-2030 mono-material dominance rather than multi-layer legacy formats. Watch for Swissmedic pre-qualification announcements as inflection indicators for novel closure mechanism adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive glass supply secures input stability for biologics vial producers amid Central European concentration risk. |
| Mono-Material Blister Qualification | Early validation of polyethylene unit-dose formats captures share from PVC-aluminum laminates facing recycling incompatibility. |
| Testing Laboratory Capacity Expansion | Additional ISO 8317 pediatric panel capacity in Germany and France compresses validation timelines for novel designs. |
| Poland Contract Packaging Corridor Entry | Central European pharmaceutical manufacturing migration creates local demand for export-serving child-resistant conversion. |
| Smart Closure NFC Integration | Digital therapeutics reimbursement pathways open for adherence-monitoring caps combining child-resistance with connectivity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with packaging procurement directors, regulatory affairs managers at pharmaceutical marketers, contract packaging operations heads, and EN 862 testing laboratory directors combined with EMA submission databases, EU Packaging and Packaging Waste Regulation impact assessments, and national poison prevention statute compilations. Bottom-up format-level demand modeling triangulated against top-down pharmaceutical production value estimates.
Data-stream reconciliation across volume shipments, raw material consumption patterns, and end-use pharmaceutical production indices shaped the analytical framework across the analysis window. Segmentation dimensions included product type, material substrate, closure mechanism, and end-use sector with regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of validated unit-dose dispensing growth and biologics cold-chain expansion, cross-referenced against REACH substance restriction implementation timelines.
Underlying measurement precision varies by segment; pharmaceutical blister packs and glass vial systems carry tighter precision than household chemical applications due to more granular production reporting. Forecasts reflect documented assumptions regarding EMA pharmacovigilance expansion pace and EU Extended Producer Responsibility framework implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Confectionery Packaging Market