
 Chocolate Wrapping Machine Market | 2026-2036
Chocolate Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Wrapping Machine Market Outlook
CE marking under the EU Machinery Directive is bifurcating the competitive landscape between certified European suppliers and emerging Asian entrants. Coesia Group leverages its integrated packaging technology portfolio to sustain premium positioning across flow wrapper and shrink wrapper lines. Syntegon Technology anchors its market presence through deep specialization in automated confectionery handling systems with servo-driven precision controls.
A chocolate wrapping machine is an electromechanical system that enrobes individual or grouped confectionery units in protective materials such as BOPP, aluminum foil, or paper, operating at speeds typically ranging from 100 to 1,200 units per minute depending on configuration and product format. Its primary commercial purpose is to extend shelf stability, ensure regulatory traceability, and deliver brand-differentiated presentation at retail touchpoints. Automated technology segments command the dominant share of capital deployment as confectionery manufacturers replace mechanical cam-driven systems with servo-based digital controls for format flexibility. Flow wrapper configurations represent the mature volume category, while horizontal wrapping systems for premium molded chocolates capture concentrated margin pools through precision folding and registered print alignment capabilities.
EMA food contact material standards, EU F-Gas Regulation restrictions on refrigerants in cooling tunnels, and REACH compliance for packaging substrates collectively shape equipment specification requirements and supplier qualification protocols across European installations. FDA 21 CFR regulations for food-contact surfaces and BIS certification requirements for imported machinery into India add parallel compliance layers that filter market access for non-domestic vendors. Stakeholders must monitor evolving Extended Producer Responsibility frameworks for packaging waste, as these mechanisms will increasingly dictate material compatibility requirements and retrofit obligations for installed machine bases.
Market Dynamics
Servo-based digital control architectures are displacing mechanical cam-driven systems across European confectionery processing clusters, compressing replacement cycles and rewiring supplier qualification protocols around CE marking and EMA food contact compliance.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant restrictions in cooling tunnels force energy-efficient machinery upgrades across German industrial chocolate processing sites in Cologne and Hamburg.
- Artisan automation:Premium confectionery brands deploy automated wrapping capacity to meet shelf-life and presentation standards for molded chocolate formats.
- Servo precision controls:Format flexibility demands from short-run premium SKUs accelerate capital deployment into digitally configurable wrapping lines.
Market Restraints
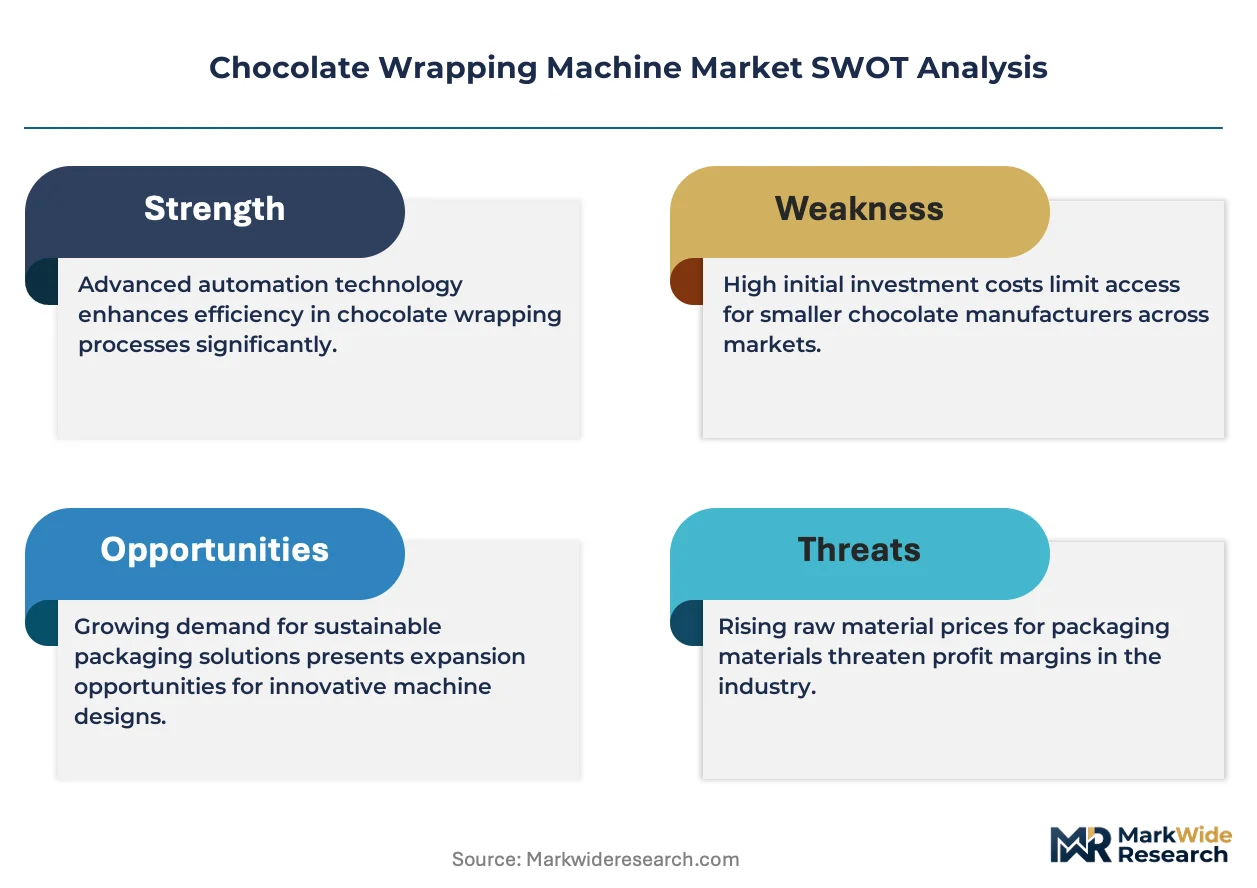
- Stainless steel input volatility:Food-grade 316L and 304 alloy price swings compress margin visibility for equipment fabricators serving mid-tier confectionery processors.
- REACH compliance friction:ECHA substrate restrictions for BOPP and aluminum foil packaging materials extend supplier qualification timelines and limit sourcing pools.
- Mechanical system stranded assets:Installed cam-driven bases in Eastern European secondary processing facilities face accelerated functional obsolescence without retrofit pathways.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:EU packaging waste frameworks create retrofit demand for material compatibility upgrades in installed machine bases across France and Italy.
- India import certification:BIS machinery certification requirements filter non-domestic vendor access, creating qualified supplier scarcity for European entrants meeting documentation standards.
- Servo-vision convergence:Integrated registered print alignment and precision folding capabilities unlock premium molded chocolate margin pools previously captured by manual finishing.
Industry Challenges
- Servomechatronics skill scarcity:Confectionery engineering teams lack diagnostic capability for multi-axis digital control architectures, extending commissioning timelines and warranty exposure.
- CE marking certification backlog:EU Machinery Directive conformity assessment delays compress delivery windows for brownfield installation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Wrapping Machine Market |
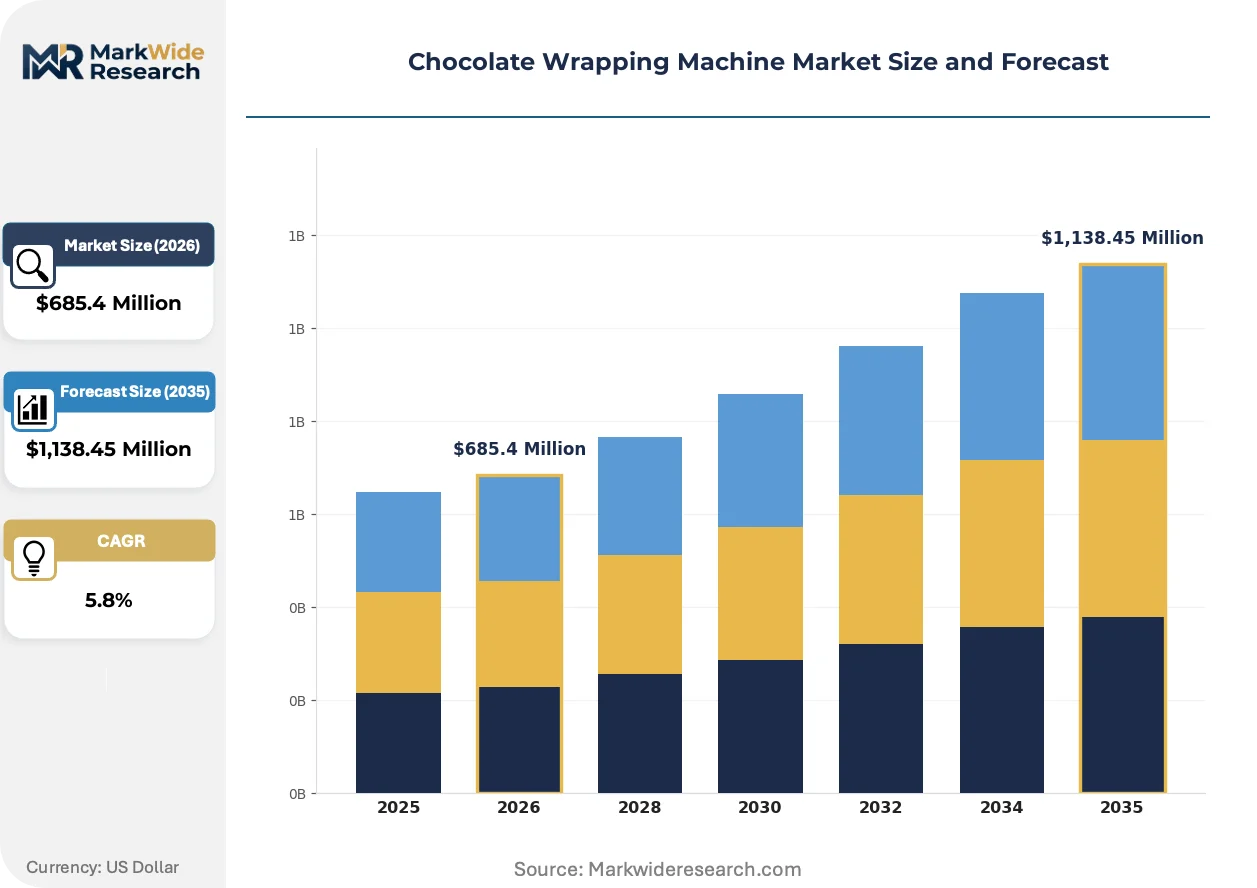
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Flow Wrapper, Shrink Wrapper Technology: Automated, Semi-Automated, Manual, Digital End User: Confectionery Manufacturers, Bakeries, Food Processing, Retail Packaging Type: Polyethylene, BOPP, Aluminum Foil, Paper |
| Companies Covered | LOYNDS International Ltd., Coesia Group, Syntegon Technology, Taizhou Funengda Industry Co., Ltd., MAKREV Packaging, IMA Ilapak, AMP Rose Ltd., TENCHI SANGYO & TENCHI KIKAI Co., Ltd., Lareka Confectionery Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Wrapping Machine Market Strategic Shifts
Active displacement of mechanical architectures by digital control systems is compressing equipment lifecycles and rewiring aftermarket service economics. Regulatory material restrictions and demand-side format fragmentation are simultaneously reshaping specification requirements and procurement patterns.
Servo-driven motion control with integrated vision systems is displacing mechanical cam-driven wrapping mechanisms in high-throughput flow wrapper configurations. Mid-sized Belgian and Swiss premium chocolate manufacturers are adopting these platforms for 300-800 unit-per-minute lines to enable same-day format changeovers. This displacement is compressing residual value for mechanical assets and fragmenting the installed base upgrade pathway into modular retrofit versus full replacement decisions.
EMA food contact material standards and EU F-Gas Regulation restrictions are tightening equipment specification requirements for cooling tunnel integration and substrate handling systems. Industrial chocolate processors in Germany and the Netherlands face extended supplier qualification protocols as REACH compliance for packaging materials filters approved component lists. Premium molded chocolate segments bear the highest compliance burden due to registered print alignment precision demands and aluminum foil substrate restrictions.
After-sales service unbundling is separating maintenance contracts from original equipment procurement in mid-market buyer segments. Confectionery manufacturers in Italy and Spain are negotiating standalone technical support agreements with third-party servicers rather than captive OEM service plans. This behavioral shift is most visible among artisan producers scaling automated capacity without legacy vendor relationships, compressing OEM service revenue per installed unit.
Chocolate Wrapping Machine Market Segmentation
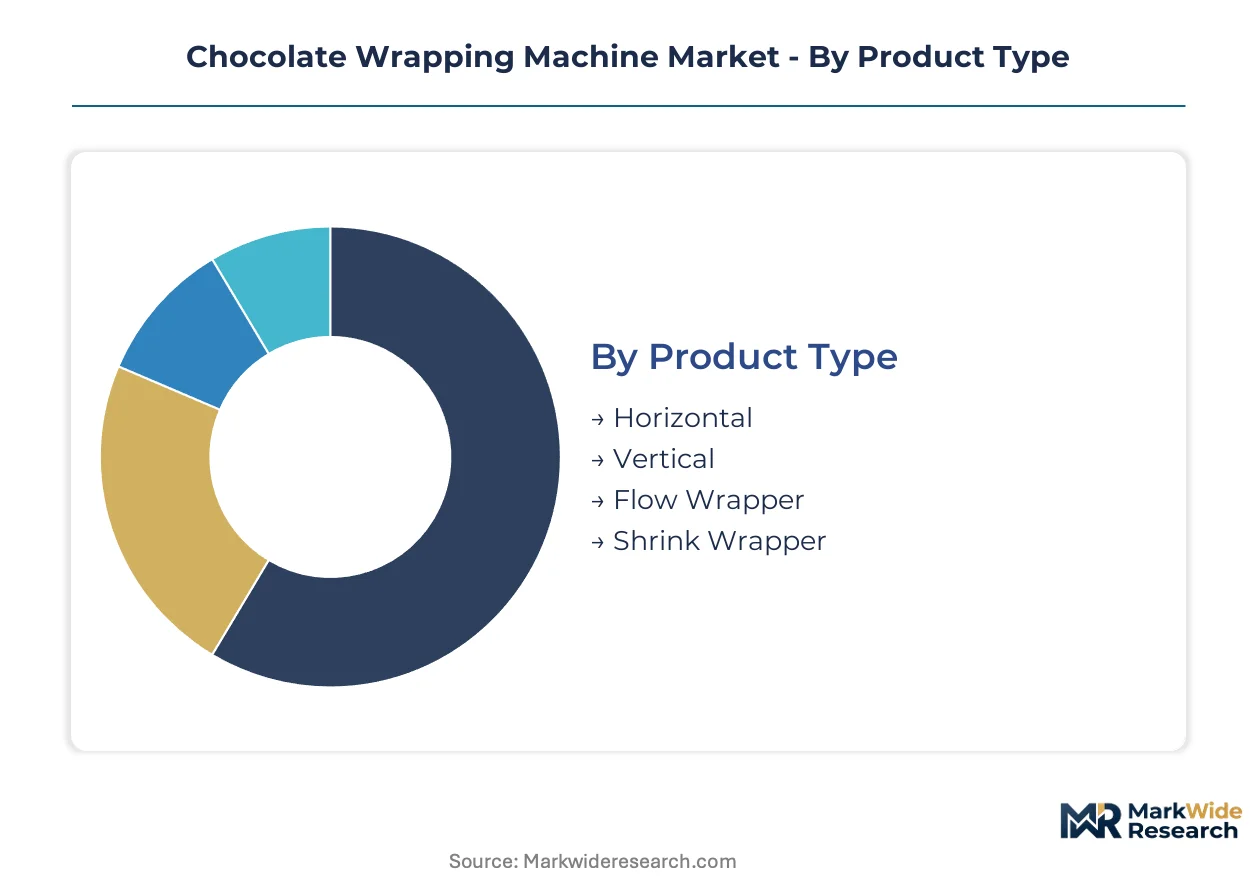
Chocolate wrapping machine procurement patterns diverge sharply across product formats and automation tiers. Equipment specification requirements flow from end-use shelf-life demands, regulatory material restrictions, and line-speed targets that separate artisan producers from industrial processors.
Product Type:
German and Belgian confectionery clusters drive replacement demand for horizontal and flow wrapper configurations, while export-led demand from Indian and Brazilian processors concentrates in vertical and shrink wrapper lines for emerging market cost structures.
- Flow Wrapper:Servo-driven configurations dominate high-throughput installations across Cologne and Hamburg industrial chocolate processing sites. German manufacturers deploy these systems for 800-1,200 unit-per-minute operations where format flexibility from short-run premium SKUs justifies capital intensity.
- Horizontal:Precision folding and registered print alignment capabilities capture premium molded chocolate margin pools in Swiss and Belgian artisan automation projects. These systems enable same-day format changeovers that mechanical cam-driven architectures cannot match.
- Vertical:Compact footprint configurations serve bakeries and retail packaging operations with space-constrained production floors.
- Shrink Wrapper:Bundling applications for multi-pack confectionery formats concentrate in secondary processing facilities across Eastern Europe.
Flow wrapper configurations hold the largest share; momentum sits with horizontal wrapping systems for premium applications.
Technology:
Capital deployment intensity stratifies across automation tiers, with servo-based digital controls commanding premium pricing against mechanical alternatives.
- Automated:Multi-axis servo architectures displace mechanical cam-driven systems across European installations. EMA food contact compliance and CE marking requirements filter supplier pools for these capital-intensive deployments.
- Digital:Integrated vision systems enable registered print alignment precision that REACH-compliant aluminum foil substrates demand. Belgian premium chocolate manufacturers adopt these platforms for 300-800 unit-per-minute lines.
- Semi-Automated:Mid-tier confectionery processors in Italy and Spain deploy hybrid configurations during capacity scaling phases.
- Manual:Artisan producers retain hand-finishing for ultra-premium molded chocolate formats where presentation differentiation justifies labor intensity.
Automated technology commands dominant capital deployment; digital control architectures are climbing the fastest as format fragmentation accelerates replacement cycles.
End User:
Procurement authority concentrates with engineering teams at industrial confectionery processors, while artisan bakeries and retail chains negotiate through equipment leasing channels.
- Confectionery Manufacturers:Industrial chocolate processors in Germany and the Netherlands specify cooling tunnel integration compliant with EU F-Gas Regulation refrigerant restrictions. These buyers demand REACH-compliant substrate handling systems with extended supplier qualification protocols.
- Food Processing:Multi-product facilities require format flexibility that servo-driven architectures provide for confectionery line diversification.
- Bakeries:Mid-sized Belgian operations adopt automated wrapping capacity to meet shelf-life standards without legacy vendor relationships.
- Retail:Private-label confectionery programs drive demand for shrink wrapper configurations in supermarket supply chain integration.
Confectionery manufacturers represent the dominant installed base; food processing applications are gaining share fastest through line diversification strategies.
Packaging Type:
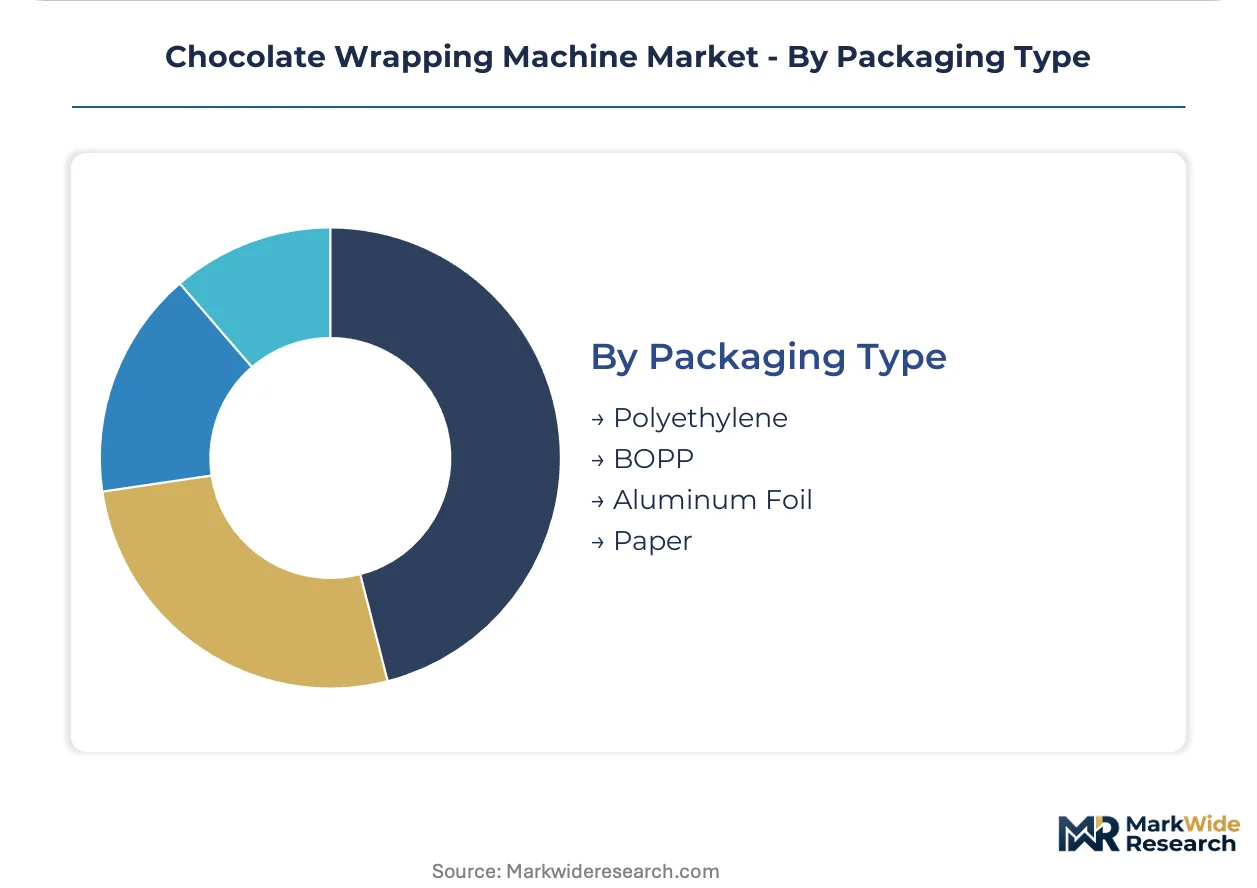
Material specification requirements fragment across regulatory jurisdictions, with European EMA standards and Indian BIS certification creating divergent compliance pathways.
- BOPP:Biaxially oriented polypropylene dominates high-speed flow wrapper applications where clarity and seal integrity meet shelf-life targets. ECHA substrate restrictions under REACH compliance extend supplier qualification timelines for European installations.
- Aluminum Foil:Premium molded chocolate segments bear the highest compliance burden due to registered print alignment precision demands and material restriction protocols. Swiss and Belgian manufacturers specify these substrates for barrier properties.
- Paper:Extended Producer Responsibility frameworks in France and Italy create retrofit demand for material compatibility upgrades in installed machine bases.
- Polyethylene:Cost-sensitive applications in emerging market installations favor this substrate for equipment compatibility with existing sealing technologies.
BOPP holds the largest share; paper substrates are expanding most quickly under packaging waste regulation tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial confectionery processors in Germany, Belgium, and Switzerland anchor capital deployment for high-throughput wrapping systems. Artisan automation demand from mid-sized premium chocolate manufacturers concentrates procurement authority across Western European clusters.
Germany
Industrial chocolate processors around Cologne and Hamburg drive replacement cycles for servo-based flow wrappers handling 800-1,200 units per minute. EU F-Gas Regulation refrigerant restrictions in cooling tunnels force energy-efficient machinery upgrades. The North Rhine-Westphalia cluster concentrates brownfield installation projects facing CE marking certification backlogs.
Belgium
Mid-sized premium chocolate manufacturers adopt 300-800 unit-per-minute horizontal wrapping systems for same-day format changeovers. EMA food contact material standards extend supplier qualification timelines for REACH-compliant aluminum foil substrate handling. The Flanders region anchors artisan automation scaling without legacy vendor relationships.
Switzerland
Precision molded chocolate segments demand registered print alignment capabilities that servo-vision convergence enables. Swissmedic-aligned quality protocols filter equipment specifications for ultra-premium presentation standards. The Lake Geneva corridor concentrates specialized engineering teams for multi-axis digital control commissioning.
Italy
Extended Producer Responsibility frameworks for packaging waste create retrofit demand for material compatibility upgrades in installed machine bases. Mid-tier confectionery processors negotiate standalone technical support agreements with third-party servicers. The Piedmont and Lombardy clusters concentrate aftermarket service unbundling behavior.
India
BIS machinery certification requirements filter non-domestic vendor access for imported wrapping equipment. Export-led demand from secondary processing facilities concentrates in vertical and shrink wrapper configurations for emerging market cost structures. The Maharashtra and Gujarat industrial corridors drive qualified supplier scarcity for European entrants meeting documentation standards.
Chocolate Wrapping Machine Market Competitive Environment
Player mix skews toward integrated packaging technology groups and specialized confectionery handling fabricators. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with cross-sector packaging portfolios, pure-play confectionery equipment specialists with deep format expertise, and emerging Asian fabricators competing on cost-adjusted specifications. Competitive dynamics center on CE marking certification velocity and aftermarket service contract attachment rates.
Within the diversified industrial tier, Coesia Group and Syntegon Technology exemplify integrated packaging technology positioning across flow wrapper and automated handling lines. Among specialized confectionery fabricators, LOYNDS International Ltd. and Lareka Confectionery Equipment occupy positions anchored in artisan and mid-tier processor segments. Taizhou Funengda Industry Co., Ltd. represents the emerging Asian fabricator archetype competing on equipment cost structures for export markets.
| Leading Market Players |
|---|
| LOYNDS International Ltd. |
| Coesia Group |
| Syntegon Technology |
| Taizhou Funengda Industry Co., Ltd. |
| MAKREV Packaging |
| IMA Ilapak |
| AMP Rose Ltd. |
| TENCHI SANGYO & TENCHI KIKAI Co., Ltd. |
| Lareka Confectionery Equipment |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-sixteen-week delivery windows for servo-drive assemblies from German and Italian component suppliers concentrate pricing power with CE-certified OEMs serving premium confectionery processors. This lead-time band forces mid-tier buyers into extended equipment financing or third-party refurbishment alternatives, compressing margin capture for non-certified Asian entrants.
Pricing Analysis
Cost-plus contracts indexed to LME stainless steel benchmarks dominate equipment procurement for industrial chocolate processors in Germany and Belgium. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked servo systems from semi-automated mechanical retrofits and manual finishing equipment. Pricing pressure stems from food-grade 316L alloy volatility eroding fabricator margins on fixed-price agreements. Artisan bakeries in Italy exhibit highest price sensitivity, while Swiss premium chocolate manufacturers prioritize precision specifications over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Belgian OEMs for servo motors and vision systems, while strategic stockpiling of food-grade stainless steel concentrates with Italian and Spanish fabricators facing alloy price swings. Component sourcing draws from Germany, Italy, and Japan for precision motion control hardware. Single-source vulnerability sits with specialized aluminum foil substrate suppliers under REACH compliance scrutiny. Distribution runs through direct OEM sales channels for large installations and equipment leasing networks serving mid-tier artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in aftermarket service unbundling, as artisan automation demand from mid-sized premium chocolate manufacturers creates niches outside legacy vendor relationships.
For Market Incumbents: Compound service revenue attachment through predictive maintenance platforms for installed servo-based systems. Defend position against emerging Asian fabricators by accelerating CE marking certification velocity for brownfield retrofit configurations. Vertical integration into vision system calibration services captures margin pools from precision folding applications in Swiss and Belgian premium segments. For New Entrants and Emerging Players: Differentiate on BIS documentation compliance for Indian import certification, where qualified European supplier scarcity creates white-space. Target aftermarket technical support agreements in Italy and Spain where mid-tier processors negotiate standalone servicer relationships. Penetrate through equipment-leasing channel partnerships serving retail private-label confectionery programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core packaging technology units with confectionery-specialized engineering teams. Long-term viability hinges on servo-vision convergence capabilities replacing mechanical asset bases. Watch for Extended Producer Responsibility framework enforcement intensity in France and Italy as inflection signal for material compatibility retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Vision Platform Integration | Enables registered print alignment precision for REACH-compliant aluminum foil substrates. |
| CE Marking Acceleration Program | Compresses conformity assessment timelines for brownfield installations facing certification backlogs. |
| Aftermarket Service Unbundling | Captures standalone technical support contracts from artisan producers scaling automated capacity. |
| BIS Certification Documentation Investment | Filters qualified supplier access for European entrants targeting Indian import demand. |
| Extended Producer Responsibility Retrofit Capability | Positions installed base upgrades for paper substrate compatibility under EU packaging waste frameworks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at German and Belgian confectionery processors, aftermarket service heads at Italian equipment distributors, and procurement leads at Swiss premium chocolate manufacturers. Secondary validation drew from EU F-Gas Regulation implementation reports, ECHA REACH substance restriction updates, BIS machinery certification documentation requirements, and trade flow data for food-grade stainless steel inputs. Bottom-up equipment shipment analysis and top-down capital expenditure triangulation anchored market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions including automation tier, wrapping configuration type, end-user scale, and substrate material compliance pathway. CAGRs were derived from replacement cycle compression rates and artisan automation penetration curves. Industry-specific inputs incorporated servo-drive adoption velocity in Cologne and Hamburg industrial clusters and REACH-compliant substrate qualification timelines.
Forecasts assume regulatory continuity in EU F-Gas and REACH regimes; material policy shifts would require re-modeling cooling tunnel integration specifications and aluminum foil handling requirements. Stainless steel price volatility and servomechatronics skill scarcity constitute primary revision triggers. Revision becomes warranted when CE marking certification backlogs exceed sixteen weeks or Extended Producer Responsibility enforcement thresholds accelerate retrofit demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Medicine Decoction and Packing Machines Market