
 Specialty Labels Packaging Market | 2026-2036
Specialty Labels Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Labels Packaging Market Analytics
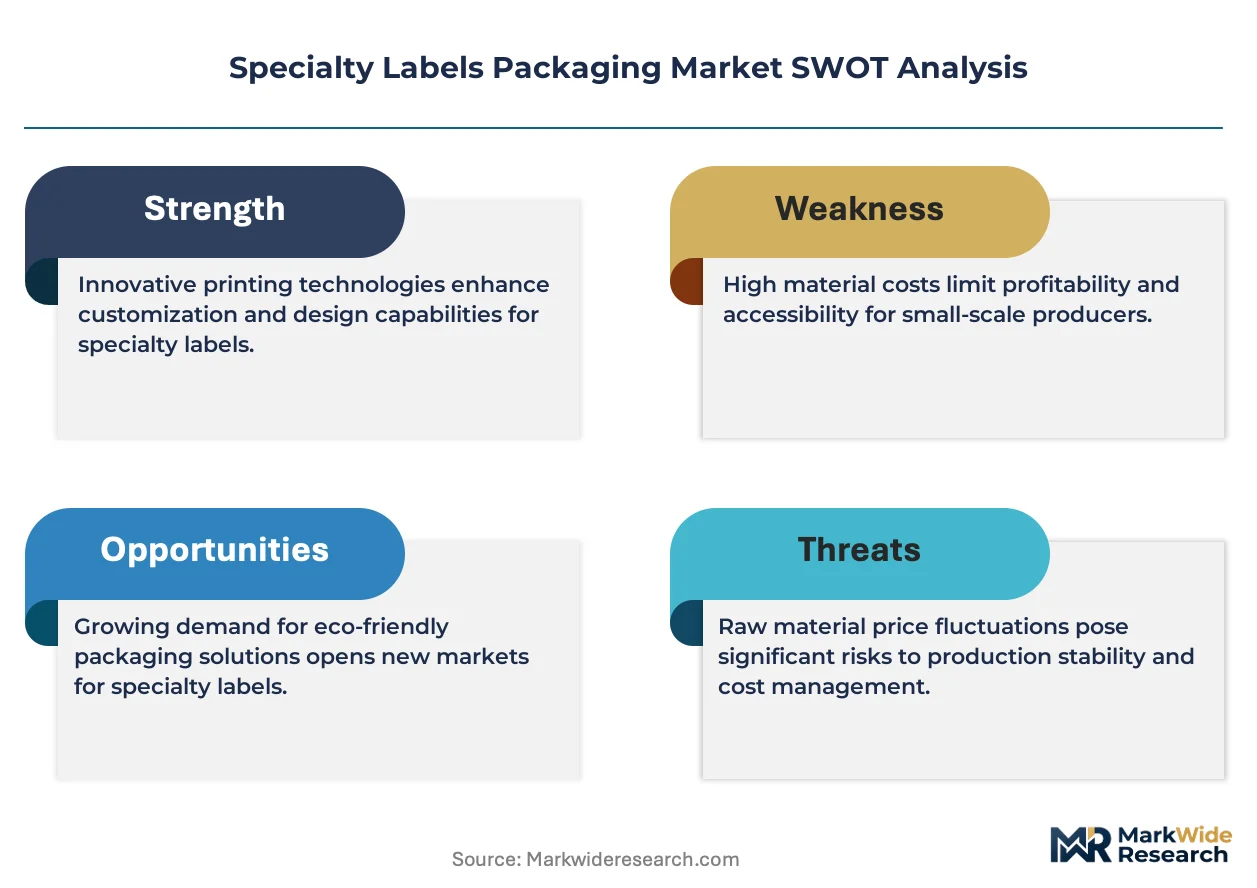
The gap between premium functional labels and commodity adhesive products is expanding. Avery Dennison leverages its materials science portfolio to dominate high-performance segments with temperature-resistant and RFID-enabled solutions. CCL Industries anchors its position through backward integration into printed electronics and pharmaceutical authentication technologies. UPM Raflatac specializes in sustainable film and paper substrates, competing on renewable content credentials rather than unit cost alone.
Specialty labels packaging encompasses engineered adhesive constructions, printed substrates, and functional coatings designed for product identification, regulatory compliance, and supply-chain traceability. These assemblies typically incorporate pressure-sensitive adhesives with defined peel strengths, face stocks ranging from metallized films to direct-thermal papers, and release liners calibrated for automated dispensing speeds. Pressure-sensitive labels lead volume due to universal compatibility with existing applicator infrastructure across food and beverage lines. Shrink sleeves capture premium margin pools in personal care and pharmaceuticals, where full-body decoration and tamper-evident sealing command price premiums. In-mold labels sustain growth in durable goods, where permanent bonding to injection-molded containers eliminates secondary labeling steps.
FDA DSCSA requirements for pharmaceutical track-and-trace are reshaping label specifications in the United States, while EU MDR and REACH compliance in Europe mandate biocompatible adhesives and restricted substance documentation for medical device labels. The EU Green Deal and emerging packaging waste regulations are forcing substrate transitions away from conventional vinyl toward recyclable films and certified papers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in digital printing flexibility or lock in scale economies with conventional flexographic assets.
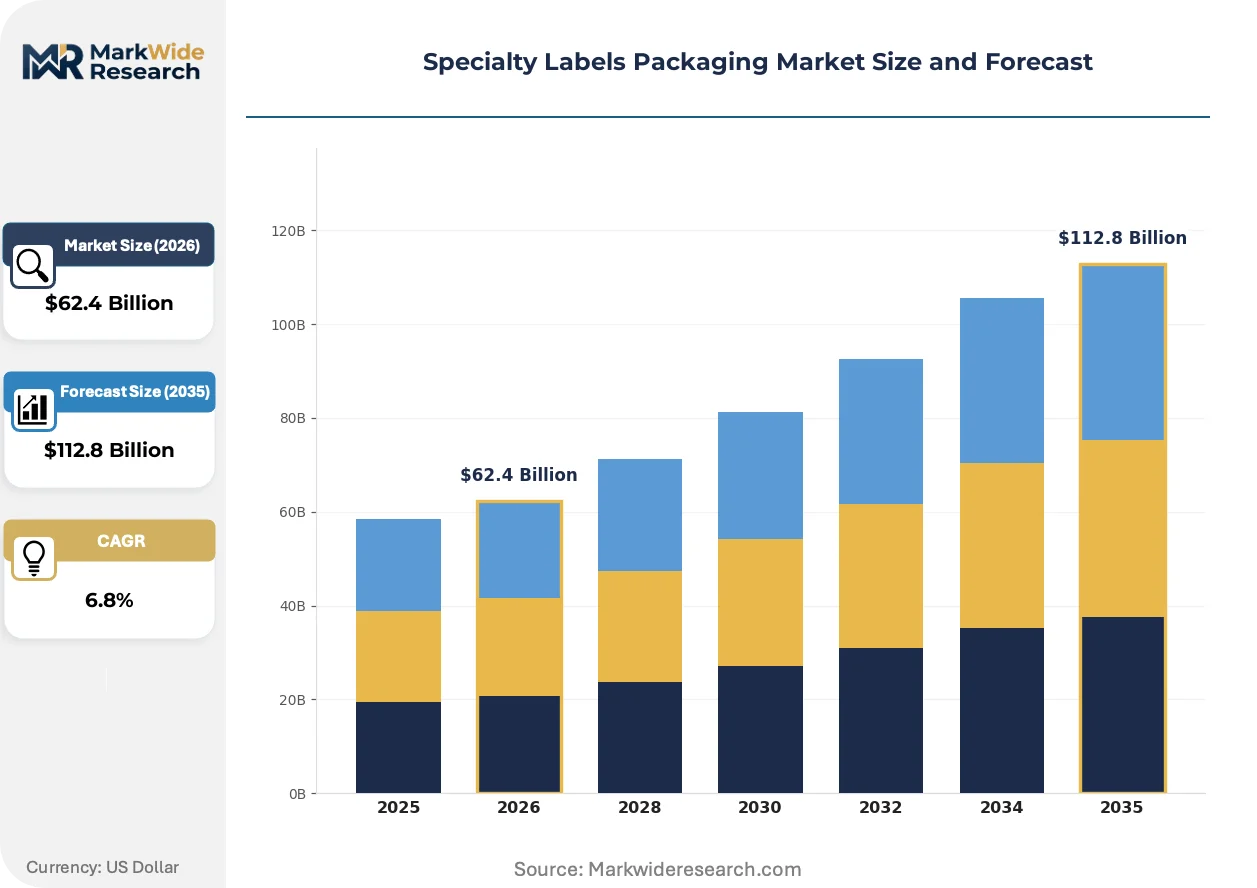
Market Dynamics
Pharmaceutical serialization mandates are compressing label specification cycles and forcing packaging converters to integrate authentication technologies directly into substrate manufacturing workflows.
Growth Catalysts
- EU MDR and FDA DSCSA mandates:Pharmaceutical track-and-trace requirements in Europe and the United States are accelerating tamper-evident label adoption across prescription drug packaging lines.
- RFID-enabled smart labels:Retail and logistics operators are embedding radio-frequency identification into shipping labels to enable real-time inventory visibility and automated sorting.
- Germany's pharmaceutical corridor:Concentrated demand from Merck KGaA and Bayer operations is pulling integrated label-authentication solutions into high-volume production.
Market Restraints
- Petrochemical substrate volatility:Face stock films derived from ethylene and propylene chains expose converters to input cost swings that compress margin buffers on fixed-price contracts.
- Release liner supply concentration:Glassine and super-calendered kraft liner production clusters in Scandinavian pulp networks, creating single-source vulnerability for European label converters.
- Silicone coating technical limitations:Low-surface-energy adhesives required for pharmaceutical cold-chain applications remain incompatible with standard thermal transfer printing ribbons.
Strategic Opportunities
- India pharmaceutical export labeling:CDSCO serialization requirements for export-bound generics are creating demand for multi-language, multi-jurisdiction compliant label systems.
- EU Green Deal substrate transitions:Packaging waste directives are forcing vinyl-to-polyolefin film substitutions, rewarding converters with certified recyclable film portfolios.
- Digital printing-flexographic convergence:Hybrid press configurations combining inkjet personalization with flexographic base coating are enabling short-run pharmaceutical serialization at scale economics.
Industry Challenges
- Pharmaceutical authentication engineering talent:Shortage of specialists capable of integrating physical-chemical security features with digital track-and-trace databases is extending product development timelines.
- Serialization equipment capex intensity:Vision inspection systems and aggregation hardware required for DSCSA compliance demand capital deployment that strains mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Labels Packaging Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, In-Mold Labels, Glue-Applied Labels End User: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Material: Paper, Plastic, Film, Vinyl Application: Retail Packaging, Durable Goods, Product Identification, Inventory Tracking |
| Companies Covered | Avery Dennison, CCL Industries, UPM Raflatac, Multi-Color Corporation, Brady Corporation, Fort Dearborn Company, All4Labels, Mondi, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Labels Packaging Market Evolving Landscape
Functional coating technologies and substrate engineering are converging to transform labels from passive identification into active data-capture and authentication interfaces.
Printed electronics integration is embedding near-field communication chips and printed sensors directly into label substrates. Pharmaceutical manufacturers in Switzerland and the Netherlands are piloting temperature-logging labels for cold-chain biologics. This convergence is decentralizing quality assurance from centralized laboratory testing to distributed package-level monitoring.
REACH substance restrictions and ECHA candidate list updates are banning specific phthalate plasticizers and bisphenol-based coatings from medical device labels. European converters are reformulating adhesives to eliminate restricted substances while maintaining peel strength for autoclave sterilization cycles. The medical device segment is responding by dual-sourcing compliant label stocks to preempt supply interruption.
Brand owners are compressing artwork approval cycles and demanding digital proofing capabilities that eliminate physical press checks. Food and beverage manufacturers in California and São Paulo are adopting web-to-print portals that bypass traditional broker relationships. This pattern is most pronounced in craft beverage segments where seasonal SKU proliferation outpaces conventional flexographic plate turnaround times.
Specialty Labels Packaging Market Segmentation
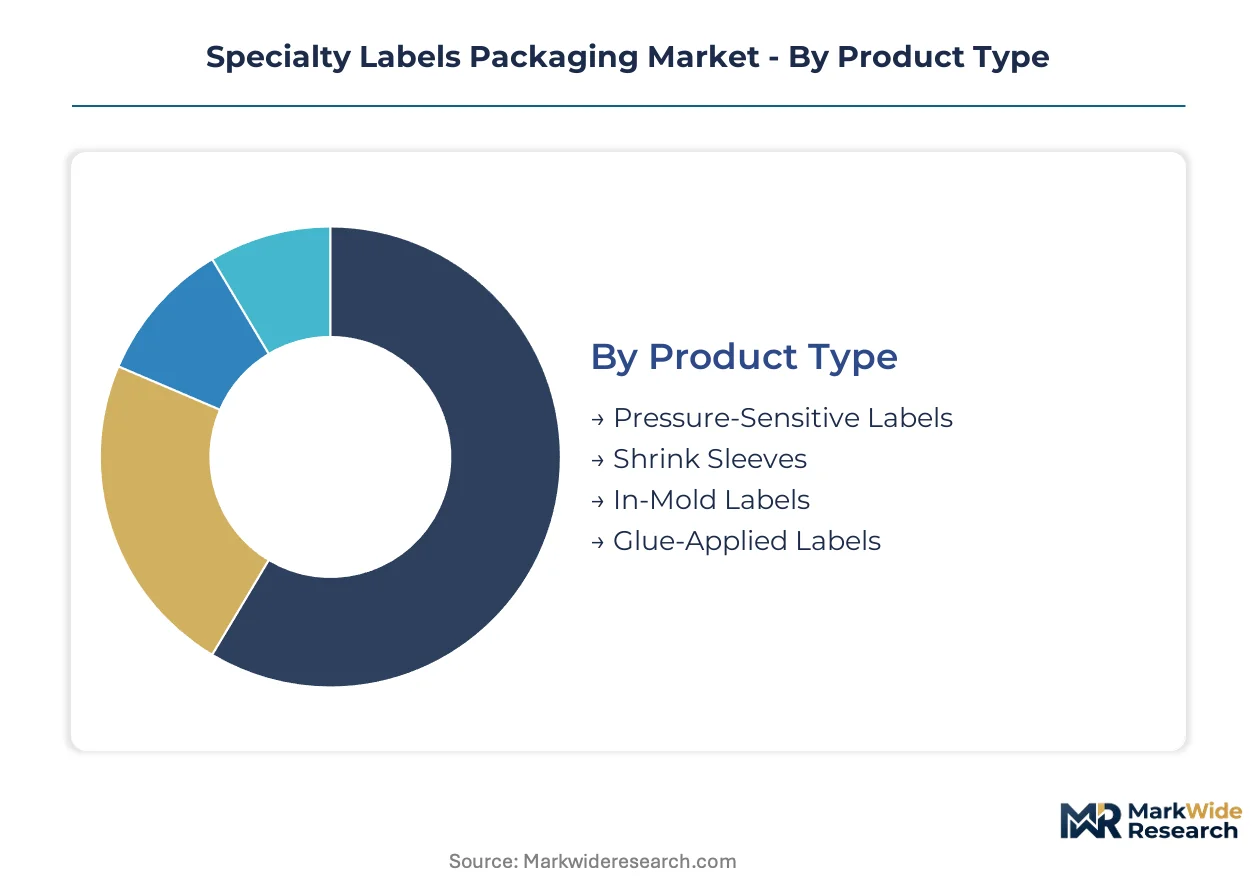
Segmentation in specialty labels packaging reveals how capital allocation, regulatory exposure, and substrate technology determine margin structures. Converters must match equipment investments to segment-specific requirements around serialization, decoration permanence, and dispensing automation.
Product Type:
Capital intensity varies sharply across product types, with serialization-ready labels demanding vision systems and authentication hardware that smaller converters cannot finance.
- Pressure-Sensitive Labels:These constructions combine face stock, adhesive, and release liner into roll-fed formats compatible with high-speed applicators. Demand concentrates in food and beverage lines across Germany and the United States, where FDA and EU MDR compliance mandates are forcing substrate transitions toward certified recyclable films.
- Shrink Sleeves:Full-body polyester or polyolefin sleeves provide tamper-evident sealing and 360-degree decoration through heat-shrink application. Pharmaceutical and personal care manufacturers in Switzerland and the Netherlands are specifying these for biologics packaging where cold-chain integrity and authentication features must coexist.
- In-Mold Labels:Polypropylene films fused during injection molding create permanent bonding for durable goods containers. Automotive chemical and industrial lubricant producers in the US Midwest specify these for solvent-resistant identification.
- Glue-Applied Labels:Wet-glue adhesives applied to paper or metallized stocks serve beverage and canned food segments where cost minimization outweighs decoration complexity. European brewers in Belgium and Czechia maintain volume demand for these legacy formats.
Most installed capacity flows through pressure-sensitive labels. Expansion is steepest in shrink sleeves.
End User:
End-use concentration determines regulatory burden and authentication specification depth, with pharmaceutical and food segments facing the most stringent compliance architectures.
- Food & Beverage:SKU proliferation in craft beverages and clean-label food products is compressing artwork approval cycles. California and São Paulo manufacturers are adopting web-to-print portals that bypass traditional broker relationships for seasonal label runs.
- Personal Care:Premium cosmetic brands specify metallized films and tactile coatings for shelf differentiation. French and Italian luxury houses drive specification toward holographic and iridescent substrate effects.
- Pharmaceuticals:Serialization mandates under FDA DSCSA and EU MDR are compressing label specification cycles and forcing integration of track-and-trace technologies directly into substrate workflows. German packaging converters serving Merck KGaA and Bayer anchor integrated smart-label production.
- Industrial:Chemical resistance and outdoor durability specifications dominate demand for durable goods labeling. US Gulf Coast petrochemical operations and German automotive suppliers specify polypropylene and vinyl stocks with UV-stable adhesives.
Pharmaceutical end-use commands the highest authentication engineering investment. Food and beverage delivers the highest volume throughput.
Material:
Material selection now hinges on recyclability certification and restricted substance compliance rather than unit cost optimization alone.
- Paper:Certified papers with FSC or PEFC chain-of-custody documentation serve wine, spirits, and organic food segments where sustainability credentials support price positioning. Italian and Spanish wine exporters specify these for US and Northern European retail channels.
- Plastic:Polyolefin films are displacing vinyl under EU Green Deal packaging waste directives. Converters with certified recyclable polypropylene portfolios are capturing specification shifts in German and French retail packaging.
- Film:Metallized and clear polyester films provide barrier properties and decorative depth for premium personal care. Swiss and Dutch pharmaceutical manufacturers pilot temperature-logging film constructions for cold-chain biologics.
- Vinyl:Legacy PVC face stocks face regulatory pressure from REACH substance restrictions and extended producer responsibility frameworks. Remaining demand concentrates in industrial durability applications where chemical resistance cannot be replicated with polyolefin substitutes.
Polyolefin film capacity is expanding fastest. Paper maintains the broadest installed base across European converters.
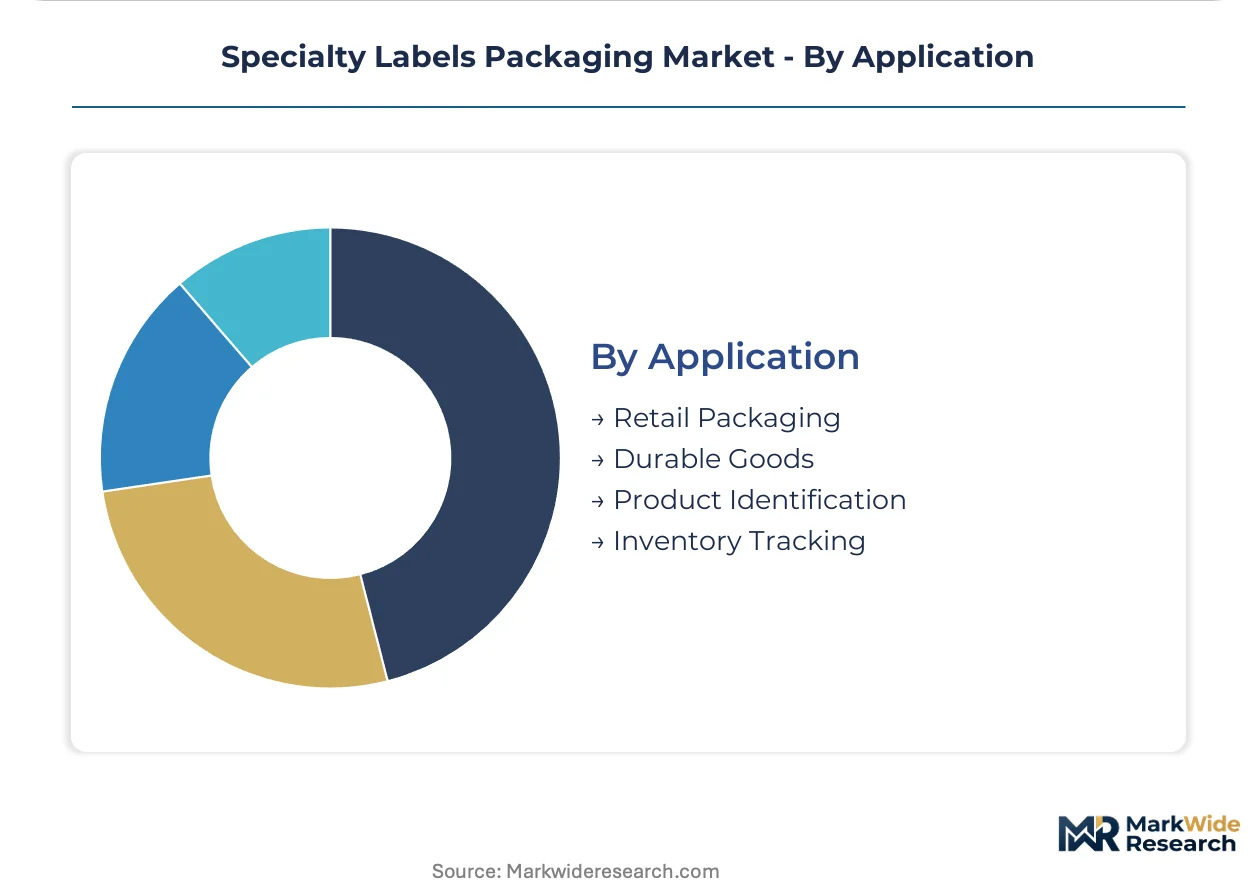
Application:
Application architecture determines whether labels serve passive identification or active data-capture functions, with inventory tracking demanding the most sophisticated substrate engineering.
- Retail Packaging:Shelf appeal and barcode scannability dominate specifications for consumer-facing labels. US and Brazilian supermarket private-label programs are driving demand for digital-printed short runs with variable data capabilities.
- Durable Goods:Permanent bonding and environmental resistance distinguish labels for automotive, appliance, and industrial equipment. Japanese and South Korean electronics manufacturers specify these for component traceability through assembly and service life.
- Product Identification:Regulatory compliance labels for hazardous materials, electrical safety, and medical device classification require certified substrate-adhesive combinations. EU CE marking and US OSHA hazard communication standards dictate specification parameters.
- Inventory Tracking:RFID-enabled and printed sensor labels are transforming supply chain visibility for logistics operators. Retail and pharmaceutical distributors in the Netherlands and Singapore are embedding these into shipping labels for automated sorting and real-time inventory positioning.
Product identification carries the heaviest regulatory documentation burden. Inventory tracking is gaining share fastest among capital-deploying converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and adhesive chemists concentrate in Germany's pharmaceutical corridor, Switzerland's precision manufacturing belt, and the US Midwest industrial belt, anchoring regional capability clusters that serve multinational brand owners.
Germany
Merck KGaA and Bayer operations in Darmstadt and Leverkusen pull integrated smart-label solutions into high-volume production. EU MDR serialization mandates force packaging converters to embed track-and-trace authentication directly into substrate workflows. The Rhine-Main and Rhine-Ruhr corridors host specialized converters serving cold-chain biologics with temperature-resistant adhesive constructions.
United States
FDA DSCSA compliance deadlines compress specification cycles for prescription drug distributors and generic manufacturers. The FDA mandates unit-level traceability by November 2024, forcing label converters to invest in vision inspection and aggregation hardware. New Jersey and Pennsylvania pharmaceutical packaging clusters anchor East Coast supply chains for serialization-ready constructions.
Switzerland
Novartis and Roche headquarters in Basel drive demand for pharmaceutical authentication labels with printed sensor integration. Swissmedic regulations require biocompatible adhesives for medical device labels exposed to sterilization cycles. The Basel-Zurich corridor pilots temperature-logging film constructions for biologics cold-chain monitoring.
India
CDSCO serialization requirements for export-bound generics create demand for multi-language, multi-jurisdiction compliant label systems. The Directorate General of Foreign Trade mandates traceability data matrix codes on pharmaceutical exports to regulated markets. Gujarat and Maharashtra pharmaceutical manufacturing clusters anchor label specification shifts toward EU MDR and FDA DSCSA alignment.
Netherlands
Rotterdam logistics operators and Schiphol pharmaceutical distributors embed RFID-enabled labels into shipping workflows for automated sorting. ECHA REACH substance restrictions ban specific phthalate plasticizers from medical device labels. The Randstad region hosts converters reformulating adhesives to eliminate restricted substances while maintaining autoclave sterilization performance.
Specialty Labels Packaging Market Competitive Landscape
Top-tier vendors anchor premium functional segments, while mid-scale converters compete on digital printing flexibility and regional regulatory expertise. The vendor base stratifies across materials science specialists, integrated authentication technology providers, and sustainable substrate innovators. Three archetypes dominate: backward-integrated film producers, pharmaceutical serialization specialists, and renewable content credential builders. Competitive moves center on hybrid press configurations combining inkjet personalization with flexographic base coating, and substrate portfolio diversification toward certified recyclable polyolefin films.
Within the materials science tier, Avery Dennison Corporation exemplifies high-performance adhesive and RFID-enabled solution provision. CCL Industries Inc. occupies a position anchoring printed electronics and pharmaceutical authentication technology integration. UPM Raflatac represents sustainable film and paper substrate specialization competing on renewable content credentials rather than unit cost positioning alone.
| Leading Market Players |
|---|
| Avery Dennison |
| CCL Industries |
| UPM Raflatac |
| Multi-Color Corporation |
| Brady Corporation |
| Fort Dearborn Company |
| All4Labels |
| Mondi |
| Huhtamaki Group |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging waste directives gate qualified supply for converters seeking premium-tier pricing access, as certified recyclable polyolefin film portfolios command margin premiums over vinyl legacy stocks while excluding uncertified competitors from specification pools.
Pricing Analysis
Bundled authentication-services-plus-substrate contracts versus unbundled commodity label supply splits the market into divergent margin structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and serialization-readiness, with FDA DSCSA-compliant constructions carrying substantial premiums over generic adhesive products. Cost compression in commodity pressure-sensitive tiers is intensifying because petrochemical input volatility exposes converters to margin erosion on fixed-price pharmaceutical contracts. Generic pharmaceutical distributors exhibit the highest price sensitivity, while Swiss biologics manufacturers prioritize authentication engineering over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand from Merck KGaA and Bayer, while distributor networks serve mid-tier food and beverage converters. Raw material flows draw from German specialty chemical producers for silicone coatings, Scandinavian pulp networks for glassine release liners, and Saudi petrochemical operations for polyolefin face stock films. Single-source vulnerability concentrates in Scandinavian kraft liner production, where limited alternative sourcing extends lead times during pulp mill maintenance cycles. Distribution runs through regional converter hubs in Germany's Rhine-Ruhr corridor and the US New Jersey-Pennsylvania pharmaceutical packaging cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters operating across EU MDR and FDA DSCSA jurisdictions exploit a geographic-arbitrage play, as Indian pharmaceutical export labeling demand for multi-jurisdiction compliant systems carries lower regulatory compliance overhead than European domestic production while accessing premium pricing in regulated markets.
For Market Incumbents: Deploy hybrid press configurations combining inkjet personalization with flexographic base coating to defend against digital-native entrants attacking short-run pharmaceutical serialization. Incumbents must deepen backward integration into printed electronics to protect margin pools from authentication-technology specialists. Capacity consolidation in Germany's pharmaceutical corridor anchors integrated smart-label production against fragmented regional competitors.
For New Entrants and Emerging Players: Web-to-print portals for craft beverage seasonal SKU proliferation offer the most penetrable entry vector, bypassing traditional broker relationships that incumbents lock through long-term pharmaceutical contracts. New entrants should target California and São Paulo food manufacturers with digital proofing capabilities that compress artwork approval cycles. A direct-to-brand-owner go-to-market angle eliminates distributor margin extraction.
For Investors and Strategic Acquirers: Roll-up economics work for pharmaceutical serialization specialists because EU MDR and FDA DSCSA mandates are compressing specification cycles and forcing mid-tier converters to seek authentication-technology capabilities through acquisition. Platform consolidation across European converters with certified recyclable film portfolios captures substrate transition premiums under packaging waste directives. Watch for CDSCO serialization requirement expansions beyond export-bound generics as the inflection signal for Indian pharmaceutical labeling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Press Configuration | Combines inkjet personalization with flexographic coating for pharmaceutical serialization at scale economics. |
| Backward Integration into Printed Electronics | CCL Industries anchors market position through in-house production of NFC chips and authentication sensors. |
| Certified Recyclable Film Portfolio Expansion | UPM Raflatac competes on renewable content credentials under EU Green Deal packaging waste directives. |
| Pharmaceutical Authentication Talent Acquisition | Shortage of specialists integrating physical-chemical security features with digital track-and-trace databases extends development timelines. |
| Regional Converter Hub Consolidation | Germany's Rhine-Main and Rhine-Ruhr corridors host specialized converters serving Merck KGaA cold-chain biologics demand. |
Research Methodology
Multiple input streams — packaging converter plant managers, pharmaceutical procurement leads at Merck KGaA and Bayer, adhesive R&D directors, and distribution channel partners — were reconciled with secondary validation from EMA submissions, FDA DSCSA guidance documents, EU packaging waste directive filings, and customs trade data for polyolefin film imports. Bottom-up volume builds across pressure-sensitive, shrink sleeve, and in-mold label product types were cross-checked against top-down pharmaceutical packaging expenditure estimates.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, end-use industry, material substrate, and application architecture. CAGRs were derived from slope analysis of fitted trend lines applied to reconciled historical data. Industry-specific forecast inputs incorporated EU MDR serialization mandate implementation timelines and CDSCO traceability requirement phase-ins for Indian pharmaceutical exports.
Petrochemical substrate price volatility, REACH substance restriction updates, and pharmaceutical serialization equipment capex intensity are the dominant revision risks that could alter trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Speciality Vials Market