
 Air Dried Vegetables Market | 2026-2036
Air Dried Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Air Dried Vegetables Market Analysis
Ready-to-eat soup manufacturers is expanding their share of bulk air dried vegetable procurement as consumer pantry stocking normalizes post-pandemic. Van Drunen Farms leverages its Midwestern sourcing network to anchor supply contracts with North American convenience food brands. BCFoods competes on cost-efficient processing of commodity vegetables across multiple growing regions. Olam Food Ingredients controls international distribution corridors linking Indian and Egyptian production bases to European and Asian buyers.
Air dried vegetables retain cellular structure through controlled low-temperature dehydration, typically reducing moisture content to 3-5 percent while preserving rehydration ratios above 1:3 by weight for carrot and onion substrates. This physical state enables shelf-stable logistics for food manufacturers requiring twelve-month inventory cycles without cold chain expenditure. Carrots and onions dominate product type volumes due to uniform drying behavior and established agricultural scale, though spinach commands margin premiums in retail pouch formats. Soups and sauces anchor application demand through industrial procurement contracts, while snacks represents the fastest-growing application as air dried vegetable crisps penetrate convenience retail channels in Western Europe and East Asia.
FDA food facility registration and HACCP compliance shape US market access requirements for imported dehydrated vegetable ingredients, with FSMA preventive controls adding traceability obligations. The EU's REACH framework governs processing aid residues on European-sourced material, while India's FSSAI licensing mandates hygiene benchmarks for domestic dehydration units supplying export channels. Stakeholders must monitor evolving energy cost structures and carbon border adjustment mechanisms as these determine competitive positioning between solar-assisted dehydration clusters and conventional fossil-fuel operations.
Market Dynamics
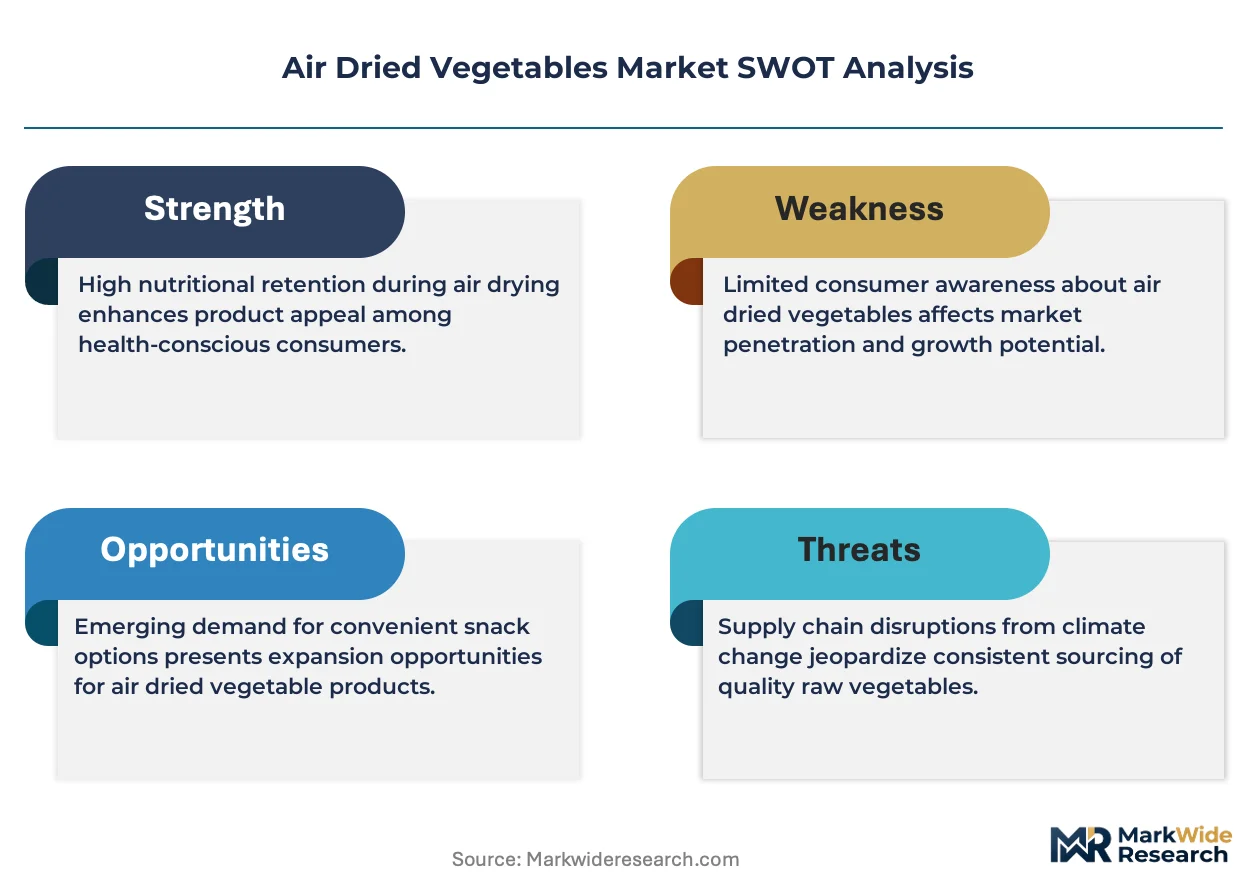
Energy cost differentials between solar-assisted and fossil-fuel dehydration clusters are reshaping processor location decisions across Mediterranean and South Asian supply zones. The EU Green Deal's farm-to-fork targets are accelerating capital migration toward reduced-energy drying infrastructure.
Growth Catalysts
- EU Green Deal compliance pressure:European processors face binding sustainability targets that favor air drying over freeze drying for carrot and onion substrates, redirecting procurement toward low-energy dehydration methods.
- Instant soup manufacturing expansion:Convenience food producers in India and Egypt are scaling bulk vegetable procurement as post-pandemic pantry stocking patterns stabilize at elevated baselines.
- Shelf-stable logistics economics:Twelve-month inventory cycles without cold chain expenditure enable food manufacturers to optimize working capital deployment across volatile agricultural input markets.
Market Restraints
- Natural gas price volatility:Conventional fossil-fuel dehydration operations in European processing clusters face margin compression from input energy cost swings that solar-assisted competitors partially hedge.
- Indian supply concentration:Export channel dependency on Jain Irrigation Systems and domestic dehydration units creates procurement risk for European and Asian buyers seeking diversified sourcing.
- Freeze drying substitution threat:Premium retail segments in Western Europe retain preference for freeze dried spinach and specialty vegetables where cellular structure preservation justifies higher unit economics.
Strategic Opportunities
- East Asian snack channel penetration:Air dried vegetable crisps remain underdeveloped in Japanese and South Korean convenience retail relative to Western European benchmarks, creating white space for format innovation.
- FSSAI export hygiene certification:Indian dehydration units achieving upgraded licensing standards can capture premium positioning in European procurement tenders that specify traceability protocols.
- Solar-thermal hybrid drying convergence:Integration of photovoltaic generation with biomass thermal backup is unifying cost and carbon performance for processors in Egypt and Rajasthan production zones.
Industry Challenges
- HACCP preventive controls implementation:FDA food facility registration requirements demand documented hazard analysis across Indian and Egyptian export-oriented dehydration units, extending compliance timelines for new market entrants.
- Rehydration ratio standardization:Absence of harmonized ISO performance benchmarks for carrot and onion substrates creates specification friction between industrial buyers and regional processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Dried Vegetables Market |
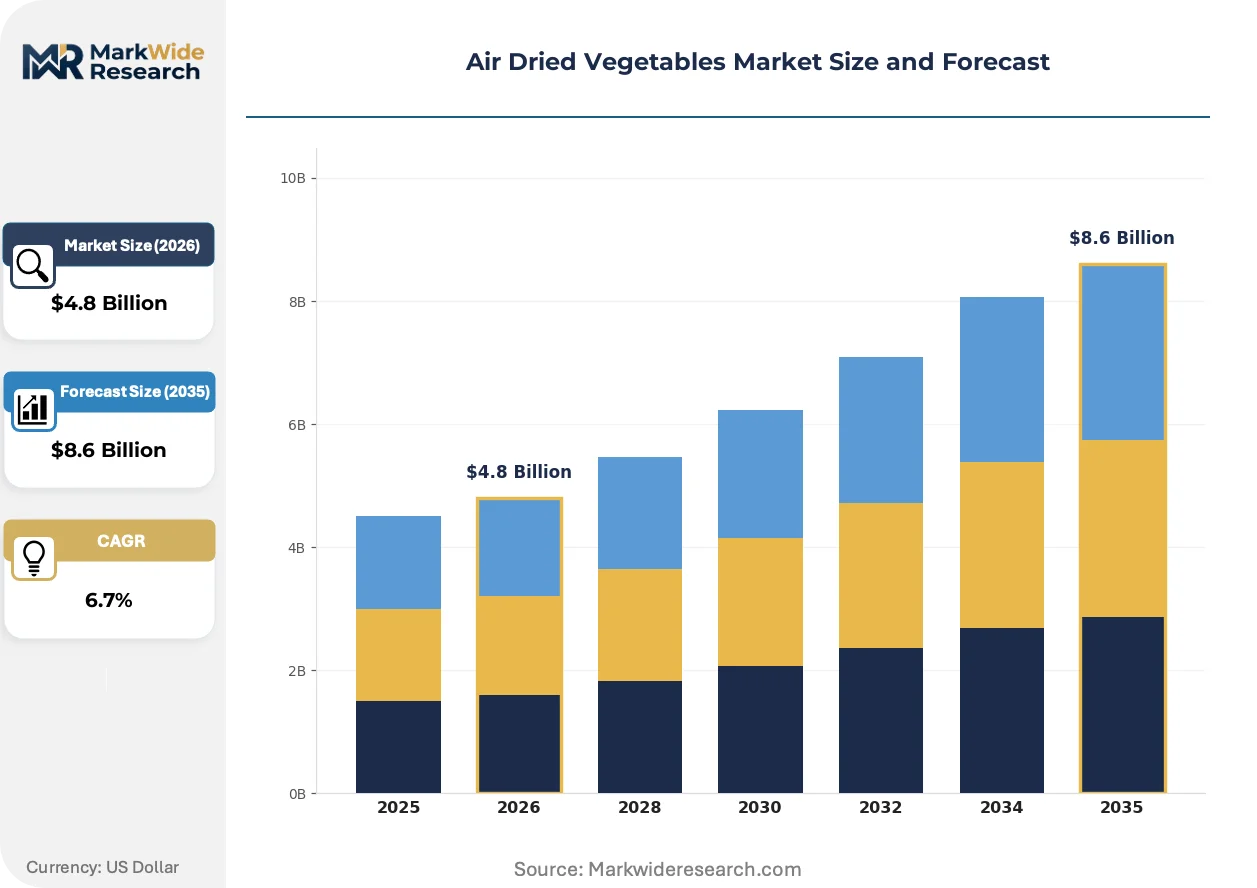
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrots, Peas, Spinach, Onions Application: Convenience Foods, Snacks, Soups, Sauces End User: Households, Food Service, Catering, Retail Packaging Type: Bags, Jars, Pouches, Vacuum-Sealed Packs |
| Companies Covered | Olam Food Ingredients, Van Drunen Farms, BCFoods, Saraf Foods Pvt. Ltd., Harmony House Foods, European Freeze Dry, Sensient Technologies, Jain Irrigation Systems, Dehydrates Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Dried Vegetables Market Emerging Trajectories
Processing technology convergence and procurement specification tightening are compressing the competitive set toward operators with integrated energy and quality control systems. Sustainability-linked sourcing requirements are becoming default rather than premium-tier contract terms.
Hybrid solar-thermal dehydration infrastructure is unifying energy cost stability with carbon intensity reduction for Mediterranean and South Asian processing clusters. Egyptian and Indian operators deploying photovoltaic-biomass hybrid systems are securing multi-year supply contracts with European convenience food manufacturers. This technology compression is marginalizing conventional fossil-fuel dehydration capacity in procurement tender evaluations.
REACH framework processing aid residue limits are tightening specification windows for European-sourced vegetable substrates. Industrial buyers are demanding expanded documentation of drying agent composition and migration testing. Snack segment manufacturers in Germany and France face the most acute compliance pressure, accelerating supplier qualification cycles toward REACH-registered dehydration units.
Industrial procurement contracts are consolidating volume commitments toward processors with dual-certification coverage across FSSAI and HACCP standards. Ready-to-eat soup manufacturers are displacing spot-market purchasing with twelve-month minimum offtake agreements that specify rehydration performance thresholds. This contract structure shift is most visible in Dutch and British manufacturing clusters sourcing from Indian and Egyptian supply bases.
Air Dried Vegetables Market Segmentation
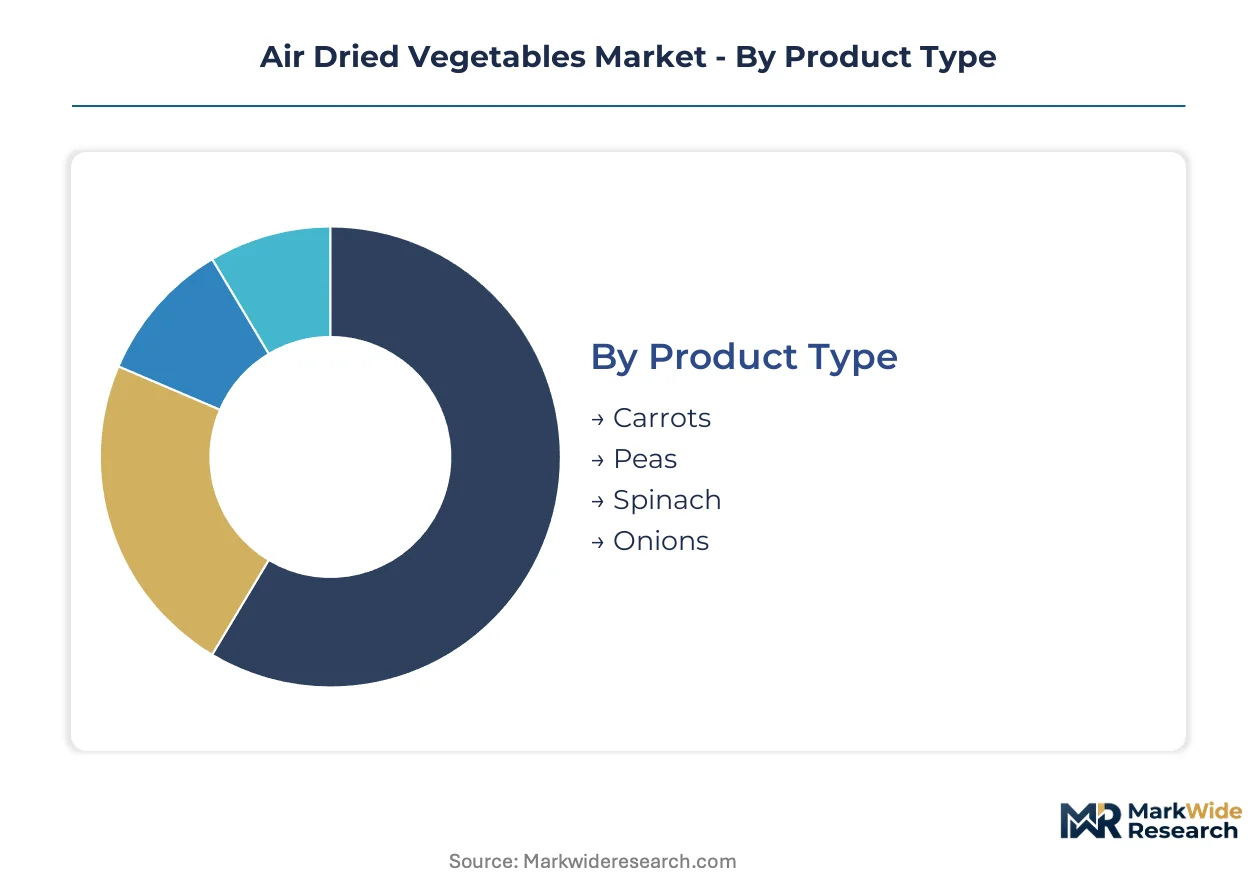
Air dried vegetable procurement specifications vary sharply across downstream channels, with industrial buyers prioritizing rehydration ratios and retail formats emphasizing visual integrity. Segment boundaries blur where snack manufacturers source carrot substrates originally developed for soup applications.
Product Type:
Upgrade cycles in dehydration equipment favor substrates with uniform cellular structure, rewarding processors that standardize around proven drying behaviors.
- Carrots:Beta-carotene retention exceeds 85% through controlled low-temperature dehydration, with rehydration ratios stabilizing above 1:3 by weight. Industrial soup manufacturers in the Netherlands and Germany anchor procurement volumes here, though margin pressure from Egyptian solar-assisted competitors is compressing contract premiums.
- Onions:Pungency compounds require precise temperature staging to prevent thermal degradation of sulfur volatiles. Ready-to-eat sauce producers in France and Britain concentrate demand for white and yellow varieties, with Jain Irrigation Systems capturing tier-one supply contracts through FSSAI-upgraded facilities.
- Peas:Starch gelatinization during drying demands modified atmospheric controls; snack channel applications in Japan show emerging interest.
- Spinach:Chlorophyll preservation commands retail pouch premiums, though freeze drying retains preference in German organic segments.
Volume placements concentrate in carrots and onions; the faster expansion belongs to spinach as clean-label retail formats proliferate.
Application:
Cost tier differentiation separates commodity industrial procurement from branded retail positioning, with specification windows widening at the premium end.
- Soups:Twelve-month inventory cycles without cold chain expenditure drive procurement economics for North American and European manufacturers. Rehydration performance thresholds now appear in minimum offtake agreements from Dutch and British manufacturing clusters.
- Snacks:Air dried vegetable crisps penetrate convenience retail channels in Western Europe and East Asia, with Japanese and South Korean markets showing particular whitespace for format innovation beyond existing Western European benchmarks.
- Convenience Foods:Instant meal applications require rapid rehydration specifications; Indian domestic retail segments show accelerating uptake.
- Sauces:Powdered vegetable bases for industrial sauce manufacturing concentrate procurement in Egyptian and Indian export channels.
Industrial contracts dominate current volumes; snack applications are climbing the fastest as retail format innovation accelerates.
End User:
Customer type fragmentation reflects divergent specification priorities, with food service operators tolerating bulk format variance that retail channels reject.
- Food Service:Institutional catering and restaurant supply chains prioritize cost-stable procurement through multi-year contracts, with HACCP compliance now baseline for Indian and Egyptian export-oriented dehydration units.
- Households:Pantry stocking normalization post-pandemic has stabilized at elevated baselines, with pouch formats commanding shelf space in German and French retail.
- Catering:Event and contract catering segments favor bulk bags for reconstitution flexibility; specifications lag industrial soup manufacturing rigor.
- Retail:Branded pouch positioning demands REACH-registered processing documentation and visual uniformity that commodity dehydration infrastructure struggles to deliver.
Food service anchors procurement scale; retail channels are gaining share fastest as clean-label positioning penetrates mainstream grocery.
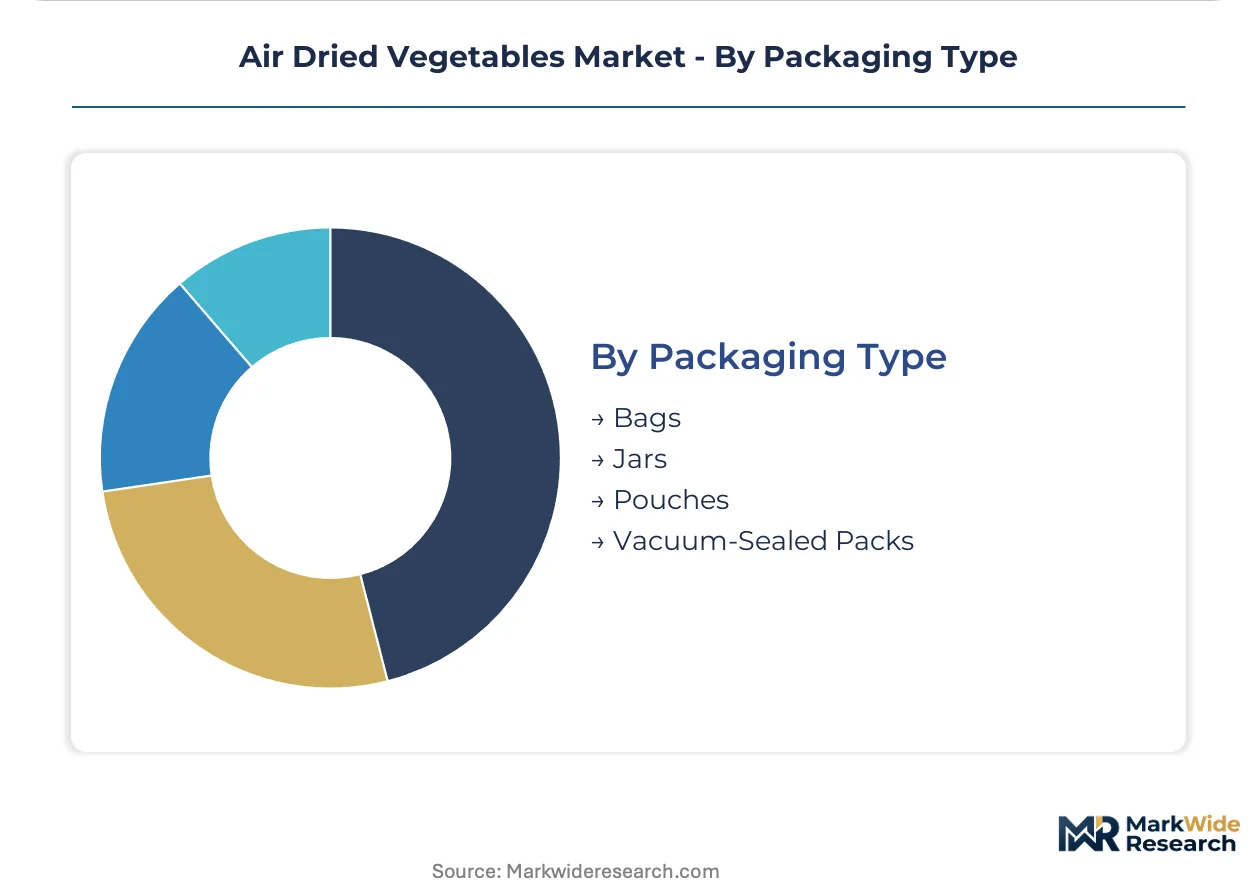
Packaging Type:
Supply concentration in vacuum-sealed formats reflects shelf-life extension requirements for export logistics, though cost-sensitive segments retain breathable alternatives.
- Vacuum-Sealed Packs:Oxygen exclusion extends shelf stability to twenty-four months, justifying premium positioning in Japanese import channels and European organic retail. Egyptian processors deploying hybrid solar-thermal infrastructure increasingly specify this format for carbon-accounted supply contracts.
- Pouches:Stand-up pouch formats with reseal features dominate Western European retail placement, with German snack manufacturers driving specification innovation around transparent window panels.
- Bags:Bulk woven polypropylene remains standard for industrial soup manufacturing procurement from Indian supply bases.
- Jars:Glass packaging retains niche positioning in premium Italian and Spanish retail segments where visual product display outweighs logistics cost considerations.
Industrial procurement concentrates in bags and vacuum-sealed formats; pouches show the steepest expansion trajectory as retail channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's food processing special economic zones attract dehydration equipment investment from domestic and export-oriented operators. Tax incentives for agricultural value-addition concentrate capacity near Nashik and Pune industrial corridors.
India
Gujarat dehydration clusters supply bulk carrot and onion substrates to European soup manufacturers through Mundra port logistics. FSSAI licensing mandates upgraded hygiene benchmarks for export-oriented units. Jain Irrigation Systems anchors procurement networks from Jalgaon and Aurangabad processing bases.
Germany
REACH framework residue limits tighten specification windows for vegetable substrates entering industrial sauce manufacturing. The EU Green Deal's farm-to-fork targets redirect capital toward reduced-energy drying infrastructure. Lower Saxony processing corridors near Hanover concentrate solar-thermal hybrid pilot installations.
Egypt
Solar-assisted dehydration clusters in the Nile Delta exploit photovoltaic cost advantages for carrot and onion exports to European buyers. Carbon border adjustment exposure drives fossil-fuel unit conversions. Beni Suef and Minya governorates anchor biomass-thermal backup integration projects.
Netherlands
Twelve-month offtake agreements from Dutch soup manufacturers specify rehydration performance thresholds above 1:3 by weight. FSMA preventive controls documentation requirements filter Indian and Egyptian supplier pools. Rotterdam-Antwerp logistics corridors optimize inventory cycle economics for North European distribution.
United States
Midwestern sourcing networks supply North American convenience food brands through Chicago-area distribution hubs. FDA food facility registration and HACCP compliance shape import requirements for dehydrated vegetable ingredients. Van Drunen Farms leverages Illinois and Wisconsin agricultural bases for industrial procurement contracts.
Air Dried Vegetables Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with private-label dehydration capacity dominating industrial soup procurement while retail pouch positioning rewards REACH-registered documentation. The vendor base organizes around three archetypes: integrated agricultural processors controlling upstream supply, specialized dehydration operators with hybrid solar-thermal infrastructure, and diversified food ingredient distributors managing international logistics corridors. Consolidation pressure concentrates in Mediterranean and South Asian supply zones where energy cost differentials determine tender outcomes. Multi-year offtake agreements displace spot-market purchasing as buyers seek rehydration ratio guarantees and carbon-accounted supply chains.
Among India-based agricultural processors, Jain Irrigation Systems exemplifies integrated upstream control, while Saraf Foods occupies a position within the specialized dehydration tier. Van Drunen Farms represents Midwestern sourcing network consolidation for North American industrial accounts. These anchors illustrate how geographic proximity to growing regions and certification coverage across FSSAI and HACCP standards determine competitive positioning in procurement evaluations.
| Leading Market Players |
|---|
| Olam Food Ingredients |
| Van Drunen Farms |
| BCFoods |
| Saraf Foods Pvt. Ltd. |
| Harmony House Foods |
| European Freeze Dry |
| Sensient Technologies |
| Jain Irrigation Systems |
| Dehydrates Inc. |
| Others |
Supply Flow & Price Mechanics
Dehydration equipment technician clusters in Maharashtra and Gujarat feed labor-cost differentials into pricing-tier spreads, with FSSAI-certified units commanding premiums over uncertified competitors while Egyptian solar-assisted operations undercut European fossil-fuel processors on energy-adjusted quotes.
Pricing Analysis
Short lead-time premiums separate emergency procurement from contract-scheduled deliveries, with Dutch soup manufacturers paying above-baseline rates for expedited Indian supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with REACH-registered documentation and FSSAI-hygiene upgrades driving tier placement. Pricing pressure stems from Egyptian photovoltaic-biomass hybrid entrants compressing margins for conventional European dehydration units. Industrial soup manufacturers exhibit highest price sensitivity due to commodity procurement volumes, while Japanese snack importers tolerate premium positioning for vacuum-sealed carbon-accounted supply.
Supply Chain Analysis
Dual-sourcing requirements from Dutch and British manufacturers mandate multi-supplier qualification across Indian and Egyptian dehydration bases, reducing Jain Irrigation Systems concentration risk. Geographic supply draws from India, Egypt, and the United States, with raw material dependencies on carrot and onion agricultural cycles, natural gas or solar-thermal energy inputs, and REACH-compliant processing aids. Supply chain risk centers on carbon border adjustment exposure for fossil-fuel European operations. Distribution runs through Rotterdam-Antwerp logistics corridors for North European manufacturing clusters and Mundra port channels for Indian export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as energy cost differentials force conventional fossil-fuel dehydration capacity toward obsolescence, eliminating margin-weak operators unable to fund solar-thermal hybrid conversions.
For Market Incumbents: Hedge against Egyptian and Indian solar-assisted competitors by securing captive agricultural supply through backward integration into Nashik and Jalgaon growing regions. Accelerate FSSAI and HACCP dual-certification coverage to maintain procurement eligibility for Dutch and British manufacturing clusters. Prioritize hybrid solar-thermal infrastructure deployment to neutralize carbon border adjustment exposure.
For New Entrants and Emerging Players: Japanese and South Korean snack channel buyers remain underserved relative to Western European benchmarks, presenting white-space entry through air dried vegetable crisp format innovation. Target Egyptian solar-thermal hybrid clusters for cost-base advantages in European export tenders. Pursue FSSAI export hygiene certification as the primary qualification lever for premium procurement positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized dehydration operators possessing hybrid solar-thermal infrastructure given EU Green Deal compliance pressure accelerating capital migration toward reduced-energy methods. Long-term viability over the coming decade favors processors with integrated photovoltaic-biomass systems and dual-certification coverage. Monitor carbon border adjustment implementation timelines as the critical inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Thermal Infrastructure Deployment | Egyptian and Indian processors secure multi-year European supply contracts through carbon-accounted dehydration methods. |
| FSSAI-HACCP Dual Certification Investment | Export-oriented dehydration units capture premium positioning in Dutch and British procurement tenders specifying traceability protocols. |
| Backward Integration into Agricultural Supply | Processors controlling Nashik and Jalgaon growing regions neutralize input cost volatility for carrot and onion substrates. |
| East Asian Snack Channel Format Innovation | Air dried vegetable crisp penetration in Japanese and South Korean convenience retail unlocks fastest-growing application demand. |
| REACH Processing Aid Compliance Program | German and French snack manufacturers qualify suppliers through residue documentation and migration testing protocols. |
Methodological Framework
Multi-period observation of rehydration ratio benchmarks, energy cost structures, and certification adoption rates anchored the trend analysis, supplemented by interviews with dehydration plant managers, procurement leads at European soup manufacturers, FSSAI regulatory affairs officers, and Egyptian solar-thermal project developers. Secondary validation drew from EU Green Deal policy documents, REACH framework amendments, FSSAI licensing databases, and customs trade records for dehydrated vegetable flows. Bottom-up facility capacity assessments and top-down demand modeling from end-use applications were triangulated for convergence.
Input-output matrix framing connected agricultural input volumes through dehydration capacity utilization to downstream procurement contracts across the projection horizon. Segmentation dimensions modeled include product substrate type, application channel, end-user category, and packaging format, with regional regulatory clusters overlaying geographic splits. CAGRs were derived from fitted trend extrapolation against historical procurement contract growth. Industry-specific forecast inputs incorporated solar-thermal adoption curves and carbon border adjustment exposure scenarios.
Revisions become necessary when EU Green Deal implementation timelines accelerate, natural gas price volatility exceeds modeled ranges, or FSSAI hygiene standards tighten beyond current upgrade trajectories. Deviation in carbon border adjustment enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
North America Sweet Potatoes Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Sweet Potatoes Market
Vegetables
Microgreens Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
UAE Tomato Market
Vegetables
Potato Market
Vegetables
Fresh Vegetables Market
Vegetables
Artichokes Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Greenhouse Produce Market
Vegetables
Vegetable Chutney Market
Vegetables
North America Christmas Tree Market
Vegetables
Yam Products Market