
 Europe Swine Feed Premix Market | 2026-2036
Europe Swine Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Swine Feed Premix Market Foresight
Specialized additive formulation revenue is rewriting margin distribution across the value chain. Cargill Inc. leverages its backward integration into amino acid production to capture formulation premiums. Nutreco N.V. anchors its position through R&D intensity in gut health microencapsulation. Evonik Industries AG dominates methionine supply, a critical premix input for European lean-meat production targets.
Europe swine feed premix denotes a homogenous blend of vitamins, minerals, amino acids, and functional additives dosed at 0.5-3.0% of total feed weight, manufactured through precision mixing and microencapsulation to ensure nutrient stability during pelleting at 80-90°C. Its primary purpose is to standardize nutritional delivery across commercial herd batches while enabling targeted intervention for growth performance and disease prevention. Medicated premix holds mature volume leadership as antibiotic-alternative regulations harden, while vitamin premix commands margin concentration due to raw material volatility and formulation complexity. Powder form sustains broad adoption across mid-scale operations, though pelletized premix is gaining traction among automated feeding systems in Denmark and the Netherlands.
EMA guidelines on veterinary medicinal products and EFSA feed additive authorizations shape product registration timelines and label claims across member states. The EU Green Deal livestock methane targets and national nitrate directives in Germany and France are redirecting premix portfolios toward enzyme and probiotic platforms. Stakeholders must monitor the interplay between ECHA biocidal substance reviews and emerging precision fermentation inputs to anticipate formulation cost trajectories and compliance exposure.
Market Dynamics
EU Green Deal livestock methane targets and EFSA feed additive authorizations are compressing formulation timelines while accelerating premix portfolio turnover across European commercial farms. Manufacturers must now synchronize R&D cycles with tightening environmental compliance windows.
Growth Catalysts
- EFSA Novel Food and Feed Additive Pathways:Streamlined safety assessments for enzyme and probiotic platforms are accelerating product registration across member states.
- Denmark Automated Feeding Infrastructure:Precision dosing systems in integrated pork operations are standardizing pelletized premix procurement at scale.
- Lean-Meat Production Mandates:Amino acid optimization protocols in Spanish and German commercial herds are elevating premix specification intensity.
Market Restraints
- Vitamin Raw Material Volatility:Supply concentration for fat-soluble vitamin precursors in Asian chemical hubs exposes European formulators to input cost swings.
- ECHA Biocidal Substance Review Cycles:Extended hazard classifications for preservative additives are freezing label claims and extending reformulation lead times.
- Antibiotic-Alternative Efficacy Gaps:Functional additive performance variability in high-pathogen-pressure environments limits complete therapeutic substitution.
Strategic Opportunities
- Poland Consolidating Integrated Operations:Underpenetrated large-scale pork producers present volume aggregation potential for premix suppliers with formulation customization capabilities.
- Precision Fermentation Inputs:Emerging microbial protein and bioactive compound production methods are converging with premix manufacturing to reduce reliance on agricultural commodity streams.
- EU F-Gas Regulation Phase-Down:Refrigeration-dependent feed additive storage mandates are creating demand for thermostable microencapsulation technologies.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in heat-stable nutrient matrix design remains concentrated among aging technical workforces in the Netherlands and Germany.
- Multi-State Registration Synchronization:Divergent national implementation of EMA veterinary medicinal product guidelines across France, Spain, and Italy fragments compliance workflows.
- Legacy Feed Mill Integration:Retrofitting mid-scale Polish and Romanian operations for precision premix dosing requires capital deployment against compressed payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Swine Feed Premix Market |
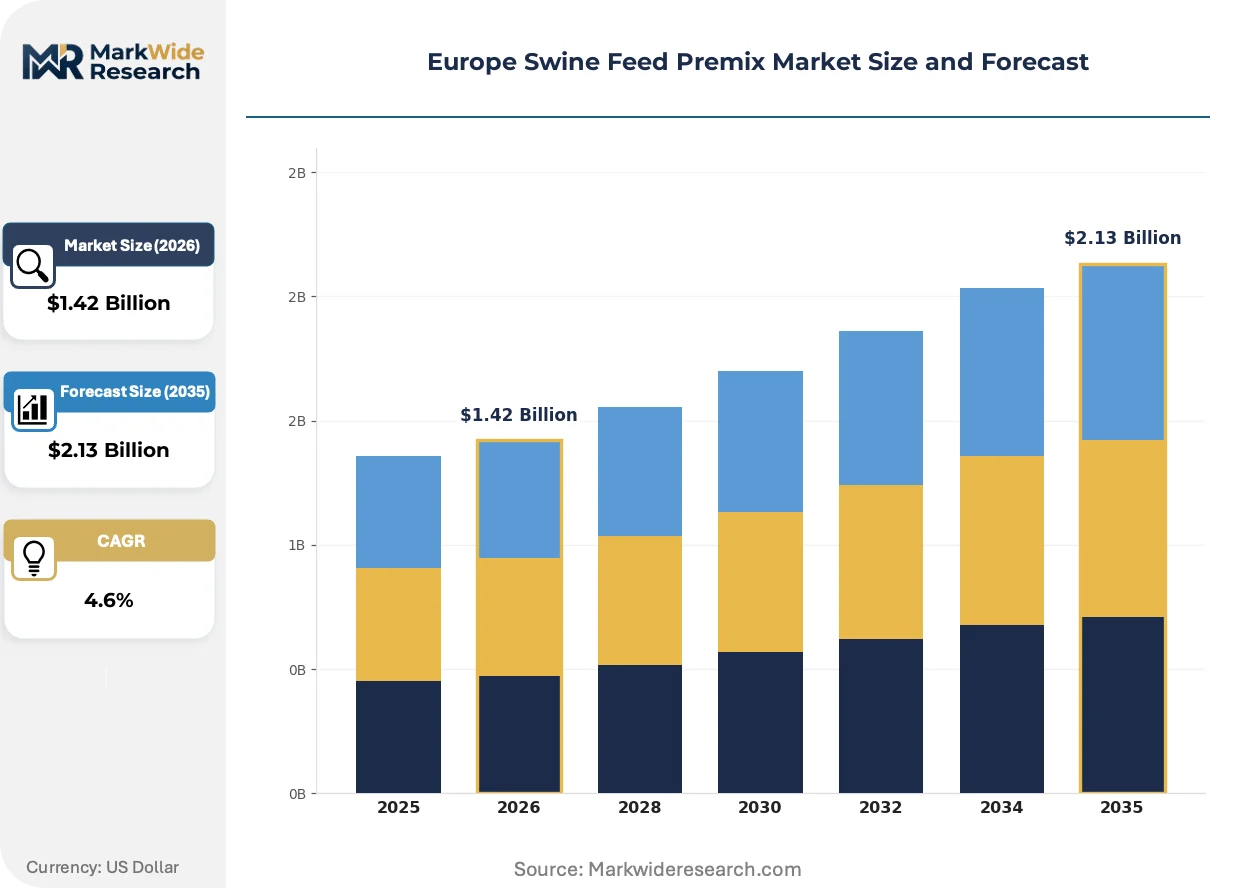
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated Premix, Non-Medicated Premix, Vitamin Premix, Mineral Premix End User: Commercial Farms, Small Hold Farmers, Co-operative Groups, Research Institutions Distribution Channel: Online Retail, Offline Retail, Direct Sales, Agricultural Cooperatives Form: Powder, Granules, Pellets, Liquid |
| Companies Covered | Cargill Inc., Nutreco N.V., Archer Daniels Midland Company, Koninklijke DSM N.V., Land O'Lakes Inc., Evonik Industries AG, ForFarmers N.V., Alltech Inc., Huvepharma Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Swine Feed Premix Market Shifts & Advancements
Microencapsulation and precision fermentation are compressing traditional nutrient delivery economics while regulatory pressure on methane emissions redirects R&D investment toward functional additive platforms. These forces are rewriting technical specifications across the premix value chain.
Heat-stable microencapsulation of organic trace minerals and fat-soluble vitamins is collapsing the performance gap between powder and pelletized premix formats. Danish and Dutch automated feeding operations are adopting these formulations at accelerated replacement cycles. The technology is collapsing legacy pelleting temperature constraints that previously capped nutrient inclusion rates.
EU Green Deal national implementation plans and F-Gas Regulation refrigerant phase-down schedules are tightening cold-chain requirements for heat-sensitive additives. Industrial consequence includes mandatory investment in thermostable formulation infrastructure or outsourced climate-controlled logistics. Medicated premix segments in Germany and France are responding with accelerated microencapsulation R&D partnerships.
Integrated pork operations in the Netherlands and Spain are consolidating premix procurement through direct manufacturer contracts, bypassing traditional distributor networks. This channel compression is displacing regional feed compounders from specification influence. The shift is most visible in Denmark, where cooperative buying groups are centralizing additive selection authority.
Europe Swine Feed Premix Market Segmentation
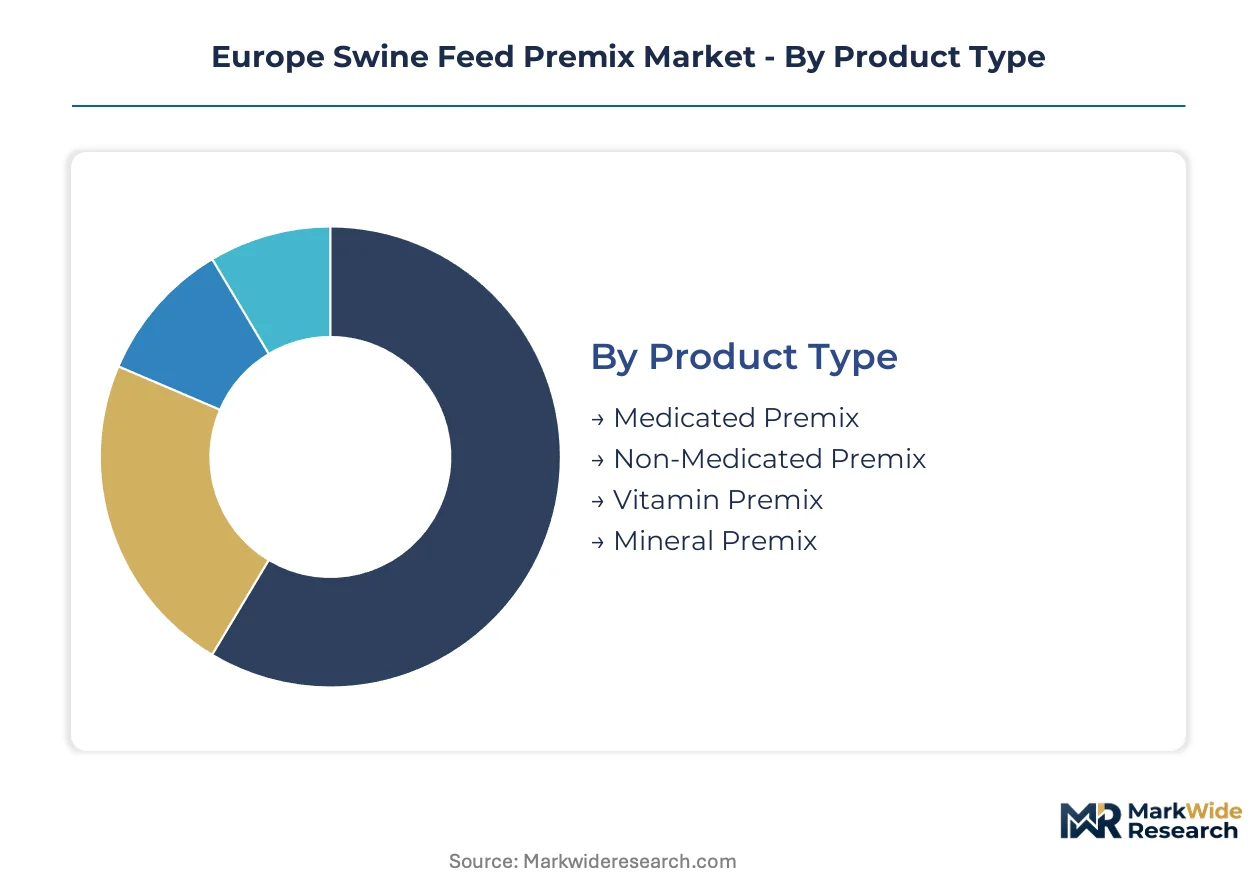
Premix segmentation in Europe maps directly to regulatory exposure cycles and procurement consolidation patterns. Each dimension carries distinct margin profiles and compliance timelines that reshape supplier positioning across member states.
Product Type:
Medicated premix cycles through regulatory reauthorization fastest, while vitamin premix endures longest formulation stability windows.
- Medicated Premix:Contains veterinary medicinal additives at therapeutic or sub-therapeutic levels, requiring EMA marketing authorization renewal every five years. Spanish and German commercial farms drive procurement as antibiotic-alternative regulations harden, though ECHA biocidal reviews extend reformulation lead times.
- Vitamin Premix:Blends fat-soluble and water-soluble vitamins at standardized IU concentrations, commanding formulation premiums due to raw material volatility. Dutch integrated operations specify high-inclusion variants for lean-meat production targets, while Asian precursor supply concentration exposes margin compression.
- Non-Medicated Premix:Functional additive platforms excluding regulated medicinal compounds, accelerating registration through EFSA feed additive pathways.
- Mineral Premix:Organic and inorganic trace element matrices, standardizing across mid-scale Polish operations with heat-stable microencapsulation adoption.
Medicated premix anchors the volume base while vitamin premix gains share at the steepest rate.
End User:
Procurement scale separates cost-tier access, with volume thresholds determining formulation customization depth.
- Commercial Farms:Large-scale integrated pork operations with direct manufacturer contracting, bypassing distributor markups. Denmark and Netherlands operations specify pelletized premix for automated feeding infrastructure, while Polish consolidators aggregate multi-site procurement.
- Co-operative Groups:Centralized buying authorities pooling member demand, prevalent in Danish agricultural cooperatives. These entities standardize additive selection across affiliated farms, compressing regional compounder influence.
- Small Hold Farmers:Fragmented operations relying on distributor networks and generic premix specifications.
- Research Institutions:Trial-scale procurement for feed additive efficacy validation under EFSA novel food pathways.
Commercial farms dominate absolute volume while co-operative groups expand most quickly as procurement centralization accelerates.
Distribution Channel:
Channel selection reflects feed mill automation levels and cold-chain infrastructure maturity across member states.
- Direct Sales:Manufacturer-to-farm contracting for large-scale integrated operations, eliminating distributor margins. Netherlands and Spain pork integrators lead this shift, consolidating specification authority with premix formulators.
- Agricultural Cooperatives:Member-owned procurement hubs aggregating demand across regional farm clusters, standardizing premix selection at scale.
- Offline Retail:Traditional feed compounder and distributor networks serving mid-scale operations without direct manufacturer access.
- Online Retail:Emerging platform procurement for small-hold farmers and specialty additive sourcing.
Direct sales anchors the volume base while agricultural cooperatives gain share at the steepest rate.
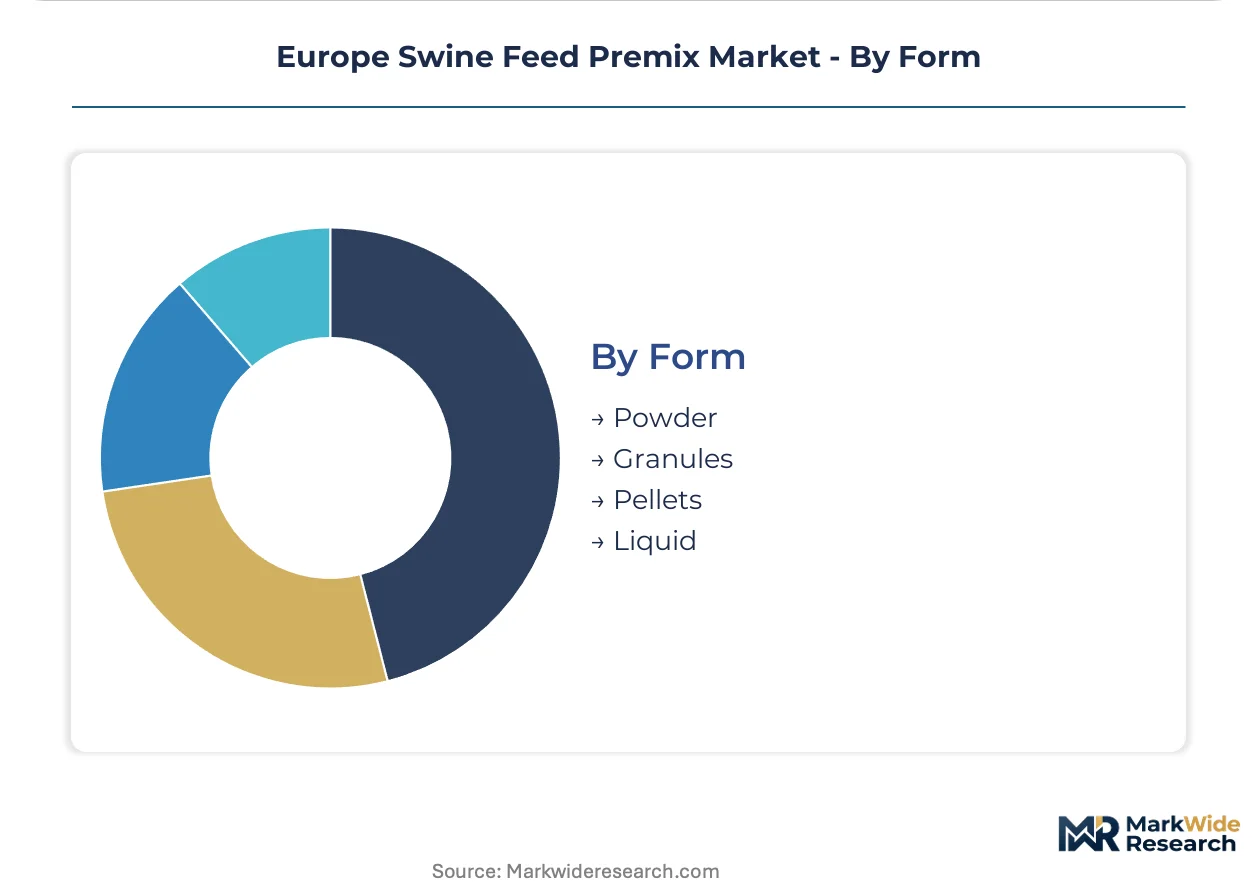
Form:
Thermal stability requirements during pelleting separate application suitability across feed mill infrastructure tiers.
- Powder:Standard particle-size premix for manual or mechanical dosing systems, sustaining broad adoption across mid-scale Polish and Romanian operations. Legacy feed mill compatibility preserves volume, though dust losses and segregation limit precision.
- Pellets:Compressed premix with enhanced flowability for automated feeding systems, accelerating replacement cycles in Denmark and Netherlands precision pork operations. Heat-stable microencapsulation collapses nutrient degradation gaps with powder formats.
- Granules:Intermediate particle size reducing segregation versus powder, bridging manual and automated dosing applications.
- Liquid:Pump-dosed premix for specialized additive delivery, limited by EU F-Gas Regulation cold-chain requirements for heat-sensitive compounds.
Powder anchors the volume base while pellets gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain and Germany deploy premix at higher therapeutic intensities than Poland or the Netherlands, where lean-meat amino acid optimization dominates formulation spend.
Spain
Commercial pork integrators in Aragon and Catalonia drive medicated premix volumes as EFSA antibiotic-alternative pathways harden label requirements. The national nitrate directive pressures feed mills toward enzyme-supplemented formulations. Zaragoza-based operations consolidate procurement through direct manufacturer contracts, bypassing regional compounders.
Germany
Lower Saxony's dense hog belt specifies high-inclusion vitamin premix for lean-carcass premiums at slaughter. The EU Green Deal livestock methane targets redirect R&D spend toward probiotic microencapsulation. Münsterland feed clusters retrofit pelleting lines for heat-stable nutrient matrices at 80-90°C processing thresholds.
Netherlands
Brabant and Gelderland integrated operations standardize pelletized premix for automated feeding infrastructure. ECHA biocidal substance reviews freeze preservative additive claims, extending reformulation cycles. Eindhoven-region cooperatives centralize specification authority, compressing distributor influence across member farms.
Poland
Masovian and Greater Poland provinces aggregate multi-site procurement as consolidation accelerates among underpenetrated large-scale producers. National implementation of EU F-Gas Regulation phase-down schedules tightens cold-chain requirements for heat-sensitive additives. Poznań-area mills adopt powder premix for legacy mechanical dosing systems.
Denmark
Jutland cooperative buying groups pool demand across 2,000-plus member farms, standardizing additive selection at scale. EMA veterinary medicinal product guidelines synchronize with national antibiotic reduction targets. Horsens-region precision pork operations accelerate replacement cycles for microencapsulated formulations.
Europe Swine Feed Premix Market Competitive Landscape
Capability concentration sits with formulation specialists; scale advantage sits with diversified nutrition conglomerates. The vendor base stratifies across three tiers: integrated chemical producers controlling amino acid inputs, premix specialists with microencapsulation R&D intensity, and regional feed compounders losing specification influence. Dominant competitive moves include backward integration into vitamin precursor production and direct contracting with integrated pork operations to bypass distributor networks.
Within the integrated chemical tier, Cargill Inc. and Evonik Industries AG exemplify upstream control over critical premix inputs. Nutreco N.V. occupies a position among formulation specialists emphasizing gut health delivery technologies. These three entities represent divergent strategic anchors: captive amino acid supply, methionine dominance, and R&D-intensive microencapsulation platforms respectively.
| Leading Market Players |
|---|
| Cargill Inc. |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Land O'Lakes Inc. |
| Evonik Industries AG |
| ForFarmers N.V. |
| Alltech Inc. |
| Huvepharma Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors absorb vitamin precursor shipments from Asian chemical hubs, translating container cost swings into margin compression for European formulators while downstream buyers face tiered premix pricing based on thermal stability certification.
Pricing Analysis
Long-term offtake contracts dominate procurement between Dutch integrated pork operations and premix manufacturers, insulating volume buyers from vitamin raw material volatility that spot purchasers in Poland absorb directly. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated formulations certified for 90°C pelleting from uncoated powder alternatives. Pricing pressure stems from ECHA biocidal substance review cycles extending reformulation lead times and freezing label claims. Commercial farms with automated feeding infrastructure demonstrate lowest price sensitivity, while small-hold farmers in Romania and Bulgaria face acute cost compression.
Supply Chain Analysis
Contract manufacturing concentration sits with Cargill's Ghent and Krefeld facilities alongside Nutreco's Boxmeer and Saint-Nolff plants, which together process the majority of thermostable premix volumes for northwestern European markets. Raw material supply draws from Chinese vitamin precursor producers, German methionine synthesis operations, and Spanish enzyme fermentation facilities. Single-source vulnerability concentrates in fat-soluble vitamin A and E precursor streams from Zhejiang and Shandong chemical clusters. Distribution runs through direct manufacturer contracting for large-scale integrators, bypassing traditional feed compounder networks in the Netherlands and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment; EMA veterinary medicinal product authorizations and EFSA feed additive pathways create five-year switching costs that lock in formulation relationships.
For Market Incumbents: Pre-empt emerging precision fermentation entrants by securing exclusive offtake agreements with microbial protein startups in Denmark and the Netherlands, while accelerating heat-stable microencapsulation R&D to defend against Asian vitamin precursor supply disruptions. Backward integration into amino acid production remains the critical lever for margin defense. For New Entrants and Emerging Players: Mid-scale Polish pork operations upgrading from legacy mechanical dosing systems represent the most penetrable entry point, as these consolidators seek formulation customization capabilities absent from regional feed compounders. Non-medicated functional additive platforms bypass EMA authorization timelines and accelerate through EFSA pathways. Target cooperative buying groups in Denmark with pelletized premix samples calibrated to automated feeding specifications. For Investors and Strategic Acquirers: Microencapsulation specialists with proven heat-stable nutrient matrices command scarcity premiums as formulation chemist talent concentrates among aging technical workforces in the Netherlands and Germany. Monitor ECHA biocidal substance review outcomes for preservative additives as an inflection signal; extended hazard classifications would trigger consolidation among smaller formulators unable to absorb reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Production | Cargill and Evonik capture formulation premiums through captive methionine and lysine supply. |
| Heat-Stable Microencapsulation R&D Partnerships | Danish and Dutch operations adopt these formulations at accelerated replacement cycles for automated systems. |
| Direct Manufacturer Contracting with Pork Integrators | Netherlands and Spain bypass distributor networks, compressing regional compounder influence. |
| Precision Fermentation Input Sourcing | Emerging microbial protein production reduces reliance on agricultural commodity price volatility. |
| Multi-State Registration Synchronization Investment | Fragmented EMA implementation across France, Spain, and Italy requires compliance workflow unification. |
Research Methodology
Operator-level perspectives from premix formulation chemists, commercial farm procurement directors, feed mill operations managers, and EMA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EFSA feed additive authorization databases, ECHA biocidal substance review filings, EU customs trade data for vitamin precursor imports, and SEC 10-K disclosures from listed nutrition conglomerates. Bottom-up volume modeling across member states triangulated with top-down value estimates from premix manufacturer revenue disclosures.
Scenario-bracketing around EU Green Deal methane target implementation timelines and F-Gas Regulation phase-down schedules shaped the projection horizon. Segmentation dimensions modeled include product type, end user procurement scale, distribution channel structure, and thermal stability form factor. CAGRs derived from regression analysis against historical premix intensity ratios and pork production forecasts. Industry-specific inputs incorporated EMA veterinary medicinal product reauthorization cycles and EFSA novel feed additive approval velocities.
Macroeconomic conditions sit as an overlay; deviation in euro-zone energy costs, Asian vitamin precursor pricing, or Baltic freight rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation cadence and consolidation velocity among Polish pork operations. Quarterly review of ECHA biocidal substance review announcements and EFSA feed additive authorization queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Global Dinotefuran Market