
 North America Feed Pigments Market | 2026-2036
North America Feed Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Pigments Market Analytics
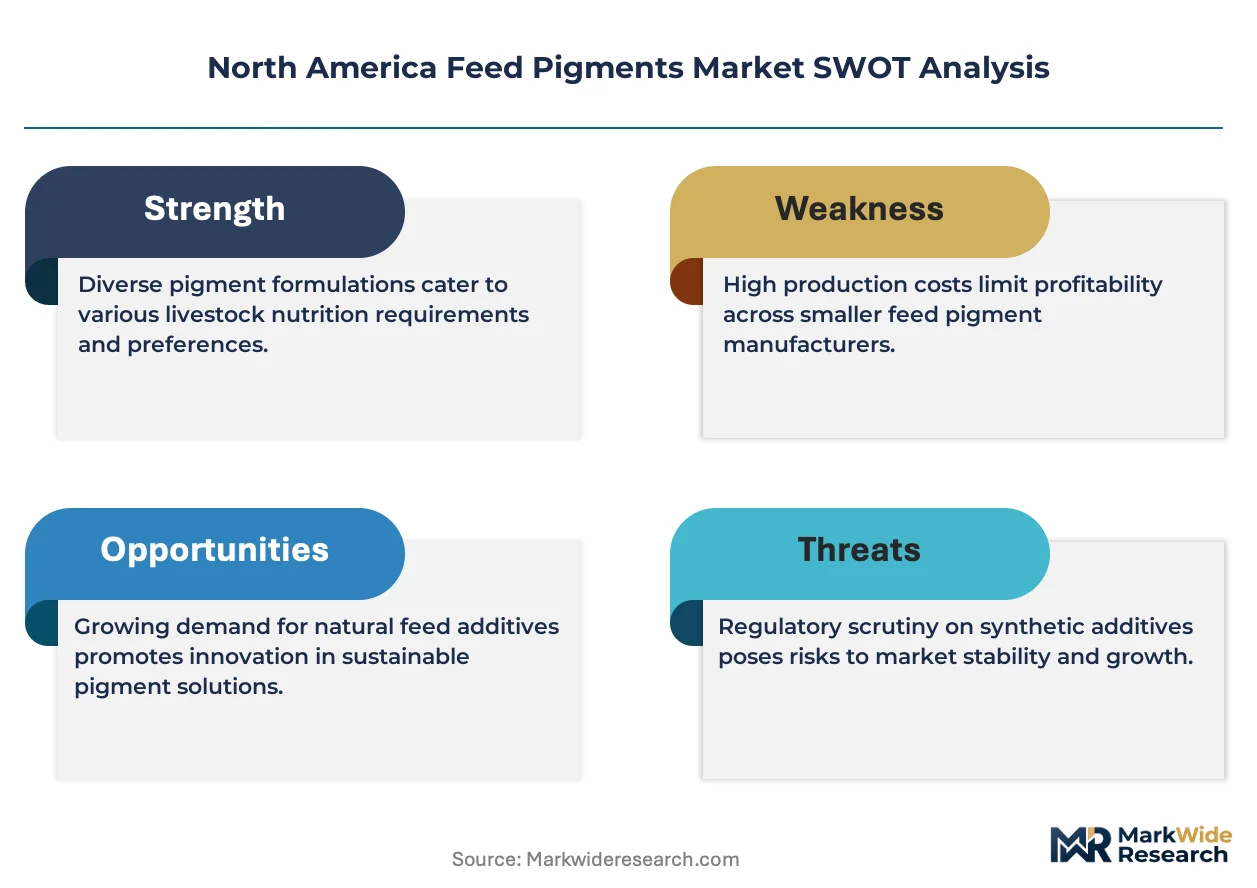
The gap between premium natural pigment formulations and commodity synthetic grades is broadening as livestock producers face divergent customer expectations. BASF SE leverages its integrated petrochemical feedstock position to sustain cost leadership in bulk astaxanthin and canthaxanthin output for broiler and layer operations. Kemin Industries Inc differentiates through its specialized delivery systems that improve pigment bioavailability in ruminant feed applications.
Feed pigments are color-active compounds, primarily carotenoids and phycocyanin derivatives, dosed at parts-per-million levels to impart desired hues to animal tissues, eggs, and finished meat products. Synthetic canthaxanthin and astaxanthin dominate volume owing to standardized potency and lower unit costs, while natural spirulina extracts command premium positioning in antibiotic-free and organic-certified feed programs. The poultry application segment leads absolute consumption due to yolk color grading systems that directly influence consumer purchase decisions at retail. Powder formulations occupy the largest share of the form dimension because of blending compatibility with standard feed mill equipment and extended shelf stability.
The FDA's color additive regulations under 21 CFR 73.75 and 21 CFR 73.200 establish permitted pigment sources and maximum inclusion rates for target species, while the USDA's Process Verified Program creates market access differentiation for producers documenting natural pigment usage. Health Canada and PMRA coordinate closely with U.S. regulators on cross-border feed ingredient approvals, reducing friction for suppliers operating throughout the integrated North American supply base. Stakeholders must monitor evolving clean-label certification requirements and assess whether backward integration into algal or microbial fermentation feedstock production will secure margin protection against volatile petrochemical-derived intermediate costs.
Market Dynamics
The divergence between commodity synthetic pigments and premium natural alternatives is restructuring procurement patterns across U.S. poultry and swine operations, as integrators weigh cost efficiency against clean-label certification requirements from downstream retail partners.
Growth Catalysts
- Layer Yolk Grading Systems:Retail chains in the U.S. Southeast now mandate specific yolk color scores, compelling feed mills to standardize carotenoid inclusion rates across contract grower networks.
- FDA 21 CFR 73.75:Clear regulatory pathways for canthaxanthin and astaxanthin approvals reduce formulation uncertainty, accelerating adoption in broiler skin pigmentation programs.
- Midwest Concentration:Iowa, Illinois, and Minnesota host the continent's densest cluster of large-scale swine finishing operations, generating economies of scale in bulk pigment premix procurement.
Market Restraints
- Petrochemical Intermediate Volatility:Synthetic astaxanthin production relies on acetone and petrochemical-derived precursors, exposing margins to crude oil price swings.
- Canadian Border Synchronization:Health Canada and PMRA approval lags relative to FDA clearances delay cross-border product launches by 8-14 months.
- Natural Extract Yield Limits:Spirulina and Haematococcus pluvialis cultivation face photosynthetic efficiency ceilings that constrain batch-to-batch color consistency.
Strategic Opportunities
- Antibiotic-Free Certification:USDA Process Verified Program documentation of natural pigment sourcing opens premium channel access for mid-size layer operations.
- Microbial Fermentation:Yeast-derived carotenoid platforms bypass agricultural weather risk and offer year-round production stability.
- Direct-to-Integrator Distribution:Bypassing traditional feed mill intermediaries allows pigment suppliers to capture margin and secure volume commitments from top-10 U.S. poultry producers.
Industry Challenges
- Algal Cultivation Expertise Scarcity:Commercial-scale photobioreactor operation requires specialized phycologists and process engineers in short supply across North American labor markets.
- Dual Jurisdiction Compliance:Simultaneous FDA and Health Canada dossier preparation demands redundant toxicology studies and analytical method validations.
- Legacy Feed Mill Equipment Compatibility:Liquid pigment emulsion systems require spray nozzle retrofits that many Midwest facilities have deferred since the 2010s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Pigments Market |
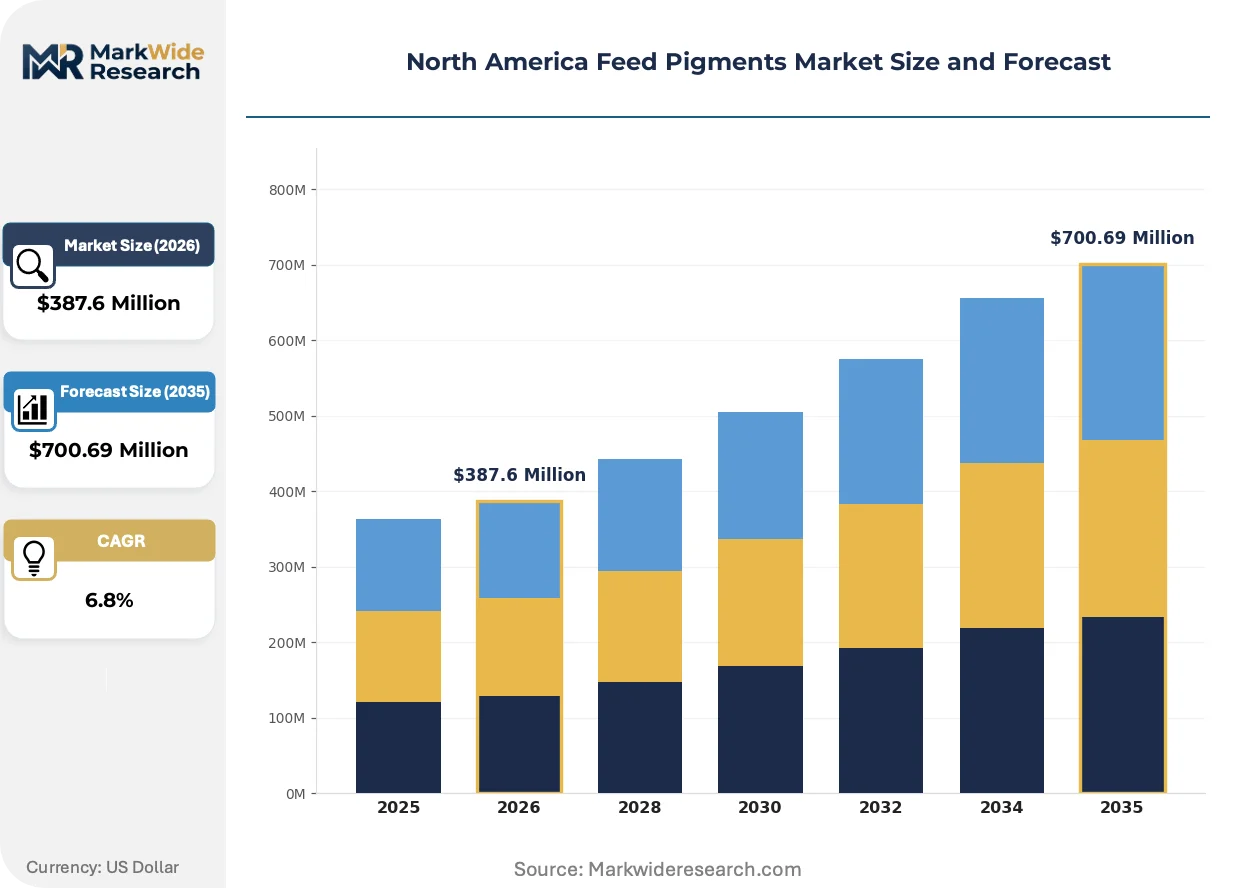
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carotenoids, Spirulina, Anthocyanins, Curcumin Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Paste Source: Natural, Synthetic, Organic, Inorganic |
| Companies Covered | BASF SE, Kemin Industries Inc, DSM, Novus International Inc, Synthite Industries Ltd, DSM-Firmenich, Vitafor NV, Cyanotech Corporation, Nutrex NV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Pigments Market Evolving Landscape
Encapsulation technologies and fermentation-derived alternatives are compressing the performance gap between synthetic and natural pigment platforms, while regulatory clarity on novel production methods accelerates commercialization timelines.
Microencapsulated carotenoid beadlets with modified starch coatings are integrating into high-temperature pelleting processes without thermal degradation, enabling broiler integrators in Arkansas and Georgia to maintain skin color consistency across summer production cycles. Layer operations report 12-15% bioavailability improvements versus standard powder formulations. This integration is compressing the premium commanded by synthetic grades in standard broiler programs.
Health Canada's Veterinary Drugs Directorate has aligned with FDA timelines for novel microbial pigment sources, collapsing the historical 18-month approval gap that delayed Canadian market entry. The synchronized review process now permits simultaneous U.S.-Canada product launches. Ruminant feed applications face the steepest compliance burden under this framework.
Certification-driven procurement now separates premium contract tiers from commodity supply agreements, with integrators in the Carolinas and Virginia mandating third-party verification of natural pigment claims for retail-branded egg programs. Traditional spot-market purchasing persists in undifferentiated broiler channels. This bifurcation concentrates margin in supplier relationships that can document chain-of-custody from fermentation or algal source to finished feed.
North America Feed Pigments Market Segmentation
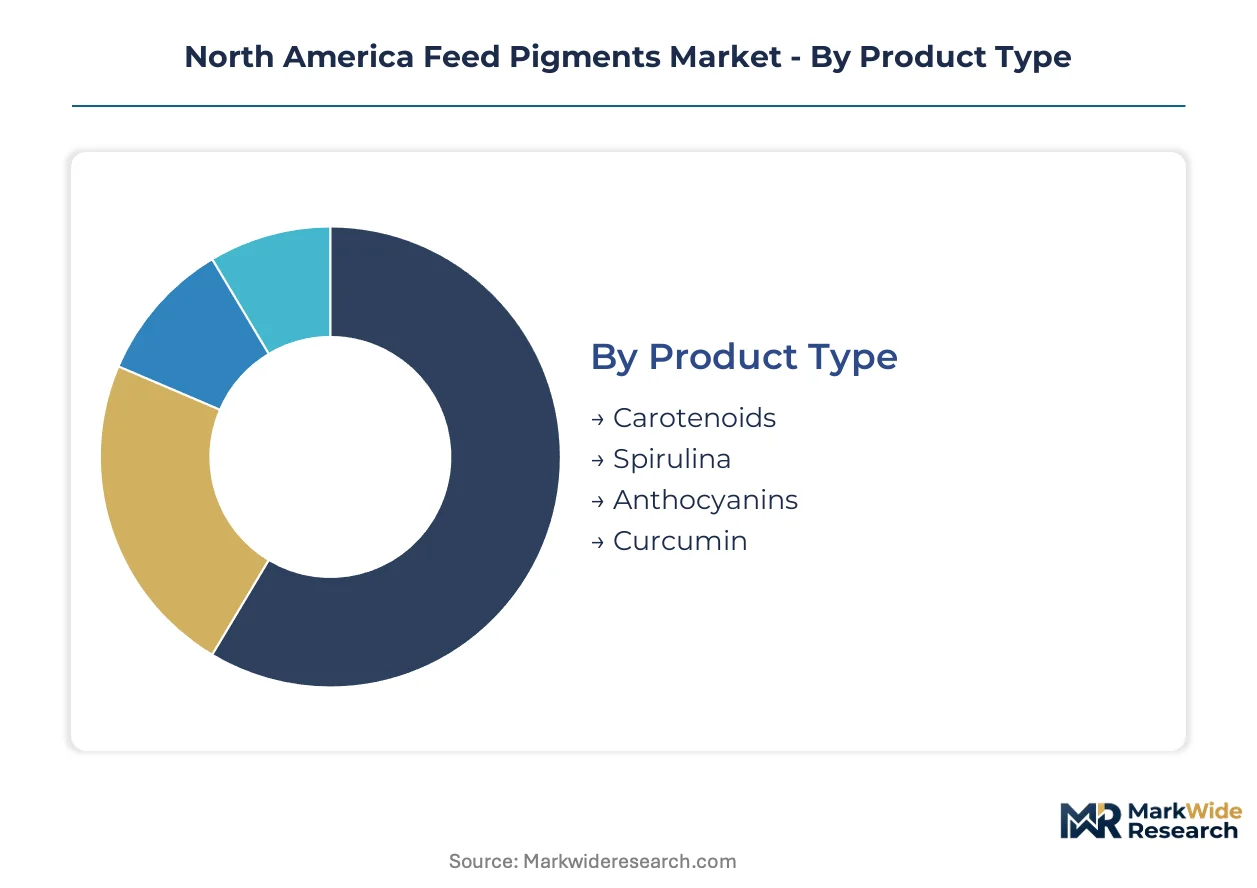
Feed pigment purchasing decisions diverge sharply across livestock categories and formulation requirements. Integrators select pigment types based on species-specific tissue deposition kinetics, regulatory constraints, and downstream certification demands from retail partners.
Product Type:
Cost tier separates commodity synthetics from premium natural extracts in procurement workflows.
- Carotenoids:Synthetic astaxanthin and canthaxanthin dominate volume through standardized potency and lower unit costs. Broiler integrators in Arkansas and Georgia standardize inclusion rates for skin pigmentation consistency across summer production cycles.
- Spirulina:Phycocyanin-rich extracts command premium positioning in antibiotic-free and organic-certified feed programs. Layer operations in the Carolinas mandate third-party verification of natural pigment claims for retail-branded egg programs.
- Anthocyanins:Grape skin and berry-derived pigments serve niche applications in specialty poultry feeds.
- Curcumin:Turmeric extracts function primarily as dual-purpose colorants with perceived functional benefits in ruminant formulations.
Carotenoids lead volumes today; spirulina is gaining share fastest.
Application:
Volume concentration tracks the density of large-scale contract grower networks.
- Poultry:Yolk color grading systems directly influence consumer purchase decisions at retail. U.S. Southeast retail chains now mandate specific yolk color scores, compelling feed mills to standardize carotenoid inclusion rates across contract grower networks.
- Swine:Skin and fat coloration requirements drive synthetic pigment use in Midwest finishing operations. Iowa, Illinois, and Minnesota host the continent's densest cluster of large-scale swine finishing operations, generating economies of scale in bulk pigment premix procurement.
- Ruminants:Bioavailability challenges constrain adoption despite dairy and beef coloration potential.
- Aquaculture:Salmonid flesh pigmentation demands high-purity astaxanthin formulations.
Poultry leads volumes today; aquaculture is expanding most quickly.
Form:
Equipment compatibility determines adoption barriers at the feed mill level.
- Powder:Dry pigment premixes blend compatibly with standard feed mill equipment and offer extended shelf stability. This formulation occupies the largest share of the form dimension across North American operations.
- Liquid:Emulsion systems require spray nozzle retrofits that many Midwest facilities have deferred since the 2010s, limiting penetration despite superior dispersion characteristics.
- Granular:Microencapsulated beadlets with modified starch coatings integrate into high-temperature pelleting processes without thermal degradation.
- Paste:High-concentration formulations serve specialty applications and small-batch organic feed production.
Powder leads volumes today; granular is climbing the fastest.
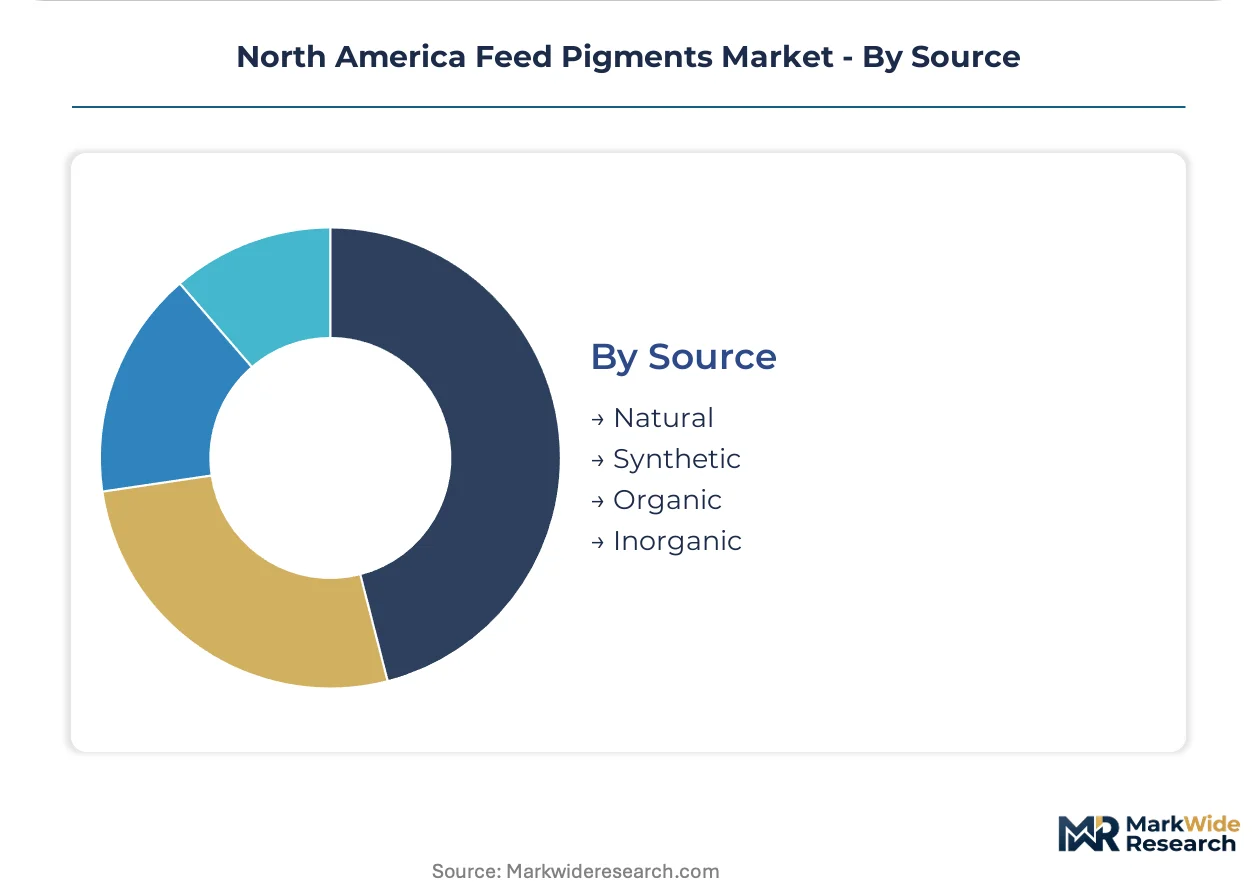
Source:
Certification requirements split procurement between commodity and premium supply tiers.
- Synthetic:Petrochemical-derived pigments offer batch-to-batch consistency and lower unit costs. FDA 21 CFR 73.75 establishes clear regulatory pathways for canthaxanthin and astaxanthin approvals, reducing formulation uncertainty.
- Natural:Algal and plant-derived extracts satisfy clean-label demands from downstream retail partners. Spirulina and Haematococcus pluvialis cultivation face photosynthetic efficiency ceilings that constrain batch-to-batch color consistency.
- Organic:USDA Process Verified Program documentation opens premium channel access for mid-size layer operations.
- Inorganic:Mineral-based colorants serve limited applications in ruminant mineral premixes.
Synthetic leads volumes today; organic is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized phycologists and process engineers concentrate in the U.S. Midwest and Southeast, anchoring North America's algal cultivation and synthetic pigment manufacturing base.
United States
Broiler integrators in Arkansas and Georgia standardize carotenoid inclusion rates for skin pigmentation consistency across summer production cycles. The FDA's 21 CFR 73.75 regulations establish clear pathways for canthaxanthin and astaxanthin approvals, reducing formulation uncertainty for feed mills. Iowa, Illinois, and Minnesota host the densest cluster of large-scale swine finishing operations, generating economies of scale in bulk pigment premix procurement.
Canada
Health Canada's Veterinary Drugs Directorate has aligned review timelines with FDA processes for novel microbial pigment sources, collapsing historical approval gaps. The PMRA coordinates cross-border feed ingredient approvals with U.S. regulators, reducing friction for suppliers operating throughout the integrated North American supply base. Ontario and Quebec layer operations benefit from synchronized regulatory frameworks that permit simultaneous U.S.-Canada product launches.
Mexico
Poultry operations in Jalisco and Nuevo León expand contract grower networks to supply U.S. retail chains with yolk-color-graded eggs. Mexico's national food safety regulator maintains alignment with FDA color additive standards to facilitate export compliance. The Bajío Region concentrates feed mill infrastructure that processes both domestic and imported pigment premixes for integrated poultry producers.
North America Feed Pigments Market Competitive Landscape
Top-tier vendors anchor synthetic carotenoid production, while specialized natural extract suppliers occupy premium positioning tiers. The market structure reflects a bifurcated procurement pattern where commodity scale competes with certification-driven differentiation. Three archetypes dominate: integrated petrochemical feedstock players, algal cultivation specialists, and microbial fermentation platforms. Capacity expansion and backward integration into fermentation feedstock production represent the dominant competitive moves across the landscape.
Within the integrated chemical producer tier, BASF SE and DSM exemplify scale-driven positioning through captive supply of petrochemical-derived intermediates. Kemin Industries Inc occupies the specialized delivery systems segment, representing the natural extract archetype with differentiated bioavailability technologies. These three anchors illustrate how procurement patterns split between cost-efficient synthetic grades and premium natural formulations serving antibiotic-free certification programs.
| Leading Market Players |
|---|
| BASF SE |
| Kemin Industries Inc |
| DSM |
| Novus International Inc |
| Synthite Industries Ltd |
| DSM-Firmenich |
| Vitafor NV |
| Cyanotech Corporation |
| Nutrex NV |
| Others |
Value Network & Pricing Analysis
Specialized phycologists and process engineers concentrate in the U.S. Midwest and Southeast, anchoring labor-cost differentials that widen spreads between commodity synthetic grades and premium natural formulations. Feed mills in Iowa and Arkansas face divergent procurement economics depending on whether they source petrochemical-derived carotenoids or algal-extracted phycocyanin.
Pricing Analysis
Bundled technical service contracts separate premium natural pigment suppliers from unbundled commodity synthetic traders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale as primary price differentiation drivers. Cost compression in synthetic astaxanthin is intensifying because acetone feedstock volatility squeezes margins. Contract poultry integrators in the Southeast exhibit lowest price sensitivity due to retail chain yolk-color mandates, while independent Midwest swine finishers remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with petrochemical intermediate suppliers in the U.S. Gulf Coast and German chemical complexes. The North American feed pigment supply chain draws from China for spirulina biomass, India for turmeric extracts, and domestic fermentation facilities for yeast-derived carotenoids. Raw material dependencies center on acetone and petrochemical precursors, algal cultivation substrates, and modified starch encapsulation coatings. Tariff exposure on Chinese spirulina imports constitutes the dominant structural risk. Distribution runs through integrated feed mill networks and direct-to-integrator channels serving top-10 poultry producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 21 CFR 73.75 clarity on color additive approvals continuously generates formulation demand from compliance-driven integrators.
For Market Incumbents: Extend backward integration into algal cultivation or microbial fermentation feedstock production to insulate margins from petrochemical price swings. Add encapsulation technology capacity in Arkansas or Georgia to capture broiler skin pigmentation standardization demand. Defend against yeast-derived carotenoid platforms by locking multi-year volume commitments with top-10 poultry producers. For New Entrants and Emerging Players: FDA 21 CFR 73.75 in the United States opens a window for microbial fermentation platforms to bypass agricultural weather risk and photosynthetic yield limits. Target underpenetrated ruminant feed applications where bioavailability challenges have constrained synthetic pigment adoption. Pursue USDA Process Verified Program certification as the primary go-to-market angle for premium channel access. For Investors and Strategic Acquirers: Integrated petrochemical feedstock players are the most active acquirer in this space, seeking captive supply of fermentation-derived alternatives. The five-to-ten year viability window favors platforms with regulatory dossiers in both FDA and Health Canada jurisdictions. Acquisition target archetypes include microbial fermentation specialists and algal cultivation technology holders. Watch for synchronized U.S.-Canada approval timelines as the inflection indicator for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captive supply of yeast-derived carotenoid platforms insulates margins from acetone volatility. |
| Microencapsulation Capacity Expansion | Modified starch beadlet production in Arkansas serves broiler integrators' thermal stability requirements. |
| Dual Jurisdiction Regulatory Dossier Filing | Simultaneous FDA and Health Canada submissions collapse historical approval gaps for novel pigments. |
| Direct-to-Integrator Distribution Buildout | Bypassing feed mill intermediaries secures volume commitments from top-10 U.S. poultry producers. |
| USDA Process Verified Program Certification | Third-party verification of natural pigment claims opens premium retail channel access for layer operations. |
Research Methodology
Direct dialogue with feed mill procurement managers, layer operation integrators, regulatory affairs specialists at pigment suppliers, and algal cultivation process engineers grounded the qualitative foundation. Secondary validation drew from FDA 21 CFR filings, Health Canada Veterinary Drugs Directorate submissions, USDA Process Verified Program documentation, and American Feed Industry Association technical guidelines. Bottom-up volume estimates from individual facility throughput data triangulated against top-down market sizing from trade flow analysis.
Bottom-up modeling tracked carotenoid inclusion rates by species, form factor adoption curves, and certification tier penetration across the projection horizon. Segmentation dimensions covered product type, application species, formulation form, and source origin. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking integrator expansion plans. Industry-specific forecast inputs included yolk color grading score mandates from Southeast retail chains and broiler skin pigmentation standardization timelines.
Revisions become necessary when regulatory approval delays, petrochemical price shocks, or algal cultivation batch failures materialize beyond modeled assumptions. Forecasts reflect documented parameters around FDA-Health Canada synchronization and microbial fermentation yield improvements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Feed Flavor Market