
 Lawn Care Chemicals Market | 2026-2036
Lawn Care Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Care Chemicals Market Analytics
A shift from single-source active ingredient procurement to multi-source botanical and synthetic blending is realigning how formulators secure supply chain resilience. Scotts Miracle-Gro leverages its captive retail distribution through garden centers and mass merchants to sustain margin capture. Bayer anchors its lawn care portfolio on systemic fungicide chemistry developed from crop science crossovers. Corteva competes through specialized herbicide formulations targeting warm-season grass species.
Lawn care chemicals encompass synthetic and biological formulations applied to turfgrass for weed suppression, insect control, disease management, and nutritional supplementation, typically delivered as granules with particle sizes between 0.5 and 4 millimeters or as emulsifiable concentrates diluted in water carriers. These products serve commercial landscapers, residential property owners, and sports turf managers seeking uniform aesthetic standards and playable surface conditions. Herbicides command the largest revenue share within product type segments due to entrenched broadleaf weed pressure across temperate lawns, while liquid application methods are gaining ground among professional users seeking calibrated coverage and rapid foliar uptake. Fertilizer formulations with enhanced efficiency coatings represent the fastest-growing structural category as phosphorus runoff regulations tighten nutrient management protocols.
The US EPA governs pesticide registration under FIFRA, requiring extensive toxicological and environmental fate data that extends development timelines and elevates barrier costs for new entrants. State-level restrictions in jurisdictions such as New York and Minnesota on neonicotinoid and phenoxy herbicide applications further fragment permissible product portfolios. The EU REACH framework and F-Gas Regulation constrain export-oriented manufacturers serving European turf markets. Stakeholders must monitor evolving state preemption battles and pollinator risk assessments to anticipate which chemistries will retain market access.
Market Dynamics
The US EPA's re-registration review process for conventional pesticides is compressing product lifecycles and forcing formulators toward multi-source active ingredient blending strategies that reduce single-chemistry dependency.
Growth Catalysts
- Suburban lawn culture:Residential homeowners in the United States sustain the highest per-household chemical expenditure globally, creating durable pull-through demand for retail-formulated products.
- FIFRA compliance infrastructure:Established manufacturers with existing EPA registration dossiers capture market access that new entrants cannot easily replicate, consolidating incumbent positions.
- Enhanced-efficiency fertilizer coatings:Phosphorus runoff regulations in multiple states are accelerating adoption of controlled-release formulations that reduce application frequency.
Market Restraints
- Active ingredient concentration:Supply of key synthetic herbicide precursors concentrates among Chinese chemical manufacturers, exposing formulators to tariff and logistics volatility.
- Neonicotinoid restrictions:State-level prohibitions in New York and Minnesota on systemic insecticides eliminate product options for turf managers serving those jurisdictions.
- Biological formulation stability:Microbial inoculants and botanical extracts face shelf-life limitations that constrain distribution radius and retail inventory cycles.
Strategic Opportunities
- Warm-season grass specialization:Corteva's herbicide formulations for Bermuda and Zoysia turf indicate underserved demand in the southeastern United States where cool-season chemistry underperforms.
- Mass merchant channel expansion:Captive retail distribution through home improvement chains and garden centers enables margin capture bypassing professional applicator intermediaries.
- EU F-Gas Regulation alignment:Export-oriented manufacturers can access European turf markets by reformulating propellant systems and solvent carriers to meet REACH framework constraints.
Industry Challenges
- Toxicological data generation:EPA's expanded pollinator risk assessment protocols require multi-year field studies that extend registration timelines and consume technical staff capacity.
- Application equipment calibration:Liquid concentrate adoption among professional users demands precision sprayer investment that smaller landscaping operations struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Care Chemicals Market |
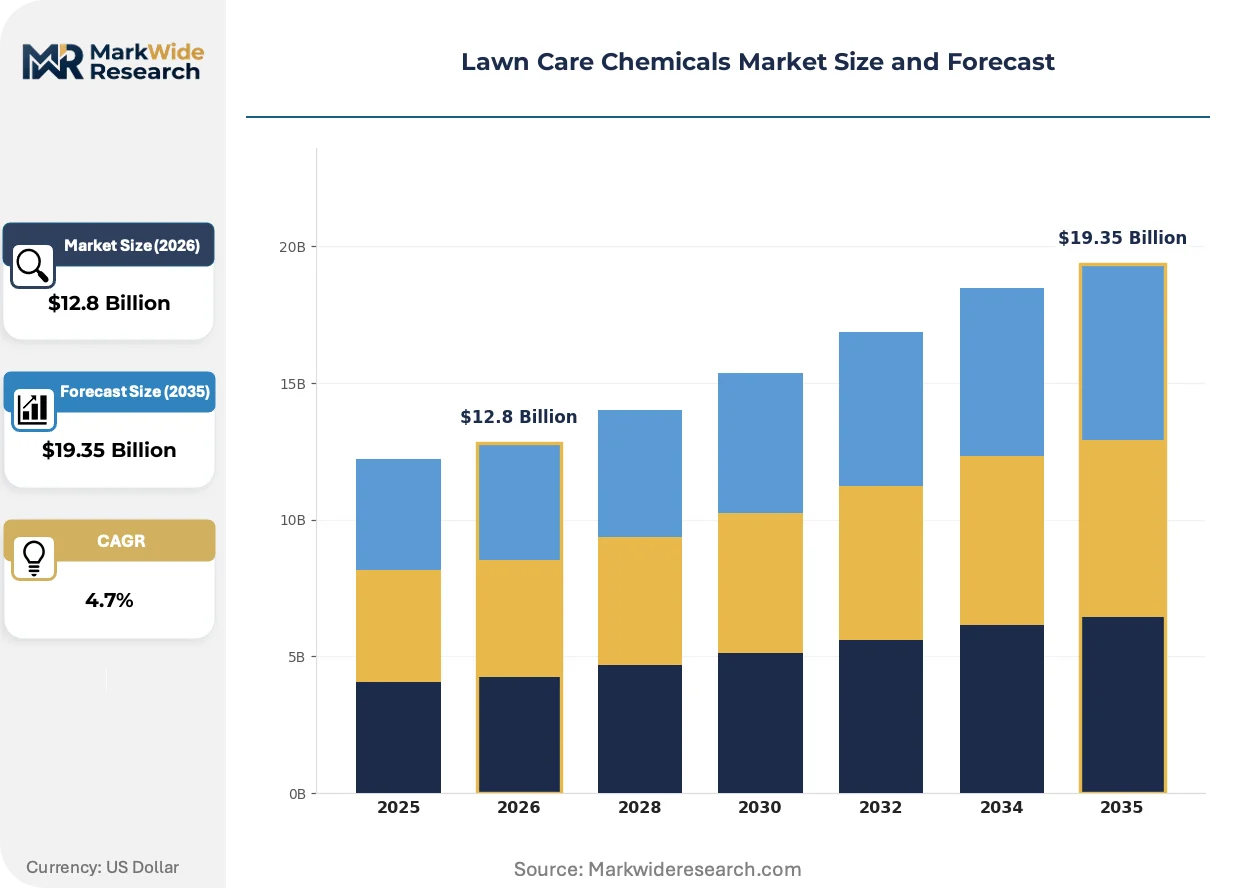
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Fertilizers Application Method: Granular, Liquid, Spray, Soil Treatment End User: Commercial, Residential, Sports Fields, Golf Courses Distribution Channel: Online Retail, Garden Centers, Wholesale, Direct Sales |
| Companies Covered | Scotts Miracle-Gro, Bayer, Syngenta, Corteva, BASF SE, FMC Corporation, Nufarm Limited, ADAMA Agricultural Solutions, American Vanguard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Care Chemicals Market Evolving Landscape
Formulation chemistry is pivoting toward bio-synthetic hybrids as regulatory pressure on conventional pesticides intensifies and end-users seek application flexibility across diverse turf conditions.
Microencapsulated herbicide delivery is electrifying weed control efficacy by extending residual activity and reducing volatilization losses. Professional lawn care operators in the United States are accelerating adoption of these formulations to meet callback reduction targets and labor cost containment goals. The technology is electrifying competitive positioning among formulators who can demonstrate measurable performance advantages in split-application programs.
REACH framework substance restrictions are eliminating certain solvent carriers and adjuvant chemistries from products destined for European markets. Manufacturers serving export channels must maintain parallel formulation inventories or absorb reformulation costs to retain market access. Turf managers in Germany and France face contracting product portfolios as registrants withdraw marginal registrations rather than generate new environmental fate data.
Residential buyers are consolidating purchase decisions around seasonal bundle offerings that combine fertilizer, herbicide, and insecticide in single-SKU programs. Mass merchant retailers are displacing independent garden centers as the primary discovery channel for first-time homeowners entering lawn maintenance. This pattern concentrates most visibly in the United States where subscription-style lawn care boxes are capturing trial among digitally native consumers.
Lawn Care Chemicals Market Segmentation
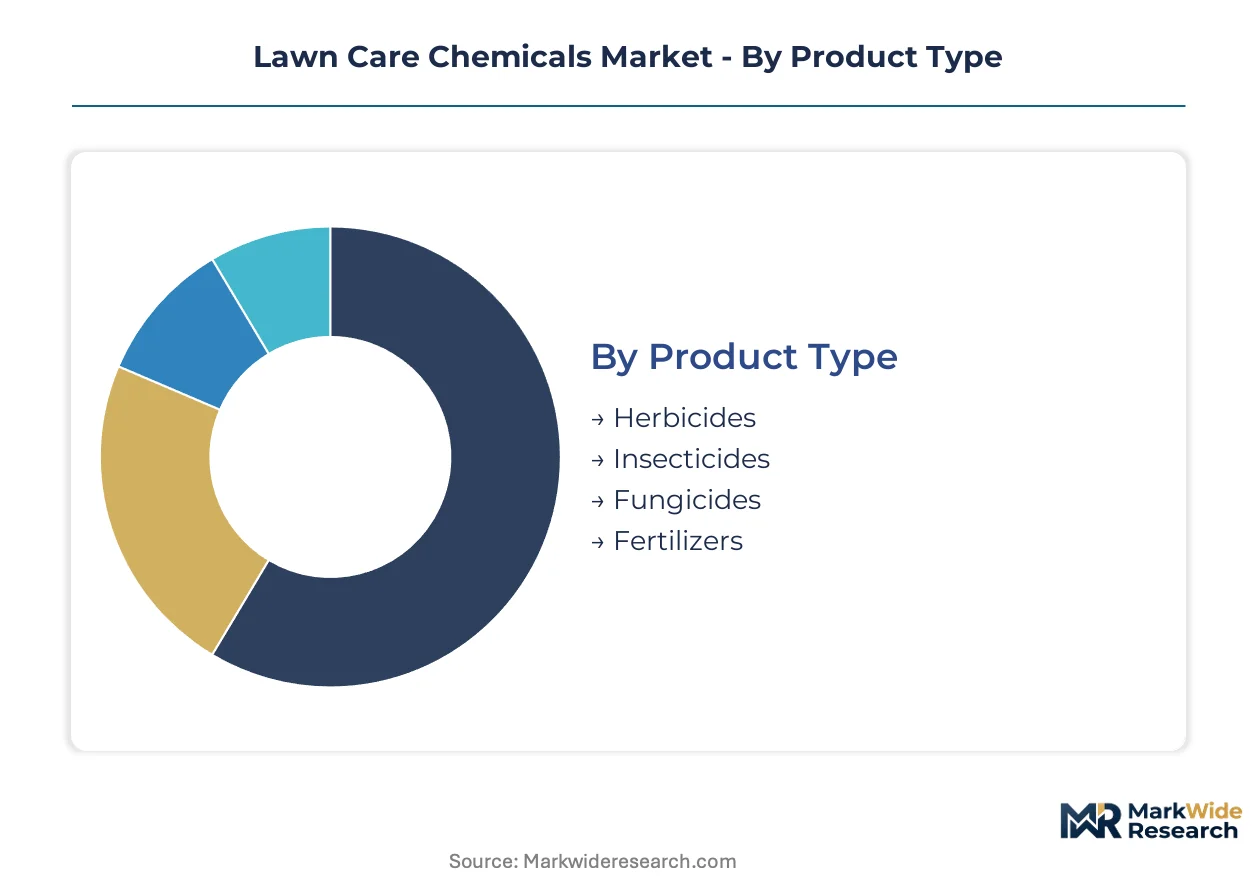
Formulators configure product portfolios around four intersecting dimensions that determine pricing power, channel access, and regulatory exposure. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape competitive positioning across the value chain.
Product Type:
Supply of active ingredient precursors concentrates among specialty chemical manufacturers in Asia, forcing formulators to hedge procurement through multi-source blending strategies.
- Herbicides:Synthetic auxin and photosystem II inhibitors dominate broadleaf weed control in temperate turfgrass systems. Residential homeowners in the United States generate the highest per-household expenditure on these formulations, though neonicotinoid co-formulation restrictions in New York and Minnesota eliminate certain product options.
- Fertilizers:Enhanced-efficiency coatings using polymer sulfur or urease inhibitors extend nutrient release timelines. Phosphorus runoff regulations across multiple states accelerate demand for controlled-release structures that reduce application frequency and environmental loading.
- Insecticides:Pyrethroid and neonicotinoid chemistries target grub and surface-feeding insect populations.
- Fungicides:Systemic azole and strobilurin formulations manage dollar spot and brown patch pressure in high-maintenance turf.
Herbicides absorb the bulk of installed capacity; fertilizers are expanding most quickly.
Application Method:
Equipment requirements and labor intensity diverge sharply across delivery formats, with professional users gravitating toward precision-calibrated systems that reduce callback rates.
- Liquid:Emulsifiable concentrates diluted in water carriers enable calibrated coverage and rapid foliar uptake. Professional lawn care operators accelerate adoption to meet labor cost containment targets, though smaller landscaping operations struggle to justify precision sprayer investment.
- Granular:Particulate formulations with diameters between 0.5 and 4 millimeters distribute through broadcast spreaders. Mass merchant retail channels favor these SKUs for residential DIY application due to storage stability and handling simplicity.
- Spray:Ready-to-use formulations eliminate mixing steps for consumer convenience.
- Soil Treatment:Pre-emergent and systemic chemistries applied to root zones require specialized injection or drench equipment.
Granular formats dominate residential volume; liquid methods gain share fastest among commercial applicators.
End User:
Performance specifications and purchasing authority fragment demand across customer types with divergent aesthetic tolerances and regulatory exposure.
- Residential:Suburban homeowners sustain the highest per-household chemical expenditure globally, consolidating purchase decisions around seasonal bundle offerings that combine fertilizer, herbicide, and insecticide in single-SKU programs.
- Commercial:Landscaping contractors and property management firms demand calibrated application protocols and documented efficacy. The segment concentrates procurement through wholesale distributors rather than retail channels.
- Sports Fields:Playability standards and athlete safety protocols constrain product selection timelines.
- Golf Courses:Superintendent-directed purchasing emphasizes disease management and presentation quality for high-visibility turf.
Residential buyers absorb the bulk of unit volume; commercial accounts generate the steepest expansion trajectory in liquid concentrate adoption.
Distribution Channel:
Channel control determines margin capture and customer access, with captive retail networks displacing independent intermediaries in high-growth segments.
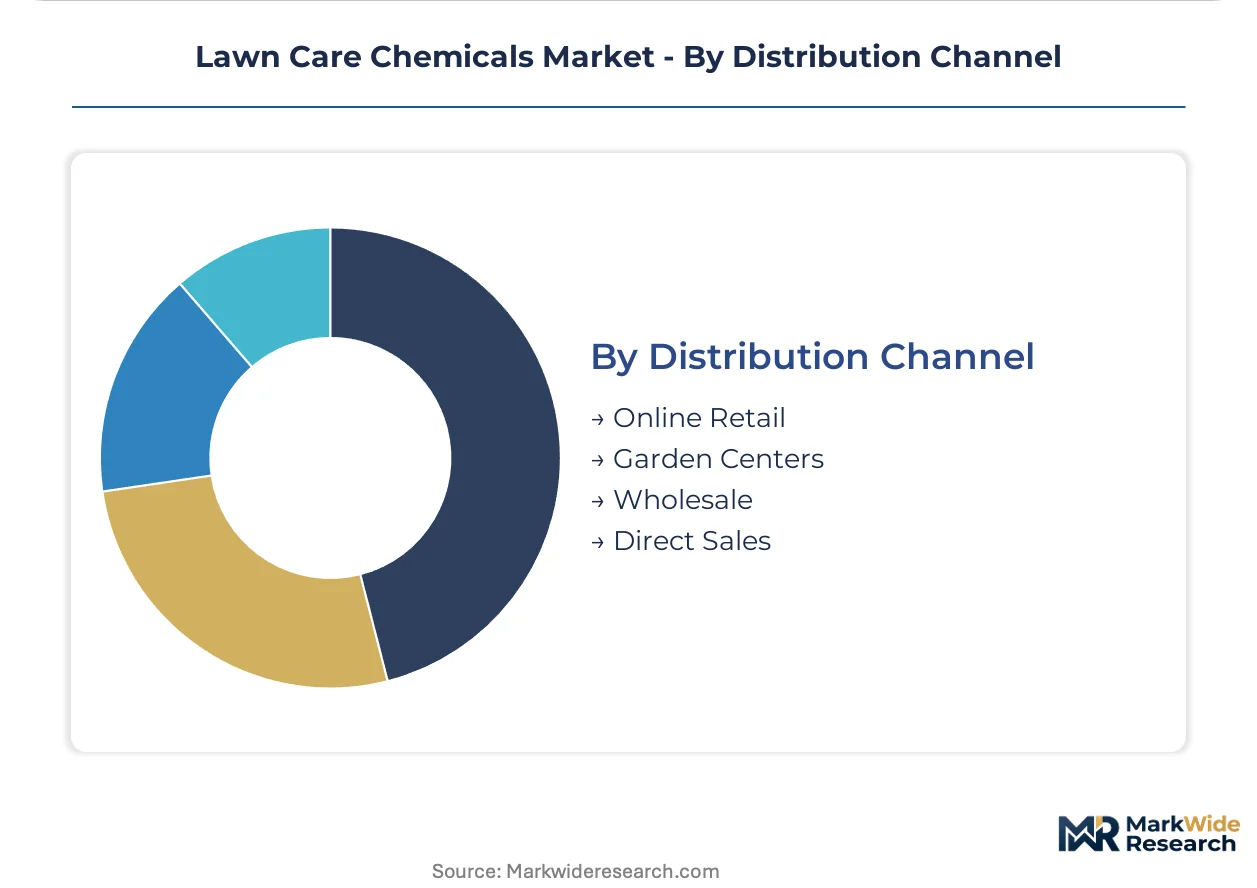
- Garden Centers:Independent and chain garden centers provide technical consultation and seasonal merchandising. These outlets face displacement pressure as mass merchants capture trial among first-time homeowners entering lawn maintenance.
- Online Retail:Subscription-style lawn care boxes capture trial among digitally native consumers, concentrating most visibly in the United States where direct-to-home delivery reduces transport friction for bulky granular products.
- Wholesale:Distributors serve professional applicators with volume pricing and technical support.
- Direct Sales:Manufacturer field representatives engage golf courses and sports turf managers with customized programs.
Garden centers retain the bulk of established customer relationships; online retail is climbing the fastest among entry-level residential buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient precursor manufacturing clusters in Jiangsu and Shandong provinces anchor global supply chains for lawn care formulators, while suburban lawn culture in North American and European metropolitan zones generates concentrated end-use demand.
United States
Residential homeowners in suburban Atlanta, Dallas-Fort Worth, and Phoenix sustain the highest per-household chemical expenditure globally, with warm-season grass specialization driving differentiated formulation demand. The EPA's re-registration review process under FIFRA compresses product lifecycles and elevates compliance costs for conventional pesticides. Formulation R&D concentrates in Research Triangle Park, North Carolina, where agrochemical companies maintain toxicological testing facilities.
Germany
Golf course superintendents and sports turf managers in Bavaria and North Rhine-Westphalia generate specialized demand for disease management chemistries. The EU REACH framework and F-Gas Regulation constrain permissible solvent carriers and adjuvant systems, forcing reformulation of export-oriented products. Industrial formulation activity clusters around Ludwigshafen and Leverkusen, where integrated chemical complexes enable captive active ingredient supply.
China
Domestic lawn and landscape investment in Shanghai, Beijing, and Shenzhen metro areas is accelerating demand for imported and locally manufactured turf maintenance products. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for chemical manufacturing. Active ingredient synthesis concentrates in Jiangsu province, where specialty chemical manufacturers supply global formulators with herbicide precursors.
Japan
Compact residential lawns in Tokyo, Osaka, and Nagoya metropolitan areas favor precision application equipment and low-volume formulations. METI administers chemical substance regulations that align with international standards while maintaining domestic testing protocols. Turfgrass research institutes in Tsukuba Science City develop warm-season grass varieties adapted to humid subtropical conditions.
Australia
Sports field managers in Sydney, Melbourne, and Brisbane prioritize drought-tolerant turfgrass systems with reduced chemical input requirements. The Australian Pesticides and Veterinary Medicines Authority maintains registration standards that recognize overseas data packages with supplementary local efficacy trials. Distribution infrastructure concentrates in Melbourne's western industrial corridor, where agricultural chemical wholesalers serve professional applicator networks.
Lawn Care Chemicals Market Competitive Landscape
Global majors compete with regional champions across registration infrastructure and distribution channel control, producing a tiered structure where EPA dossier ownership separates incumbents from aspirants. Three archetypes dominate: integrated agrochemical conglomerates with crop science crossovers, specialized turf and ornamental formulators, and captive retail brands with mass merchant channel control. Competitive moves concentrate on multi-source active ingredient blending to reduce supply concentration risk, and direct-to-consumer subscription models that bypass professional applicator intermediaries.
Within the integrated conglomerate tier, Bayer and BASF SE exemplify players leveraging crop science R&D infrastructure for turfgrass chemistry development. Corteva occupies a position bridging specialized warm-season grass formulation with broader agricultural chemical portfolios. Among retail-captive specialists, Scotts Miracle-Gro anchors mass merchant distribution through garden center and home improvement chain relationships. These three companies represent distinct strategic postures: chemistry-forward innovation, regional turf specialization, and channel-integrated consumer access.
| Leading Market Players |
|---|
| Scotts Miracle-Gro |
| Bayer |
| Syngenta |
| Corteva |
| BASF SE |
| FMC Corporation |
| Nufarm Limited |
| ADAMA Agricultural Solutions |
| American Vanguard Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap formulators in the United States and Germany anchor pricing discipline through generational customer relationships and captive technical service bundling, while their supply procurement patterns concentrate on Jiangsu province manufacturers exposed to EPA tariff volatility and dual carbon enforcement from China's Ministry of Ecology and Environment.
Pricing Analysis
Warranty-backed application guidance and seasonal callback guarantees differentiate premium formulations from unbundled commodity chemistry. Three-tier pricing structure across premium, standard, and economy levels reflects EPA registration investment recovery, with professional-grade liquid concentrates commanding substantial premiums over mass merchant granular SKUs. Pricing pressure stems from phosphorus runoff regulation compliance costs that compress margins on conventional fertilizer formulations. Residential DIY buyers exhibit highest price sensitivity, while golf course superintendents prioritize performance consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Corteva and Bayer procurement teams require qualified backup suppliers for synthetic auxin precursors and azole fungicide intermediates. Active ingredient synthesis concentrates in China, India, and Germany, with formulators drawing from Jiangsu province chemical manufacturers, Gujarat specialty intermediates producers, and Ludwigshafen integrated complexes. Key dependencies include 2,4-D acid precursors, glyphosate technical, and polymer sulfur coating resins. Single-source vulnerability runs through Chinese precursor concentration exposed to tariff and logistics disruption. Distribution runs through mass merchant retail chains, wholesale distributor networks, and direct field sales to institutional turf managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn care chemicals sector is transitioning from conventional synthetic chemistry toward bio-synthetic hybrid formulations as microencapsulated delivery systems and controlled-release coatings displace legacy granular and emulsifiable concentrate platforms.
For Market Incumbents: Anchor market position through backward integration into active ingredient precursor manufacturing in Germany and the United States, reducing dependency on Chinese supply concentration. Accelerate EPA registration dossier expansion for bio-synthetic hybrids before pollinator risk assessment protocols tighten further. Prioritize captive retail distribution control through exclusive mass merchant shelf space agreements that block challenger brand trial. For New Entrants and Emerging Players: Microbial inoculant stabilization technology offers entry wedge into professional landscaping channels underserved by biological formulation suppliers. Target warm-season grass specialization in southeastern United States metropolitan zones where Corteva's herbicide portfolio leaves residual demand gaps. Pursue direct-to-consumer subscription models with seasonal bundle offerings that bypass wholesale distributor margin extraction. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional formulators with existing EPA registration infrastructure in Minnesota and New York, jurisdictions where neonicotinoid restrictions have compressed valuations without eliminating market access. Five-to-ten-year viability hinges on successful navigation of re-registration review timelines and biological formulation shelf-life extension. Monitor state preemption battles and pollinator risk assessment publication schedules as inflection indicators for chemistry portfolio obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive supply of 2,4-D acid and azole intermediates insulates formulators from Jiangsu province tariff exposure. |
| Microencapsulation Technology Licensing | Extended residual activity from licensed delivery systems reduces professional applicator callback rates and labor costs. |
| Mass Merchant Channel Exclusivity Agreements | Shelf space control through Home Depot and Lowe's blocks trial of competing brands among first-time homeowners. |
| Biological Formulation Stability Investment | Shelf-life extension for microbial inoculants expands distribution radius beyond current 500-mile constraints. |
| Warm-Season Grass Registration Expansion | EPA submissions for Bermuda and Zoysia-specific chemistries capture underserved demand in Atlanta and Dallas-Fort Worth markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with EPA registration consultants, golf course superintendents, mass merchant category buyers, professional lawn care operators, and specialty chemical procurement directors. Secondary sources included FIFRA registration databases, REACH substance restriction notices, USITC trade flow records, and SEC 10-K disclosures from listed agrochemical firms. Bottom-up volume estimates triangulated against top-down expenditure surveys from residential homeowner panels.
Data-stream reconciliation across manufacturer shipment reports, distributor inventory audits, and retail point-of-sale tracking generated consistent baseline estimates. Segmentation modeling spanned product type, application method, end user, and distribution channel dimensions, with additional granularity on warm-season versus cool-season grass chemistry requirements. CAGRs derived from regression analysis of historical expenditure patterns and regulatory timeline impacts, incorporating EPA re-registration review completion schedules and state-level restriction adoption curves as forward inputs.
Several conditions sit outside the modeled scope, including unforeseen EPA suspension orders, abrupt neonicotinoid class-wide prohibitions, and biological formulation contamination events that could trigger batch recalls. Forecasts reflect documented assumptions regarding registration timeline continuity and tariff rate stability. Deviation in Chinese environmental enforcement intensity or Midwest drought frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market