
 Global Agricultural Colorants Market | 2026-2036
Global Agricultural Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Colorants Market Foresight
Premium-grade pigment specifications for seed treatment coatings is unwinding legacy commodity dynamics across the agricultural colorants sector. BASF SE leverages its integrated pigment-synthesis network to sustain supply security for high-purity iron oxide reds used in seed coatings. LANXESS AG anchors its position through specialized azo pigment grades engineered for UV stability in tropical field conditions. Huntsman Corporation competes on titanium dioxide dispersion technology optimized for aqueous seed-treatment formulations.
Agricultural colorants are color-imparting substances formulated into dyes or pigments with defined particle size distributions, lightfastness ratings, and regulatory purity thresholds, applied to seeds, fertilizers, or crop protection products to enable visual identification, dosage verification, and brand differentiation. Pigment-based formulations dominate volume due to their superior opacity and weather resistance in soil-contact applications, while natural colorants represent the fastest-expanding category as EFSA and organic certification bodies tighten synthetic additive restrictions. Seed treatment commands the largest application share, though fertilizer enhancement is gaining traction among precision agriculture operators seeking visual nutrient-grade markers.
REACH registration requirements in Europe, EPA tolerance specifications in the United States, and FSSAI colorant approvals in India collectively constrain formulation freedom and elevate compliance costs for cross-border suppliers. The EU Green Deal's Farm to Fork strategy is accelerating substitution mandates that favor biodegradable pigment carriers over petroleum-based dispersants. Stakeholders must monitor evolving residue thresholds and certification harmonization between organic and conventional supply chains to anticipate qualification barriers.
Market Dynamics
Seed treatment coatings are rewiring procurement priorities across the agricultural colorants sector as treated seed programs expand in Brazil and traceability mandates tighten in Europe.
Growth Catalysts
- EU Green Deal substitution mandates:The Farm to Fork strategy accelerates demand for biodegradable pigment carriers, forcing formulators to reformulate petroleum-based dispersants ahead of compliance deadlines.
- Brazilian soybean expansion:Large-scale operations in Mato Grosso and Paraná are scaling treated seed programs, pulling premium-grade iron oxide reds into South American supply chains.
- Seed coating automation:Precision planting equipment requires high-visibility colorants for dosage verification, embedding pigment specifications into OEM equipment standards.
Market Restraints
- Titanium dioxide feedstock volatility:Huntsman and other dispersion specialists face margin pressure from sulfate-process TiO2 supply tightness concentrated in Chinese chloride-process expansions.
- REACH registration cost escalation:ECHA data requirements for new pigment substances create six-figure compliance barriers that freeze SME formulation entry in European markets.
- Natural colorant performance gaps:EFSA-pending anthocyanin and chlorophyll derivatives lack the lightfastness ratings required for tropical seed storage, limiting organic certification penetration.
Strategic Opportunities
- India FSSAI colorant approvals:Pending positive lists for iron oxide and titanium dioxide in agricultural applications open formulation licensing opportunities for multinationals ahead of domestic capacity buildout.
- Fertilizer enhancement markers:Precision agriculture operators in the US Corn Belt are piloting visual nutrient-grade colorants for variable-rate application verification, creating a parallel demand stream to seed treatment.
- Bio-based azo pigment R&D:Convergence of fermentation-derived aromatic precursors with conventional diazotization chemistry promises drop-in replacements for petroleum-based azo intermediates.
Industry Challenges
- Cross-jurisdictional residue harmonization:Discrepancies between EPA tolerance specifications and EFSA migration thresholds force dual-track toxicology studies, stretching certification timelines for global formulations.
- Legacy equipment retrofitting:Aqueous dispersion technologies require stainless-steel milling infrastructure that conflicts with solvent-based pigment grinding assets common in mid-tier coating facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Colorants Market |
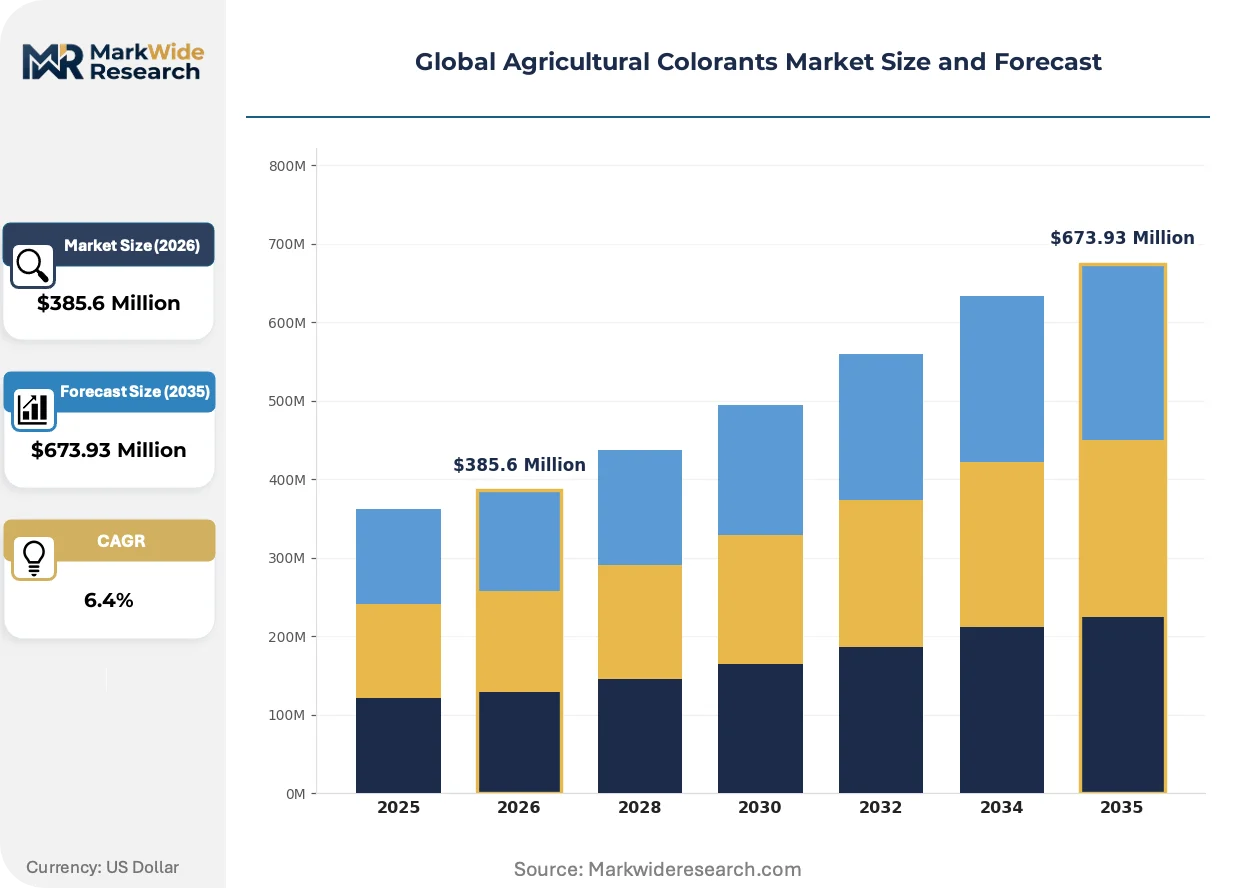
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Pigments, Food Colorants, Natural Colorants, Synthetic Colorants Application: Crop Coatings, Seed Treatment, Fertilizer Enhancement, Pesticide Marking, Soil Amendment End User: Agri Input Manufacturers, Seed Producers, Growers, Agrochemical Companies, Agronomic Service Providers Packaging Type: Bulk Containers, Sachets, Bottles, Drums, Pouches |
| Companies Covered | Huntsman Corporation, LANXESS AG, BASF SE, Heubach GmbH, DIC Corporation, Clariant AG, Sudarshan Chemical Industries Limited, Merck KGaA, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Colorants Market Shifts & Advancements
Formulation chemistry is splitting along regulatory fault lines as bio-based mandates collide with performance requirements for soil-contact durability.
Encapsulated pigment technologies are bifurcating supply security strategies across the sector. Polymeric shell architectures protect iron oxide cores from alkaline fertilizer leaching, extending colorfastness in field storage. Seed cooperatives in Iowa and Illinois are specifying encapsulated grades for multi-season inventory carry. This technology is bifurcating procurement into premium encapsulated tiers versus commodity dry pigment sourcing.
REACH authorization amendments are compressing formulation freedom for chromium-based pigments in European seed coatings. ECHA sunset dates for lead chromate and molybdate orange are forcing colorant suppliers to validate bismuth vanadate and high-performance organic alternatives under accelerated stability protocols. German seed treatment houses are absorbing reformulation costs six to eighteen months ahead of legal deadlines to secure supply continuity.
Certification-driven procurement is consolidating buyer preferences around third-party organic and non-GMO verification marks. Distributors in France and Benelux are bundling colorant sourcing with full seed treatment service packages, displacing standalone pigment transactions. This shift is most visible in Dutch vegetable seed operations, where Rijk Zwaan and Enza Zaden parent companies mandate colorant traceability through certified handler networks.
Global Agricultural Colorants Market Segmentation
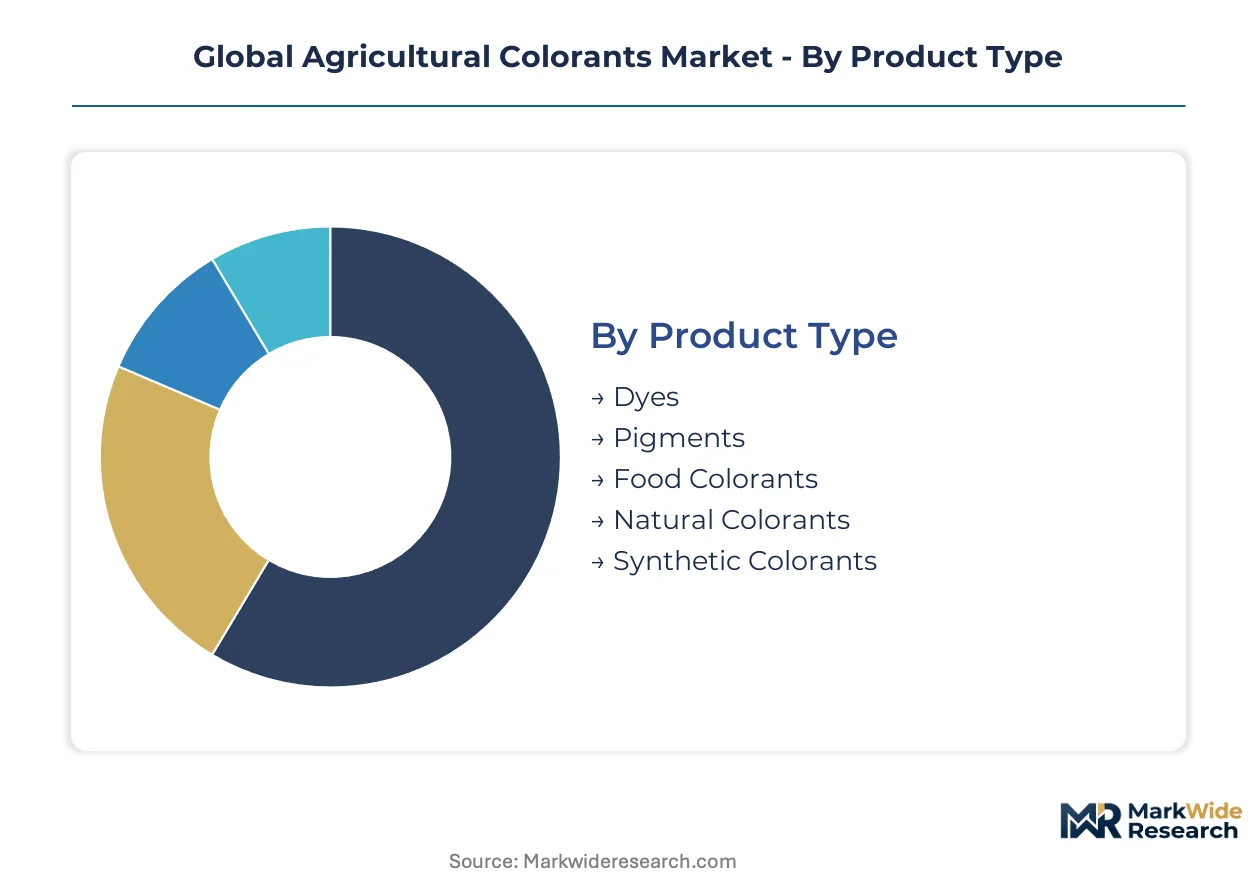
Segmentation in agricultural colorants reveals how regulatory pressure and application-specific performance requirements split procurement strategies across distinct technical tiers. Buyers optimize formulations around opacity demands, biodegradability mandates, and equipment compatibility rather than treating colorants as interchangeable commodities.
Product Type:
REACH authorization timelines and EPA tolerance specifications differentiate compliance burdens across chemical classes, channeling R&D investment toward pre-registered substances while freezing novel synthetic pathways.
- Pigments:Iron oxide and titanium dioxide formulations deliver superior opacity and UV stability for soil-contact applications. Demand concentrates in Brazilian soybean seed treatment programs where tropical storage conditions stress lightfastness ratings.
- Natural Colorants:Anthocyanin and chlorophyll derivatives extracted from agricultural waste streams offer biodegradable pathways aligned with EU Green Deal substitution mandates. EFSA-pending approvals constrain penetration in organic-certified supply chains.
- Dyes:Soluble azo and anthraquinone compounds provide transparent tinting for aqueous fertilizer solutions where particle suspension is problematic.
- Food Colorants:Carotenoid and curcumin grades repurposed from food additive registers meet residue thresholds for edible crop applications.
- Synthetic Colorants:Petroleum-derived intermediates face sunset pressure under ECHA authorization amendments, compressing formulation freedom for chromium-based orange and yellow pigments.
Established volume favors pigments; emerging adoption favors natural colorants.
Application:
Equipment integration requirements and traceability mandates split procurement between precision planting systems and bulk fertilizer operations.
- Seed Treatment:High-visibility coatings enable dosage verification in automated planting equipment. Iowa and Illinois seed cooperatives specify encapsulated iron oxide grades for multi-season inventory carry.
- Fertilizer Enhancement:Visual nutrient-grade markers support variable-rate application verification in US Corn Belt precision agriculture pilots.
- Crop Coatings:Post-harvest protective films use color-coded identification for organic versus conventional certification boundaries.
- Pesticide Marking:Spray pattern indicators require rapid biodegradation to avoid residue accumulation on edible tissues.
- Soil Amendment:Liming and conditioning products incorporate pH-stable pigments for application uniformity assessment.
Seed treatment commands procurement volume; fertilizer enhancement is climbing the fastest as precision agriculture scales.
End User:
Formulation control and certification liability concentrate purchasing power among integrated agri-input manufacturers versus fragmented grower segments.
- Agri Input Manufacturers:Vertically integrated formulators in Germany and the Netherlands internalize colorant specification to secure supply continuity ahead of REACH sunset dates.
- Seed Producers:Dutch vegetable seed operations mandate traceability through certified handler networks, bundling colorant sourcing with full treatment service packages.
- Agrochemical Companies:Multi-product portfolios require cross-compatible pigment systems that perform across seed, foliar, and soil applications.
- Growers:Direct procurement concentrates in large-scale Brazilian operations with captive seed treatment capacity.
- Agronomic Service Providers:Custom application businesses favor bulk pigment sourcing for on-site formulation flexibility.
Integrated manufacturers dominate volume; seed producers are gaining share fastest through certification-driven procurement consolidation.
Packaging Type:
Supply chain configuration and handling infrastructure determine format preference across concentrated production hubs versus distributed application sites.
- Bulk Containers:Stainless-steel totes support aqueous dispersion logistics for high-volume seed treatment facilities in Mato Grosso and Paraná.
- Drums:Standardized steel and HDPE formats serve mid-tier coating houses with solvent-based grinding assets requiring gradual equipment transition.
- Sachets:Pre-weighed unit doses reduce measurement error for small-batch organic certification runs.
- Bottles:Retail-scale packaging serves grower-direct channels and specialty crop consultants.
- Pouches:Flexible formats minimize shipping cube for export-oriented suppliers serving dispersed Asian and African markets.
Bulk containers anchor industrial volume; sachets are expanding most quickly through organic certification penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and India exhibit the highest price elasticity, treating agricultural colorants as commodity inputs, while German and Dutch seed producers absorb premium pricing for encapsulated grades to secure certification continuity.
United States
Precision agriculture adoption in Iowa and Illinois drives demand for high-visibility seed coatings compatible with automated planting verification systems. EPA tolerance specifications for iron oxide and titanium dioxide residues constrain formulation options for cross-state suppliers. Seed cooperatives in the Corn Belt specify encapsulated pigment grades for multi-season inventory carry.
Brazil
Large-scale soybean and corn operations in Mato Grosso and Paraná scale treated seed programs, pulling premium-grade iron oxide reds into South American supply chains. ANVISA registration requirements for agricultural colorants create compliance lead times for multinational suppliers. Stainless-steel bulk totes serve high-volume treatment facilities concentrated in the Cerrado agricultural frontier.
Germany
Seed treatment houses absorb reformulation costs six to eighteen months ahead of ECHA sunset dates for chromium-based pigments to secure supply continuity. REACH authorization amendments compress formulation freedom for lead chromate and molybdate orange alternatives. Bavarian and North Rhine-Westphalian coating clusters validate bismuth vanadate and high-performance organic pigments under accelerated stability protocols.
Netherlands
Dutch vegetable seed operations mandate colorant traceability through certified handler networks, bundling pigment sourcing with full treatment service packages. EU Green Deal Farm to Fork strategy accelerates substitution mandates favoring biodegradable pigment carriers over petroleum-based dispersants. Rijk Zwaan and Enza Zaden parent companies in the Westland region drive procurement consolidation around third-party organic verification marks.
India
Pending FSSAI positive lists for iron oxide and titanium dioxide in agricultural applications open formulation licensing opportunities for multinationals ahead of domestic capacity buildout. BIS quality standards for seed treatment colorants create technical barriers for unregistered imports. Maharashtra and Gujarat agri-input distributors pilot bulk pigment sourcing for captive seed treatment operations.
Global Agricultural Colorants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the agricultural colorants sector. Integrated chemical conglomerates with captive pigment synthesis networks dominate supply security for high-purity grades, while specialized dispersion houses compete on formulation compatibility with aqueous seed treatment systems. Three archetypes define competitive positioning: vertically integrated pigment manufacturers, application-specific formulators, and regional toll processors serving localized seed cooperatives. Dominant competitive moves include backward integration into iron oxide feedstock and strategic partnerships with precision agriculture OEMs to embed colorant specifications into equipment standards.
Among Germany-based chemical conglomerates, BASF SE and LANXESS AG occupy positions anchored by integrated manufacturing footprints and specialized azo pigment portfolios respectively. Huntsman Corporation represents the dispersion-technology archetype, competing on titanium dioxide formulation compatibility. These three companies exemplify how geographic origin and structural form—SE, AG, and Corporation suffixes—correlate with divergent strategic postures: captive synthesis versus specialized formulation versus dispersion optimization.
| Leading Market Players |
|---|
| Huntsman Corporation |
| LANXESS AG |
| BASF SE |
| Heubach GmbH |
| DIC Corporation |
| Clariant AG |
| Sudarshan Chemical Industries Limited |
| Merck KGaA |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
Bio-based pigment carrier substitution for petroleum-derived dispersants simultaneously redraws supply geography toward fermentation-capable chemical hubs and compresses pricing economics for legacy formulators facing EU Green Deal compliance deadlines. German seed treatment houses now absorb premium differentials for biodegradable alternatives six to eighteen months ahead of legal mandates, while Brazilian bulk buyers resist comparable markups.
Pricing Analysis
After-sales formulation services and multi-season technical support contracts drive lifetime value for encapsulated pigment grades. Three-tier pricing structure across premium, standard, and economy levels separates certification-bundled offerings from commodity dry pigment sourcing. Pricing pressure stems from titanium dioxide sulfate-process feedstock tightness concentrated in Chinese chloride-process expansions. Large-scale Brazilian soybean operations exhibit highest price elasticity, while Dutch vegetable seed producers absorb premium differentials for traceability-assured supply.
Supply Chain Analysis
Chloride-process titanium dioxide capacity expansion in China anchors global feedstock availability for aqueous dispersion specialists. Iron oxide pigment synthesis concentrates in German and Indian manufacturing clusters, while azo intermediate production draws from Chinese and South Korean aromatic chemical bases. Single-source vulnerability runs through concentrated titanium dioxide feedstock channels. Distribution runs through stainless-steel bulk totes for high-volume Brazilian treatment facilities and drum formats for mid-tier European coating houses transitioning solvent-based assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal substitution mandates constitute a high-growth disruption, compressing reformulation timelines and rewarding first-movers with biodegradable pigment carrier validation.
For Market Incumbents: Fortify supply security through backward integration into iron oxide feedstock and captive fermentation-derived aromatic precursor capacity. Lock in multi-year service contracts with Dutch vegetable seed cooperatives ahead of REACH authorization amendments. Prioritize accelerated stability protocols for bismuth vanadate alternatives to chromium-based pigments. For New Entrants and Emerging Players: Lead with natural colorant offerings targeting organic-certified supply chains in France and Benelux where EFSA-pending approvals create temporary penetration windows. Pilot anthocyanin derivatives for temperate-zone seed storage applications where lightfastness gaps matter less. Pursue toll manufacturing partnerships with established dispersion houses to bypass capital-intensive milling infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European pigment dispersion specialists holding REACH-registered substance portfolios. Five-to-ten year viability hinges on successful bio-based transition execution rather than legacy petroleum-derived cash flow maintenance. Monitor EFSA positive list publication timelines for natural colorant categories as inflection indicators for organic certification penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Oxide Feedstock | BASF SE secures supply continuity for high-purity seed coating grades ahead of Brazilian demand surges. |
| Biodegradable Pigment Carrier Validation | LANXESS AG aligns azo pigment portfolios with EU Green Deal Farm to Fork substitution mandates. |
| Encapsulation Technology Licensing | Clariant AG extends colorfastness performance for Iowa seed cooperatives carrying multi-season inventory. |
| Regional Toll Processing Partnerships | Heubach GmbH expands aqueous dispersion capacity without stainless-steel milling capital expenditure. |
| Natural Colorant Regulatory Approval Pathway | Sudarshan Chemical Industries Limited positions for FSSAI positive list inclusion in Indian agricultural applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration databases, and SEC chemical sector filings. Plant managers at German and Dutch seed treatment facilities, procurement leads at Brazilian agri-input distributors, and technical R&D directors at pigment synthesis operations provided operational validation. Bottom-up volume estimates from application-specific consumption rates triangulate against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include pigment chemistry class, application format, certification tier, and regional regulatory cluster across the analysis window. CAGRs derive from regression analysis of historical consumption patterns projected through equipment installation rates and compliance deadline schedules. Industry-specific inputs incorporate REACH authorization sunset timelines and precision agriculture OEM specification embedding rates.
Forecasts assume regulatory continuity in EU REACH and EPA tolerance regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EFSA natural colorant approval timelines and ANVISA registration processing rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market