
 Plant Growth Promoters Market | 2026-2036
Plant Growth Promoters Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Growth Promoters Market Analytics
India is narrowing the gap between domestic biostimulant production capacity and import dependency through expanded microbial fermentation facilities in Gujarat and Maharashtra. BASF SE leverages its global R&D network to sustain technology leadership in synthetic auxin formulations. Syngenta AG anchors its position through integrated seed-treatment-to-foliar application portfolios. Bayer AG competes by controlling distribution channels across Latin American specialty crop zones.
Plant growth promoters comprise biologically active substances—auxins, gibberellins, cytokinins, and microbial metabolites—applied at concentrations between 10⁻⁶ and 10⁻³ molar to modulate cell division, elongation, and differentiation in vascular plants. These inputs serve commercial agriculture by reducing abiotic stress losses and accelerating harvest cycles in high-value fruit and vegetable systems. Biostimulants now occupy the fastest-expanding margin pool within the type dimension, driven by organic certification premiums and residue-sensitive export markets. Liquid formulations dominate the form category due to compatibility with precision fertigation infrastructure, while granular products retain cost advantages in broad-acre cereal applications. The greenhouse application segment leads value generation per hectare treated, though agricultural field crops account for the largest absolute volume throughput.
The EPA regulates plant growth promoter registrations under FIFRA, requiring ecotoxicology data that extends product development timelines by 24–36 months. REACH compliance in Europe mandates full substance characterization for microbial inoculants, creating a two-tier market split between established registrants and new entrants. India's CDSCO and FSSAI jointly oversee residue limits in food crops, influencing formulation choices for export-oriented growers. Stakeholders must monitor evolving biocontainment standards for genetically modified microbial strains, as these rules will determine which product platforms retain market access across major regulatory jurisdictions.
Market Dynamics
Specialty crop producers are consolidating purchasing power around biostimulant portfolios that reduce synthetic chemical residues for EU and North American export compliance, compressing formulation development cycles and rewiring distributor incentives toward technical advisory services.
Growth Catalysts
- EU Fertilising Products Regulation:Tightened purity standards for microbial inoculants are accelerating investment in domestic fermentation capacity across European formulators seeking to bypass import bottlenecks.
- Precision fertigation infrastructure:Liquid growth promoter compatibility with drip and hydroponic systems is expanding addressable acreage in controlled-environment agriculture clusters.
- India:State-level subsidy programs for hormonal growth regulators are pulling smallholder fruit and vegetable growers into formal input markets.
Market Restraints
- EPA FIFRA registration timelines:Ecotoxicology data requirements extend product development by 24–36 months, freezing capital in pre-revenue pipelines.
- Phosphate and nitrogen feedstock volatility:Synthetic auxin precursor costs fluctuate with energy and fertilizer commodity cycles, squeezing margin predictability for formulators.
- Microbial strain IP concentration:Patent thickets around engineered rhizobacteria limit independent R&D access for mid-tier biostimulant developers.
Strategic Opportunities
- Brazilian citrus and soybean belt:Underpenetrated biological growth promoter adoption in Latin America's largest specialty crop zone offers first-mover positioning for residue-free export certification.
- Seed-treatment-to-foliar integration:Converging application technologies enable bundled input pricing and locked-in grower relationships across full crop cycles.
- CDSCO-FSSAI harmonization:Streamlined residue limit protocols for Indian export crops reduce regulatory friction for dual-registered formulations.
Industry Challenges
- Microbial fermentation scale-up talent:Shortage of process engineers with GMP-compliant bioreactor experience constrains domestic biostimulant manufacturing expansion in Gujarat and Maharashtra.
- REACH full substance characterization:Analytical chemistry and toxicology documentation burdens create compliance backlogs for novel microbial inoculants entering European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Growth Promoters Market |
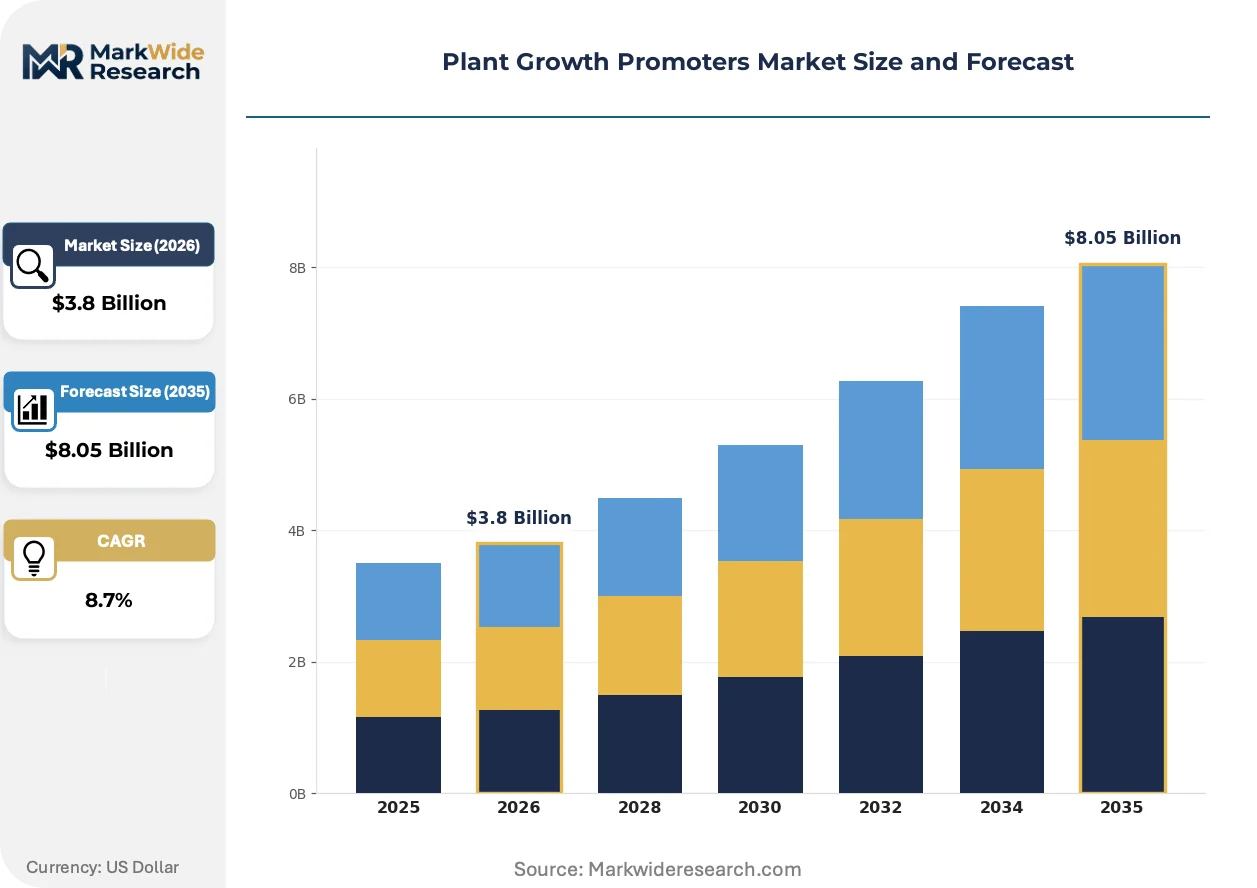
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hormonal, Biostimulants, Organic Fertilizers, Microbial Inoculants Application: Agricultural, Horticultural, Turf, Greenhouse Form: Liquid, Granular, Powder, Emulsion End User: Farmers, Gardeners, Commercial Growers, Researchers |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, Corteva, Nufarm Limited, FMC Corporation, UPL Limited, Tata Chemicals Ltd, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Growth Promoters Market Evolving Landscape
Biological and synthetic growth promoter categories are converging through formulation science advances that blend microbial metabolites with precision-dosed synthetic auxins, rewriting efficacy benchmarks and regulatory classification boundaries.
Microencapsulated gibberellin delivery systems is hybridizing controlled-release chemistry with foliar application equipment, enabling greenhouse operators in the Netherlands and Spain to reduce application frequency by half while maintaining yield targets. Equipment manufacturers are retrofitting precision sprayers for viscous biological suspensions. The technology is compressing labor cost structures in high-wage European growing regions.
REACH substance characterization mandates for microbial inoculants are forcing formulators to document full genomic and metabolic profiles before market entry, raising analytical chemistry spend as a share of product development budgets. Established registrants with existing dossiers are extending compliance cost advantages. Smaller biostimulant developers are retreating from European market ambitions toward Middle Eastern and Southeast Asian regulatory jurisdictions with lighter characterization requirements.
Export-oriented growers in India and Kenya are consolidating purchasing decisions around input suppliers with dual CDSCO-FSSAI or equivalent residue certification, displacing fragmented local distributor relationships. Certification bundling is becoming a primary vendor selection criterion. Procurement centralization is most visible in grape and pomegranate value chains supplying Middle Eastern retail chains.
Plant Growth Promoters Market Segmentation
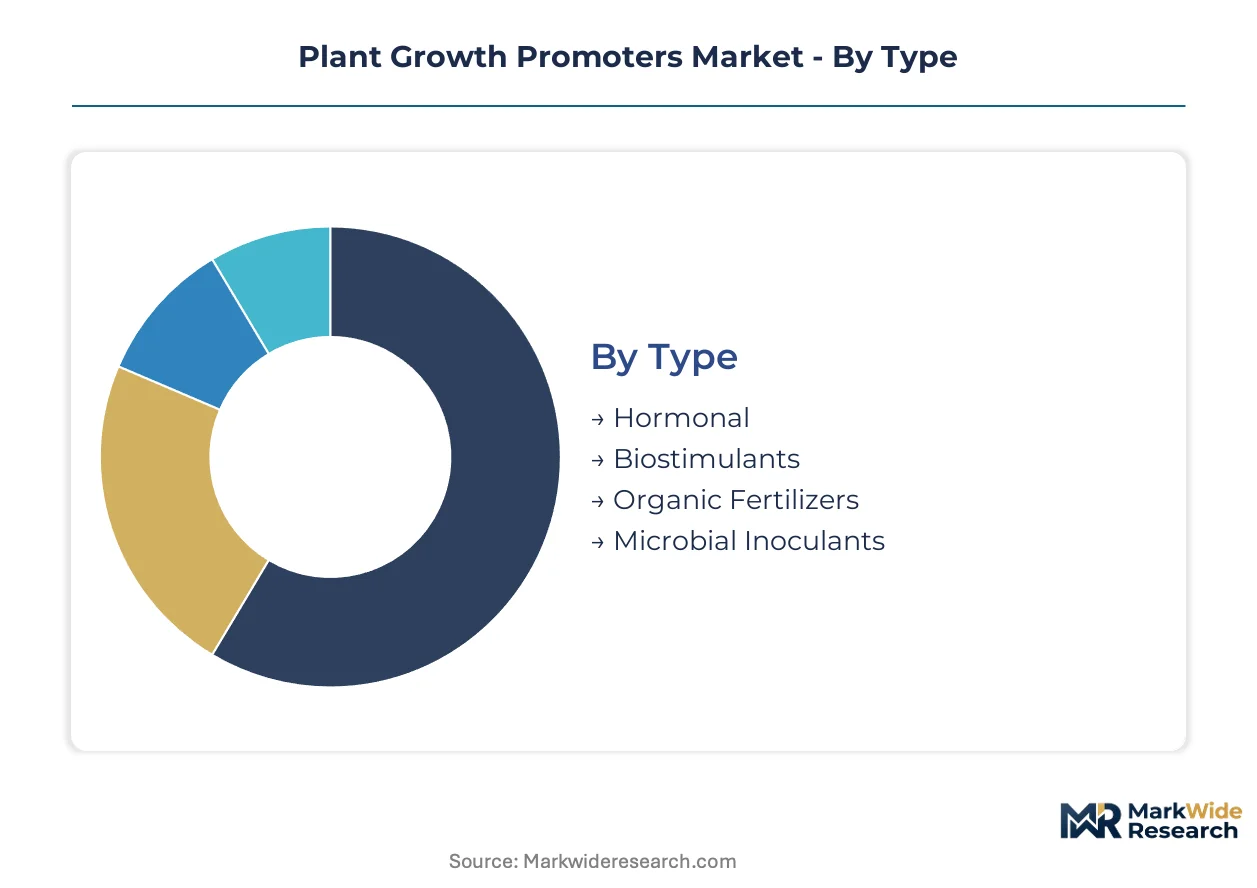
Segmentation in plant growth promoters reveals divergent service and technical support requirements across input categories. Biostimulant portfolios demand intensive agronomic advisory, while synthetic hormonal products rely on standardized application protocols. Understanding these service intensity gradients shapes distributor capability investments and margin structures.
Type:
After-sales service intensity varies sharply across type categories, with biostimulants requiring sustained technical consultation for efficacy optimization while hormonal products operate through established dosage tables.
- Biostimulants:Microbial metabolites and protein hydrolysates require customized application timing aligned with crop phenology. Dutch greenhouse operators and Indian pomegranate exporters now mandate supplier-provided agronomist support as a contract condition, pulling margin toward bundled service models.
- Hormonal:Synthetic auxins, gibberellins, and cytokinins follow concentration-calibrated protocols with minimal post-sale intervention. Brazilian citrus processors favor these inputs for predictable harvest synchronization, though residue certification requirements are tightening formulation specifications.
- Organic Fertilizers:Compost-derived and plant-based growth promoters serve certified organic operations in California and Italy with straightforward nutrient release profiles.
- Microbial Inoculants:Engineered rhizobacteria and mycorrhizal fungi face REACH characterization hurdles in Europe, concentrating demand in Middle Eastern jurisdictions with lighter dossier requirements.
By volume, Hormonal leads. By growth pace, Biostimulants is ahead.
Application:
Cost tier differentiation separates application segments, with greenhouse operations absorbing premium pricing for precision-formulated inputs while broad-acre agriculture prioritizes cost efficiency.
- Greenhouse:Controlled-environment agriculture in the Netherlands and Spain deploys growth promoters through fertigation systems at concentrations between 10⁻⁶ and 10⁻³ molar. Labor cost compression drives demand for extended-release formulations that halve application frequency.
- Agricultural:Field crop applications across India's wheat belt and Brazil's soybean zones emphasize volume throughput and distributor logistics efficiency over technical sophistication.
- Horticultural:Orchard and vineyard systems in Kenya and Chile integrate growth promoters with integrated pest management protocols for export certification compliance.
- Turf:Golf course and sports field maintenance in the US and UAE represents a specialized niche with distinct seasonal application windows and aesthetic performance metrics.
Greenhouse commands the highest value per hectare treated. Agricultural accounts for the largest absolute volume throughput.
Form:
Supply concentration in liquid formulation capacity is reshaping competitive positioning, with precision fertigation infrastructure expansion favoring fluid products over solid alternatives.
- Liquid:Aqueous solutions and suspensions integrate seamlessly with drip irrigation and hydroponic systems. Compatibility with automated dosing equipment is expanding addressable acreage in controlled-environment clusters across Spain, Mexico, and Saudi Arabia.
- Granular:Slow-release pellets retain cost advantages in Indian cereal production and Brazilian broad-acre soybeans where mechanized broadcasting dominates application methods.
- Powder:Dry concentrates serve smallholder cooperatives in Kenya and Ethiopia with extended shelf stability and reduced transport costs from port to farmgate.
- Emulsion:Oil-in-water formulations enhance foliar adhesion for high-value fruit crops in South Africa and Peru, commanding formulation premiums for rainfastness properties.
Liquid formulations lead in revenue growth trajectory. Granular products retain the widest geographic penetration.
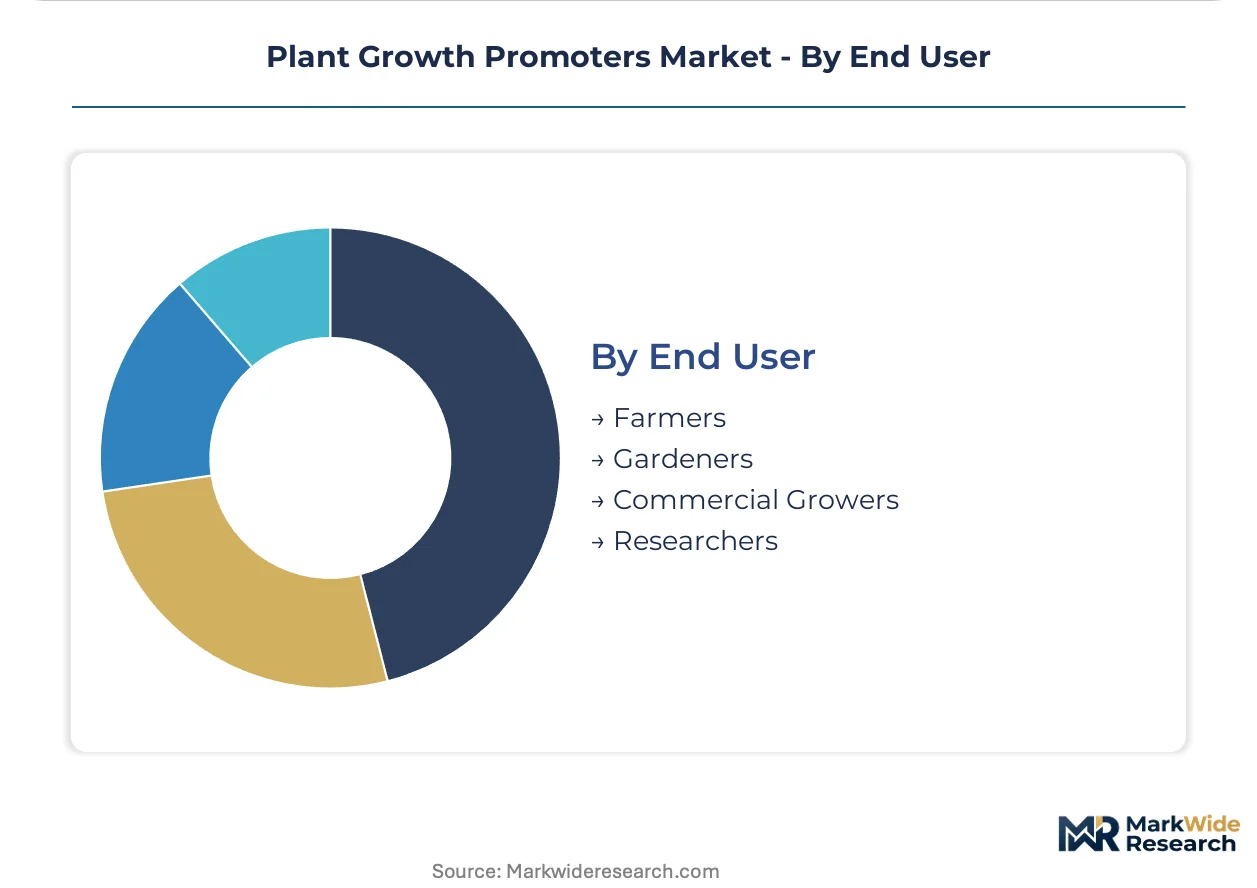
End User:
Customer type fragmentation across end user segments is forcing suppliers to maintain parallel sales channels with divergent technical support and credit term structures.
- Commercial Growers:Large-scale greenhouse operators and export-oriented specialty crop producers in India, Kenya, and Chile consolidate purchasing through procurement committees that bundle growth promoters with biological crop protection inputs.
- Farmers:Smallholder fruit and vegetable growers in Gujarat and Maharashtra respond to state subsidy programs for hormonal growth regulators, accelerating formal market participation.
- Gardeners:Amateur horticulturists in European and North American markets drive retail channel demand for ready-to-use liquid formulations with simplified dosing instructions.
- Researchers:Agricultural universities and seed company R&D stations in Brazil and China source reference-grade compounds for field trial protocols and new product development.
Commercial Growers generate the highest per-customer revenue. Farmers represent the deepest volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO and FSSAI jointly govern residue limits for food crops, pulling smallholder fruit and vegetable growers into formal input markets through state subsidy programs. The country's microbial fermentation expansion in Gujarat and Maharashtra is narrowing import dependency for biostimulant production.
India
State-level subsidy programs for hormonal growth regulators accelerate farmer adoption in Gujarat and Maharashtra. CDSCO-FSSAI harmonization on residue protocols reduces regulatory friction for export-oriented grape and pomegranate growers. Microbial fermentation facilities in Ahmedabad and Pune scale domestic biostimulant manufacturing capacity.
United States
EPA FIFRA registration timelines freeze capital in pre-revenue pipelines for 24–36 months. Commercial greenhouse operators in California and Florida consolidate purchasing through procurement committees bundling growth promoters with biological crop protection. Precision fertigation infrastructure expands addressable acreage in controlled-environment agriculture clusters.
Netherlands
REACH full substance characterization mandates concentrate demand among established registrants with existing dossiers. Greenhouse operators deploy microencapsulated gibberellin delivery systems through retrofit precision sprayers, halving application frequency. Wageningen-area research stations anchor formulation science advances blending microbial metabolites with synthetic auxins.
Brazil
Underpenetrated biological growth promoter adoption in the citrus and soybean belt offers first-mover positioning for residue-free export certification. ANVISA regulatory pathways for microbial inoculants remain lighter than European equivalents. São Paulo-state processors favor synthetic auxins for predictable harvest synchronization.
Spain
Almería and Murcia greenhouse clusters absorb premium pricing for precision-formulated liquid inputs compatible with drip irrigation systems. ECHA compliance costs displace smaller biostimulant developers toward Middle Eastern markets. Equipment manufacturers retrofit precision sprayers for viscous biological suspensions compressing labor cost structures.
Plant Growth Promoters Market Competitive Landscape
Integrated agrochemical conglomerates and specialized biostimulant developers split the market between scale-driven distribution control and technical advisory bundling. The vendor base concentrates around three strategic archetypes: global R&D networks sustaining synthetic auxin leadership, seed-treatment-to-foliar integrators locking in grower relationships, and fermentation-based biostimulant specialists. Dominant competitive moves include backward integration into microbial strain libraries and geographic expansion through dual-registration strategies for residue-sensitive export corridors.
Within the integrated agrochemical tier, BASF SE and Syngenta AG exemplify scale-driven positioning anchored by global formulation networks. Bayer AG occupies a position representing distribution channel control across Latin American specialty crop zones. Among Asia-Pacific players, UPL Limited and Tata Chemicals Ltd sit within the emerging domestic manufacturing archetype, reflecting India's state-subsidized expansion of microbial fermentation capacity.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| Corteva |
| Nufarm Limited |
| FMC Corporation |
| UPL Limited |
| Tata Chemicals Ltd |
| Sumitomo Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors carry microbial inoculant shipments from Gujarat fermentation facilities to European formulators, with container cost swings compressing margin pools for mid-tier biostimulant developers while amplifying price spreads between REACH-compliant premium tiers and economy-grade hormonal products.
Pricing Analysis
Price spreads between Indian-manufactured biostimulants and European-formulated alternatives span three certification tiers driven by REACH dossier completeness and CDSCO-FSSAI dual-registration status. Price differentiation separates residue-certified premium formulations for export grape growers from economy hormonal products serving domestic wheat belts. Pricing pressure stems from phosphate and nitrogen feedstock volatility squeezing synthetic auxin precursor costs. Smallholder cooperatives in Kenya and Ethiopia exhibit highest price sensitivity, while Dutch greenhouse operators absorb premium positioning for microencapsulated delivery systems.
Supply Chain Analysis
Supplier financing through extended 90-day payment terms anchors working capital structures for Indian microbial fermentation facilities serving domestic formulators. Supply concentrates in India, China, and the Netherlands for active ingredient production, with formulation finishing distributed across regional hubs. Raw material dependencies center on molasses feedstocks for fermentation, synthetic auxin precursors from petrochemical streams, and specialized microencapsulation polymers. Single-source vulnerability runs through engineered rhizobacteria strain libraries held by consolidated IP holders. Distribution runs through agricultural input distributors with embedded agronomist advisory capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capability gaps in GMP-compliant bioreactor process engineering constrain domestic manufacturing expansion, locking margin capture within a narrow tier of fermentation specialists with proven scale-up track records.
For Market Incumbents: Insulate formulation margins by deepening backward integration into captive microbial strain libraries and securing dual-registration dossiers for CDSCO-FSSAI harmonized residue protocols. Patent thickets around engineered rhizobacteria present existential threat from generic biostimulant developers; priority lever rests on exclusive licensing arrangements with Wageningen-area research stations. For New Entrants and Emerging Players: Build out technical advisory capabilities as bundled service differentiators targeting Brazilian citrus and soybean zones where biological growth promoter penetration remains underdeveloped. White-space opportunity concentrates in residue-free export certification for Latin American specialty crop processors. Go-to-market angle should anchor on ANVISA-registered microbial inoculants with lighter characterization burdens than European equivalents. For Investors and Strategic Acquirers: Fermentation-based biostimulant specialists with proven GMP scale-up talent represent the acquisition archetype of interest. Long-term viability hinges on regulatory arbitrage durability across REACH-heavy and lighter-jurisdiction markets. Signal to watch: CDSCO-FSSAI enforcement intensity on residue limits for grape and pomegranate export corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Strain Libraries | Captive IP control insulates against patent thicket congestion from engineered rhizobacteria holders. |
| Dual-Registration Dossier Investment | CDSCO-FSSAI harmonization reduces regulatory friction for Indian export-oriented grape growers. |
| GMP-Compliant Fermentation Scale-Up | Process engineering scarcity in Gujarat and Maharashtra limits domestic biostimulant manufacturing expansion. |
| Seed-Treatment-to-Foliar Integration | Bundled application technologies lock in grower relationships across full crop cycles in Brazilian citrus zones. |
| Residue-Free Export Certification | ANVISA pathways enable first-mover positioning in underpenetrated Latin American specialty crop markets. |
Research Methodology
A spread of perspectives from fermentation process engineers, agricultural input distributors, regulatory affairs specialists at CDSCO and EPA, and greenhouse operations managers converged on the working assumptions shaping this analysis. Primary interviews with biostimulant formulators in Gujarat and Maharashtra, synthetic auxin procurement leads at Indian agrochemical firms, and Dutch precision fertigation equipment manufacturers combined with secondary validation from EPA FIFRA registration databases, REACH substance characterization dossiers, CDSCO residue limit notifications, and ECHA compliance guidance documents. Bottom-up triangulation across production capacity estimates and top-down demand modeling from state subsidy program disbursements anchored volume and value outputs.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning biostimulant versus hormonal versus microbial inoculant type categories, greenhouse versus agricultural versus horticultural application contexts, and liquid versus granular versus powder form factors. CAGRs derived from fitted growth curves incorporating regulatory timeline delays, subsidy program ramp rates, and precision fertigation infrastructure deployment schedules. Industry-specific forecast inputs included REACH characterization backlog projections and CDSCO-FSSAI harmonization implementation pace.
Stress conditions across phosphate feedstock price volatility, EPA registration timeline extensions, and microbial fermentation scale-up talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy program continuity and regulatory enforcement intensity. Macroeconomic deviation, regulatory acceleration or delay, or breakthrough advances in synthetic biology strain engineering would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market